
 Europe Biofuel Market | 2026-2036
Europe Biofuel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biofuel Market Foresight
Multi-source feedstock procurement is repositioning how European refiners secure waste oils and agricultural residues. Neste leverages its Singapore-Rotterdam supply chain to dominate renewable diesel capacity. VERBIO AG anchors German biogas output through captive agricultural partnerships. TotalEnergies competes by extending its La Mède biorefinery into aviation fuel pathways.
Europe biofuel denotes liquid or gaseous fuels derived from biomass feedstocks through transesterification, fermentation, or thermochemical conversion, with energy densities ranging from 34 to 37 MJ per kilogram for fatty acid methyl esters. These fuels primarily displace fossil-derived gasoline, diesel, and marine fuel oil in combustion engines and industrial burners. Biodiesel retains the largest production base across EU member states, while green diesel is displacing conventional biodiesel in cold-climate performance applications. Transportation applications absorb the majority of blended volumes, though industrial process heating commands premium pricing for unblended biomethanol.
EMA, ECHA, and the EU Green Deal's Fit for 55 framework collectively mandate blending quotas, sustainability certification, and lifecycle emission thresholds that determine market access for imported feedstocks. ReFuelEU Aviation specifically obliges fuel suppliers to deliver escalating shares of sustainable aviation fuel at EU airports. Stakeholders must monitor how the CSRD's scope-three disclosure rules reshape procurement contracts between fuel producers and fleet operators.
Market Dynamics
The EU Green Deal's ReFuelEU Aviation mandate is compressing offtake timelines for sustainable aviation fuel, forcing refiners to reconfigure feedstock procurement before 2030 blending thresholds take effect.
Growth Catalysts
- ReFuelEU Aviation Mandate:The EU Green Deal framework obliges fuel suppliers to deliver escalating sustainable aviation fuel shares at EU airports, creating guaranteed demand pools for hydrotreated esters.
- Marine Fuel Switching:The International Maritime Organization's carbon intensity regulations are pulling ship operators toward fatty acid methyl esters in Rotterdam and Hamburg bunkering hubs.
- Biogas Grid Injection:Germany's industrial corridor is absorbing compressed biomethane for process heat, displacing natural gas in chemical and steel applications.
Market Restraints
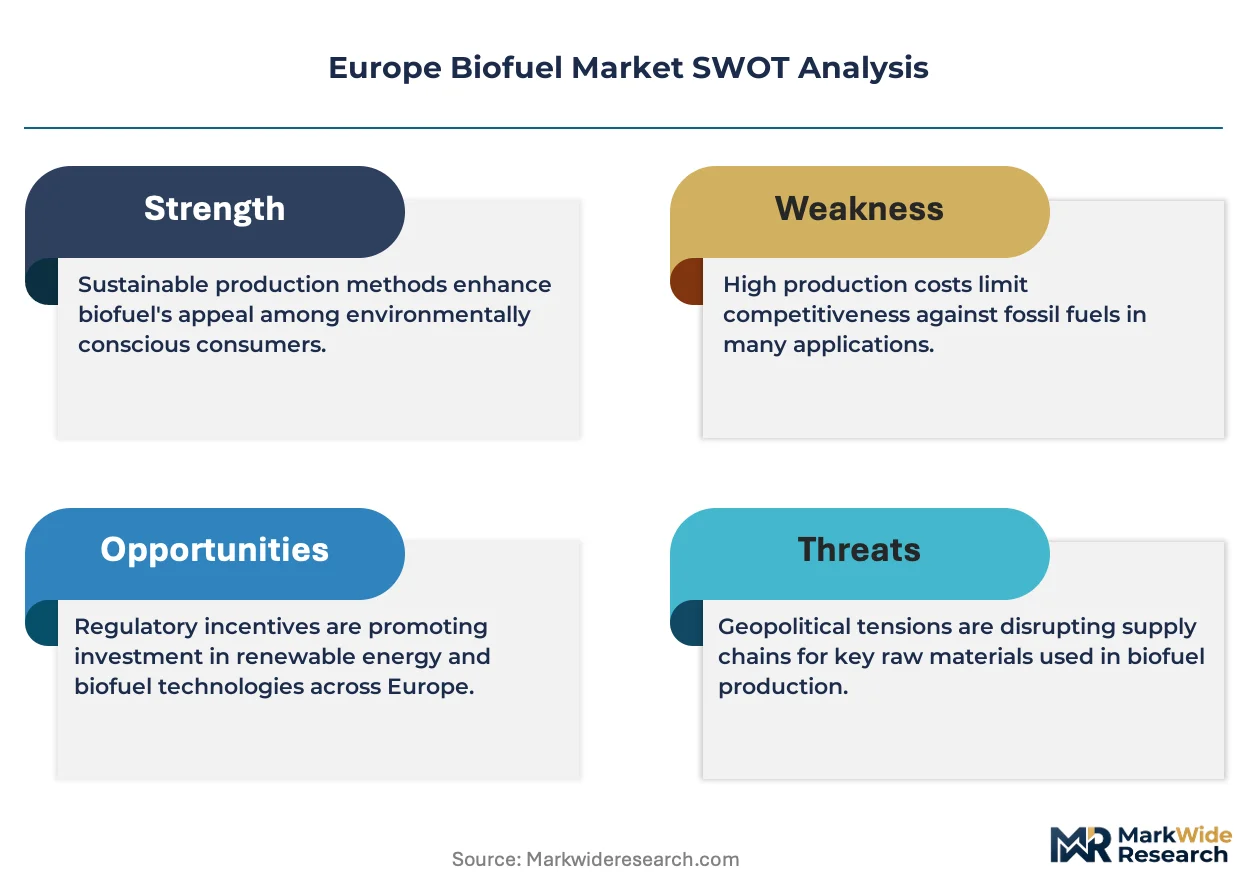
- Feedstock Concentration Risk:Waste oil collection networks cluster in Benelux and northern France, leaving Iberian and eastern European refiners exposed to supply shortfalls.
- Hydrogen Cost Structure:Green hydrogen for hydrotreatment commands premiums that compress margins on renewable diesel versus fossil parity pricing.
- Certification Bottlenecks:The EU's sustainability certification schemes create month-long validation queues for imported used cooking oils from non-EU origins.
Strategic Opportunities
- Poland's Agricultural Residue Base:Untapped straw and manure stocks in Greater Poland Voivodeship offer biogas developers captive feedstock for biomethane liquefaction.
- Power-to-X Convergence:Electrofuel synthesis combining captured CO2 with green hydrogen is opening aviation fuel pathways independent of biomass constraints.
- Industrial Cluster Offtake:The Port of Antwerp-Bruges is aggregating demand from chemical producers for unblended bio-methanol at process-heat specifications.
Industry Challenges
- Feedstock Chemist Scarcity:Refiners face acute shortages of specialists capable of characterizing multi-source waste oil acidity and contaminant profiles at scale.
- Capex Intensity for Hydroprocessing:Hydrotreater retrofits at legacy refineries demand capital allocations that strain mid-cap balance sheets before offtake contracts mature.
- ISCC Certification Timelines:Audit backlogs for International Sustainability and Carbon Certification are delaying market access for new market entrants by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biofuel Market |
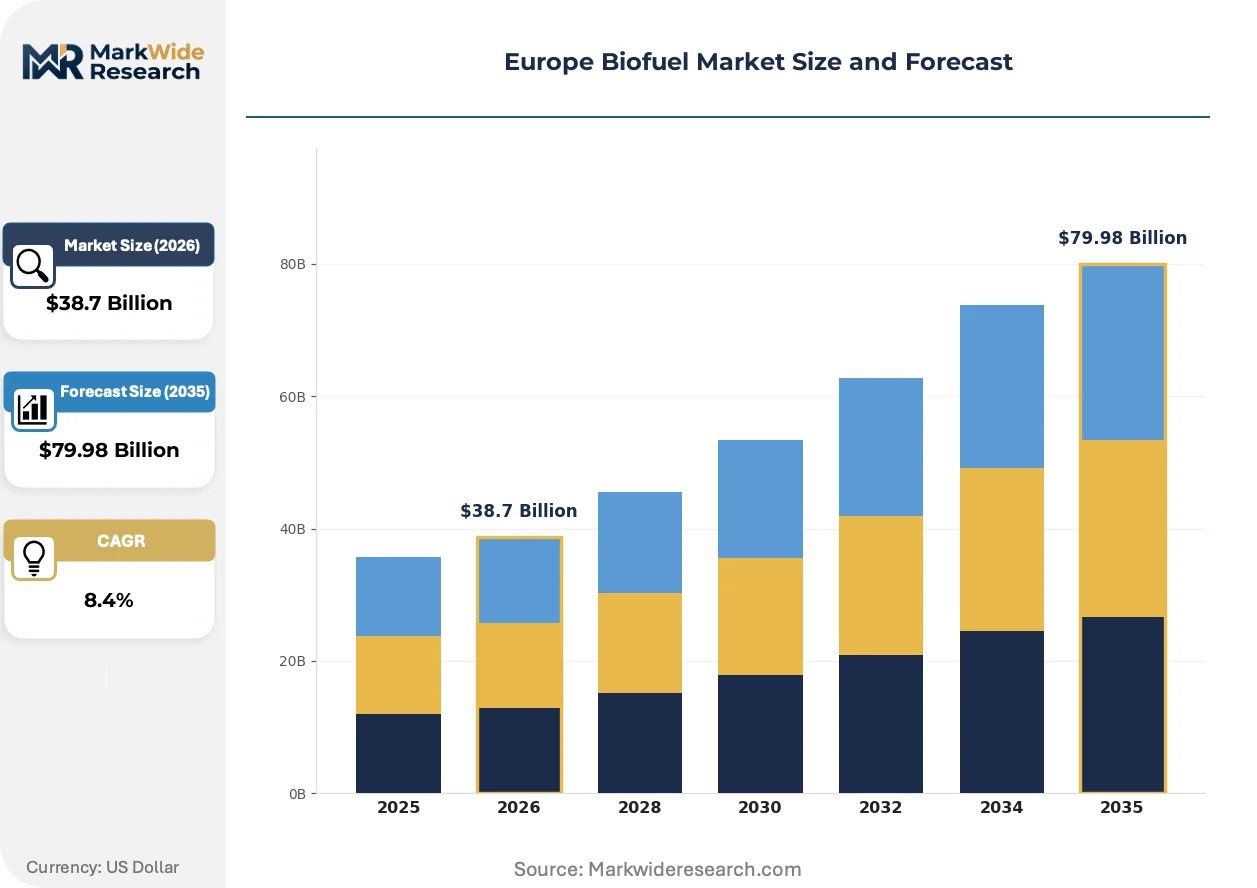
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biofuel Type: Biodiesel, Bioethanol, Biogas, Green Diesel, Biomethanol Application: Transportation, Power Generation, Heating, Industrial Processes, Agricultural Machinery End User: Vehicle Fleets, Utilities, Manufacturing Plants, Farm Operators, Marine Vessels Distribution Channel: Retail Fuel Stations, Direct Industrial Supply, Wholesale Distributors, Online Platforms |
| Companies Covered | Neste, TotalEnergies, CropEnergies AG, VERBIO AG, Archer Daniels Midland Company, Cargill, BP, Clariant, Borregaard AS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biofuel Market Shifts & Advancements
European biofuel production is pivoting from first-generation crop-based pathways toward waste-residue and power-to-X technologies that satisfy stricter lifecycle emission thresholds under Fit for 55.
Hydrotreated vegetable oil is expanding into cold-climate diesel applications across Scandinavia and the Baltic states. Fleet operators in Sweden and Finland are specifying HVO for Arctic-grade performance without cloud-point additives. This technology is expanding into maritime bunkering as shipowners seek drop-in compatibility with existing engine infrastructure.
The EU Green Deal's Fit for 55 framework is tightening lifecycle emission accounting for imported feedstocks. Fuel suppliers must now document full supply chain carbon intensity from cultivation or collection through combustion. Advanced biodiesel producers in the Netherlands and Germany are responding by backward integrating into waste oil collection networks rather than relying on merchant supply.
Long-term offtake contracting is displacing spot market purchases among aviation fuel buyers. Airlines at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle are locking ten-year supply agreements directly with biorefiners. This pattern concentrates procurement leverage with carriers holding balance sheet capacity, squeezing smaller regional airlines into secondary supply tiers.
Europe Biofuel Market Segmentation
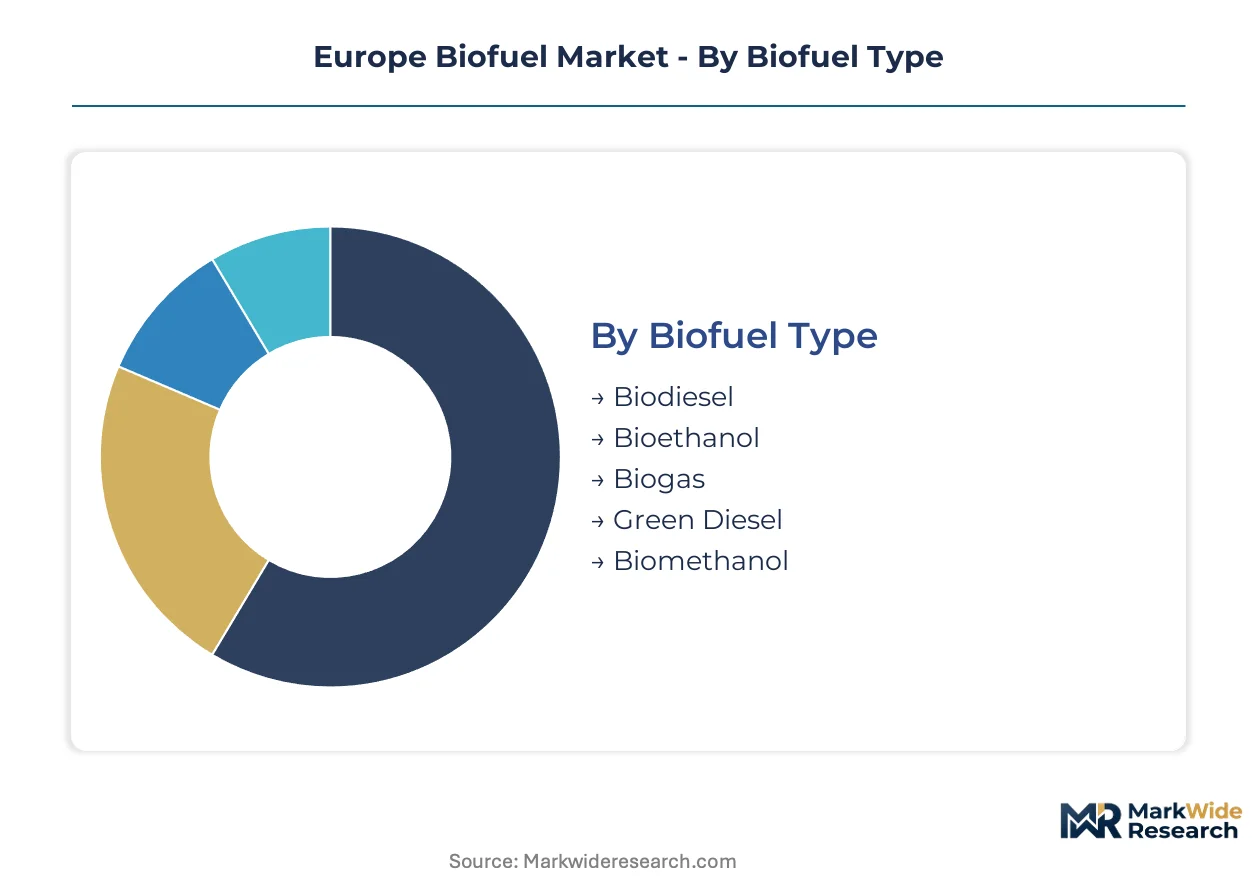
Segmentation in the Europe biofuel market reveals how supply chain configuration and regulatory thresholds fragment procurement patterns across fuel types, applications, and customer categories. Understanding these divisions exposes where feedstock access, certification requirements, and infrastructure investments concentrate competitive advantage.
Biofuel Type:
Production capacity clusters where hydrotreatment infrastructure and waste oil collection networks overlap, creating geographic moats for specific fuel categories.
- Biodiesel:Fatty acid methyl esters produced through transesterification of vegetable oils or animal fats. German and Dutch refiners dominate output, with demand concentrating in road transport fleets seeking compliance with EU renewable energy directive blending mandates.
- Green Diesel:Hydrotreated esters and fatty acids offering drop-in compatibility with fossil diesel infrastructure. Scandinavian cold-climate specifications pull supply toward Arctic-grade performance applications, displacing conventional biodiesel where cloud-point requirements are stringent.
- Bioethanol:Fermentation-derived alcohol blended with gasoline at ratios up to E85. French and Spanish producers leverage cereal and sugar beet feedstocks for road transport blending pools.
- Biogas:Methane-rich output from anaerobic digestion of agricultural residues and organic waste. German industrial corridors absorb volumes for process heat and grid injection, with chemical and steel producers displacing natural gas.
- Biomethanol:Synthesis gas conversion product used in chemical synthesis and marine fuel formulations. Rotterdam and Antwerp-Bruges chemical clusters command premium pricing for unblended specifications in process-heat applications.
Today's leader: Biodiesel. Tomorrow's challenger: Green Diesel.
Application:
End-use differentiation follows energy density requirements and emission accounting rules, with premium pricing attaching to applications where carbon intensity thresholds are binding.
- Transportation:Road, rail, aviation, and maritime mobility applications absorbing blended and drop-in fuels. ReFuelEU Aviation mandates at Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle are compressing offtake timelines for sustainable aviation fuel, forcing refiners to reconfigure procurement.
- Industrial Processes:High-temperature heat and chemical feedstock applications in cement, steel, and petrochemical sectors. The Port of Antwerp-Bruges aggregates demand from chemical producers for unblended bio-methanol at process-heat specifications.
- Power Generation:Combined heat and power plants and dedicated biomass facilities converting biogas or liquid biofuels to electricity. Italian and Polish utilities integrate biomethane into flexible generation portfolios.
- Heating:Residential and commercial building warmth through oil boiler retrofits and district heating networks. Nordic municipalities specify HVO-compatible systems for building stock decarbonization.
- Agricultural Machinery:Tractors, harvesters, and irrigation equipment operating on high-blend biodiesel or biomethane. German farm cooperatives anchor demand through captive biogas upgrading facilities.
Transportation commands volume leadership. Industrial Processes capture margin premiums.
End User:
Procurement scale and balance sheet capacity determine contract structures, with large fleet operators locking long-term supply agreements that squeeze smaller buyers into secondary tiers.
- Vehicle Fleets:Road transport operators with centralized fueling infrastructure and volume commitments. Long-haul trucking corridors through the Rhine-Alpine TEN-T network anchor diesel substitution demand.
- Marine Vessels:Ship operators subject to International Maritime Organization carbon intensity regulations. Rotterdam and Hamburg bunkering hubs are pulling demand toward fatty acid methyl esters for deep-sea and short-sea routes.
- Utilities:Power and gas grid operators procuring biomethane for injection or electricity generation. German network operators prioritize grid-connected biogas with ISCC certification for renewable gas guarantees.
- Manufacturing Plants:Industrial facilities seeking process heat and captive power from liquid or gaseous biofuels. Chemical producers in the Benelux cluster specify unblended bio-methanol for steam boiler applications.
- Farm Operators:Agricultural producers with on-farm digestion capacity and machinery fuel requirements. Polish and Romanian cooperatives are expanding straw-to-biogas installations for self-supply.
Vehicle Fleets dominate contract volume. Marine Vessels represent the steepest expansion trajectory.
Distribution Channel:
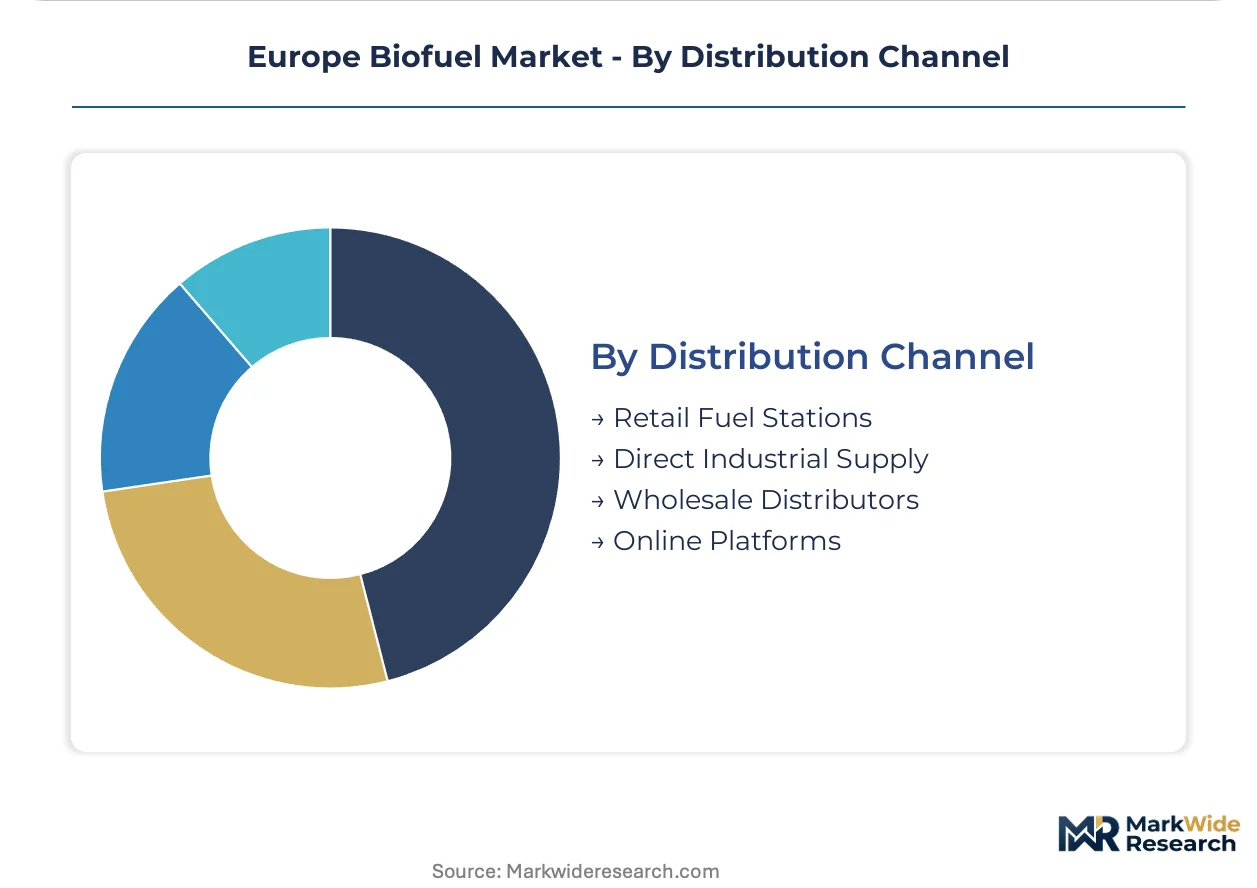
Channel selection reflects volume scale, certification requirements, and the physical infrastructure for blending or direct use.
- Direct Industrial Supply:Refiner-to-consumer contracts for unblended fuels meeting process specifications. Large chemical and steel producers in Germany and the Netherlands negotiate bilateral offtake agreements bypassing intermediaries.
- Wholesale Distributors:Intermediate aggregators supplying smaller fleets and regional industrial users. Benelux-based traders concentrate waste oil procurement for redistribution to Iberian and eastern European refiners.
- Retail Fuel Stations:Public refueling infrastructure offering B7-B100 diesel blends and E5-E85 gasoline formulations. Swedish and Finnish networks lead HVO availability for cold-climate performance.
- Online Platforms:Digital procurement interfaces for spot market purchases and certification documentation. Emerging channels serve regional airlines and mid-cap industrial buyers seeking supply diversification.
Direct Industrial Supply captures value. Wholesale Distributors bridge geographic gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redrawing production maps as refiners relocate hydrotreatment capacity toward jurisdictions with streamlined EU Green Deal compliance pathways and clustered waste oil collection infrastructure.
Germany
Industrial biogas demand from chemical and steel producers in the Rhine-Ruhr corridor anchors near-term volume concentration. The national renewable energy directive implements stricter sustainability certification timelines than EU baselines. VERBIO AG operates captive agricultural partnerships across Saxony-Anhalt and Brandenburg, securing straw and manure feedstocks for biomethane liquefaction.
Netherlands
Rotterdam's bunkering hub pulls fatty acid methyl esters toward maritime fuel switching under International Maritime Organization carbon intensity rules. REACH enforcement through ECHA mandates comprehensive lifecycle emission documentation for imported used cooking oils. The Port of Rotterdam Authority aggregates biorefiner investments alongside waste oil preprocessing terminals.
France
Cereal and sugar beet ethanol producers in Picardy and Champagne-Ardenne supply road transport blending pools. The national energy regulator enforces ReFuelEU Aviation mandates at Paris Charles de Gaulle with accelerated timelines. TotalEnergies extends La Mède biorefinery operations in Provence-Alpes-Côte d'Azur toward sustainable aviation fuel pathways.
Sweden
Arctic-grade HVO specifications from fleet operators in Norrland displace conventional biodiesel where cloud-point requirements are stringent. The Swedish Energy Agency administers premium certificate trading for cold-climate performance fuels. Preem operates hydrotreatment capacity at Lysekil and Gothenburg refineries targeting Scandinavian diesel substitution.
Poland
Untapped straw and manure stocks in Greater Poland Voivodeship attract biogas developers seeking captive feedstock for grid injection. The national agricultural ministry coordinates with EU Green Deal rural development funds for anaerobic digestion subsidies. Farm cooperatives in Lower Silesia expand biogas upgrading facilities for self-supply and industrial offtake.
Europe Biofuel Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue power-to-X and electrofuel synthesis adjacent to conventional biomass pathways. Market structure consolidates around integrated refiners with backward control over waste oil collection networks and merchant biogas operators dependent on agricultural partnerships. Three archetypes dominate: hydrotreatment specialists with Singapore-Rotterdam supply chains, farm-integrated biogas producers with captive feedstock, and diversified energy majors retrofitting legacy refineries. Competitive moves concentrate on hydrotreater capacity expansion and ISCC certification pre-positioning ahead of 2030 aviation mandates.
Among Nordic-European integrated refiners, Neste anchors renewable diesel capacity through its Rotterdam terminal network. VERBIO AG exemplifies the farm-integrated biogas archetype with German agricultural partnerships. TotalEnergies occupies the diversified energy major position with Mediterranean biorefinery assets.
| Leading Market Players |
|---|
| Neste |
| TotalEnergies |
| CropEnergies AG |
| VERBIO AG |
| Archer Daniels Midland Company |
| Cargill |
| BP |
| Clariant |
| Borregaard AS |
| Others |
Supply & Pricing Matrix
Green hydrogen feedstock costs cascade through hydrotreatment economics, compressing renewable diesel margins as German and Dutch refiners absorb premium inputs before passing differential pricing to aviation fuel buyers under ReFuelEU mandates.
Pricing Analysis
Input-cost pass-through from waste oil collection networks shapes contract structures across the value chain. Long-term offtake agreements dominate sustainable aviation fuel procurement, with ISCC-certified volumes commanding premium positioning over uncertified alternatives. Pricing pressure intensifies in conventional biodiesel tiers as hydrotreated vegetable oil displaces fatty acid methyl esters in cold-climate specifications. Fleet operators with centralized Rhine-Alpine corridor infrastructure exhibit lowest price sensitivity; regional airlines locked out of ten-year supply agreements face acute cost exposure.
Supply Chain Analysis
Direct-to-industrial channels handle hyperscale chemical and steel producer demand for unblended biomethanol at Antwerp-Bruges process specifications. Feedstock procurement concentrates in Germany, the Netherlands, and Belgium where waste oil collection infrastructure clusters, leaving Iberian and eastern European refiners exposed to supply shortfalls. Hydrotreater retrofits, green hydrogen procurement, and ISCC audit backlogs constitute critical path dependencies. Distribution runs through bilateral refiner-to-consumer contracts for premium specifications, with wholesale distributors bridging geographic gaps for smaller fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe biofuel market represents a late-cycle quality story as aviation fuel buyers pivot procurement toward certified sustainable aviation fuel specifications with binding lifecycle emission thresholds under Fit for 55.
For Market Incumbents: Hedge feedstock concentration risk by backward integrating into Polish and Romanian agricultural residue networks before 2030 aviation mandates compress procurement timelines. Prioritize hydrotreater capacity expansion at Rotterdam and Hamburg corridor locations to capture maritime fuel switching demand under International Maritime Organization carbon intensity regulations.
For New Entrants and Emerging Players: Capture white-space in Greater Poland Voivodeship biogas liquefaction by securing captive straw and manure partnerships with farm cooperatives. Target industrial process heat applications in the Benelux chemical cluster where unblended bio-methanol specifications command premium positioning unavailable to blended transportation fuel suppliers.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap refiners lack balance sheet capacity for hydrotreater retrofits before offtake contracts mature. Frame five-to-ten year viability around integrated producers with Singapore-Rotterdam supply chain control and ISCC certification pre-positioning. Monitor audit backlog resolution timelines at ECHA as inflection indicator for new entrant market access velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreater Capacity Expansion | Rotterdam and Hamburg retrofits capture maritime fuel switching demand under International Maritime Organization rules. |
| Backward Integration into Waste Oil Collection | Benelux and northern French network control secures feedstock against Iberian and eastern European supply shortfalls. |
| ISCC Certification Pre-Positioning | Early audit completion accelerates market access before ReFuelEU Aviation mandates compress procurement timelines. |
| Long-Term Aviation Fuel Offtake Agreements | Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle carriers lock procurement leverage through bilateral refiner contracts. |
| Power-to-X Electrofuel Synthesis | Captured CO2 and green hydrogen pathways open aviation fuel production independent of biomass feedstock constraints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged biorefinery operations directors, aviation fuel procurement managers at Frankfurt and Amsterdam Schiphol, chemical plant energy officers at Antwerp-Bruges, waste oil collection network coordinators, and ECHA regulatory affairs specialists. Secondary validation drew from EU Green Deal implementation reports, ISCC certification registry data, International Maritime Organization carbon intensity filings, and customs trade flows for used cooking oil imports. Bottom-up capacity modeling and top-down demand aggregation triangulated market sizing across fuel type, application, and end-user segments.
Comparable-period anchoring linked forward projections to historical production capacity, feedstock price series, and regulatory implementation trajectories. The analytical framework segmented by biofuel type, application, end-user scale, and distribution channel, with additional dimensioning for certification tier and geographic production cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity buildout schedules. Key inputs included hydrotreater retrofit investment pipelines, aviation mandate compliance trajectories, and green hydrogen cost evolution assumptions.
Underlying measurement precision varies by segment; certified sustainable aviation fuel and hydrotreated vegetable oil carry tighter precision than conventional biodiesel given concentrated producer disclosure. Forecasts embed assumptions around ReFuelEU Aviation implementation pace, International Maritime Organization carbon intensity enforcement stringency, and green hydrogen cost reduction trajectories. Feedstock supply disruptions, certification audit backlogs, or hydrogen subsidy scheme modifications could materially revise outlooks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Biofuel Ethanol Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Biodiesel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Second Generation Biofuels Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Latin America Biodiesel Market
Biofuels
Brazil Biofuel Market
Biofuels
United States Biodiesel Market
Biofuels
Europe Biodiesel Market
Biofuels
Biofuels Market
Biofuels
Bioethanol Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Rotating Machines for Biofuels Market