
 Heat Sensitive Cups Market | 2026-2036
Heat Sensitive Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Sensitive Cups Market Foresight
Market Context
Capital-intensity divergence between thermochromic coating specialists and commodity cup manufacturers is reorganizing competitive tiers in the heat sensitive cups sector. Ember Technologies, Inc. leverages proprietary phase-change materials to sustain premium positioning in temperature-controlled drinkware. Huhtamaki Group anchors large-format foodservice contracts through integrated paperboard and printing capabilities. Shenzhen Yong Rui Bianse Arts & Crafts specializes in small-batch color-changing ceramics for promotional markets, competing on design velocity rather than scale.
Technical and Segment Structure
Heat sensitive cups incorporate thermochromic pigments, leuco dye microencapsulation systems, or bimetallic temperature sensors that trigger reversible visual state changes between 15°C and 65°C, serving food safety communication and brand engagement functions. Ceramic and glass segments command premium pricing due to firing-process compatibility with organic pigment systems, while plastic variants dominate volume through injection-molded leuco dye integration. The color changing feature category captures the majority of promotional and hospitality demand, whereas temperature indication applications are penetrating healthcare and institutional catering procurement specifications.
Regulatory Environment
FDA food-contact substance notifications and EU REACH Annex XVII restrictions on heavy metals in thermochromic formulations are elevating compliance costs for pigment suppliers and cup finishers. China's GB standards for food-contact materials and the EU F-Gas Regulation indirectly shape insulation-type product development through refrigerant-linked cold-chain specifications. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these jurisdictions are drafting drinkware-specific recycling and chemical disclosure requirements that could fragment national product lines.
Market Dynamics
REACH Annex XVII restrictions on heavy metals and evolving FDA food-contact material rules are compressing formulation options for thermochromic pigment suppliers, forcing cup finishers to requalify entire coating portfolios.
Growth Catalysts
- EU REACH compliance mandates:Tighter pigment specifications are accelerating supplier consolidation toward certified coating houses with in-house toxicology testing. Specialty coffee chains in France and Germany now require REACH-compliant documentation for all branded drinkware.
- Leuco dye microencapsulation:Advances in shell-wall durability are expanding color-changing applications to dishwasher-safe ceramics. Jingdezhen kilns have adopted these systems for export-grade production.
- Healthcare procurement specifications:Temperature indication functionality is penetrating institutional catering contracts in Japan and South Korea, where bimetallic sensor integration meets food safety audit requirements.
Market Restraints
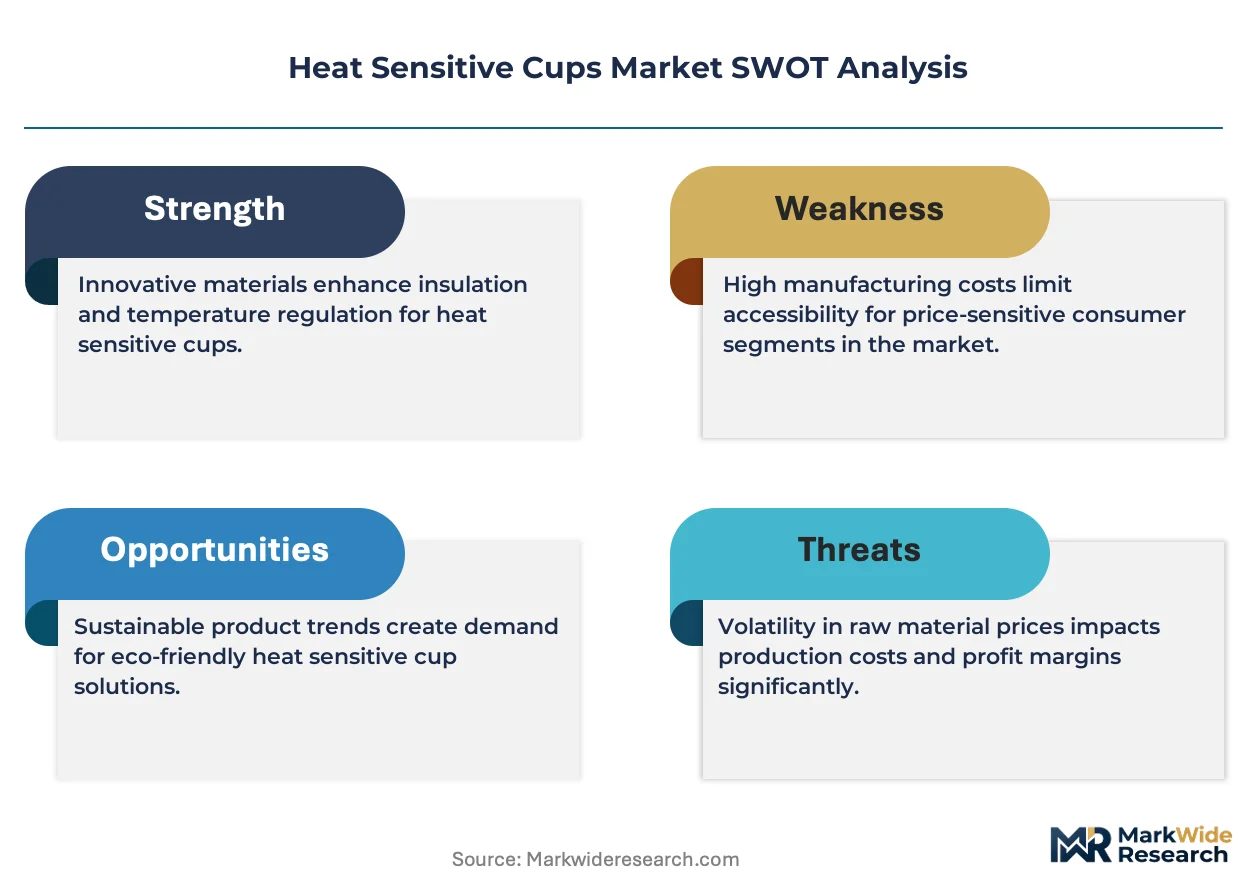
- Organic pigment input volatility:Phthalocyanine blue and leuco dye precursor costs fluctuate with petrochemical feedstock markets, squeezing margin at mid-tier cup finishers.
- Shenzhen manufacturing cluster concentration:Over 60% of global thermochromic plastic cup production sits within a 50-kilometer radius, creating single-point vulnerability to regional power rationing or logistics disruption.
- Thermochromic reversibility limits:Current organic formulations degrade after 1,000-3,000 thermal cycles, restricting use in high-frequency commercial dishwashing environments.
Strategic Opportunities
- India foodservice expansion:Quick-service restaurant chains in Mumbai and Bangalore are piloting color-changing cups for beverage temperature communication, with FSSAI food-contact approvals still nascent in this category.
- EU F-Gas Regulation tailwind:Cold-chain refrigerant phase-downs are indirectly boosting demand for insulated temperature-indicating drinkware in pharmaceutical logistics.
- Digital printing convergence:Integration of inkjet-deposited thermochromic layers with variable data printing enables batch-level customization for promotional markets.
Industry Challenges
- Formulation chemist scarcity:Expertise in leuco dye encapsulation and ceramic firing compatibility concentrates among aging specialists in Germany and Japan.
- Dual certification timelines:Simultaneous FDA notification and REACH registration for new pigment systems extends commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Sensitive Cups Market |
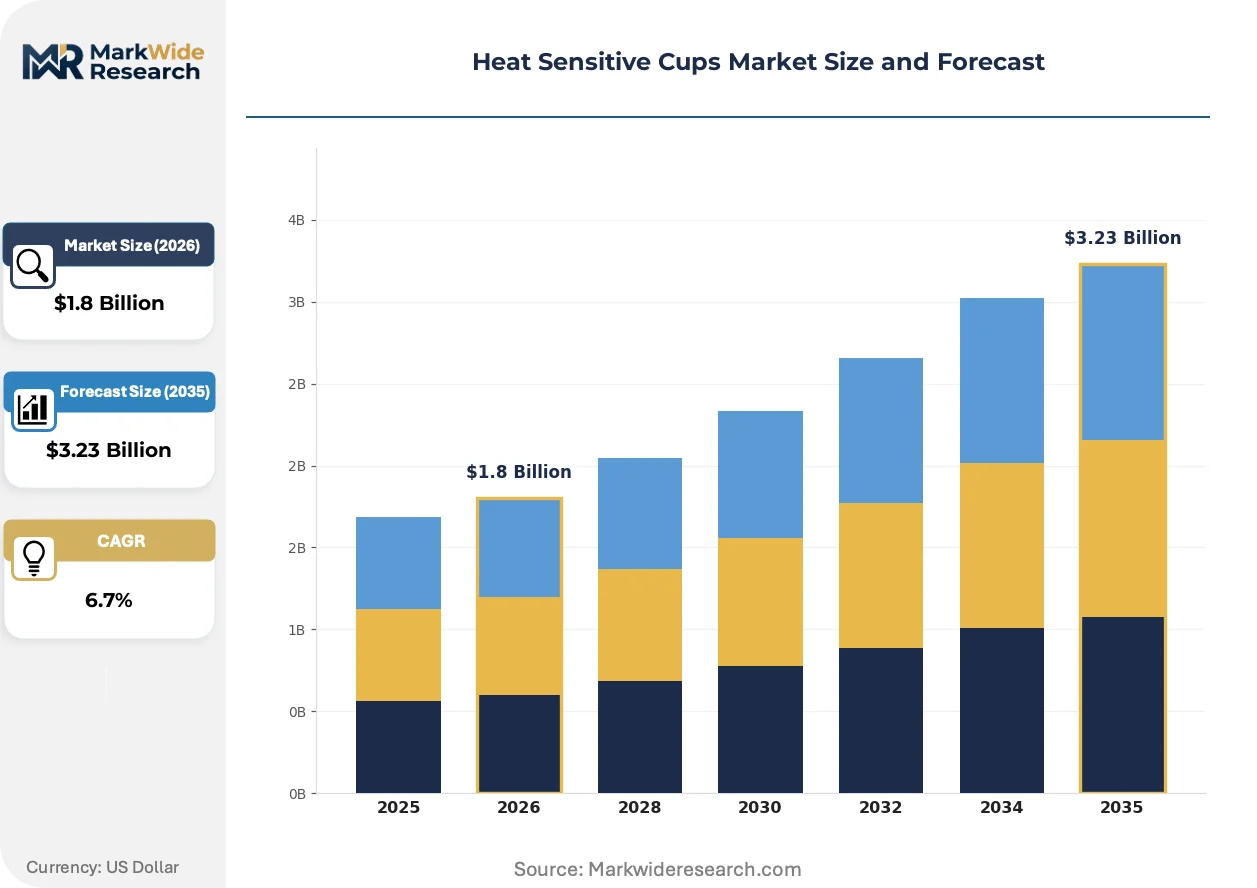
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Ceramic, Glass Feature: Color Changing, Temperature Indication, Pattern Display, Insulation Type End User: Retailers, Restaurants, Events, Households Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Dexsim (M) Sdn Bhd, Shenzhen Yong Rui Bianse Arts & Crafts, Huhtamaki Group, Shenzhen Yongfeng Ceramics, Ember Technologies, Inc., Thermos LLC, Zojirushi Corporation, Yeti Holdings, Inc., Cauldryn LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Sensitive Cups Market Shifts & Advancements
Thermochromic coating chemistry and regulatory compliance frameworks are the twin forces compressing supplier margins while opening premium positioning for certified finishers.
Reversible thermochromic pigments with enhanced thermal stability are displacing conventional leuco dye systems in high-cycle commercial applications. Hospital cafeterias and institutional caterers in Germany and Switzerland are specifying these advanced formulations for temperature safety compliance. The displacement is compressing demand for standard-grade color-changing coatings into purely promotional and gift-market channels.
EU REACH Annex XVII additions targeting nickel and cobalt compounds in consumer goods are forcing reformulation of metallic-based thermochromic systems. Pigment houses in the Netherlands and Belgium are accelerating organic alternative development to maintain EU market access. Ceramic cup exporters from Jingdezhen face extended requalification timelines as they adapt to heavy-metal-free firing protocols.
Direct procurement relationships between specialty coffee chains and certified coating specialists are disintermediating traditional promotional product distributors. Starbucks Reserve and independent roasters in Portland and Copenhagen are sourcing temperature-responsive drinkware through audited supplier programs rather than catalog intermediaries. This channel compression is most visible in North American and Nordic markets where sustainability disclosure requirements favor supply chain transparency.
Heat Sensitive Cups Market Segmentation
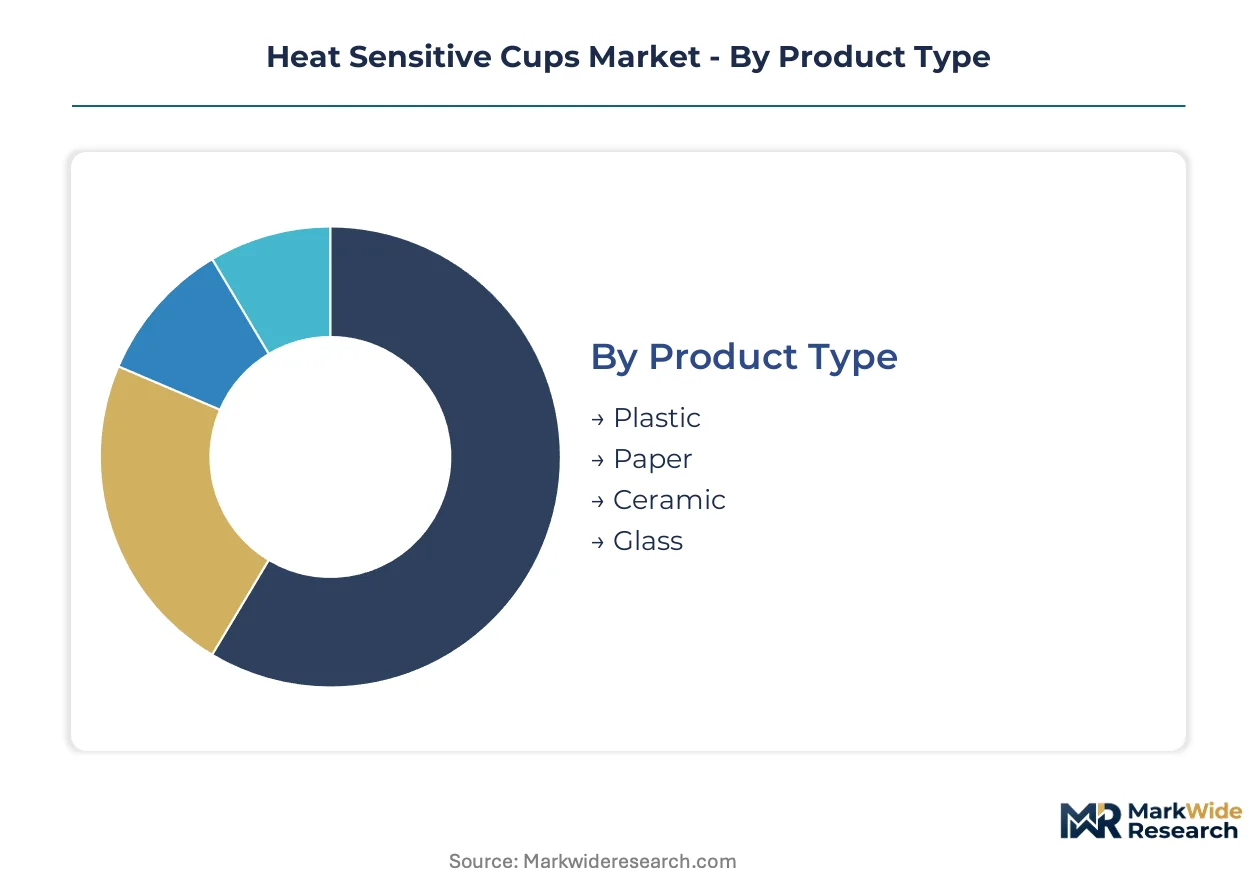
Segmentation in heat sensitive cups reveals divergent supply chain configurations and regulatory exposure profiles across material substrates and functional categories. Each dimension carries distinct margin structures, certification requirements, and geographic demand concentrations that reshape competitive positioning.
Product Type:
Plastic variants dominate export volume from Shenzhen manufacturing clusters, while ceramic and glass segments serve premium domestic markets in Europe and Japan with localized firing protocols.
- Plastic:Injection-molded leuco dye integration enables mass production at Shenzhen and Dongguan facilities. Quick-service restaurant chains in the United States and quick-commerce platforms in India drive procurement scale, though FDA and FSSAI food-contact approvals create regional formulation divergence.
- Ceramic:Jingdezhen kilns fire thermochromic glazes compatible with organic pigment systems, commanding premium pricing through specialty coffee chains in France and Germany. REACH-compliant heavy-metal-free protocols now extend requalification timelines by 12-18 months for export-grade production.
- Paper:Huhtamaki Group and similar integrated converters dominate large-format foodservice contracts, with thermochromic printing limited to cold-beverage applications due to heat sensitivity of paper substrates.
- Glass:Borosilicate compatibility with thermochromic coatings remains technically constrained; production concentrates in Czech and Italian specialty glasshouses serving pharmaceutical logistics and premium hospitality.
Plastic holds the largest share; momentum sits with ceramic as REACH compliance disfavors metallic pigment alternatives.
Feature:
Cost tier separation is pronounced: color-changing applications serve promotional price points while temperature indication commands specification-grade premiums in healthcare and institutional procurement.
- Color Changing:Reversible leuco dye microencapsulation triggers visual shifts between 15°C and 65°C, dominating gift-market and brand-activation channels. Advances in shell-wall durability from Japanese encapsulation specialists now extend dishwasher-cycle tolerance to 3,000+ exposures.
- Temperature Indication:Bimetallic sensor integration and calibrated thermochromic bands serve food safety audit requirements in German hospital cafeterias and South Korean institutional catering. Regulatory specification in Japan's METI guidelines accelerates adoption.
- Pattern Display:Heat-reveal hidden graphics serve limited promotional niches; technical constraints on resolution and color fidelity restrict commercial scale.
- Insulation Type:Double-wall vacuum construction with temperature-indicating outer layers addresses EU F-Gas Regulation tailwinds in pharmaceutical cold-chain logistics.
Color Changing generates highest volume; Temperature Indication climbs the fastest as healthcare procurement specifications harden.
End User:
Customer type determines order cadence and customization depth, with household segments favoring e-commerce immediacy while events demand batch-level design velocity.
- Retailers:Private-label programs at Carrefour and Auchan in France require REACH-compliant documentation and 90-day design-to-shelf cycles, favoring Shenzhen suppliers with in-house toxicology testing.
- Restaurants:Temperature-responsive branded drinkware at Starbucks Reserve and independent Nordic roasters bypasses traditional promotional distributors through direct audited supplier relationships.
- Events:Marathon and festival organizers in Mumbai and Bangalore pilot color-changing cups for beverage temperature communication, with FSSAI approvals still nascent in this category.
- Households:Amazon and Flipkart channels in India concentrate demand for novelty-grade color-changing plastics, with price sensitivity limiting coating durability specifications.
Restaurants command highest per-unit pricing; Events represent the steepest expansion trajectory as experiential marketing budgets recover.
Distribution Channel:
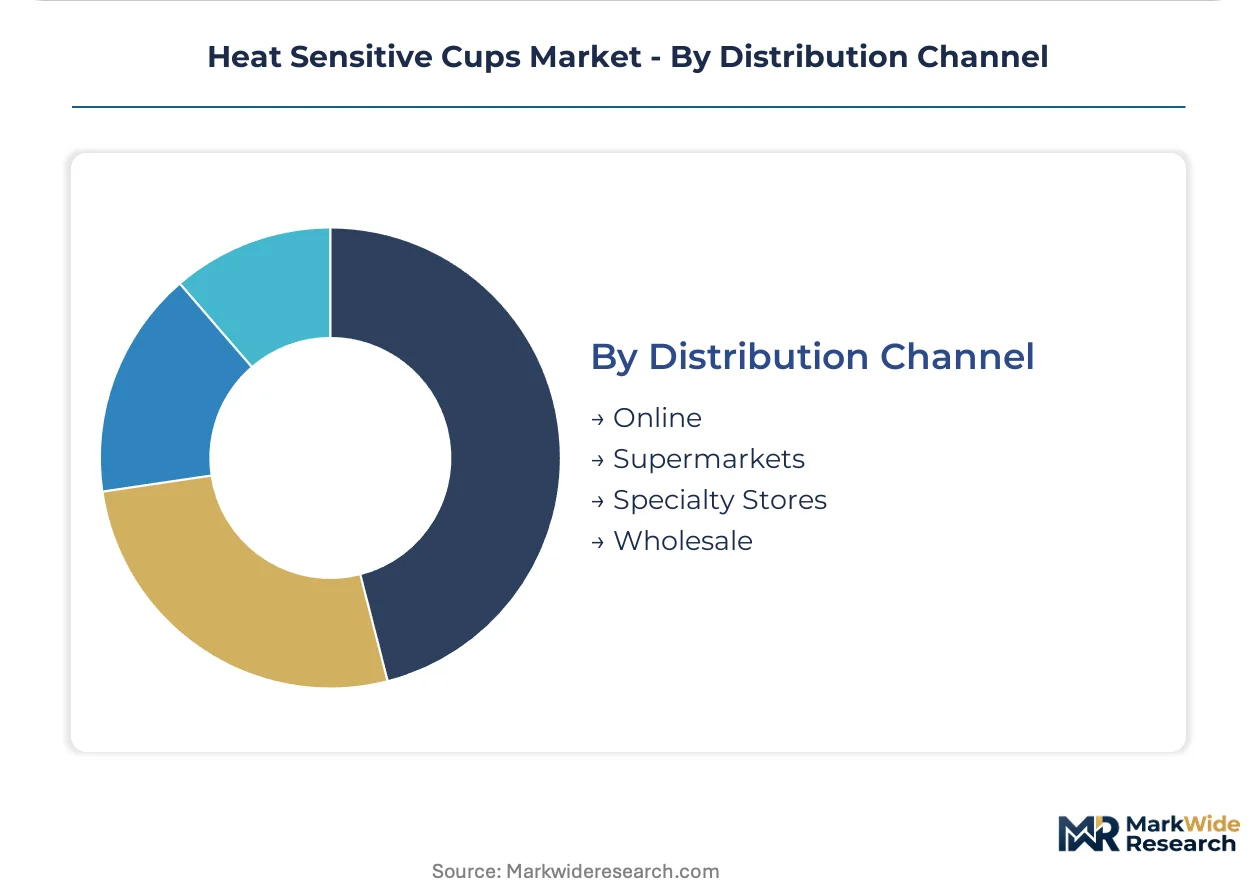
Supply concentration varies sharply: online and wholesale channels aggregate fragmented demand, while specialty stores and supermarkets require compliant documentation and extended payment terms.
- Online:Direct-to-consumer platforms aggregate long-tail demand for novelty thermochromic products, with return rates elevated due to color-reversibility degradation exceeding customer expectations.
- Supermarkets:Aldi and Lidl in Germany stock seasonal color-changing cup programs with 12-week shelf windows, requiring suppliers to absorb markdown risk on unsold inventory.
- Specialty Stores:Williams Sonoma and Crate & Barrel in the United States curate premium ceramic and glass temperature-responsive drinkware with sustainability disclosure requirements favoring supply chain transparency.
- Wholesale:Promotional product distributors in the United States and Europe face disintermediation pressure as end-users source directly from certified coating specialists.
Online captures highest transaction volume; Specialty Stores deliver strongest margin contribution through premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium ceramic pricing in Germany sits 40-60% above Shenzhen-sourced plastic equivalents, creating a transatlantic value chain split between specification-grade and commodity supply tiers.
United States
Starbucks Reserve and independent roasters in Portland drive direct procurement of REACH-compliant temperature-responsive drinkware through audited supplier programs. FDA food-contact substance notifications govern thermochromic pigment approvals for domestic production. California's emerging extended producer responsibility legislation is drafting drinkware-specific chemical disclosure requirements that could fragment national product lines.
Germany
Specialty coffee chains in Berlin and Hamburg require ECHA REACH Annex XVII documentation for all branded temperature-indicating ceramics. Hospital cafeterias in Bavaria specify bimetallic sensor integration for food safety audit compliance. Pigment houses in the Netherlands and Belgium supply organic alternatives to maintain EU market access amid heavy-metal restrictions.
China
Shenzhen and Jingdezhen manufacturing clusters supply over 60% of global thermochromic ceramic and plastic cup production. GB standards for food-contact materials shape domestic formulation protocols. Dongguan facilities face power rationing vulnerability that concentrates single-point supply risk within a 50-kilometer radius.
Japan
METI guidelines accelerate temperature indication adoption in institutional catering procurement across Tokyo and Osaka. Healthcare foodservice contracts specify calibrated thermochromic bands for patient safety protocols. Japanese encapsulation specialists advance shell-wall durability extending dishwasher-cycle tolerance beyond 3,000 exposures.
India
Quick-service restaurant chains in Mumbai and Bangalore pilot color-changing cups for beverage temperature communication. FSSAI food-contact approvals remain nascent in this category, creating regulatory uncertainty for import qualification. Amazon and Flipkart channels concentrate household demand for novelty-grade thermochromic plastics with elevated return rates from color-reversibility degradation.
Heat Sensitive Cups Market Competitive Landscape
Concentration sits with thermochromic coating specialists and integrated paperboard converters, while commodity cup fabricators face margin compression from regulatory requalification costs. The vendor base organizes into three strategic archetypes: proprietary phase-change material developers, certified REACH-compliant finishers with in-house toxicology testing, and high-velocity promotional design houses competing on batch customization rather than scale. Dominant competitive moves include backward integration into pigment encapsulation capacity and direct sourcing relationships that disintermediate traditional promotional distributors.
Among Asia-Pacific-based specialists, Shenzhen Yong Rui Bianse Arts & Crafts and Shenzhen Yongfeng Ceramics exemplify the design-velocity archetype serving small-batch promotional markets. Ember Technologies, Inc. occupies a position within the proprietary technology tier, while Huhtamaki Group anchors the integrated converter segment through large-format foodservice contract execution. These three entities collectively represent the geographic and capability span of competitive positioning in temperature-responsive drinkware supply.
| Leading Market Players |
|---|
| Dexsim (M) Sdn Bhd |
| Shenzhen Yong Rui Bianse Arts & Crafts |
| Huhtamaki Group |
| Shenzhen Yongfeng Ceramics |
| Ember Technologies, Inc. |
| Thermos LLC |
| Zojirushi Corporation |
| Yeti Holdings, Inc. |
| Cauldryn LLC |
| Others |
Supply & Pricing Matrix
EU REACH Annex XVII compliance gates both supply qualification and price differentiation simultaneously, forcing cup finishers to absorb toxicology testing costs that separate certified coating houses from commodity manufacturers unable to cross the regulatory threshold. This certification divide creates pricing power concentration among REACH-documented suppliers serving European specialty coffee chains, while uncertified competitors retreat to promotional price points.
Pricing Analysis
The customization-premium spread separates configured-to-order ceramic programs for Berlin roasters from standard injection-molded plastics stocked by Aldi and Lidl. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and dishwasher-cycle durability specifications. Cost compression in the standard tier intensifies because phthalocyanine blue input volatility squeezes mid-tier finishers without encapsulation capabilities. Amazon and Flipkart household segments exhibit highest price sensitivity, whereas hospital cafeterias in Germany and Switzerland accept specification-grade premiums for bimetallic sensor integration.
Supply Chain Analysis
Inventory lead times stretch 12-18 months for Jingdezhen kilns adapting to heavy-metal-free firing protocols under REACH pressure. Production gravity centers on China, with Shenzhen plastic injection facilities and Jingdezhen ceramic kilns feeding global demand. Raw material dependencies rest on Japanese leuco dye encapsulation systems, German organic pigment precursors, and Belgian coating formulation expertise. Single-source vulnerability concentrates within the 50-kilometer Shenzhen-Dongguan radius where power rationing threatens 60% of global thermochromic cup output. Distribution runs through direct audited supplier relationships that disintermediate traditional promotional distributors for premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct procurement platforms between specialty coffee chains and certified finishers signal a platform-economics inflection, with interoperability demands for REACH documentation APIs reshaping supplier relationship management.
For Market Incumbents: Shield margin position by deepening backward integration into pigment encapsulation capacity and securing captive supply of shell-wall durability technology from Japanese specialists. Regulatory requalification timelines extend commercialization cycles, favoring incumbents with existing FDA notification and REACH registration portfolios against new entrants facing 18-24 month certification barriers. For New Entrants and Emerging Players: Lead with digital printing convergence capabilities that enable batch-level customization for Mumbai and Bangalore event organizers piloting color-changing cup programs. The most penetrable white space sits in FSSAI-compliant temperature indication for Indian quick-service restaurants, where food-contact approvals remain nascent and first-mover documentation advantages compound. For Investors and Strategic Acquirers: EU REACH Annex XVII additions targeting nickel and cobalt compounds reshape the acquisition landscape toward organic pigment alternative developers in the Netherlands and Belgium. Long-term viability over a multi-year horizon hinges on coating houses with in-house toxicology testing infrastructure rather than outsourced certification dependencies. The signal to watch is California extended producer responsibility legislation drafting drinkware-specific chemical disclosure requirements that could fragment national product lines and elevate compliant asset values.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Encapsulation Capacity | Captive leuco dye microencapsulation secures shell-wall durability specifications against Japanese supplier concentration. |
| REACH-Compliant Documentation API Development | Direct procurement platforms for Starbucks Reserve and Nordic roasters require automated compliance verification. |
| FSSAI Food-Contact Approval Investment | First-mover qualification in India quick-service restaurant pilots locks in temperature indication specification advantages. |
| Digital Printing Convergence Capability | Inkjet-deposited thermochromic layers with variable data printing unlock batch-level promotional customization velocity. |
| Heavy-Metal-Free Firing Protocol Adaptation | Jingdezhen kiln requalification extends export-grade ceramic production timelines, favoring capitalized finishers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food-contact substance notifications, ECHA REACH registration databases, and GB standards documentation for food-contact materials. Interviews with thermochromic coating specialists, ceramic kiln operators in Jingdezhen, quick-service restaurant procurement managers, and promotional product distributors combined with customs trade data and specialty coffee chain sustainability disclosure reports. Bottom-up demand modeling across material substrates and functional categories triangulates against top-down value chain analysis.
Segmentation dimensions modeled include material substrate, functional feature category, end-user type, and distribution channel across the analysis window. CAGRs derive from growth driver elasticity estimates calibrated to regulatory compliance cost trajectories and procurement specification adoption curves. Forecast inputs incorporate REACH Annex XVII expansion timelines, FSSAI approval progression in India, and Japanese encapsulation specialist capacity announcements.
Underlying assumptions cover sustained REACH enforcement stringency and F-Gas Regulation cold-chain tailwinds, with deviation risk concentrated in Shenzhen power rationing recurrence and California EPR legislation fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Active & Intelligent Packaging
Gel Packs Market
Active & Intelligent Packaging
Reflective Air Packaging Market
Active & Intelligent Packaging
Global Controlled Intelligent Packaging Market
Active & Intelligent Packaging
Highly Visible Packaging Market
Active & Intelligent Packaging
Multi-Sensory Packaging Market
Active & Intelligent Packaging
Global Internet of Packaging Market
Active & Intelligent Packaging
Interactive Packaging Market
Active & Intelligent Packaging
Easy Open Packaging Market
Active & Intelligent Packaging
Global Advanced Packaging Technologies Market
Active & Intelligent Packaging
Active and Modified Atmosphere Packaging Market
Active & Intelligent Packaging
Isothermal Packaging Market
Active & Intelligent Packaging
Global Augmented Reality Packaging Market
Active & Intelligent Packaging
North America Active and Intelligent Packaging Market
Active & Intelligent Packaging
Track and Trace Packaging Market
Active & Intelligent Packaging
Next Generation Packaging Market
Active & Intelligent Packaging
Active Smart and Intelligent Packaging Market