
 MENA Thermoform Plastic Packaging Market | 2026-2036
MENA Thermoform Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Thermoform Plastic Packaging Market Foresight
Polymer processing technician availability is reorganizing output schedules across Egyptian and Saudi converter facilities. Hotpack Packaging Industries LLC leverages its Jebel Ali manufacturing base to sustain Gulf-wide distribution networks. Takween Advanced Industries anchors Saudi domestic supply through its Yanbu petrochemical integration. Napco National differentiates via medical-grade cleanroom thermoforming for Saudi hospital networks.
Thermoform plastic packaging denotes rigid or semi-rigid containers produced by heating thermoplastic sheets until pliable, then vacuum-forming or pressure-forming them over molds with typical gauge ranges of 0.005 to 0.060 inches, serving primarily to protect perishables and sterile goods during distribution. Trays dominate food service and retail meat applications where barrier properties and stackability command premium positioning. Clamshells capture expanding electronics and healthcare demand due to theft-deterrent visibility and contamination control. Polypropylene leads material selection for microwaveable and retort-ready formats, while polyethylene sustains cost-sensitive bulk produce segments.
Saudi SFDA food-contact notifications, UAE MOHAP medical device packaging standards, and Egypt's EOS polymer import specifications collectively determine which resin grades and additive packages gain market access across the MENA corridor. Compliance documentation burdens favor converters with in-house regulatory affairs capabilities over import-reliant traders. Stakeholders must weigh Gulf localization incentives against Nile Delta labor cost advantages when siting new thermoforming capacity.
Market Dynamics
Cold-chain infrastructure buildout across the Gulf Cooperation Council is compressing lead times for perishable-ready thermoform trays, forcing converters to co-locate forming capacity with logistics hubs.
Growth Catalysts
- SFDA food-contact compliance mandates:Saudi Arabia's tightened material notification requirements are filtering out informal importers and consolidating volume with certified domestic converters.
- Healthcare procurement centralization:Saudi hospital network purchasing reforms are standardizing on medical-grade clamshell specifications, creating pull-through for ISO 15378-certified suppliers.
- Polypropylene barrier coextrusion:Advances in oxygen-scavenging layer integration are extending shelf life for retort-ready meat trays, unlocking premium positioning in UAE retail channels.
Market Restraints
- Ethylene feedstock volatility:Gulf petrochemical pricing swings transmit directly to polyethylene sheet costs, squeezing margin predictability for Egyptian converters dependent on imported resin.
- SFDA notification backlog:Extended approval timelines for new additive packages are freezing product development pipelines for regional compounders.
- Fiber-based substitution pressure:Molded pulp advances in European export markets are threatening thermoform share in premium fresh produce segments.
Strategic Opportunities
- Egyptian Nile Delta expansion:Underdeveloped cold-chain penetration in Upper Egypt provinces offers first-mover positioning for tray suppliers partnering with supermarket format rollout.
- MOHAP medical device packaging harmonization:UAE regulatory alignment with EU MDR technical documentation standards is creating streamlined market access for dual-certified converters.
- Digital print integration:Direct-to-sheet UV decoration convergence with thermoforming lines is enabling short-run customization for seasonal promotional packaging.
Industry Challenges
- Vacuum-forming technician scarcity:Specialized mold setup and gauge control expertise shortages across Egyptian facilities are forcing extended commissioning periods for new production lines.
- Cleanroom certification timelines:ISO 14644 Class 8 validation for medical thermoforming is requiring 12-18 month facility qualification cycles in Saudi Arabia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Thermoform Plastic Packaging Market |
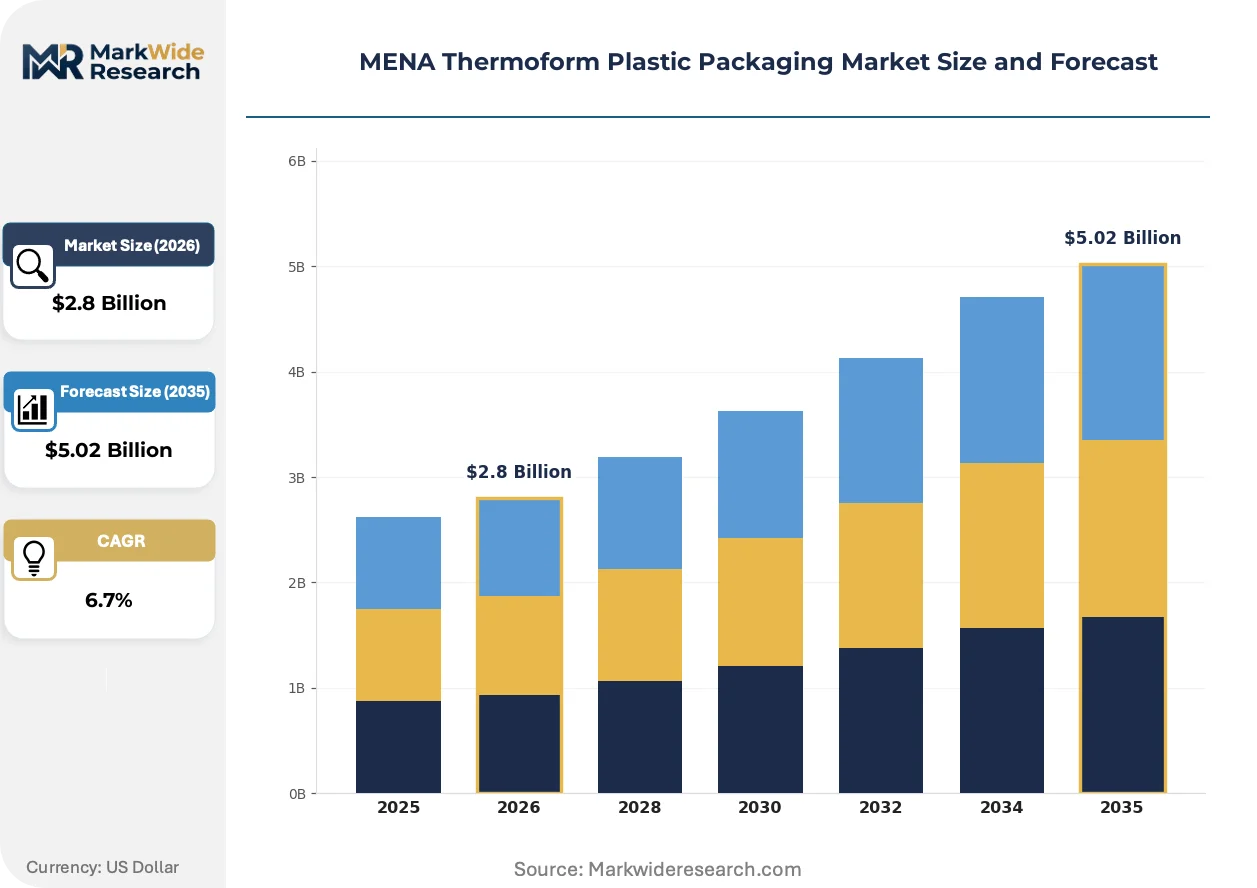
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Container, Tray, Clamshell, Blister End User: Food & Beverage, Healthcare, Consumer Goods, Electronics Material: Polypropylene, Polyethylene, PVC, PS Application: Retail Packaging, Medical Packaging, Automotive Parts, Industrial Products |
| Companies Covered | Takween Advanced Industries, Hotpack Packaging Industries LLC, Cristal Plastic Industrial LLC, Nascho General Trading LLC, Nuplas Industries, Interplast (Harwal Group of Companies), Napco National, Ghanplast, Arabian Plastics Industrial Company Limited, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Thermoform Plastic Packaging Market Shifts & Advancements
Active and intelligent packaging integration is redefining value capture in Gulf food logistics, shifting converter revenue models from unit volume to performance guarantees.
Barrier-coated polyethylene terephthalate (PET) sheet is fragmenting traditional polypropylene dominance in modified-atmosphere meat applications. Saudi retail chains are adopting the material for its clarity and seal integrity. The technology is fragmenting incumbent supply relationships as converters retool extrusion lines for crystallizable PET grades.
UAE MOHAP's 2024 technical guidance on sterile barrier systems is mandating accelerated aging protocols for medical device trays. The regulation is disqualifying legacy polystyrene formulations lacking validated seal strength data. Cardiac device manufacturers in Dubai Healthcare City are now specifying Tyvek-lidded PETG clamshells with documented peel characteristics.
Consolidated procurement by Saudi supermarket operators is compressing supplier panels and demanding vendor-managed inventory for promotional tray programs. Regional buying cooperatives are replacing fragmented independent retailer orders. The shift is most visible in Riyadh's central fresh distribution hub, where three retail groups now control sixty percent of tray volume.
MENA Thermoform Plastic Packaging Market Segmentation
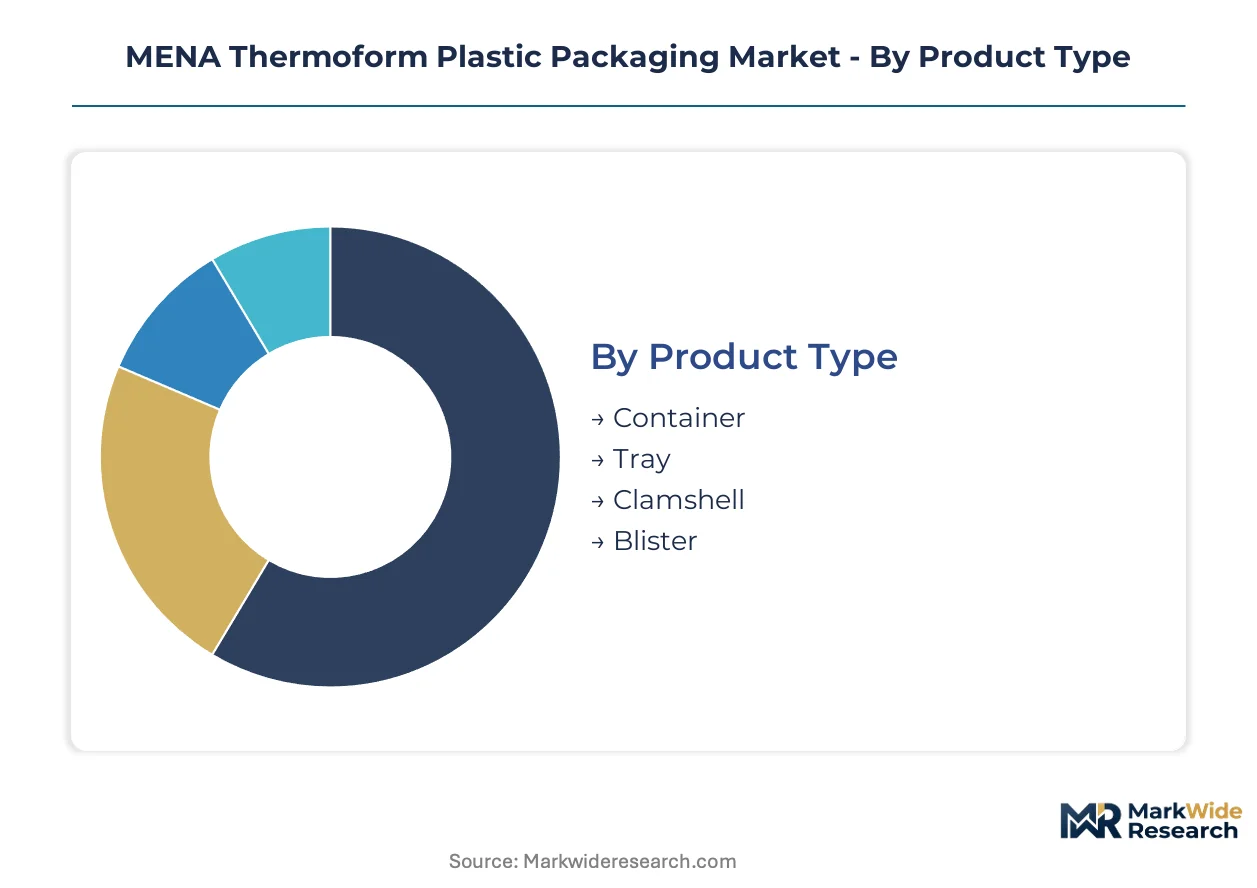
Thermoform packaging demand fragments sharply across container geometries, resin chemistries, and sterilization requirements. Each segment carries distinct tooling investments and regulatory compliance burdens that reshape converter specialization patterns across the MENA corridor.
Product Type:
Clamshell and blister formats face acute substitution pressure from fiber-based molded pulp in European export channels, while tray and container segments defend share through barrier coextrusion advances.
- Tray:Vacuum-formed or pressure-formed platforms with raised edges and stacking lugs, typically 0.010–0.040 inch gauge, serve modified-atmosphere meat and produce applications. Riyadh's central fresh distribution hub concentrates procurement for Saudi supermarket cooperatives, with oxygen-scavenging polypropylene layers extending chilled shelf life.
- Clamshell:Hinged two-piece containers with integral locking tabs provide tamper-evident protection for electronics and sterile medical devices. Dubai Healthcare City cardiac device manufacturers specify Tyvek-lidded PETG formats with validated peel characteristics under MOHAP sterile barrier guidance.
- Container:Lidded or open-top vessels with deeper draw ratios accommodate ready-meal and dairy applications. Egyptian converters supply cost-sensitive bulk formats for Nile Delta food processors.
- Blister:Clear cavity-plus-lidding combinations protect unit-dose pharmaceuticals and small consumer goods. SFDA food-contact notification requirements filter informal imports toward certified domestic suppliers.
Tray retains volume leadership; clamshell holds the steepest expansion curve.
End User:
Customer procurement scale varies dramatically—hospital network centralization contrasts with fragmented independent retail—reshaping converter salesforce deployment and inventory commitment terms.
- Food & Beverage:Cold-chain meat, dairy, and ready-meal applications dominate sheet consumption. GCC logistics hub co-location requirements compress lead times for perishable-ready formats.
- Healthcare:ISO 15378-certified medical device packaging and pharmaceutical blisters command premium positioning. Saudi hospital purchasing reforms standardize on specified clamshell geometries.
- Consumer Goods:Cosmetics and personal care applications favor high-clarity PETG and PVC formats. UAE retail chains drive clarity and seal integrity specifications.
- Electronics:Anti-static and theft-deterrent clamshells protect mobile devices and accessories during Gulf distribution. Jebel Ali manufacturing bases sustain regional supply networks.
Food and beverage commands absolute tonnage; healthcare generates the highest margin per unit.
Material:
Resin selection trade-offs center on microwave compatibility, barrier performance, and SFDA notification pathway complexity.
- Polypropylene:Semi-crystalline thermoplastic with retort stability and broad food-contact approvals anchors microwaveable and hot-fill applications. Barrier coextrusion with oxygen-scavenging layers unlocks premium meat tray positioning in UAE retail.
- Polyethylene:Cost-advantaged amorphous resin sustains bulk produce and industrial formats. Egyptian converters face margin squeeze from ethylene feedstock volatility transmitted through imported resin pricing.
- PVC:Rigid formulations deliver clarity and forming ease for blister packs and consumer displays. Regulatory scrutiny on plasticizer migration limits food-contact applications.
- PS:Crystal and high-impact grades serve low-cost trays and industrial dunnage. MOHAP sterile barrier protocols disqualify legacy polystyrene lacking validated seal strength data.
Polypropylene leads value generation; polyethylene maintains absolute volume dominance.
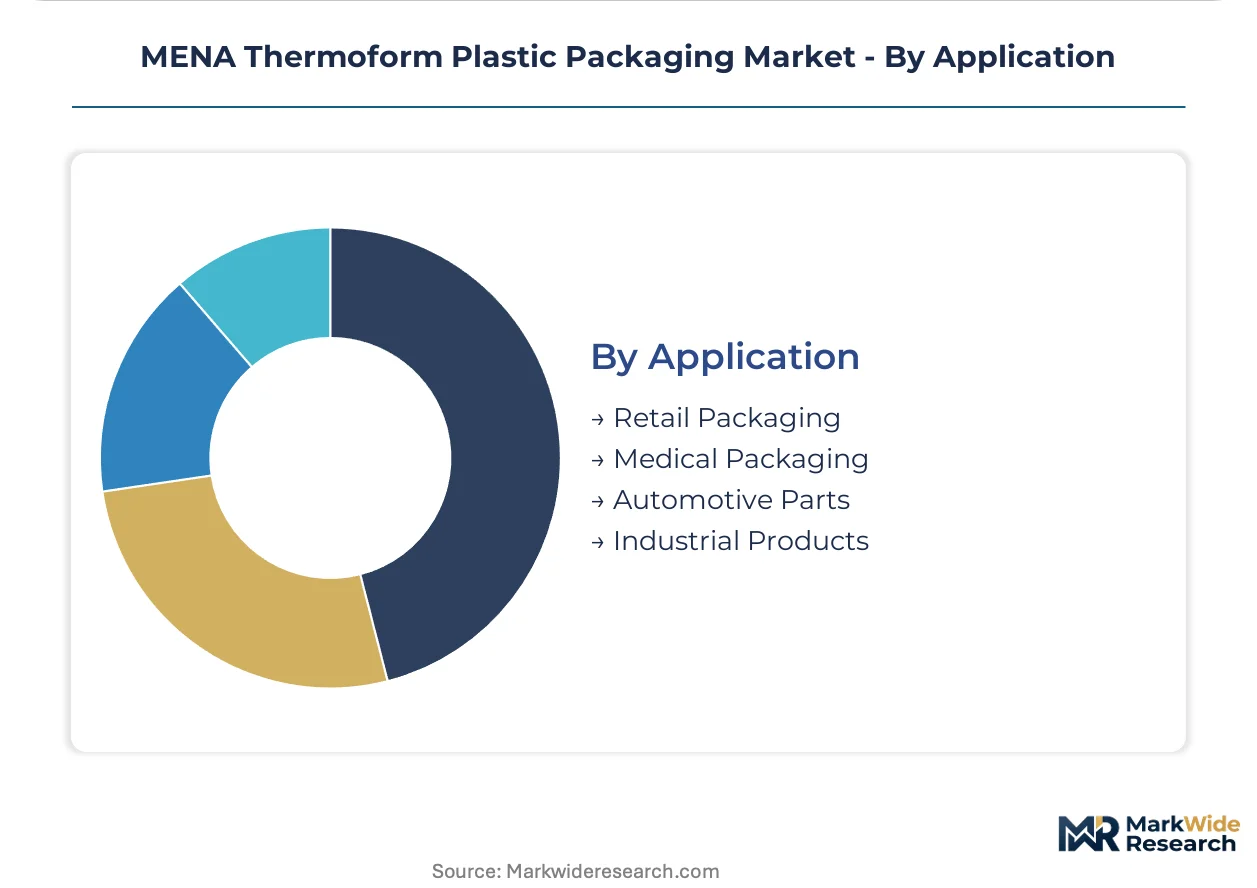
Application:
Performance certification requirements separate medical and automotive segments from commodity retail and industrial tiers.
- Retail Packaging:Modified-atmosphere meat trays, produce containers, and promotional formats serve supermarket and food service channels. Saudi retail consolidation compresses supplier panels toward vendor-managed inventory partnerships.
- Medical Packaging:Sterile barrier trays and procedure kits require ISO 14644 Class 8 cleanroom forming and documented accelerated aging protocols. Twelve-to-eighteen-month facility qualification cycles in Saudi Arabia constrain new entrant supply.
- Automotive Parts:Reusable dunnage trays and shipping containers protect interior trim and electronics components during assembly plant distribution. Yanbu petrochemical integration anchors domestic material supply.
- Industrial Products:Low-specification trays and totes for hardware and component logistics tolerate wider gauge variation. Nile Delta labor cost advantages attract volume production.
Retail packaging captures shipment volume; medical packaging commands the most stringent qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA notification requirements anchor Saudi Arabia's regulatory dominance across the MENA thermoform corridor. National standards in Egypt and the UAE create complementary compliance frameworks that shape converter siting decisions.
Saudi Arabia
Hospital network purchasing reforms generate pull-through demand for ISO 15378-certified medical clamshells. SFDA food-contact material notifications filter informal imports toward certified domestic converters. The Riyadh-Jeddah corridor concentrates tray procurement for supermarket cooperatives.
United Arab Emirates
MOHAP sterile barrier protocols mandate accelerated aging validation for medical device packaging. Dubai Healthcare City cardiac device manufacturers specify Tyvek-lidded PETG formats with documented peel characteristics. Jebel Ali manufacturing bases sustain Gulf-wide distribution networks for perishable-ready formats.
Egypt
Nile Delta food processors drive cost-sensitive bulk container demand for dairy and ready-meal applications. EOS polymer import specifications determine which resin grades gain market access. Upper Egypt provinces offer first-mover positioning for tray suppliers partnering with supermarket format rollout.
Qatar
Healthcare infrastructure investment generates demand for medical-grade cleanroom thermoforming capacity. National procurement centralization aligns with GCC regulatory harmonization trends. Doha logistics hub development compresses lead times for cold-chain perishable distribution.
Kuwait
Food retail consolidation creates vendor-managed inventory requirements for promotional tray programs. Import dependency on Gulf resin supply chains exposes converters to ethylene feedstock pricing volatility. Shuwaikh industrial zone concentrates domestic forming capacity for local distribution.
MENA Thermoform Plastic Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with petrochemical-backed converters controlling upstream resin access while medical-grade cleanroom operators capture premium positioning. The market structure favors players with in-house regulatory affairs capabilities over import-reliant traders. Two dominant archetypes emerge: Yanbu-integrated petrochemical converters and Jebel Ali-based Gulf distributors. Competitive moves center on co-location with logistics hubs and ISO 14644 cleanroom qualification cycles.
Within the integrated tier, Takween Advanced Industries anchors Saudi domestic supply through petrochemical integration, while Hotpack Packaging Industries LLC exemplifies the Gulf distribution archetype from its UAE manufacturing base. Napco National occupies the medical-grade specialization vector, representing the cleanroom certification barrier that constrains new entrant supply.
| Leading Market Players |
|---|
| Takween Advanced Industries |
| Hotpack Packaging Industries LLC |
| Cristal Plastic Industrial LLC |
| Nascho General Trading LLC |
| Nuplas Industries |
| Interplast (Harwal Group of Companies) |
| Napco National |
| Ghanplast |
| Arabian Plastics Industrial Company Limited |
| Others |
Supply & Pricing Matrix
SFDA food-contact notification requirements gate both supplier qualification and price differentiation simultaneously, as converters with in-house regulatory affairs capabilities command premium positioning over import-reliant traders while informal importers face systematic exclusion from Saudi procurement channels.
Pricing Analysis
Saudi-Egyptian price spreads of 15-25 percent persist across equivalent tray specifications, driven by Gulf petrochemical integration advantages versus Nile Delta converters dependent on imported resin. Three-tier pricing structure across ISO 15378-certified medical, SFDA-compliant food-contact, and uncertified industrial grades separates premium clamshells from commodity bulk formats. Pricing pressure stems from ethylene feedstock volatility transmitting directly to polyethylene sheet costs, squeezing margin predictability for Egyptian facilities. Supermarket cooperatives in Riyadh exhibit lowest price sensitivity due to vendor-managed inventory partnerships, while Upper Egypt dairy processors remain most cost-conscious.
Supply Chain Analysis
Saudi Arabia and the UAE anchor regional resin production through Yanbu petrochemical integration and Jebel Ali manufacturing bases respectively. Converter operations draw from polyethylene and polypropylene feedstocks, oxygen-scavenging additive packages, and Tyvek lidding materials for medical applications. Single-source vulnerability concentrates in Gulf ethylene supply chains, where pricing swings transmit asymmetrically to Egyptian import-dependent facilities. Distribution runs through cold-chain logistics hubs co-located with forming capacity, compressing lead times for perishable-ready formats across GCC markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance-as-a-service represents the fastest-expanding recurring-revenue layer, as converters bundle SFDA notification management and ISO 14644 cleanroom certification support with base tray and clamshell supply contracts.
For Market Incumbents: Consolidate procurement relationships with Saudi supermarket cooperatives through vendor-managed inventory partnerships that lock in volume commitments. Deepen backward integration into barrier coextrusion capabilities to defend margin position against fiber-based molded pulp substitution threats in European export channels. Prioritize ISO 15378 certification maintenance to sustain premium positioning in medical device packaging segments. For New Entrants and Emerging Players: Digital print integration services for short-run promotional packaging represent an under-served white-space where incumbents lack UV decoration-to-forming line convergence expertise. Target Upper Egypt provinces for tray supply partnerships aligned with supermarket format rollout in underdeveloped cold-chain corridors. Lead with regulatory compliance bundling as the primary go-to-market angle, differentiating against import-reliant traders lacking SFDA notification capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core thermoforming divisions lacking medical-grade cleanroom infrastructure. Long-term viability centers on converters with demonstrated regulatory affairs capabilities and logistics hub co-location across the analysis window. Watch MOHAP-EU MDR harmonization progress as the signal indicating accelerated consolidation opportunity for dual-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coextrusion Capacity Addition | Oxygen-scavenging layer integration extends meat tray shelf life for UAE retail chains. |
| ISO 14644 Cleanroom Qualification | Class 8 validation unlocks Saudi hospital network procurement for cardiac device manufacturers. |
| Digital Print Line Integration | UV decoration convergence enables seasonal promotional packaging for Riyadh supermarket cooperatives. |
| Backward Integration into Resin Compounding | In-house additive package formulation accelerates SFDA notification timelines for domestic converters. |
| Cold-Chain Logistics Partnership | Hub co-location compresses lead times for perishable-ready formats across GCC distribution networks. |
Research Methodology
The analysis maps tray, clamshell, blister, and container sub-sectors, each validated through polymer processing technicians, regulatory affairs managers at converter facilities, procurement directors at Saudi supermarket cooperatives, and biomedical engineers at Dubai Healthcare City cardiac device manufacturers. Primary interview insights triangulate against customs and trade data for resin imports, SFDA food-contact notification registries, MOHAP sterile barrier guidance documents, and SEC filings from listed petrochemical suppliers. Bottom-up unit economics for extrusion and forming operations reconcile with top-down market sizing derived from cold-chain infrastructure investment disclosures.
Consistency checks validate volume and value outputs against GCC logistics hub throughput data, hospital procurement database trends, and retail packaging consumption indices across the analysis window. Segmentation dimensions model product geometry, resin chemistry, sterilization requirement, and end-use application tier. CAGRs derive from fitted growth curves applied to disclosed capacity expansions, regulatory implementation timelines, and import substitution patterns. Industry-specific inputs include ethylene feedstock pricing volatility indices and ISO certification penetration rates by converter facility.
Underlying assumptions cover SFDA notification processing timelines, MOHAP-EU MDR harmonization progress, and cold-chain infrastructure buildout completion rates, with deviation risk concentrated in extended approval backlogs for new additive packages and fiber-based substitution acceleration in European export markets. Recalibration cycles align with material shifts in Gulf petrochemical pricing regimes and healthcare procurement centralization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Latin America Plastic Bottles Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Africa BOPP Films Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
United Kingdom Plastic Packaging Market