
 Polymer Waterproof Rolls Market | 2026-2036
Polymer Waterproof Rolls Market Size, Share, and Industry Trends Forecast 2026-2036
Polymer Waterproof Rolls Market Insights
Wholesale distribution through regional building-material distributors is narrowing as direct contractor relationships and project-specific procurement gain share. Sika AG leverages its global formulation expertise to sustain specification-grade positioning across European infrastructure tenders. BASF SE anchors its polymer supply chain through captive resin production, while Beijing Oriental Yuhong Waterproof Technology Co., Ltd. dominates domestic distribution density across China's provincial construction markets.
Polymer waterproof rolls are multi-layer synthetic membranes, typically 1.2–2.0 mm in thickness, manufactured through calendering or extrusion of thermoplastic polyolefin, polyvinyl chloride, or ethylene propylene diene monomer compounds to create impermeable barriers against hydrostatic pressure and vapor transmission. TPO waterproof rolls are capturing specification share in commercial roofing due to heat-weld seam integrity and reflective surface properties that reduce thermal load. SBS polymer modified bitumen sheets retain dominant volume in foundation and below-grade applications where puncture resistance and cold-flexibility down to -25°C remain critical performance parameters.
REACH compliance in Europe and China's GB 18242 standards for elastomeric waterproofing membranes are elevating testing protocols for aging resistance and seam durability, effectively filtering marginal suppliers from specification chains. The US EPA's stormwater management guidelines and state-level energy codes in California and New York are accelerating membrane specifications that integrate cool-roof reflectivity with waterproofing performance. Stakeholders must monitor evolving polymer feedstock volatility and regional certification reciprocity to align manufacturing footprints with shifting demand centers.
Market Dynamics
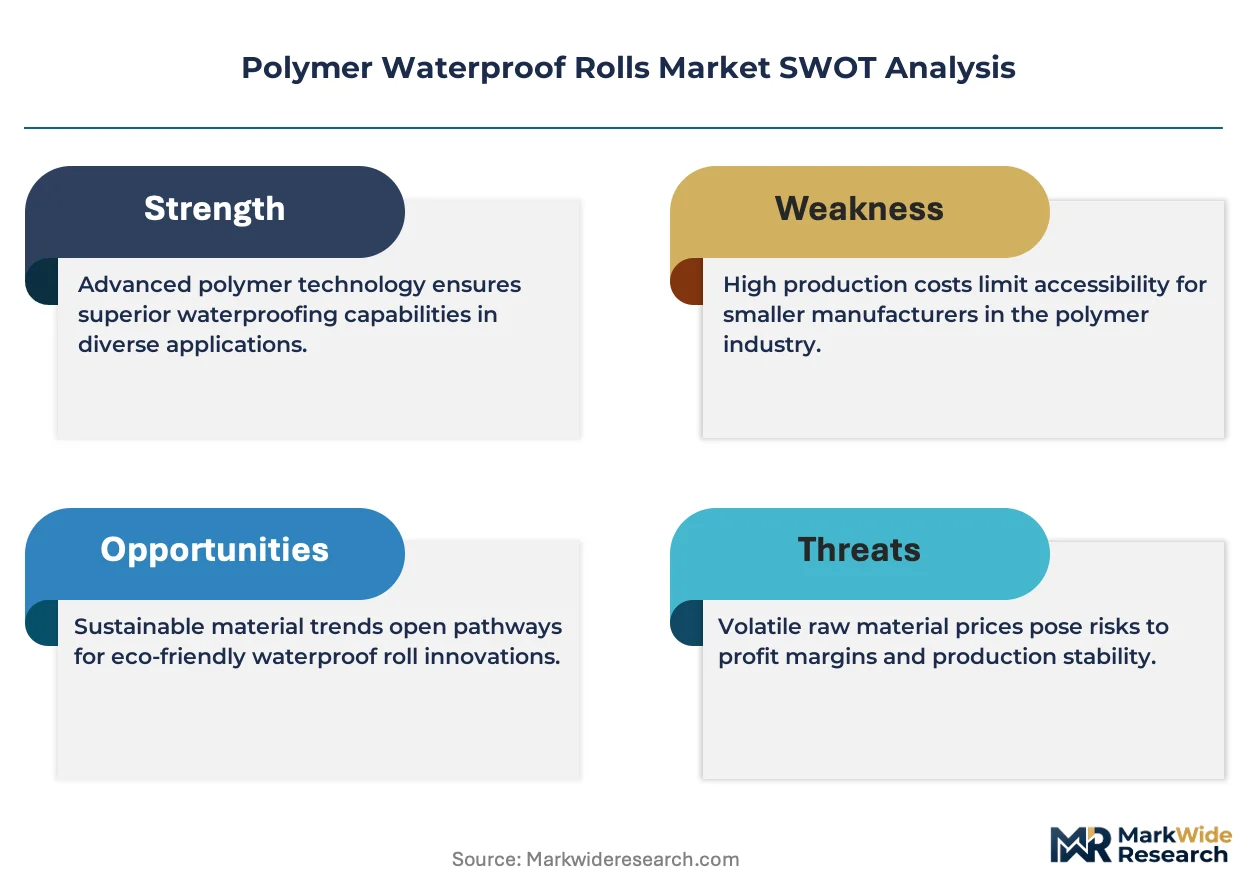
Specification-grade procurement is tightening around polymer waterproof rolls as infrastructure developers prioritize seam durability certification over unit cost, compressing margins for uncertified regional suppliers while elevating formulation-intensive manufacturers.
Growth Catalysts
- GB 18242 compliance thresholds:China's elastomeric membrane standards now mandate accelerated aging tests, forcing technology upgrades that filter out marginal producers and concentrate volume with certified suppliers.
- Metro rail foundation specifications:Underground transit authorities in India specify SBS-modified bitumen sheets with -25°C cold-flex ratings for tunnel waterproofing, creating sustained demand pull.
- TPO heat-weld technology:Thermoplastic polyolefin membranes with reflective surfaces are capturing commercial roofing specifications where thermal load reduction aligns with California and New York energy codes.
Market Restraints
- Propylene feedstock volatility:EPDM and TPO compound costs fluctuate with naphtha-cracker output cycles, squeezing formulation margins without corresponding pricing power.
- Regional supply concentration:Captive resin production anchors with BASF SE and select Chinese petrochemical groups, creating procurement dependency for non-integrated membrane converters.
- Self-adhesive bitumen substitutes:Liquid-applied polyurethane membranes are gaining share in complex geometry applications where roll membrane seaming creates technical risk.
Strategic Opportunities
- Western and southern India construction corridors:Smart city and metro investments in Maharashtra, Gujarat, Karnataka, and Tamil Nadu concentrate waterproofing demand with multi-year project visibility.
- EU Construction Products Regulation harmonization:CE marking reciprocity across member states enables single-facility supply to pan-European infrastructure tenders, reducing certification fragmentation.
- Cool-roof and stormwater integration:US EPA guidelines and state-level mandates in California combine reflectivity and waterproofing performance, opening specification space for dual-function membrane systems.
Industry Challenges
- Seam welding technician certification:TPO and PVC membrane integrity depends on certified installer density, creating bottlenecks in markets where training infrastructure lags specification uptake.
- REACH and GB standard testing timelines:Aging resistance and seam durability protocols extend product qualification cycles, delaying revenue recognition for new formulation launches.
- Legacy bitumen specification inertia:SBS-modified sheets dominate below-grade applications where contractor familiarity and established warranty chains resist technology transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymer Waterproof Rolls Market |
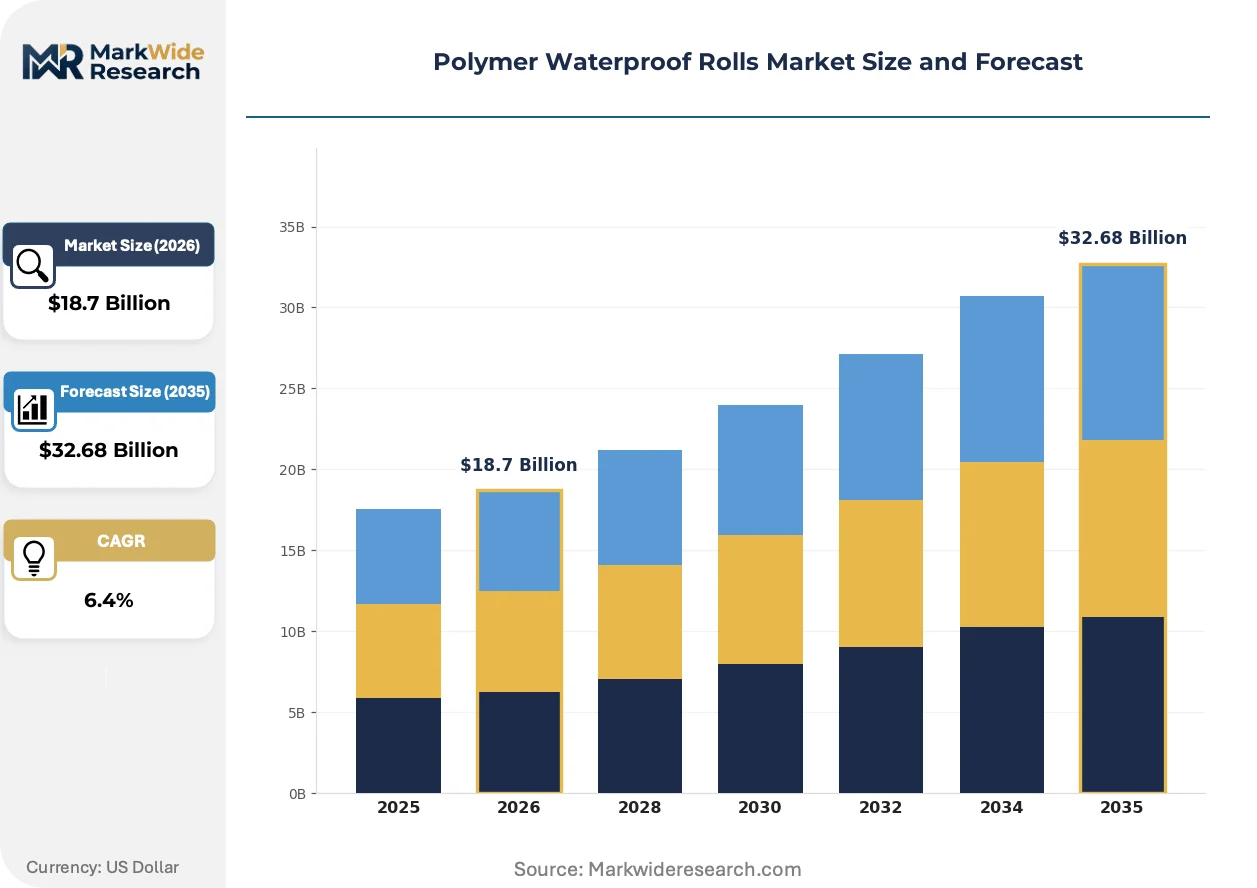
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
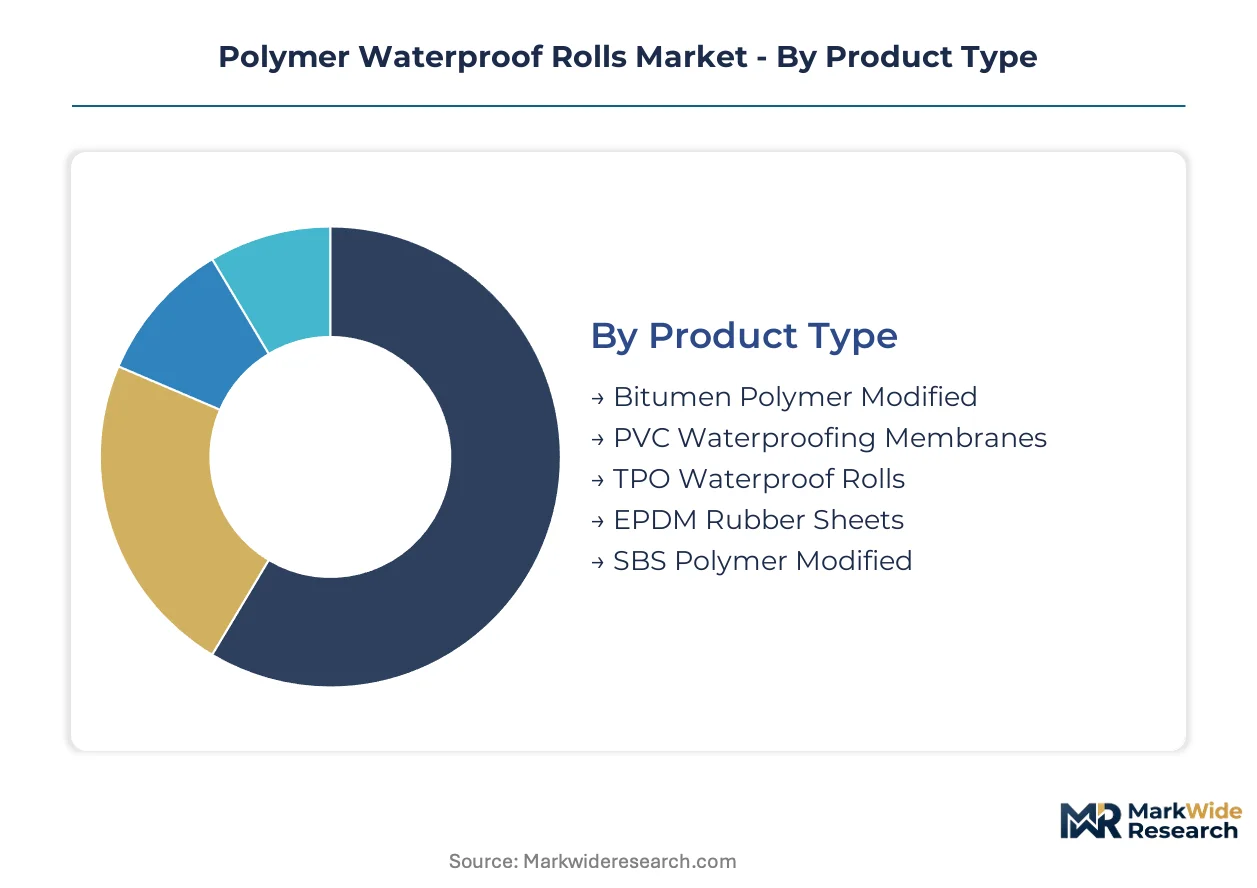
| Segmentation | Product Type: Bitumen Polymer Modified, PVC Waterproofing Membranes, TPO Waterproof Rolls, EPDM Rubber Sheets, SBS Polymer Modified Application: Roofing Membranes, Foundation Protection, Tunnel Waterproofing, Balcony Waterproofing, Bridge Deck Sealing Installation Method: Hot Melt Application, Torch-On Method, Self-Adhesive, Liquid Applied, Cold Adhesive End User Industry: Construction Firms, Infrastructure Developers, Commercial Builders, Residential Contractors, Waterproofing Specialists |
| Companies Covered | Sika AG, BASF SE, Soprema Group, RPM International Inc., Saint-Gobain, Tremco Incorporated, Johns Manville, Carlisle Companies Inc., Beijing Oriental Yuhong Waterproof Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymer Waterproof Rolls Market Trends and Innovations
Membrane technology evolution is compressing the traditional specification hierarchy as performance data transparency and automated installation methods restructure buyer decision criteria across commercial and infrastructure segments.
Pre-applied HDPE composite membranes with pressure-sensitive adhesive layers are rendering obsolete conventional loose-laid systems with separate protection boards in deep foundation applications. Transit authorities and data center developers specify these composites for their self-sealing puncture resistance and elimination of field seaming. The technology is rendering obsolete multi-step installation protocols that previously required specialized crews and extended cure times.
REACH authorization requirements for phthalate plasticizers in PVC membranes are accelerating formulation shifts toward bio-based and non-aromatic alternatives across European specification chains. ECHA substance evaluation timelines are compressing supplier transition windows, forcing premature reformulation investments. German and French infrastructure tenders now require full material disclosure, shifting competitive advantage toward integrated resin producers with captive plasticizer substitution capabilities.
Direct contractor engagement is displacing traditional distributor intermediaries in large-scale infrastructure procurement across China's provincial construction markets. Beijing Oriental Yuhong Waterproof Technology Co., Ltd. and comparable domestic suppliers are building project-specific technical service teams that embed with tunnel and metro contractors from design through commissioning. This channel compression is most advanced in China's high-speed rail and urban transit verticals where specification influence concentrates with state-owned construction enterprises.
Polymer Waterproof Rolls Market Segmentation
Polymer waterproof rolls fragment across formulation chemistry, installation physics, and project-scale procurement patterns. Specification-grade differentiation now hinges on seam integrity certification and cold-flex performance thresholds rather than commodity pricing.
Product Type:
Formulation chemistry determines thermal performance, seam weldability, and regulatory compliance pathways across infrastructure and commercial verticals.
- TPO Waterproof Rolls:Thermoplastic polyolefin compounds deliver heat-weld seam integrity and reflective surfaces that reduce thermal load. California and New York energy codes specify TPO for commercial roofing where cool-roof mandates intersect with waterproofing requirements.
- SBS Polymer Modified:Styrene-butadiene-styrene modified bitumen sheets achieve -25°C cold-flex ratings essential for tunnel and below-grade applications. Metro rail authorities in India specify these sheets for foundation waterproofing where puncture resistance and low-temperature pliability dominate performance criteria.
- Bitumen Polymer Modified:APP-modified formulations provide heat resistance for exposed roofing in high-temperature climates.
- PVC Waterproofing Membranes:Flexible polyvinyl chloride systems offer chemical resistance for industrial containment applications.
- EPDM Rubber Sheets:Ethylene propylene diene monomer compounds deliver UV stability and elongation recovery for single-ply roofing systems.
SBS-modified bitumen holds installed capacity in below-grade foundations. TPO is rotating up the share rankings in commercial roofing specifications.
Application:
Project geometry and hydrostatic pressure exposure dictate membrane specification, with below-grade and traffic-bearing applications commanding premium certification tiers.
- Foundation Protection:Deep foundation waterproofing demands pre-applied HDPE composites with pressure-sensitive adhesive layers that eliminate field seaming. Data center developers and transit authorities specify these systems for self-sealing puncture resistance in critical infrastructure.
- Tunnel Waterproofing:Underground transit projects require multi-layer systems with -25°C cold-flex certification and seam durability testing under hydrostatic pressure. India's metro rail investments in Maharashtra and Karnataka concentrate demand for SBS-modified sheets with accelerated aging compliance.
- Roofing Membranes:Commercial and industrial building envelopes specify TPO or PVC for heat-weld seam integrity.
- Bridge Deck Sealing:Traffic-bearing membranes require high-puncture resistance and asphalt overlay compatibility.
- Balcony Waterproofing:Liquid-applied polyurethane alternatives compete in complex geometries where roll seaming creates technical risk.
Foundation protection holds installed capacity in infrastructure procurement. Tunnel waterproofing is climbing the fastest as metro rail investments accelerate across India's western and southern states.
Installation Method:
Application physics and crew certification requirements structure competitive positioning between specialized contractors and generalist builders.
- Self-Adhesive:Pressure-sensitive adhesive layers eliminate open-flame equipment requirements and reduce installation crew certification burdens. Pre-applied HDPE composites with factory-bonded adhesive accelerate schedules in deep foundation projects where cure time compression delivers project cost savings.
- Hot Melt Application:Automated welding equipment delivers consistent seam integrity for TPO and PVC membranes in large-format commercial roofing. Equipment capital requirements and technician certification density create barriers to entry in markets where specification uptake outpaces training infrastructure.
- Torch-On Method:Propane-fueled equipment applies modified bitumen sheets with controlled heat fusion.
- Cold Adhesive:Solvent-based bonding systems suit restricted-flame environments and complex detailing.
- Liquid Applied:Polyurethane and polyurea spray systems penetrate irregular substrates where roll membranes cannot conform.
Torch-on methods hold installed capacity in residential and light commercial segments. Self-adhesive systems are gaining share fastest as infrastructure projects prioritize schedule compression and safety compliance.
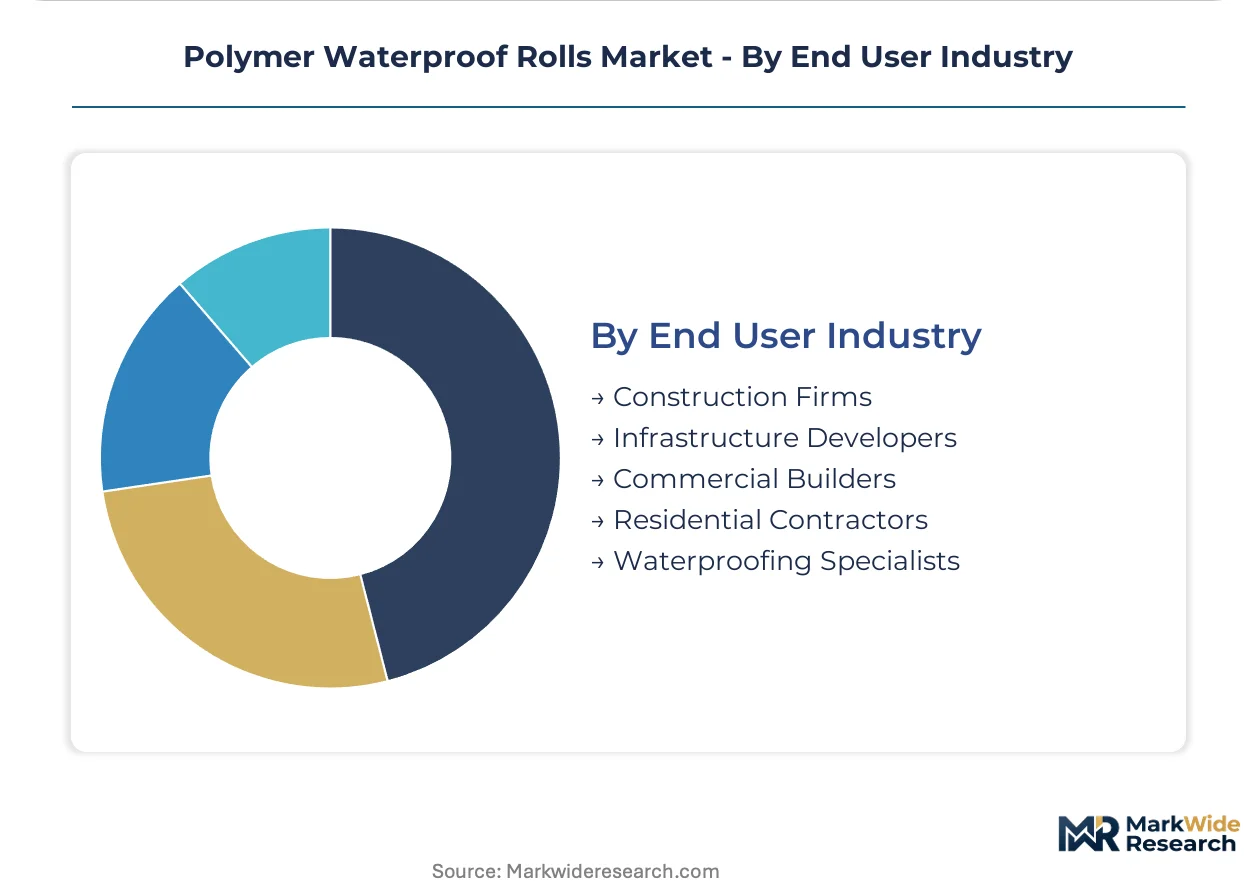
End User Industry:
Procurement scale and specification influence concentrate with state-backed infrastructure developers and tier-one construction enterprises.
- Infrastructure Developers:State-owned construction enterprises and transit authorities command specification influence through multi-year project pipelines. China's high-speed rail and urban transit verticals concentrate procurement with suppliers embedding technical service teams from design through commissioning.
- Construction Firms:Large-scale commercial and residential general contractors balance unit cost against warranty chain reliability. Direct contractor relationships are displacing traditional distributor intermediaries in China's provincial construction markets.
- Commercial Builders:Office, retail, and hospitality developers specify cool-roof membranes where energy codes mandate thermal performance.
- Waterproofing Specialists:Niche contractors deliver certified installation for high-liability applications with performance warranties.
- Residential Contractors:Single-family and multi-family builders prioritize cost efficiency and crew familiarity over specification-grade differentiation.
Infrastructure developers hold installed capacity in specification-grade procurement. Construction firms are rotating up the share rankings as direct engagement models compress distribution margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB 18242 standards for elastomeric waterproofing membranes and India's metro rail expansion programs are redirecting procurement volumes toward certified suppliers in high-growth construction corridors.
China
Provincial construction markets in Jiangsu and Zhejiang provinces are absorbing pre-applied HDPE composite membranes for high-speed rail foundations. GB standards for waterproofing durability now mandate accelerated aging tests that filter marginal producers from state-owned enterprise tender lists. Beijing-Tianjin-Hebei corridor concentrates specification-grade procurement with suppliers embedding technical service teams from design through commissioning.
India
Metro rail authorities in Maharashtra and Karnataka specify SBS-modified bitumen sheets with -25°C cold-flex ratings for tunnel waterproofing applications. BIS certification requirements for construction materials are elevating testing protocols for seam durability under hydrostatic pressure. Smart city investments in Gujarat and Tamil Nadu concentrate multi-year waterproofing demand with direct contractor engagement displacing traditional distributor channels.
United States
Commercial roofing contractors in California and New York specify TPO membranes where state energy codes mandate cool-roof reflectivity alongside waterproofing performance. EPA stormwater management guidelines are accelerating membrane specifications that integrate dual-function thermal and moisture protection. Texas and Florida construction markets absorb self-adhesive systems for schedule compression in large-format retail and logistics facility envelopes.
Germany
Infrastructure tenders in Bavaria and North Rhine-Westphalia now require full material disclosure under REACH authorization timelines for phthalate plasticizer alternatives. ECHA substance evaluation protocols are compressing supplier transition windows toward bio-based formulation pathways. Frankfurt and Munich transit authorities specify multi-layer membrane systems with CE marking reciprocity enabling pan-European supply consolidation.
Saudi Arabia
NEOM and Red Sea Project developments are importing specification-grade membranes for below-grade foundation protection in coastal saline environments. The national regulator's construction product compliance framework aligns with EU technical standards for aging resistance certification. Riyadh and Eastern Province industrial zones concentrate procurement with infrastructure developers prioritizing seam durability over unit cost in giga-project tenders.
Polymer Waterproof Rolls Market Competitive Landscape
On the supply side, the industry is consolidating around formulation-intensive manufacturers with captive resin production and certified installation networks. Three strategic archetypes dominate: integrated petrochemical groups with backward polymer supply control, regional specialists with dense distribution in provincial construction markets, and specification-grade formulators with global tender qualification. Competitive dynamics center on M&A activity targeting installer certification infrastructure and capacity expansion in high-growth metro rail corridors.
Within the integrated chemical conglomerate tier, BASF SE anchors European supply chains through captive resin production, while Sika AG exemplifies specification-grade positioning across infrastructure tender markets. Beijing Oriental Yuhong Waterproof Technology Co., Ltd. occupies the dominant distribution density position in China's provincial construction markets, representing the regional specialist archetype with embedded technical service capabilities.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Soprema Group |
| RPM International Inc. |
| Saint-Gobain |
| Tremco Incorporated |
| Johns Manville |
| Carlisle Companies Inc. |
| Beijing Oriental Yuhong Waterproof Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Jiangsu and Zhejiang provinces anchor polymer resin capacity that feeds membrane converters across Asia-Pacific, concentrating upstream pricing leverage with integrated petrochemical groups while squeezing formulation margins for non-captive producers. Certification-grade procurement by China's state-owned construction enterprises amplifies this dynamic, as GB 18242 compliance thresholds filter marginal suppliers and concentrate volume with certified manufacturers commanding specification premiums.
Pricing Analysis
Certification level creates the primary spread between premium specification-grade membranes and commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by seam durability testing and cold-flex performance ratings. Cost compression in standard-grade rolls intensifies as propylene feedstock volatility squeezes converter margins without corresponding pricing power. Infrastructure developers demonstrate lowest price sensitivity, prioritizing accelerated aging compliance over unit cost, while residential contractors remain most responsive to per-square-meter pricing.
Supply Chain Analysis
Contract manufacturing concentrates with BASF SE's captive resin facilities in Germany and Ludwigshafen, plus Chinese petrochemical groups in Shandong and Jiangsu provinces. Raw material flows draw from naphtha-cracker output cycles, EPDM compound imports, and bitumen feedstock from regional refineries. Single-source vulnerability runs through propylene monomer supply tethered to regional cracker economics. Distribution runs through direct contractor engagement displacing traditional building-material distributors in China's provincial construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid-applied polyurethane membranes threaten roll membrane incumbents in complex geometry applications where seaming creates technical risk, forcing defensive positioning around certification infrastructure and installer networks.
For Market Incumbents: Entrench specification-grade positioning through captive resin production and accelerated aging certification investments that liquid-applied substitutes cannot replicate. Deepen backward integration into polymer feedstock to insulate margins from naphtha-cracker volatility. Prioritize technical service team embedding with state-owned construction enterprises in China's high-speed rail verticals. For New Entrants and Emerging Players: Pursue white-space opportunities in western and southern India where metro rail investments concentrate multi-year demand with limited certified supplier density. Target tunnel waterproofing applications in Maharashtra and Karnataka where BIS certification requirements filter incumbent competition. Lead with self-adhesive HDPE composites that compress installation schedules and reduce crew certification burdens. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated formulators with captive plasticizer substitution capabilities navigating REACH authorization timelines. Long-term viability rests on acquisition targets combining regional distribution density with specification-grade tender qualification. Monitor ECHA substance evaluation announcements as inflection indicators for premature reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | BASF SE's captive supply insulates margins from naphtha-cracker volatility cycles. |
| Installer Certification Network Expansion | Sika AG's technician density removes TPO seam welding bottlenecks in specification uptake. |
| Direct Contractor Engagement Model | Beijing Oriental Yuhong's technical service embedding captures China's provincial tender flow. |
| Phthalate Plasticizer Substitution R&D | REACH authorization timelines force premature reformulation toward bio-based alternatives. |
| Pre-applied HDPE Composite Capacity Addition | Self-sealing puncture resistance eliminates field seaming in data center foundation projects. |
Research Methodology
A spread of perspectives from membrane plant managers, procurement leads at infrastructure developers, waterproofing contractor crews, and regulatory compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed chemical conglomerates, GB standards documentation, and ECHA substance evaluation records. Bottom-up project pipeline enumeration triangulated against top-down construction spending forecasts across the analysis window.
Demand-supply balance modeling anchored volume projections, with segmentation across formulation chemistry, installation physics, project scale, and regional regulatory clusters. CAGRs derived from elasticity-adjusted price trajectories and substitution threat penetration curves. Industry-specific forecast inputs incorporated metro rail capital expenditure pipelines and cool-roof mandate adoption rates in California and New York.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese petrochemical groups or accelerated liquid-applied membrane penetration would shift outcomes beyond modeled ranges. Quarterly review of ECHA authorization timelines, BIS certification queue depths, and propylene monomer spread movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Soft Touch Lamination Film Market
Poly film
Embossed Film Market
Poly film
Bio-PET Film Market
Poly film
Wrap Around Label Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
Starch-Based Plastic Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
Automotive Wrap Films Market
Poly film
APET Film Market
Poly film
Polycoated Packaging Market
Poly film
Soft Touch Film Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Polyurethane (PU) Film Market
Poly film
Polystyrene Films Market
Poly film
Nigeria Plastic Packaging Films Market
Poly film
North America Plastic Film Packaging Market