
 Global BOPP Films Market | 2026-2036
Global BOPP Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global BOPP Films Market Foresight
Market Context with Strategic Players
Direct-to-converter supply chains is rewriting procurement patterns across the BOPP films landscape. Jindal Poly Films leverages backward integration into resin production to control feedstock costs across South Asian operations. Toray Group anchors its position through advanced tenter-frame technology leadership in Japan. Cosmo Films Limited differentiates via specialized holographic and security film portfolios serving premium labeling segments.
Technical Definition and Structural Segments
Biaxially oriented polypropylene films are thermoplastic polymer sheets stretched longitudinally and transversely to achieve molecular alignment, yielding thickness ranges typically between 8 and 60 micrometers with high tensile strength and moisture barrier properties. These films serve primarily as printable, sealable substrates for flexible packaging, adhesive lamination, and pressure-sensitive labels across consumer goods industries. Metalized BOPP film commands premium positioning due to its oxygen and light barrier performance in snack and confectionery packaging, while holographic variants capture margin pools in anti-counterfeiting applications. Flexible packaging as an application dimension dominates volume offtake, though labeling applications sustain higher per-unit value extraction.
Regulatory Frame and Forward-Looking Close
REACH in Europe and FDA food-contact regulations in the United States govern monomer migration limits and additive permissibility, directly constraining formulation choices and qualifying protocols for export-bound producers. China's GB standards and India's BIS certification requirements create additional compliance layers for regional market access. Stakeholders must monitor evolving extended producer responsibility frameworks and recyclability mandates, as these will determine which film constructions retain commercial viability across key jurisdictions.
Market Dynamics
Backward integration into polypropylene resin production is compressing margin structures for non-integrated converters across Asia-Pacific and European supply chains. Direct-to-converter procurement models are eliminating traditional distributor layers, forcing film specialists to absorb logistics and inventory risk previously held by intermediaries.
Growth Catalysts
- REACH compliance migration:European converters upgrading to high-purity BOPP grades are locking in multi-year supply contracts with certified resin suppliers, creating captive demand pools for compliant film producers.
- India's PLI scheme:Domestic packaging material incentives are accelerating localized BOPP capacity additions, reducing import dependence for snack food and pharmaceutical blister applications.
- Coextrusion barrier technology:Five-layer film structures with ethylene vinyl alcohol interlayers are displacing aluminum foil in retort pouch applications, expanding BOPP's addressable market in ready-to-eat meals.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and refinery output shifts in the Middle East are transmitting price instability to film-grade polypropylene pellet costs.
- China supply concentration:Zhejiang and Jiangsu provinces host over sixty percent of Asia's BOPP film capacity, creating geographic risk exposure for brand owners dependent on single-origin supply.
- Polyethylene terephthalate substitution:PET films with equivalent clarity and improved heat resistance are capturing premium labeling applications in beverage and cosmetics segments.
Strategic Opportunities
- Brazil's underpenetrated snack packaging:Local converter consolidation and multinational brand localization are creating demand for metalized barrier films previously imported from North America.
- Extended producer responsibility mandates:EU packaging waste directives are incentivizing mono-material BOPP constructions that simplify mechanical recycling streams versus multilayer alternatives.
- Digital printing convergence:Electron beam curing systems paired with corona-treated BOPP substrates are enabling short-run customization for craft food brands without plate costs.
Industry Challenges
- Tenter frame technician scarcity:Specialized knowledge of simultaneous stretching mechanics and thermal profile optimization is concentrating among aging workforces in Germany and Japan.
- FDA food-contact notification timelines:Novel additive packages for high-barrier films face eighteen-month qualification cycles, delaying commercialization of next-generation oxygen scavenger technologies.
- Legacy lamination asset stranding:Solvent-based adhesive coating lines face escalating volatile organic compound compliance costs in California and South Coast Air Quality Management District jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global BOPP Films Market |
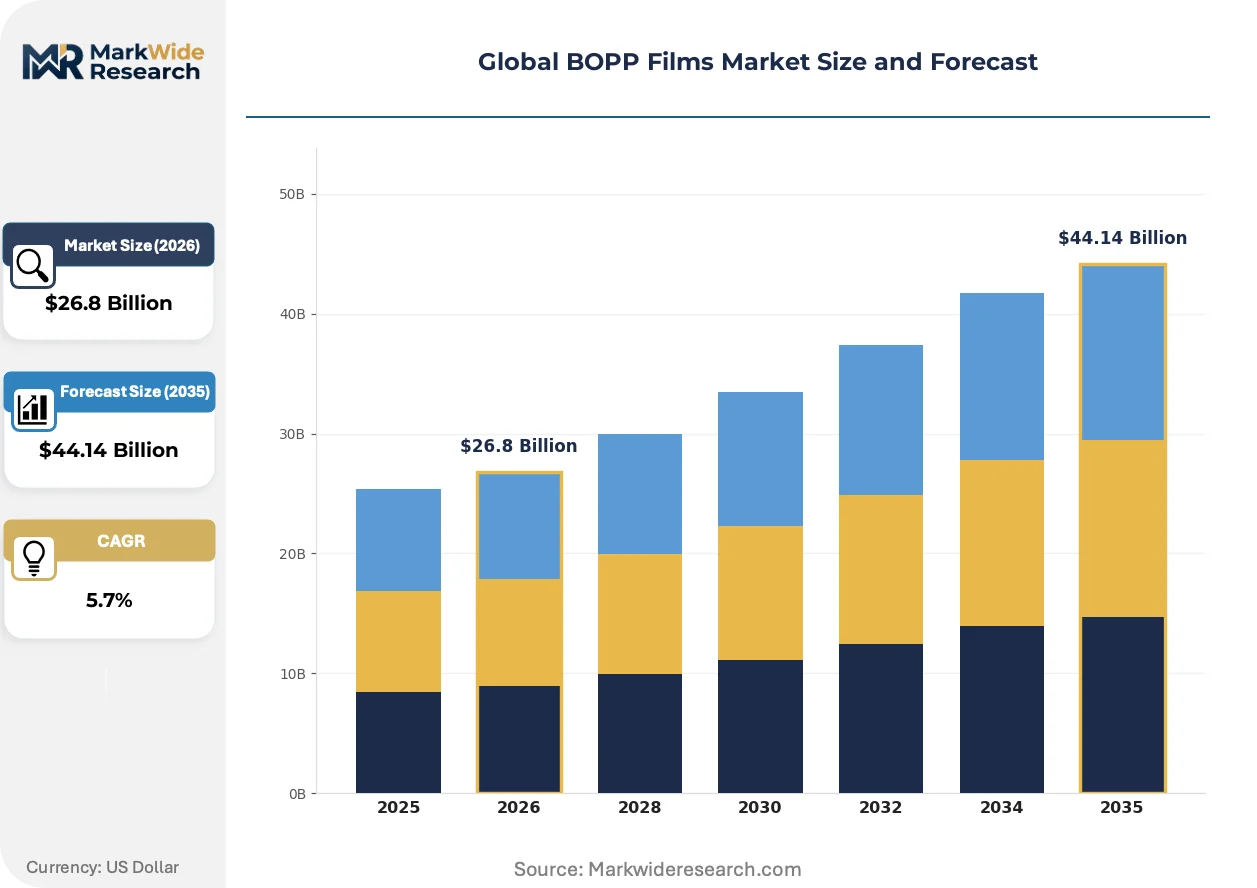
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $44.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte BOPP Film, Glossy BOPP Film, Metalized BOPP Film, Holographic BOPP Film Application: Flexible Packaging, Labeling, Lamination, Printing, Stationery End User Industry: Food & Beverage, Personal Care, Pharmaceuticals, Electronics, Textiles Packaging Type: Rolls, Sheets, Cut Films, Rewound Films |
| Companies Covered | CCL Industries, NAN YA Plastics Corporation, Cosmo Films Limited, Innovia Films, Taghleef Industries, Jindal Poly Films, Toray Group, Mondi, Uflex Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global BOPP Films Market Shifts & Advancements
Digital workflow integration is collapsing design-to-delivery timelines for customized packaging films. Machine learning algorithms now optimize molecular orientation parameters in real-time during biaxial stretching operations.
Machine-direction orientation (MDO) technology paired with inline vacuum metallization is virtualizing traditional offline lamination steps for snack food packaging. Major brand owners in North American salty snack segments are specifying these integrated lines for mid-volume SKU proliferation. The compression of capital intensity and floor space requirements is enabling regional hub strategies versus centralized mega-plants.
China's GB standards for food-contact plastics are tightening monomer migration thresholds effective 2025, forcing reformulation of random copolymer sealant layers. Domestic producers in Shandong and Guangdong provinces are accelerating compliance testing to maintain export eligibility. Japanese converters serving premium confectionery markets are preemptively adopting these specifications to secure year-round supply continuity.
Brand owner direct specification of film substrates is disintermediating traditional converter autonomy in packaging procurement. Major food multinationals now mandate approved supplier lists with locked resin sources and certified additive packages. This concentration of buying power is most pronounced in German and Dutch retail private-label supply chains, where sustainability scorecards weight recyclability and carbon intensity metrics.
Global BOPP Films Market Segmentation
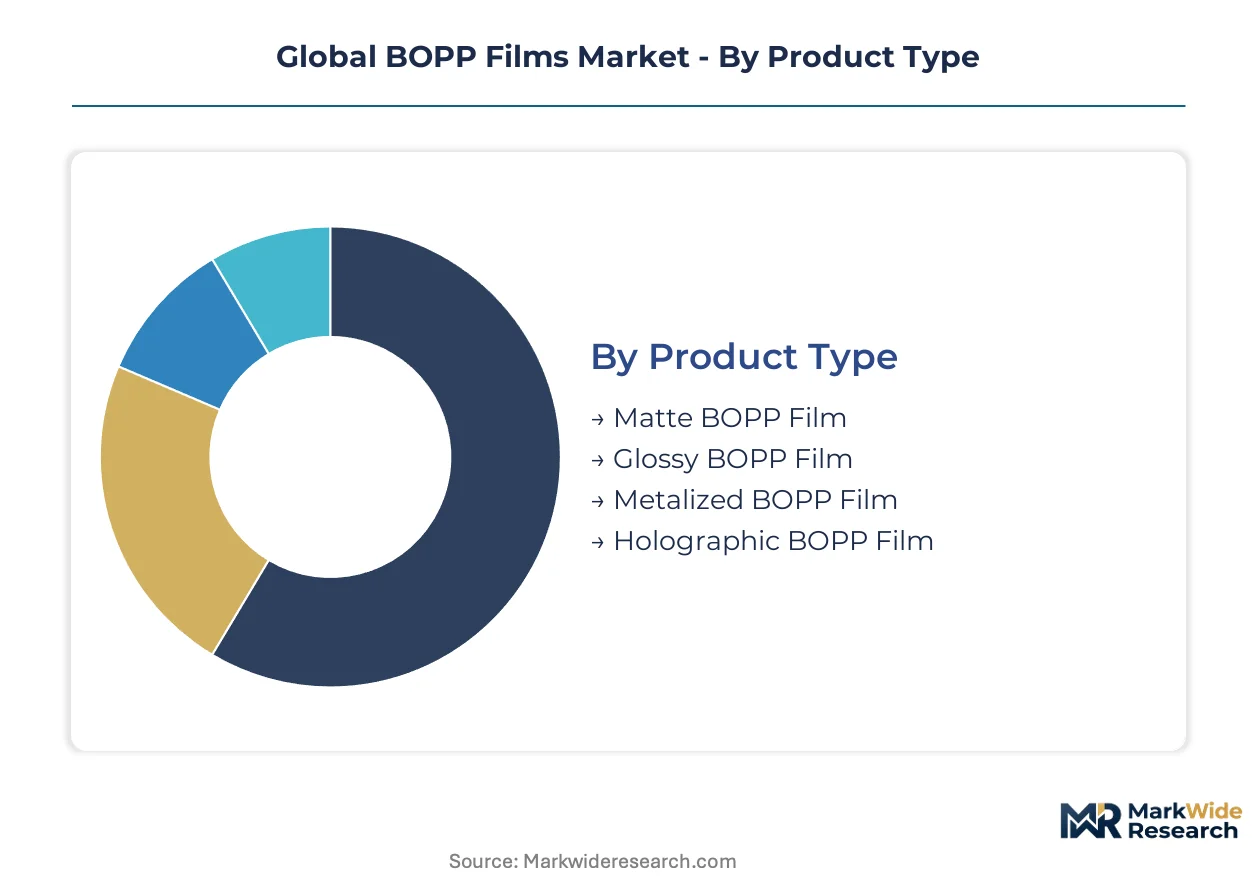
BOPP film producers optimize production lines around specific surface finishes and barrier specifications. Segmentation by product type, application, and end-use industry determines pricing power and technical qualification requirements. Packaging format choices influence logistics economics and converter equipment compatibility.
Product Type:
Surface finish and optical properties define cost tiers and margin structures across BOPP film grades.
- Matte BOPP Film:Diffuse surface treatment reduces glare for premium label applications in cosmetics and spirits. European luxury goods converters specify matte grades for tactile differentiation in shelf-facing packaging. Demand concentrates in German and French labeling clusters where haptic quality commands price premiums.
- Glossy BOPP Film:High-clarity transparent construction maximizes product visibility in retail environments. Snack food packaging in North America and confectionery wrapping in Japan drive volume offtake for this standard grade. Heat-sealable variants dominate flow-wrap applications for bakery and frozen food segments.
- Metalized BOPP Film:Vacuum-deposited aluminum layer delivers oxygen and moisture barrier performance. Retort pouch applications in ready-to-eat meals and coffee packaging utilize this grade for extended shelf stability.
- Holographic BOPP Film:Diffractive surface patterns enable anti-counterfeiting and premium decorative effects. Security labeling for pharmaceuticals and tobacco tax stamps represents primary demand concentration.
Glossy BOPP holds installed capacity. Metalized BOPP is rotating up the share rankings.
Application:
Functional requirements across converting processes segment demand by barrier needs, printability, and lamination compatibility.
- Flexible Packaging:Primary film substrate for form-fill-seal equipment in food manufacturing. Stand-up pouches and pillow bags for snacks, confectionery, and frozen foods consume the largest volume share. China's processed food sector and India's organized retail expansion are accelerating specification of high-slip, low-SIT variants.
- Labeling:Pressure-sensitive adhesive face stock for beverage, personal care, and logistics applications. Clear-on-clear constructions for premium cosmetics and no-label look designs sustain per-unit value premiums. German and Italian wine labeling markets favor wet-glue compatible BOPP over paper alternatives.
- Lamination:Web substrate for adhesive and extrusion lamination to paper, foil, or other films. Publishing and flexible packaging converters utilize this grade for composite structure assembly.
- Printing:Corona-treated surfaces optimized for flexographic and gravure ink adhesion. Publication wrappers and promotional overwrap applications specify this segment.
- Stationery:Transparent and translucent films for document lamination and office supplies. School supply and corporate document protection markets in Southeast Asia drive regional demand.
Flexible Packaging dominates volume. Labeling is climbing the fastest.
End User Industry:
Customer type determines regulatory burden, specification stringency, and contract duration in BOPP procurement.
- Food & Beverage:Largest consuming sector with FDA and EFSA compliance requirements for direct food contact. Snack foods, bakery, confectionery, and ready-to-eat meals specify metalized and high-barrier constructions. India's PLI scheme for packaging materials is localizing supply for this vertical.
- Personal Care:Premium labels and sachet packaging for cosmetics, hair care, and oral hygiene. Japanese and South Korean beauty brands drive demand for ultra-clear and soft-touch surface treatments.
- Pharmaceuticals:Blister packaging and strip pack applications requiring strict extractables and leachables control. FDA drug master file compliance and EU pharmacopeia adherence qualify suppliers for this segment.
- Electronics:Capacitor films and release liner substrates for tape applications. This segment demands ultra-thin gauges and controlled electrical properties.
- Textiles:Packaging for garments, fabrics, and technical textiles. Polybag applications for apparel export from Bangladesh and Vietnam utilize standard glossy grades.
Food & Beverage anchors capacity allocation. Pharmaceuticals is gaining share fastest.
Packaging Type:
Physical delivery format shapes converter workflow integration and inventory economics.
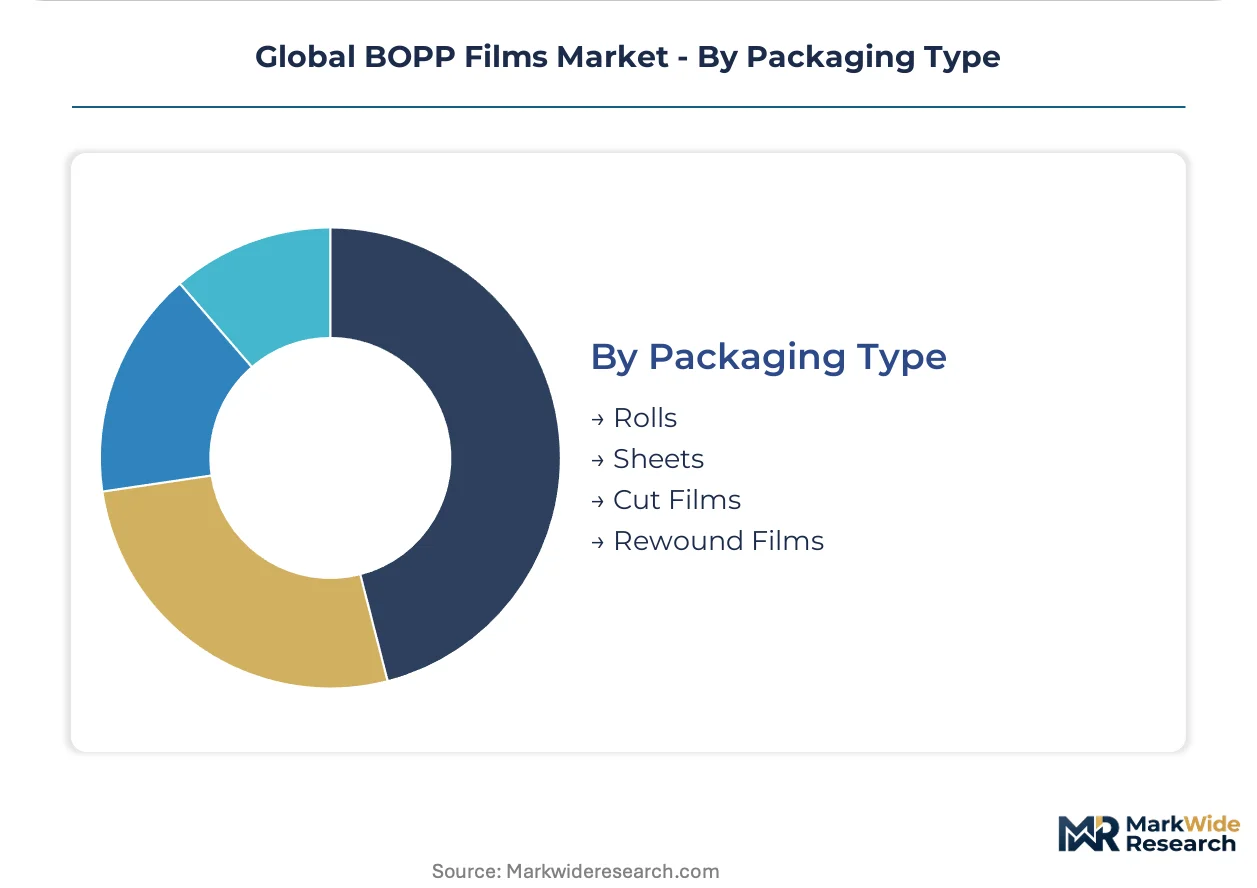
- Rolls:Standard mill wound format for continuous web processing on flexographic and rotogravure presses. Large format rolls reduce changeover frequency in high-speed packaging lines. German and Dutch converters prefer jumbo rolls for slitting optimization.
- Sheets:Cut-to-size formats for sheet-fed offset and screen printing applications. Point-of-sale display and promotional insert production utilize this format.
- Cut Films:Pre-dimensioned pieces for manual packaging operations and small-batch converters. Artisan food producers and specialty chemical packagers specify this format.
- Rewound Films:Custom slit widths for specific equipment configurations and narrow web label presses. Digital printing service providers in North America favor precision-rewound narrow rolls for short-run efficiency.
Rolls hold installed capacity. Rewound Films is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany command pricing premiums for REACH-certified high-barrier grades, while Chinese producers compete on scale in standard glossy segments. This asymmetry shapes procurement strategies across food and beverage supply chains.
China
GB standards tightening monomer migration thresholds in 2025 are forcing reformulation of random copolymer sealant layers. Domestic producers in Shandong and Guangdong provinces are accelerating compliance testing to maintain export eligibility. Zhejiang and Jiangsu provinces host over sixty percent of Asia's BOPP film capacity, creating geographic concentration risk for brand owners.
Germany
European converters upgrading to high-purity BOPP grades are locking in multi-year supply contracts with certified resin suppliers. REACH compliance migration creates captive demand pools for compliant film producers. The Rhine-Ruhr industrial cluster anchors tenter-frame technology leadership, though specialized technician knowledge concentrates among aging workforces.
India
The PLI scheme for domestic packaging materials is accelerating localized BOPP capacity additions, reducing import dependence for snack food and pharmaceutical blister applications. BIS certification requirements create additional compliance layers for regional market access. Maharashtra and Gujarat states are emerging as converter consolidation zones for organized retail expansion.
United States
FDA food-contact notification timelines for novel additive packages face eighteen-month qualification cycles, delaying commercialization of next-generation oxygen scavenger technologies. Solvent-based adhesive coating lines face escalating volatile organic compound compliance costs in California and South Coast Air Quality Management District jurisdictions. Midwest packaging corridors specify metalized barrier films for coffee and ready-to-eat meal applications.
Japan
Converters serving premium confectionery markets are preemptively adopting China's GB specifications to secure year-round supply continuity. METI industrial policy supports advanced tenter-frame technology retention. The Kanto region maintains technology leadership through simultaneous stretching mechanics expertise concentrated in Greater Tokyo industrial zones.
Global BOPP Films Market Competitive Landscape
Backward-integrated resin producers and specialized film converters split the market between cost-controlled volume plays and premium barrier technology. The vendor base concentrates around three strategic archetypes: petrochemical-backed integrated producers, independent multi-line converters, and niche holographic security specialists. Capacity expansion and direct-to-brand procurement partnerships constitute the dominant competitive moves reshaping supply relationships.
Within the integrated-producer tier, Jindal Poly Films exemplifies backward integration into resin production to control feedstock costs across South Asian operations. Toray Group anchors Japanese technology leadership through tenter-frame expertise. Cosmo Films Limited occupies a position among specialized converters differentiating via holographic and security film portfolios for premium labeling segments.
| Leading Market Players |
|---|
| CCL Industries |
| NAN YA Plastics Corporation |
| Cosmo Films Limited |
| Innovia Films |
| Taghleef Industries |
| Jindal Poly Films |
| Toray Group |
| Mondi |
| Uflex Limited |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Zhejiang and Jiangsu provinces is compressing spot pricing for standard glossy grades while tightening supply for REACH-certified metalized films, forcing European converters to absorb premium differentials for compliant resin sourcing.
Pricing Analysis
The customization-premium spread between configured-to-order holographic security films and commodity glossy grades exceeds three-to-one in European procurement. Contract-based long-term offtake dominates, with price differentiation driven by FDA food-contact certification tiers and volume scale commitments. Pricing pressure stems from propylene feedstock volatility transmitted through naphtha-cracking economics. Brand owners in German retail private-label chains exhibit lowest price sensitivity, prioritizing sustainability scorecards over unit economics.
Supply Chain Analysis
Tariff exposure between China and North American brand owners dominates supply chain risk calculus for film procurement teams. Manufacturing concentrates in China, India, and Germany, with raw material dependencies on polypropylene resin, ethylene vinyl alcohol copolymers, and vacuum metallization aluminum feedstocks. Single-source vulnerability concentrates in Zhejiang province tenter-frame clusters. Distribution runs through direct-to-converter procurement models that eliminated traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH and FDA compliance timelines create switching costs that lock converters into qualified supplier relationships.
For Market Incumbents: Build certification moats by accelerating BIS and GB standards pre-qualification ahead of 2025 implementation deadlines. PET film substitution in premium beverage labeling represents the primary technology threat. Capacity addition in Maharashtra and Gujarat states captures India's PLI scheme incentives. Channel control through approved supplier list concentration with multinational food brands reinforces pricing power. For New Entrants and Emerging Players: Brazil's underpenetrated snack packaging market represents the most penetrable entry point for metalized barrier film specialists. Regional converter consolidation and multinational brand localization create demand previously served by North American imports. Digital printing convergence with electron beam curing systems enables short-run craft food brand targeting without plate cost infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among backward-integrated resin producers with captive feedstock supply. Long-term viability across the projection horizon favors specialists with holographic security portfolios and pharmaceutical-grade certification. The signal to watch is extended producer responsibility mandate acceleration in EU jurisdictions, which will mechanically advantage mono-material BOPP constructions over multilayer alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Jindal Poly Films exemplifies feedstock cost control across South Asian operations. |
| REACH Compliance Pre-Certification | German converters lock multi-year contracts ahead of 2025 GB standards alignment. |
| Digital Printing Workflow Convergence | Electron beam curing paired with corona-treated substrates collapses design-to-delivery timelines. |
| Mono-Material Construction Transition | EU packaging waste directives mechanically advantage recyclable BOPP over multilayer films. |
| Regional Hub Capacity Expansion | Machine-direction orientation with inline metallization enables mid-volume SKU proliferation. |
Research Methodology
A spread of perspectives from tenter-frame operations managers, resin procurement leads at integrated producers, flexible packaging converters, and regulatory affairs directors converged on the working assumptions. Primary fieldwork combined with secondary validation against customs trade data, BIS certification registries, FDA food-contact notification filings, and EU ECHA substance restriction updates. Bottom-up capacity utilization estimates triangulated against top-down demand modeling from food and beverage packaging procurement databases.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include surface finish grade, barrier specification tier, end-use industry vertical, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules cross-referenced against converter equipment purchase intentions. Propylene feedstock price trajectories and tenter-frame technician availability constraints served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in refinery output shifts and naphtha-cracking spreads would shift the trajectory. Forecasts reflect assumptions on regulatory timeline adherence and resin qualification protocol stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyimide Films and Tapes Market
Poly film
Poly Coated Paper Market
Poly film
Cleanroom Film and Bags Market
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
PVC Films Market
Poly film
Global Polyethylene Packaging Market
Poly film
Packaging Film Market
Poly film
Blown Film Extruder Market
Poly film
United Kingdom Plastic Packaging Films Market
Poly film
Lidding Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Laminated Packaging Films Market
Poly film
Bopet Films Market
Poly film
Global Reclosable Films Market
Poly film
Soft Touch Lamination Film Market
Poly film
Bundling Film Market