
 Bakery Bread Bag Market | 2026-2036
Bakery Bread Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Bread Bag Market Outlook
Artisan bakery chains is decoupling from mass-market retail as the primary growth vector for specialty bread bags. Mondi Plc leverages its integrated paper operations to dominate kraft-based bakery packaging across Central Europe. Smurfit Kappa anchors its position through corrugated supply chain adjacencies that extend into printed bread bag solutions. Huhtamaki Oyj competes on fiber-formed technology leadership, particularly in grease-resistant bag structures for crusty loaves.
Bakery bread bags are engineered packaging containers, typically constructed from bleached or unbleached kraft paper, polyethylene-lined films, or compostable biopolymers, designed to maintain product freshness through controlled moisture vapor transmission while protecting against physical damage during distribution. Paper bag types command premium positioning in European markets where retailer sustainability mandates prioritize fiber-based substrates over plastic alternatives. Heat seal closure methods are displacing twist ties in automated bakery lines, reducing labor touchpoints and improving shelf presentation consistency. Biodegradable bag types remain niche but capture margin pools where municipal composting infrastructure supports end-of-life claims.
FDA food contact regulations govern polymer migration limits in US-sold bread bags, while EU REACH and F-Gas Regulation frameworks restrict certain fluorinated grease-barrier chemistries in paper-based formats. EFSA compliance requirements for recycled fiber content are tightening specification windows for converters serving pan-European bakery brands. Stakeholders must monitor evolving extended producer responsibility schemes that will reshape material cost structures and regional sourcing footprints.
Market Dynamics
EU REACH and F-Gas Regulation frameworks are forcing material transitions across European bakery packaging, compressing specification windows for converters and redrawing competitive advantage around barrier chemistry expertise.
Growth Catalysts
- EU Green Deal packaging mandates:Retailer sustainability scorecards in Germany, France, and the Netherlands now penalize plastic bread bags, redirecting procurement toward fiber-based alternatives.
- Industrial bakery automation:Heat seal closure systems are displacing twist ties on high-speed lines, reducing labor touchpoints and improving shelf presentation consistency.
- Municipal composting infrastructure:Cities with established organic waste collection create viable end-of-life pathways for biodegradable bag claims, unlocking premium positioning.
Market Restraints
- Kraft pulp cost volatility:Unbleached fiber prices fluctuate with Nordic pulp mill capacity, squeezing converter margins on fixed-price retail contracts.
- Fluorinated barrier restrictions:ECHA scrutiny of PFAS chemistries limits grease-resistant paper options, forcing costly reformulation of crusty loaf packaging.
- Corrugated supply chain concentration:Smurfit Kappa and Mondi control integrated paperboard networks, creating sourcing dependency for printed bread bag substrates.
Strategic Opportunities
- Artisan bakery chain expansion:Specialty retailers in Belgium and Switzerland seek differentiated packaging that signals craft credentials through tactile paper finishes.
- Digital printing convergence:Variable data inkjet on kraft substrates enables short-run seasonal designs, collapsing minimum order quantities for regional bakeries.
- Extended producer responsibility schemes:France's Citeo and Italy's CONAI packaging taxes reward fiber-based formats with lower fee schedules.
Industry Challenges
- Barrier chemistry certification timelines:EFSA compliance for novel grease-resistant coatings extends 18-24 months, delaying product launches.
- Legacy equipment retrofit costs:Converting from wicketed plastic to paper formats requires bagger line modifications that smaller industrial bakeries defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Bread Bag Market |
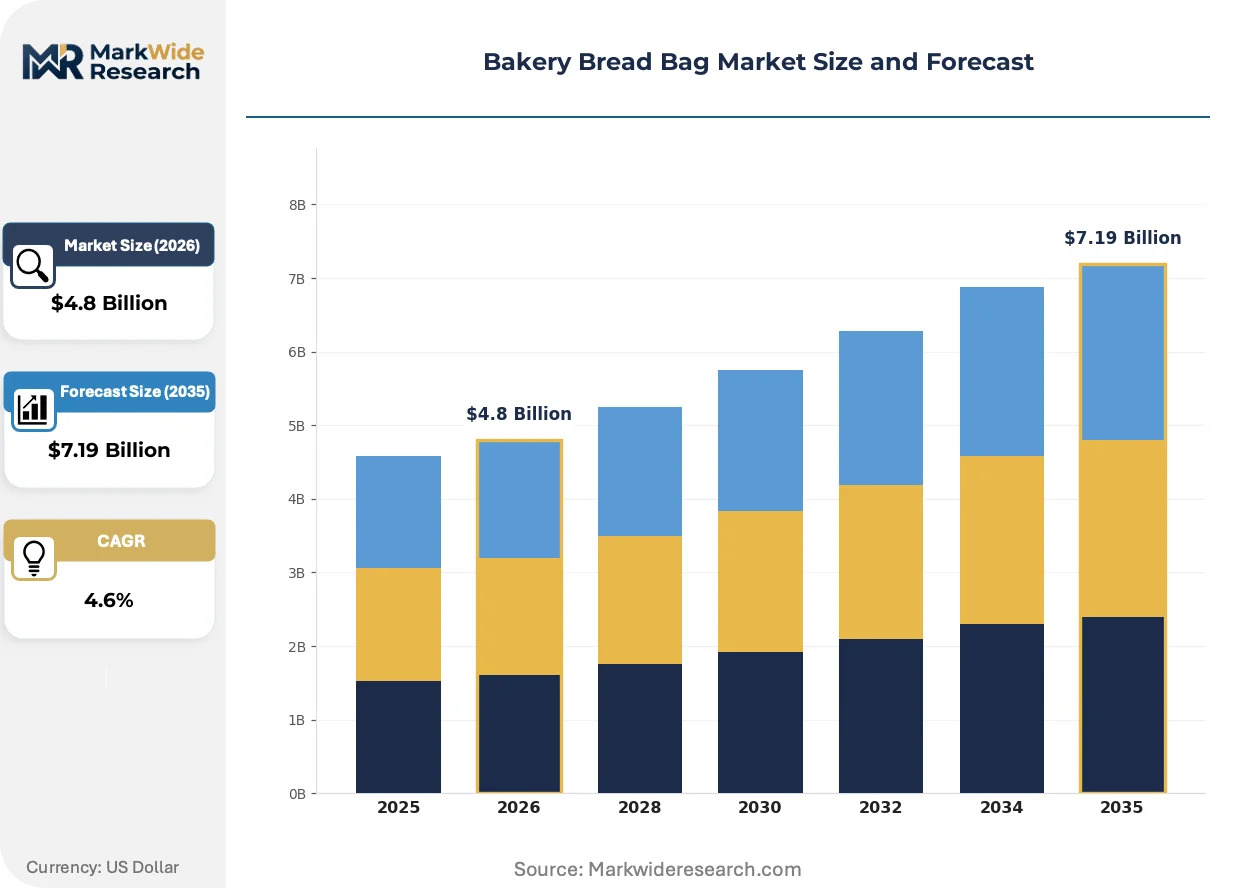
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bag Type: Plastic, Paper, Biodegradable, Foil Closure Method: Twist Tie, Zip Lock, Heat Seal, Clip End User: Bakeries, Retailers, Food Service, Distributors Size: Small, Medium, Large, Extra Large |
| Companies Covered | Mondi Plc, Smurfit Kappa, St. Johns Packaging, Huhtamaki Oyj, WestRock Company, Amcor Plc, Berry Global Inc., International Paper Co., Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Bread Bag Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are compressing the viable solution set for bakery bread bags, favoring suppliers with integrated fiber operations and proprietary barrier formulations.
Water-based barrier coatings are consolidating technical alternatives to fluorinated chemistries in European markets. Industrial bakeries in Germany and Austria have adopted these formulations at scale since 2023. The technology is consolidating supplier positions around converters with in-house coating capabilities, marginalizing toll-coating dependent competitors.
EU F-Gas Regulation amendments are phasing down certain fluorinated greenhouse gases used in barrier manufacturing. This restriction eliminates established grease-proofing chemistries from the approved substance list. Paper-based bread bag producers serving pan-European brands are accelerating migration to silicone and clay-based alternatives.
Direct store delivery consolidation is compressing distributor networks serving independent bakeries. Regional wholesalers in Northern Italy and Bavaria are acquiring route-based delivery operations, centralizing packaging procurement decisions. This concentration shifts bargaining power toward buyers capable of specifying custom bag formats across multiple outlet locations.
Bakery Bread Bag Market Segmentation
Bread bag procurement splits sharply between high-volume industrial contracts and premium artisan specifications. Understanding these fault lines reveals where margin pools concentrate and which material technologies command pricing power.
Bag Type:
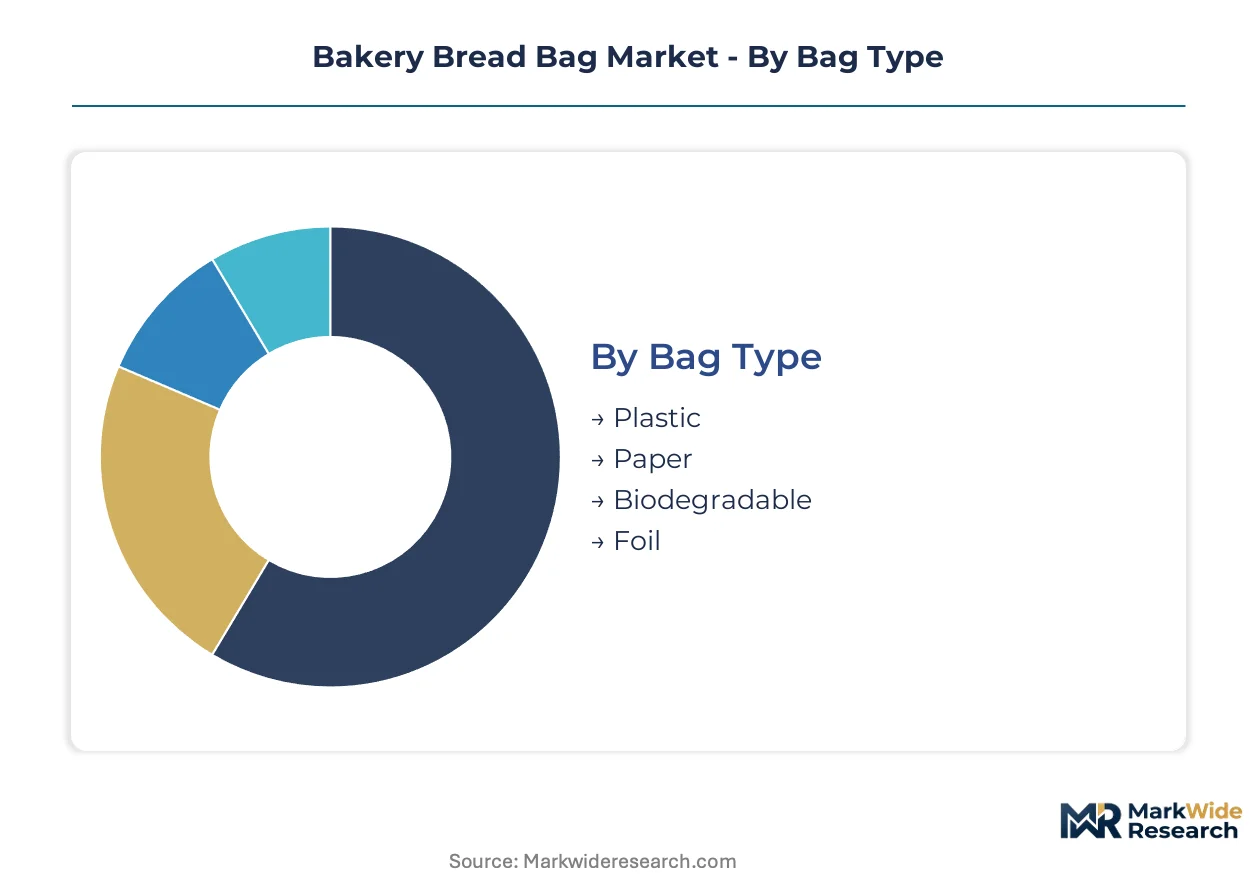
Paper formats capture premium positioning while plastic retains volume dominance in cost-sensitive channels.
- Paper:Bleached and unbleached kraft constructions with controlled moisture vapor transmission rates serve German and French retailers under EU Green Deal mandates. Industrial bakeries in Bavaria and Baden-Württemberg specify these for automated heat-seal lines.
- Plastic:Polyethylene-lined films dominate US supermarket chains and emerging market distributors where FDA compliance focuses on migration limits rather than material bans. Cost efficiency sustains this segment in high-throughput operations.
- Biodegradable:Compostable biopolymers target Belgian and Swiss municipal collection zones with established organic waste infrastructure.
- Foil:Metallized barrier layers protect specialty loaves in premium retail with extended shelf-life requirements.
Today's leader: Plastic. Tomorrow's challenger: Paper.
Closure Method:
Automation economics favor seal technologies over manual handling in industrial bakery settings.
- Heat Seal:Thermal bonding systems integrate with high-speed bagging equipment across Austrian and German industrial lines, eliminating labor touchpoints and ensuring uniform shelf presentation.
- Twist Tie:Wicketed plastic bags with wire closures persist in smaller bakeries deferring capital equipment upgrades.
- Zip Lock:Reclosable tracks appear in retail-ready formats for multi-serve bread varieties.
- Clip:Plastic or wooden clips serve artisan positioning in Belgian specialty chains.
Procurement is shifting toward heat seal as labor costs climb across Central European manufacturing.
End User:
Channel concentration is compressing distributor networks and centralizing packaging specifications.
- Bakeries:Industrial producers in Germany drive standardized bag formats through direct store delivery consolidation, while artisan chains in Switzerland demand tactile paper finishes signaling craft credentials.
- Retailers:French and Dutch supermarket sustainability scorecards now penalize plastic, redirecting category management toward fiber-based alternatives with lower Citeo fee schedules.
- Food Service:Hotels and restaurants prioritize cost efficiency and storage density in back-of-house operations.
- Distributors:Regional wholesalers in Northern Italy and Bavaria are acquiring route-based delivery operations, shifting bargaining power toward centralized procurement.
Bakeries anchor current volume. Retailers are gaining fastest as sustainability mandates harden.
Size:
Format standardization varies by channel automation level and product portfolio breadth.
- Medium:Standard loaf dimensions dominate supermarket and industrial bakery procurement, matching automated bagger specifications across German and Austrian production lines.
- Large:Family-size formats concentrate in US club retail and European hypermarket channels with multi-serve positioning.
- Small:Single-serve and specialty portions serve grab-and-go convenience retail.
- Extra Large:Bulk formats target food service and institutional baking operations.
Medium formats command the specification standard. Large formats are expanding most quickly as household consolidation trends favor bigger pack sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production footprints as converters relocate to jurisdictions with lower compliance costs for PFAS-free barrier coatings. Nordic pulp proximity and centralized bakery automation drive site selection decisions across the continent.
Germany
Industrial bakeries in Bavaria and Baden-Württemberg specify heat-seal kraft formats for automated lines serving Aldi and Lidl supply chains. The EU Green Deal packaging mandates enforce plastic reduction targets by 2030. Stuttgart-based converters are expanding water-based coating capacity to serve pan-European brands.
France
Artisan chain expansion in Lyon and Bordeaux creates demand for tactile paper finishes with craft positioning. Citeo extended producer responsibility fees penalize plastic formats while rewarding fiber-based alternatives. The Île-de-France cluster concentrates digital printing investments for short-run seasonal designs.
United States
FDA migration limits govern polyethylene-lined films dominating Walmart and Kroger procurement. Regional industrial bakeries in the Midwest defer capital upgrades from wicketed plastic to paper formats. Chicago-area distributors are consolidating route networks and centralizing packaging specifications.
Belgium
Municipal composting infrastructure in Flanders and Wallonia unlocks premium positioning for biodegradable bag claims. Artisan retailers in Brussels seek differentiated substrates signaling sustainability credentials. The Port of Antwerp anchors import logistics for Nordic kraft pulp supply.
Switzerland
Swissmedic-adjacent food contact standards exceed EU baseline requirements, filtering supplier qualification. Specialty chains in Zurich and Geneva demand metallized barrier layers for extended shelf-life positioning. The Basel industrial corridor hosts coating specialists serving Alpine bakery brands.
Bakery Bread Bag Market Competitive Environment
Capacity expansion dominates the current landscape as integrated paper producers add in-house barrier coating lines to capture margin from toll-dependent competitors. The vendor base splits between pulp-to-package conglomerates and regional converting specialists. Two archetypes prevail: Nordic pulp-integrated giants controlling substrate supply, and mid-tier converters competing on digital printing agility. M&A activity concentrates in corrugated adjacencies, while technology licensing agreements proliferate for water-based grease barrier formulations.
Within the integrated pulp-to-package tier, Mondi Plc and Smurfit Kappa exemplify the Nordic model of captive kraft supply. Huhtamaki Oyj occupies a distinct position emphasizing fiber-formed technology leadership. These three anchors represent how barrier chemistry expertise and upstream pulp access are consolidating competitive advantage as fluorinated coating restrictions tighten specification windows.
| Leading Market Players |
|---|
| Mondi Plc |
| Smurfit Kappa |
| St. Johns Packaging |
| Huhtamaki Oyj |
| WestRock Company |
| Amcor Plc |
| Berry Global Inc. |
| International Paper Co. |
| Sealed Air |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EFSA-compliant barrier coatings and conventional formulations splits procurement economics across German and French retail channels, compressing margins on legacy stock while rewarding in-house coating investments with pricing premiums and supply security.
Pricing Analysis
Distributor margin layers concentrate value capture in the artisan channel, where Belgian and Swiss specialty retailers absorb markups for tactile kraft finishes and metallized barrier substrates. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA certification status, heat-seal automation compatibility, and volume scale. Price erosion runs through plastic formats as EU Green Deal mandates harden retailer sustainability scorecards. Industrial bakeries in Bavaria exhibit highest price sensitivity due to fixed-contract exposure to Nordic pulp volatility, while Swiss specialty chains show lowest sensitivity given craft-positioning requirements.
Supply Chain Analysis
Workforce availability constraints in Nordic pulp mill regions and Stuttgart coating corridors tether capacity expansion to skilled technician pools rather than capital deployment alone. Supply concentrates in Sweden, Finland, and Germany for unbleached kraft substrate, with barrier coating specialization clustering in Baden-Württemberg and the Basel corridor. Raw material dependencies rest on Nordic softwood pulp, silicone-based grease barriers, and clay-coated substrates. Single-source vulnerability concentrates in integrated paperboard networks controlled by Mondi and Smurfit Kappa. Distribution runs through direct store delivery consolidation in Northern Italy and Bavaria, centralizing procurement decisions at regional wholesaler level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
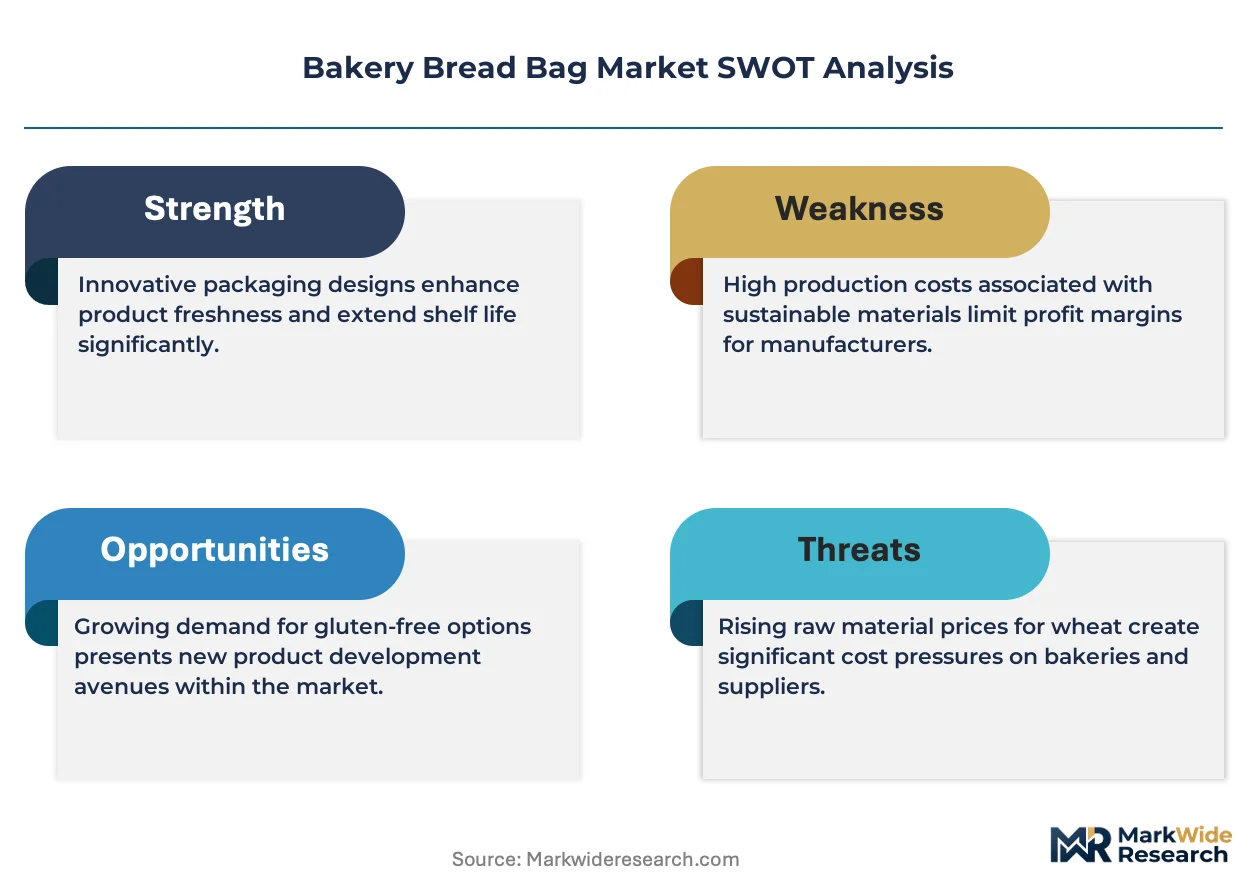
Geographic-arbitrage opportunities emerge between EU REACH-compliant coating investments in Germany and lower-regulation plastic conversion in US Midwest markets, where FDA migration limits permit cost structures unavailable under European fluorinated chemistry bans.
For Market Incumbents: Deploy water-based barrier coating capacity in Stuttgart and Basel corridors to capture margin pools from toll-dependent competitors. Backward integration into Nordic pulp supply secures substrate access against Smurfit Kappa and Mondi network concentration. ECHA scrutiny of PFAS chemistries threatens legacy grease-proofing formulations, accelerating reformulation timelines for crusty loaf packaging. For New Entrants and Emerging Players: Begin with digital printing agility for short-run seasonal designs in French artisan chains, where variable data inkjet collapses minimum order quantities. Belgian municipal composting infrastructure offers the most penetrable white-space for biodegradable bag claims with verified end-of-life pathways. Target Citeo and CONAI fee arbitrage through fiber-based format specialization. For Investors and Strategic Acquirers: Consolidation pressure builds where EFSA compliance timelines extend 18-24 months, stranding toll-coating dependent converters without in-house barrier formulation. Long-term viability favors integrated pulp-to-package operations with proprietary coating chemistry. Acquisition target archetype: mid-tier converters with digital printing assets and coating line retrofit potential. Signal to watch: municipal composting infrastructure rollouts in Flanders and Northern Italy as premium positioning enablers.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Scale-Up | Captures margin from fluorinated chemistry restrictions under EU F-Gas Regulation amendments. |
| Digital Printing Platform Investment | Enables short-run seasonal designs for Belgian and Swiss artisan bakery chains. |
| Nordic Pulp Supply Integration | Secures substrate access against corrugated network concentration by Mondi and Smurfit Kappa. |
| Heat-Seal Line Retrofit Program | Aligns with industrial bakery automation in Bavaria and Baden-Württemberg. |
| EFSA Compliance Certification | Unlocks pan-European brand procurement with 18-24 month barrier chemistry validation. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging procurement managers at German industrial bakeries, sustainability officers at French retail chains, coating R&D directors in Stuttgart and Basel, and route-based distributors in Northern Italy with secondary validation through EU customs data, EFSA substance approvals, Citeo fee schedules, and SEC filings from integrated paper producers. Bottom-up volume estimates from bagger line specifications and top-down category spend analysis triangulated market sizing.
Segment-weighting approaches applied differential growth assumptions across paper, plastic, biodegradable, and foil bag types, with closure method automation levels and end-user channel concentration as cross-cutting dimensions. CAGR derivation rested on production line investment cycles, regulatory phase-in timelines, and municipal composting infrastructure deployment patterns. Forecast inputs incorporated Nordic pulp mill capacity utilization, ECHA PFAS restriction trajectories, and direct store delivery consolidation velocity.
Several conditions sit outside the modeled scope, including unannounced EFSA substance bans, abrupt Nordic pulp mill closures, and breakthrough biopolymer cost parity events. Forecasts reflect stated regulatory trajectories and announced capacity investments. Material deviation in EU Green Deal packaging mandate enforcement or fluorinated chemistry restriction timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag in Drum Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
Textile Bags Market
Bags and Containers
Frosted Bag Market
Bags and Containers
Desiccant Bags Market
Bags and Containers
Octabin Market
Bags and Containers
Grip Seal Bags Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Flip-Up Vacuum Pack Market
Bags and Containers
Lawn and Leaf Bags Market