
 Foam Labels Market | 2026-2036
Foam Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Labels Market Foresight
Modular packaging configurations with detachable instruction panels and variable-data inserts is repositioning buyer expectations for foam label integration. UPM Raflatac leverages its European substrate network to dominate technical foam laminates for automotive underhood applications. CCL Industries anchors North American supply through specialized pressure-sensitive foam constructions for durable goods. Avery Dennison differentiates via silicone adhesive formulations that sustain performance across extreme thermal cycling in aerospace asset tagging.
Foam labels are pressure-sensitive constructions comprising a compressible cellular substrate bonded to a facestock and release liner, typically measuring 0.5–3.0 mm in caliper to conform to irregular surfaces while maintaining print legibility. Their primary purpose is to provide durable identification, cushioning, and insulation in environments where rigid labels would delaminate or transmit vibration. Polyurethane foam substrates command premium positioning due to superior chemical resistance and conformability in electronics and marine applications, while polyethylene variants compete on cost efficiency in high-volume consumer goods packaging. Acrylic-based adhesives represent the fastest-expanding adhesive category as manufacturers phase out solvent-heavy rubber formulations under VOC regulations.
REACH and RoHS frameworks in Europe restrict halogenated compounds and heavy metals in foam substrates and adhesives, forcing reformulation investments across the supply base. The EPA governs VOC emissions from adhesive coating operations in the United States, directly influencing domestic manufacturing location decisions and capital allocation. China's GB standards and MEE enforcement on industrial chemical labeling create parallel compliance obligations for exporters serving dual-source supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification costs.
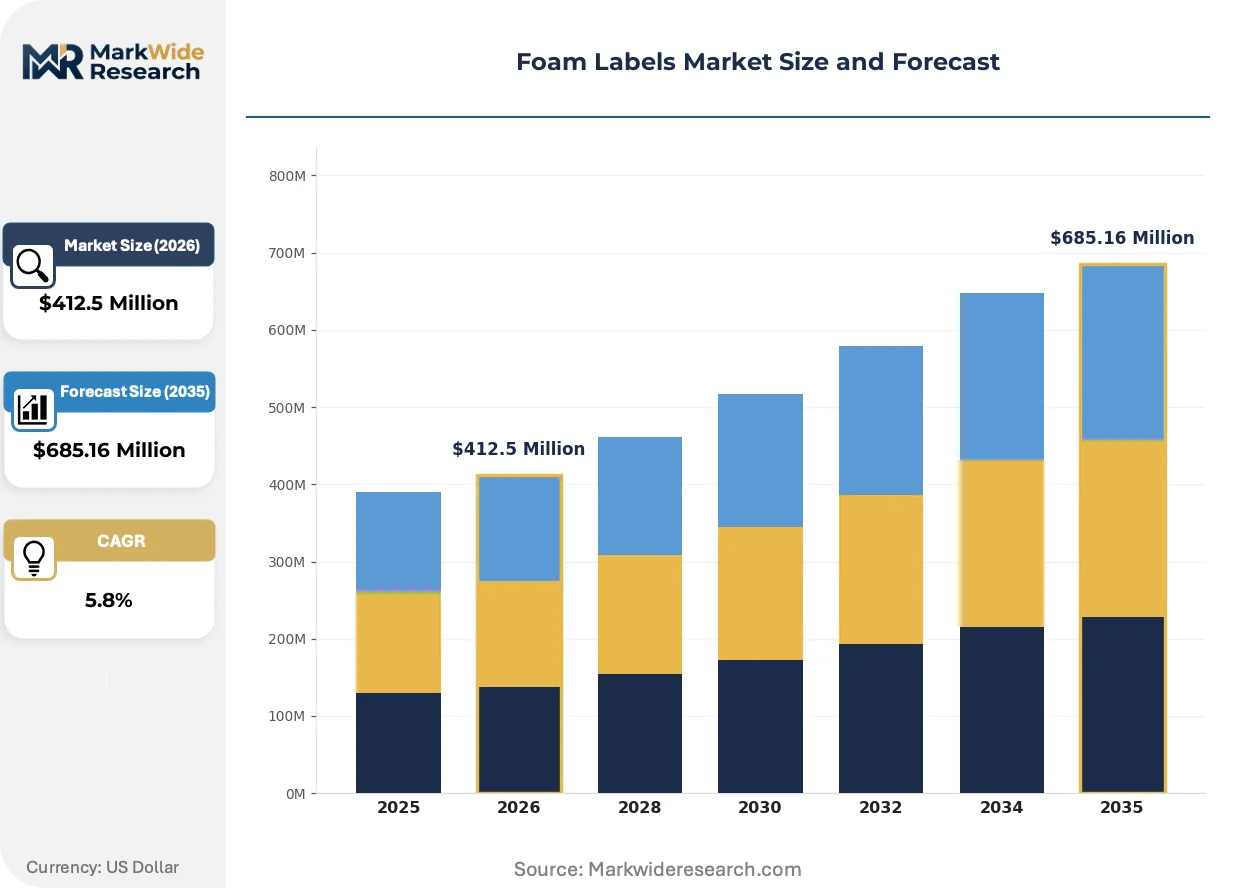
Market Dynamics
REACH compliance in Europe is forcing substrate reformulation across the foam label supply base, compressing margins for manufacturers dependent on halogenated foam chemistries while creating first-mover advantage for adhesive innovators with clean-label portfolios.
Growth Catalysts
- Cold-chain logistics expansion:Pharmaceutical distributors in Germany are scaling foam label procurement for temperature-sensitive shipment tracking, driving volume in the Stuttgart-Munich industrial corridor.
- RoHS substrate mandates:Electronics manufacturers face compulsory heavy-metal elimination in foam constructions, accelerating demand for polyurethane alternatives with embedded compliance documentation.
- Aerospace thermal cycling requirements:Asset tagging specifications now mandate silicone-adhesive foam labels rated for extreme temperature swings, pulling technical-grade capacity from automotive applications.
Market Restraints
- Petrochemical input volatility:Polyurethane foam substrates depend on isocyanate and polyol feedstocks whose price swings compress converter margins unpredictably.
- Adhesive supply concentration:Solvent-free acrylic adhesive production clusters in the US Gulf Coast and northwestern Europe, exposing buyers to regional disruption risk.
- Thin-film RFID substitution:Flexible electronics manufacturers are piloting chipless RFID tags for asset tracking, threatening foam label share in high-value logistics applications.
Strategic Opportunities
- India pharmaceutical cold-chain buildout:CDSCO serialization mandates for export drugs create first-mover openings for foam label converters with EU-validated adhesive systems.
- Marine electronics conformability:Salt-spray-resistant polyurethane foam constructions are penetrating yacht instrumentation panels as OEMs abandon rigid polycarbonate overlays.
- EU Green Deal procurement incentives:Public sector buyers now weight bio-based substrate content in label tenders, rewarding converters with certified renewable foam feedstocks.
Industry Challenges
- Adhesive formulation talent scarcity:Solvent-to-waterborne conversion expertise resides with a narrow cohort of polymer chemists nearing retirement, constraining reformulation velocity.
- Dual-certification timeline compression:Suppliers serving parallel EU REACH and China GB standard obligations face staggered testing protocols that delay product launches by 8-14 months.
- Legacy coating line retrofit costs:VOC-compliant adhesive application equipment demands capital outlays that mid-size converters cannot finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Labels Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane, Polyethylene, Polyvinyl Chloride, Silicone, Acrylic, Neoprene Application: Electronics, Consumer Goods, Packaging, Safety Identification, Aerospace, Marine End User: Manufacturers, Labeling Providers, Logistics, Repair Services, Equipment Assemblers, Retailers Adhesive Type: Rubber-Based, Acrylic-Based, Silicone-Based, Hot Melt, Water-Based, Heat Activated |
| Companies Covered | UPM Raflatac, CCL Industries Inc., Lintec Corporation, Hellermann Tyton Corporation, Avery Dennison Corporation, Multi-Color Corporation, WS Packaging Group, Labelcraft, MacDermid Enthone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Labels Market Shifts & Advancements
Modular packaging architectures are dissolving the boundary between protective foam and information-bearing surfaces, forcing label converters to engineer compressible substrates that integrate seamlessly with variable-data print workflows.
Laser-activated adhesive systems is modularizing how foam labels bond to irregular substrates in automotive underhood applications. Tier-1 suppliers in Germany are adopting these technologies to eliminate mechanical fasteners from engine-bay identification schemes. The shift compresses assembly time while enabling downstream disassembly for recycling compliance.
ECHA's 2023 restriction proposal on microplastics in single-use products is forcing foam substrate manufacturers to document polymer composition at the monomer level. Electronics OEMs in the Netherlands and Denmark are now rejecting uncharacterized foam constructions from Asian suppliers. The regulatory pressure is accelerating migration toward thermoplastic elastomer alternatives with full supply-chain traceability.
Consolidated buying desks at multinational logistics providers are compressing supplier rosters from twelve-vendor portfolios to three-preferred-partner structures. DHL Supply Chain and Kuehne+Nagel have both implemented unified foam label specifications across their European cold-chain networks. The procurement concentration rewards converters with pan-European coating capacity and REACH-registered adhesive formulations.
Foam Labels Market Segmentation
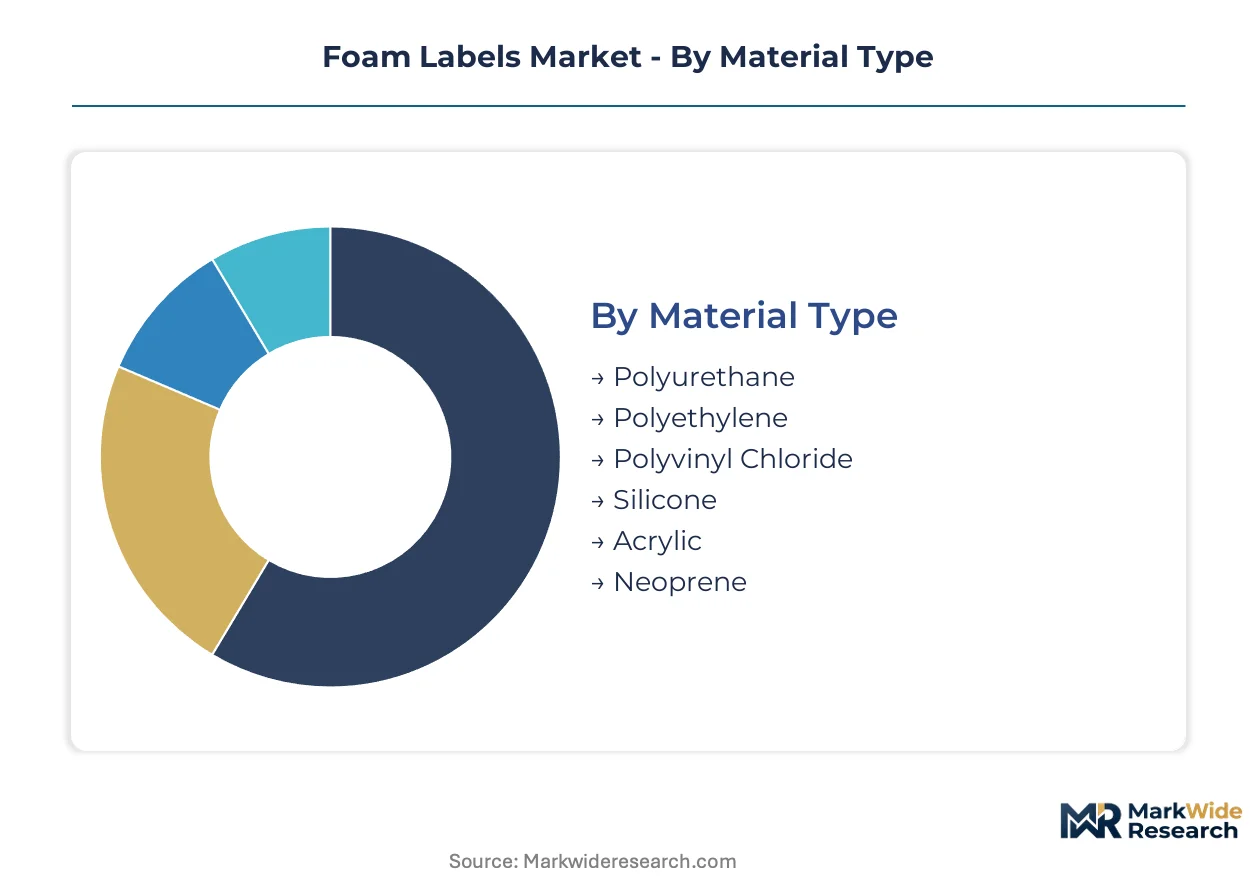
Foam label buyers select materials and adhesives based on surface conformity demands, chemical exposure profiles, and regulatory compliance burdens. Segmentation reveals where technical specifications override cost considerations versus where commodity economics dominate procurement decisions.
Material Type:
Cost tolerance and performance thresholds split buyers into premium-specification and efficiency-driven camps.
- Polyurethane:Closed-cell structures deliver superior chemical resistance and compression set recovery for electronics underhood applications. Demand clusters in Germany's automotive labeling corridor around Stuttgart, where REACH-registered formulations command preference over uncharacterized imports.
- Polyethylene:Lower-density open-cell constructions compete on unit economics in high-volume consumer goods packaging. Retailers and contract packagers in cost-sensitive segments specify polyethylene for short-lifecycle products where label durability requirements remain modest.
- Polyvinyl Chloride:Halogenated chemistry faces accelerating substitution pressure under ECHA microplastic scrutiny.
- Silicone:Extreme temperature stability serves aerospace asset tagging with thermal cycling mandates.
- Acrylic:Thermoplastic elastomer alternatives gain traction where supply-chain traceability documentation is mandatory.
- Neoprene:Oil-resistant formulations retain niche positioning in marine electronics despite higher substrate costs.
Volume sits with Polyethylene; growth tilts toward Polyurethane.
Application:
Environmental exposure severity determines whether buyers specify technical-grade foam or accept standard constructions.
- Electronics:RoHS substrate mandates and miniaturization trends favor ultra-thin polyurethane laminates with embedded compliance documentation. OEMs in the Netherlands and Denmark now reject foam constructions lacking monomer-level polymer characterization.
- Aerospace:Asset tagging specifications mandate silicone-adhesive foam labels rated for extreme thermal swings, pulling technical-grade capacity from automotive applications.
- Consumer Goods:Modular packaging with detachable instruction panels drives demand for variable-data-compatible foam substrates.
- Packaging:Cold-chain pharmaceutical distributors scale procurement for temperature-sensitive shipment tracking.
- Safety Identification:Industrial facilities specify retroreflective foam constructions for low-visibility hazard marking.
- Marine:Salt-spray-resistant polyurethane penetrates yacht instrumentation panels as rigid polycarbonate overlays lose favor.
Electronics captures current volume; Aerospace shows the steepest expansion trajectory.
End User:
Technical specification authority and procurement consolidation reshape supplier relationships across buyer categories.
- Logistics:DHL Supply Chain and Kuehne+Nagel have compressed vendor rosters to three-preferred-partner structures with unified foam label specifications across European cold-chain networks.
- Manufacturers:Automotive and electronics OEMs retain direct adhesive formulation approval rights, constraining converter flexibility.
- Labeling Providers:Mid-size converters face stranded capital in legacy coating lines without strategic partnerships for VOC-compliant equipment.
- Repair Services:Fragmented demand pools limit volume leverage but reward regional stocking flexibility.
- Equipment Assemblers:Tier-1 automotive suppliers adopt laser-activated adhesive systems to eliminate mechanical fasteners from engine-bay identification.
- Retailers:Private-label packaging teams prioritize unit cost over technical performance in seasonal product applications.
Logistics concentrates procurement volume; Manufacturers drive specification innovation fastest.
Adhesive Type:
Regulatory phase-outs of solvent-heavy formulations accelerate migration toward clean-label chemistries.
- Acrylic-Based:Waterborne and solvent-free variants represent the fastest-expanding category as manufacturers exit rubber formulations under EPA VOC regulations and REACH restrictions. Production clusters in the US Gulf Coast and northwestern Europe expose buyers to regional disruption risk.
- Silicone-Based:Thermal stability across extreme temperature ranges commands aerospace and underhood automotive premiums.
- Rubber-Based:Solvent-heavy legacy formulations face compulsory phase-out timelines.
- Hot Melt:Block copolymer systems serve high-speed converting lines in consumer goods packaging.
- Water-Based:Emulsion acrylics compete on environmental profile where curing infrastructure exists.
- Heat Activated:Specialty applications in textile and membrane bonding remain volume-constrained.
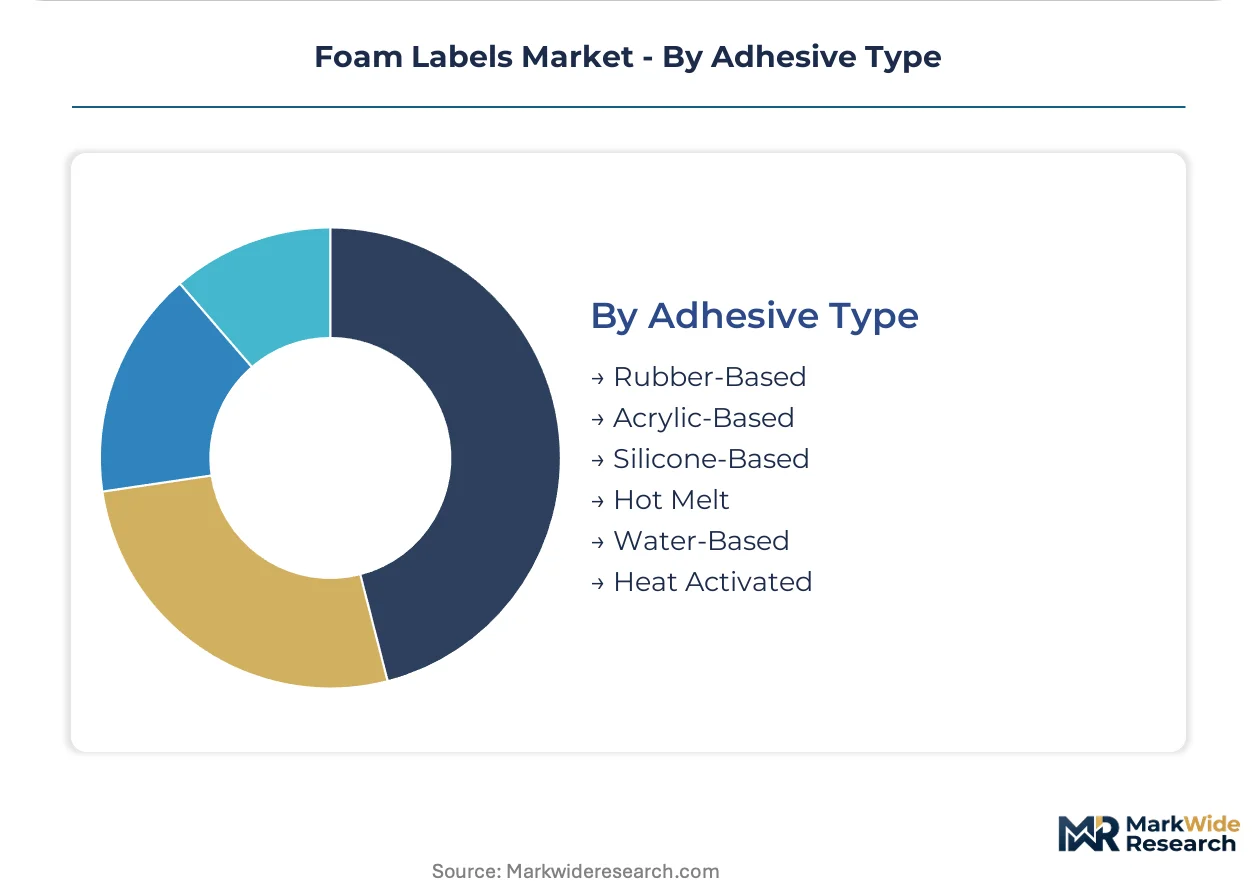
Silicone-Based anchors premium positioning; Acrylic-Based gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in northwestern Europe and the US Gulf Coast while consumption concentrates in Germany's automotive corridor and North American logistics hubs. This geographic split creates freight-cost arbitrage opportunities for converters with dual-hemisphere coating assets.
Germany
Automotive underhood labeling and pharmaceutical cold-chain tracking drive polyurethane foam demand in the Stuttgart-Munich industrial corridor. REACH-registered adhesive formulations command preference over uncharacterized imports under ECHA disclosure mandates. Tier-1 suppliers around Stuttgart adopt laser-activated bonding systems to eliminate mechanical fasteners from engine-bay identification schemes.
United States
EPA VOC regulations govern adhesive coating operations, pushing solvent-to-waterborne conversion investments in the Gulf Coast production cluster. Aerospace asset tagging specifications pull silicone-adhesive foam capacity from automotive applications. DHL Supply Chain and Kuehne+Nagel have compressed vendor rosters to three-preferred-partner structures with unified specifications across their cold-chain networks.
China
GB standards and MEE enforcement on industrial chemical labeling create parallel compliance obligations for exporters serving dual-source supply chains. Electronics OEMs in the Yangtze River Delta demand monomer-level polymer characterization documentation. Domestic converters face stranded inventory risk from regulatory divergence with EU REACH timelines.
India
CDSCO serialization mandates for export drugs create first-mover openings for foam label converters with EU-validated adhesive systems. Cold-chain infrastructure buildout for pharmaceutical distribution scales procurement in Maharashtra and Gujarat. Mid-size converters struggle with dual-certification timeline compression between EU and Indian regulatory protocols.
Netherlands
ECHA's microplastics restriction proposal forces foam substrate manufacturers to document polymer composition at the monomer level. Electronics OEMs in Eindhoven and Amsterdam now reject uncharacterized foam constructions from Asian suppliers. The regulatory pressure accelerates migration toward thermoplastic elastomer alternatives with full supply-chain traceability.
Foam Labels Market Competitive Landscape
The competitive structure tilts toward substrate specialists with REACH-registered adhesive portfolios. Tier-1 automotive and aerospace OEMs retain direct formulation approval rights, constraining converter flexibility and compressing margins for undifferentiated players. Two strategic archetypes dominate: pan-European coating networks with regulatory compliance depth, and North American pressure-sensitive construction specialists with durable goods expertise. Competitive moves concentrate on strategic partnerships for VOC-compliant equipment access and geographic expansion into Indian pharmaceutical cold-chain infrastructure.
Within the European substrate specialist tier, UPM Raflatac and Lintec Corporation occupy positions anchored by technical foam laminate capabilities for automotive underhood applications. Among North American pressure-sensitive construction specialists, Avery Dennison Corporation exemplifies the premium-tier vector through silicone adhesive formulations rated for extreme thermal cycling. CCL Industries Inc. sits within the durable goods anchoring archetype, supplying specialized foam constructions for industrial labeling requirements. These three companies represent the concentration of technical-grade capacity that tier-1 OEMs and consolidated logistics providers specify in unified procurement frameworks.
| Leading Market Players |
|---|
| UPM Raflatac |
| CCL Industries Inc. |
| Lintec Corporation |
| Hellermann Tyton Corporation |
| Avery Dennison Corporation |
| Multi-Color Corporation |
| WS Packaging Group |
| Labelcraft |
| MacDermid Enthone |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across Germany's Stuttgart-Munich corridor exercise pricing discipline through captive coating capacity and REACH-registered adhesive portfolios, insulating technical-grade foam laminates from commodity volatility while extracting premiums from automotive OEMs with formulation approval rights.
Pricing Analysis
Margin tightening in standard-grade polyethylene foam traces to petrochemical feedstock volatility and converter overcapacity in high-volume consumer packaging. Three-tier pricing structure across REACH-certified premium, ISO-compliant standard, and unvalidated economy levels separates buyers by documentation burden. Cost-down pressure on mid-tier constructions accelerates because logistics providers consolidated vendor rosters to three-preferred-partner structures. Retail packaging teams show highest price sensitivity; aerospace asset taggers accept silicone-adhesive premiums without negotiation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from DHL Supply Chain and Kuehne+Nagel with unified specifications, while regional distributors serve fragmented repair-service demand. Production clusters in Germany, the United States Gulf Coast, and northwestern Europe draw from isocyanate, polyol, and acrylic resin feedstocks. Single-source vulnerability concentrates in solvent-free adhesive production anchored in the US Gulf Coast and northwestern Europe. Distribution runs through pan-European coating networks with regulatory compliance depth and North American pressure-sensitive construction specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters are racing to secure backward integration into REACH-registered adhesive formulations and VOC-compliant coating equipment, recognizing that formulation approval rights determine supplier survival as tier-1 OEMs consolidate procurement.
For Market Incumbents: Deepen vertical integration into silicone adhesive production to defend aerospace and automotive underhood share against thin-film RFID substitution threats. Secure pan-European coating capacity with laser-activated bonding systems before mid-size converters form strategic partnerships for VOC-compliant equipment access. For New Entrants and Emerging Players: E-commerce-enabled direct procurement channels offer white-space entry into India's pharmaceutical cold-chain buildout where CDSCO serialization mandates outpace local converter capacity. Target Maharashtra and Gujarat distribution hubs with EU-validated adhesive systems and monomer-level polymer documentation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size German converters with stranded capital in legacy coating lines but intact REACH registration portfolios. Watch adhesive formulation talent scarcity as the inflection signal: retirement-driven expertise gaps will force acquisition premiums for solvent-to-waterborne conversion capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Registered Adhesive Portfolio Expansion | Secures formulation approval rights with Stuttgart automotive OEMs and Eindhoven electronics manufacturers. |
| VOC-Compliant Coating Line Retrofit | Enables EPA compliance for Gulf Coast production and unlocks DHL Supply Chain preferred-partner status. |
| Pan-European Distribution Network Buildout | Matches Kuehne+Nagel unified specifications with regional stocking flexibility for cold-chain pharmaceuticals. |
| Laser-Activated Bonding System Adoption | Eliminates mechanical fasteners for Tier-1 automotive suppliers seeking recycling compliance in engine-bay applications. |
| Monomer-Level Polymer Traceability Program | Satisfies ECHA microplastics scrutiny and Eindhoven OEM rejection of uncharacterized Asian foam constructions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with adhesive formulation chemists, automotive procurement leads at Tier-1 suppliers, cold-chain logistics operators, foam substrate plant managers, and REACH compliance officers. ECHA restriction proposals, EPA VOC emission databases, CDSCO serialization guidelines, and converter SEC disclosures provided triangulation points. Bottom-up volume builds across material grades and adhesive categories were cross-checked against top-down market sizing.
Granularity extended to polyurethane versus polyethylene substrate splits, acrylic versus silicone adhesive migration rates, and application-level modeling across electronics, aerospace, and pharmaceutical cold-chain segments. CAGRs were derived from segment-level growth differentials and input cost trajectory assumptions. Isocyanate and polyol feedstock volatility indices, REACH registration timelines, and logistics provider procurement consolidation patterns informed projection elasticity.
The model holds under stable regulatory enforcement intensity; deviation in ECHA microplastics restriction implementation or EPA VOC rule acceleration would shift capacity allocation and pricing power distribution. Forecasts reflect documented assumptions on adhesive formulation phase-out timelines and cold-chain infrastructure buildout rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Laser Printable Wristbands Market
Labels
Direct Thermal Linerless Labels Market
Labels
Global Industrial Labels Market
Labels
Booklet Labels Market
Labels
Global QR Code Labels Market
Labels
Self-Laminating Labels Market
Labels
Inspection and Inventory Labels Market
Labels
Domed Labels Market
Labels
Global Waterproof Labels Market
Labels
Global Cryogenic Label Market
Labels
Retro-Reflective Labels Market
Labels
Die Cut Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Metallic Labels Market
Labels
Foil Labels Market
Labels
Global Resealable Packaging Labels Market