
 Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market | 2026-2036
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market Size, Share, and Industry Trends Forecast 2026-2036
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market Outlook
Polypropylene is shifting away from high-barrier snack packaging as BOPET gains ground through superior oxygen barrier and printability. Toray Industries leverages its integrated resin-to-film operations across Japan and Southeast Asia to sustain cost discipline. Mitsubishi Polyester Film GmbH anchors European supply for pharmaceutical blister applications through precision coating capabilities. Jindal Poly Films dominates South Asian volume with backward integration into PET resin production.
Biaxially Oriented Polyethylene Terephthalate Films are polyester sheets stretched in both machine and transverse directions to achieve tensile strength above 200 MPa, dimensional stability, and optical clarity for industrial conversion. The biaxial orientation process involves sequential or simultaneous stretching at temperatures between the glass transition and melting points, followed by heat setting to lock molecular alignment. Transparent films occupy the largest volume share across flexible packaging substrates where optical clarity and sealability command premium positioning. Metallized films represent the fastest-expanding product category as vacuum-deposited aluminum layers replace foil laminates in barrier-sensitive snack and pharmaceutical applications. The 12-25 micron thickness band captures dominant share in label and imaging segments where die-cutting precision and thermal stability determine converter selection.
The FDA regulates direct food-contact BOPET under 21 CFR 177.1630 with migration limits on oligomers and additives, while the EU REACH framework governs substance authorization across imported film chemistries. ECHA's restriction proposals on perfluorinated compounds are forcing reformulation of coated barrier variants ahead of sunset dates. India's BIS certification mandate for food-grade plastics under IS 9845 creates compliance gates for imported film rolls. Stakeholders must monitor regulatory divergence between California's SB 54 extended producer responsibility rules and emerging EU packaging reuse targets that could redefine single-film versus multi-layer specifications.
Market Dynamics
Mono-material packaging mandates across the EU are forcing converters to abandon multi-layer laminates in favor of recyclable BOPET structures, compressing the addressable market for legacy barrier films and rewiring procurement specifications toward single-substrate solutions.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are accelerating brand transitions from foil laminates to metallized BOPET in snack and pharmaceutical formats.
- Flexible food packaging demand:India's western industrial corridor is absorbing volume as converters cluster near polymer supply nodes to minimize logistics friction.
- 12-25 micron thickness optimization:Die-cutting precision requirements in label and imaging segments are pulling specification upgrades from commodity films.
Market Restraints
- Ethylene glycol feedstock volatility:Crude-linked PET resin pricing transmits cost instability directly to film converters with limited pass-through power.
- Perfluorinated compound restrictions:ECHA's sunset proposals for PFAS coatings are forcing reformulation of high-barrier variants ahead of compliance deadlines.
- Biaxial orientation capex intensity:Simultaneous stretching lines require capital deployment that fragments competitive capacity among resin-integrated players.
Strategic Opportunities
- Pharmaceutical blister expansion:Precision coating capabilities for thermoformable BOPET are capturing share from PVC-PVDC laminates in European drug packaging.
- India BIS certification gates:IS 9845 mandates for food-grade plastics are creating compliance barriers that favor domestic resin-integrated film producers.
- Vacuum metallization convergence:Aluminum deposition technology paired with oxygen barrier coatings is opening snack applications previously reserved for foil structures.
Industry Challenges
- Biaxial process engineering talent:Simultaneous stretching line operation requires specialized technicians scarce outside Japan and Germany.
- Migration testing timelines:FDA 21 CFR 177.1630 oligomer limits demand extended validation cycles that delay new product commercialization.
- Legacy laminate line stranding:Converters face asset write-downs as mono-material specifications obsolete solvent-based adhesive coating equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market |
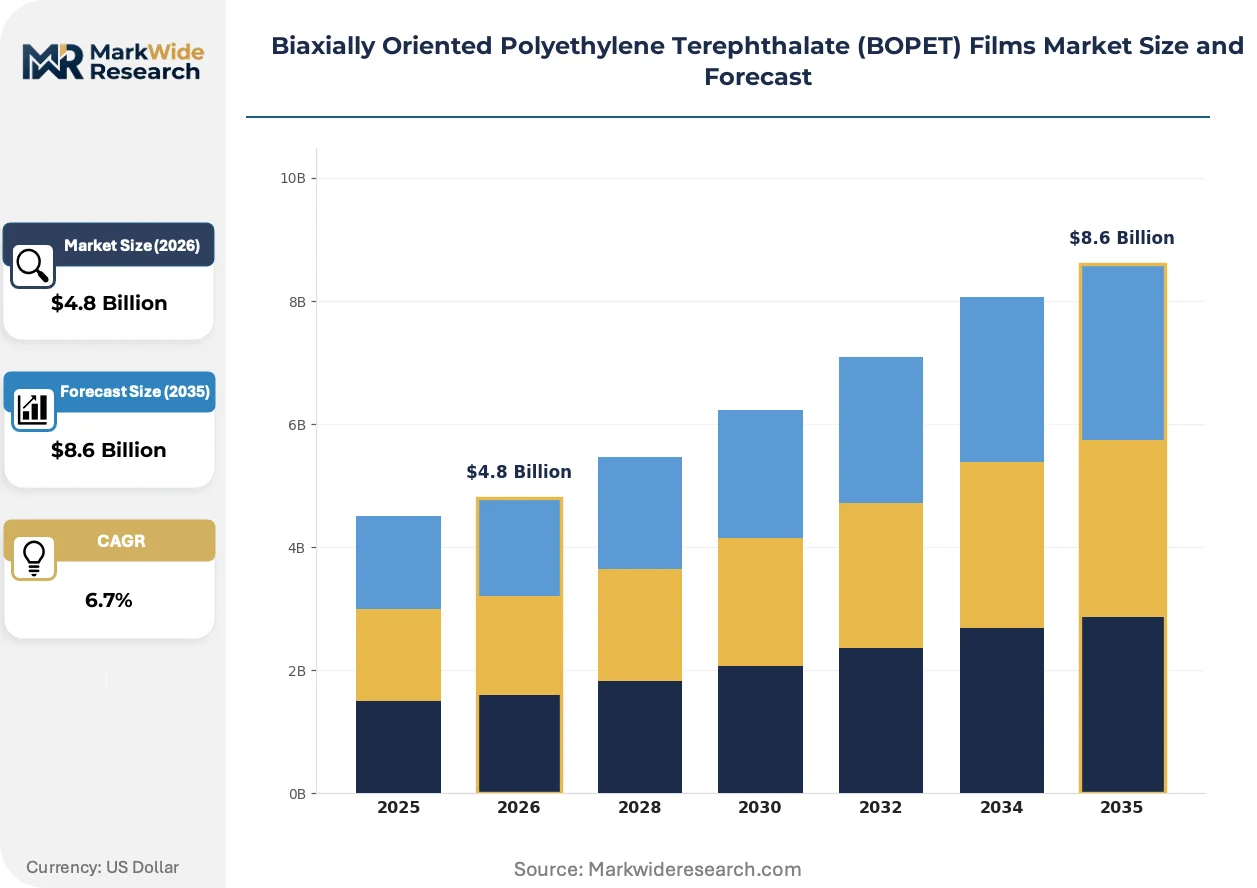
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Metallized Films, Colored Films, Coated Films Application: Packaging, Electronics, Labels, Imaging End Use Industry: Food & Beverage, Consumer Goods, Pharmaceutical, Industrial Thickness: Less than 12 Micron, 12-25 Micron, 26-50 Micron, More than 50 Micron |
| Companies Covered | Toray Industries, Inc., Mitsubishi Polyester Film GmbH, Jindal Poly Films Ltd., Dhunseri Poly Films, Terphane, Uflex Ltd., SRF Limited, Cosmo Films Limited, Polyplex Corporation Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market Strategic Shifts
Active materials innovation and regulatory chemistry bans are compressing the viable formulation space for barrier films while opening substitution pathways for coated and metallized BOPET variants.
Plasma-enhanced chemical vapor deposition barrier coatings are consolidating technical oxygen transmission performance previously delivered by multi-layer foil laminates. Pharmaceutical blister pack converters in Germany and Switzerland are adopting these coatings at accelerated qualification cycles. The technology is consolidating high-barrier applications into single-substrate formats that satisfy EU recyclability mandates without performance trade-offs.
REACH substance authorization frameworks are restricting perfluorinated chemistry across imported film formulations. Industrial consequences include forced reformulation of legacy coated barrier products and accelerated R&D spending on silicon oxide alternatives. Coated BOPET variants for sensitive food applications face the most acute compliance pressure as ECHA sunset dates approach.
Brand procurement specifications are rotating toward mono-material structures that simplify post-consumer sorting and mechanical recycling. European flexible packaging buyers are rewriting supplier qualification criteria to exclude non-recyclable laminates regardless of unit cost. This behavioral pivot is most visible in German and French snack and ready-meal segments where extended producer responsibility fees now penalize multi-layer complexity.
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market Segmentation
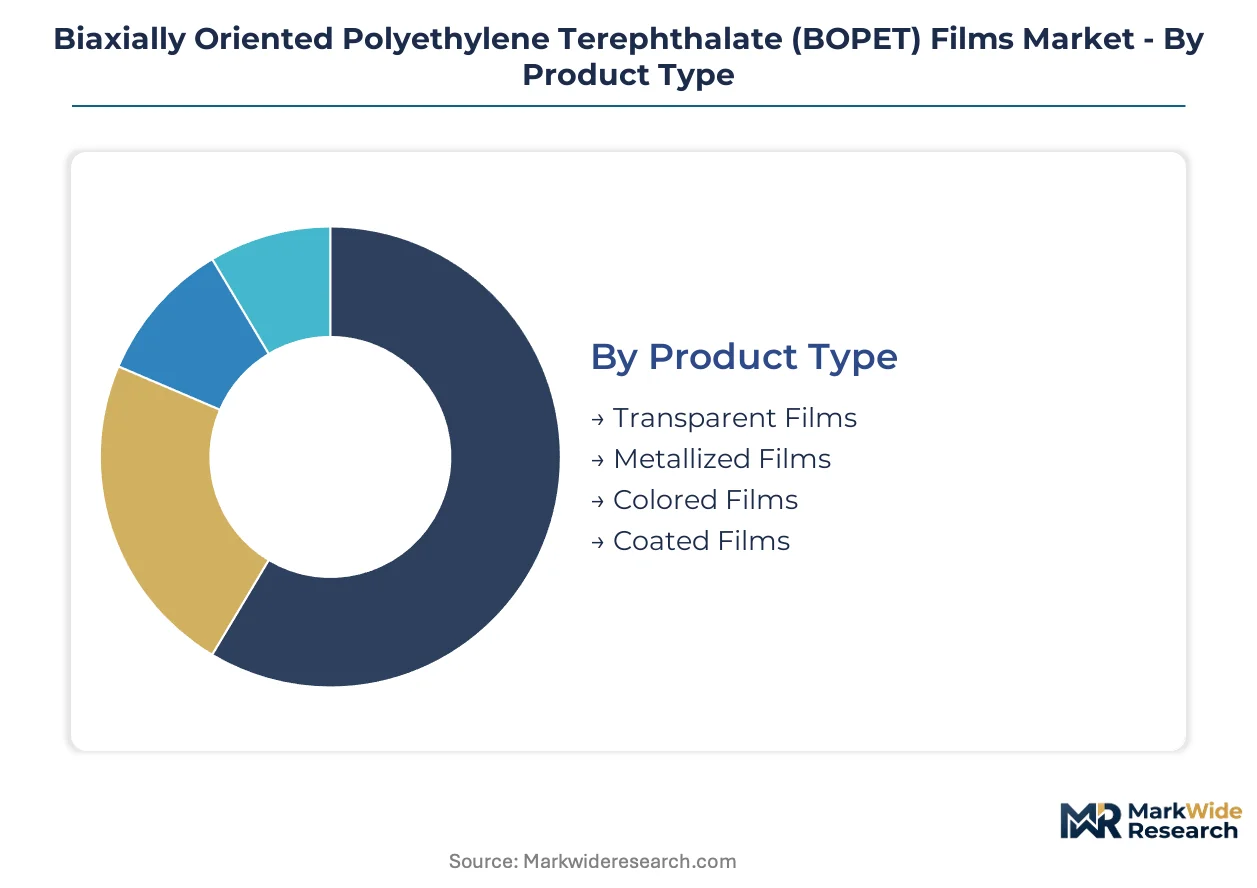
Segmentation in BOPET films reflects divergent technical specifications across optical clarity, barrier performance, and mechanical durability requirements. Converter procurement patterns split sharply between commodity transparent substrates and engineered variants demanding precision coating or metallization capabilities.
Product Type:
Customization intensity spans from commodity transparent grades to engineered barrier variants requiring vacuum deposition or solvent coating lines.
- Transparent Films:Standard polyester substrates deliver optical clarity above 90% light transmission and tensile strength exceeding 200 MPa for general-purpose flexible packaging. Demand concentrates in Asian snack and bakery segments where brand owners prioritize shelf visibility and heat-seal compatibility over barrier performance.
- Metallized Films:Vacuum-deposited aluminum layers achieve oxygen transmission rates below 0.5 cc/m²/day, displacing foil laminates in moisture-sensitive pharmaceutical and confectionery applications. European converters are adopting these at accelerated qualification cycles under EU Packaging and Packaging Waste Regulation recyclability mandates.
- Colored Films:Pigmented masterbatch integration during extrusion eliminates secondary printing steps for beverage labels and decorative consumer goods packaging.
- Coated Films:Silicon oxide and acrylic barrier layers address ECHA perfluorinated compound restrictions while maintaining thermoformability for medical blister packs.
Most installed capacity flows through Transparent Films. Expansion is steepest in Metallized Films.
Application:
Volume distribution correlates with barrier sensitivity and regulatory stringency across end-use specifications.
- Packaging:Flexible food and pharmaceutical formats absorb the dominant share of metallized and coated variants, driven by mono-material mandates replacing multi-layer laminates. India's western industrial corridor converters are clustering specification upgrades here to serve domestic processed food brands.
- Electronics:Thin-gauge films serve as dielectric substrates for capacitors and flexible printed circuit boards where dimensional stability under thermal cycling is critical. Japanese and South Korean component manufacturers anchor demand through precision thickness tolerances.
- Labels:Pressure-sensitive adhesive face stocks and shrink sleeve applications favor 12-25 micron grades with optimized die-cutting response and print receptivity.
- Imaging:Photographic and thermal transfer ribbons require ultra-low haze specifications and static control coatings for consistent toner adhesion.
Packaging commands the largest volume position. Electronics is gaining share fastest through 5G component miniaturization.
End Use Industry:
Regulatory exposure and performance premiums create divergent margin profiles across customer categories.
- Food & Beverage:Snack, ready-meal, and beverage applications prioritize oxygen barrier and seal integrity under FDA 21 CFR 177.1630 and BIS IS 9845 food-contact compliance. German and French buyers are rewriting supplier qualification criteria to exclude non-recyclable laminates regardless of unit cost.
- Pharmaceutical:Blister packs and sachet formats demand migration-tested substrates with documented oligomer compliance for FDA and EMA drug master file submissions. Swiss and German converters are adopting plasma-enhanced chemical vapor deposition coatings at accelerated cycles.
- Consumer Goods:Cosmetics and personal care labels favor metallized and holographic finishes for shelf differentiation.
- Industrial:Release liners, insulation facing, and composite reinforcement applications tolerate wider specification bands at lower unit margins.
Food & Beverage absorbs the majority of metallized film output. Pharmaceutical specifications are climbing fastest through barrier coating adoption.
Thickness:
Process equipment constraints and end-use mechanical requirements stratify capacity deployment across gauge bands.
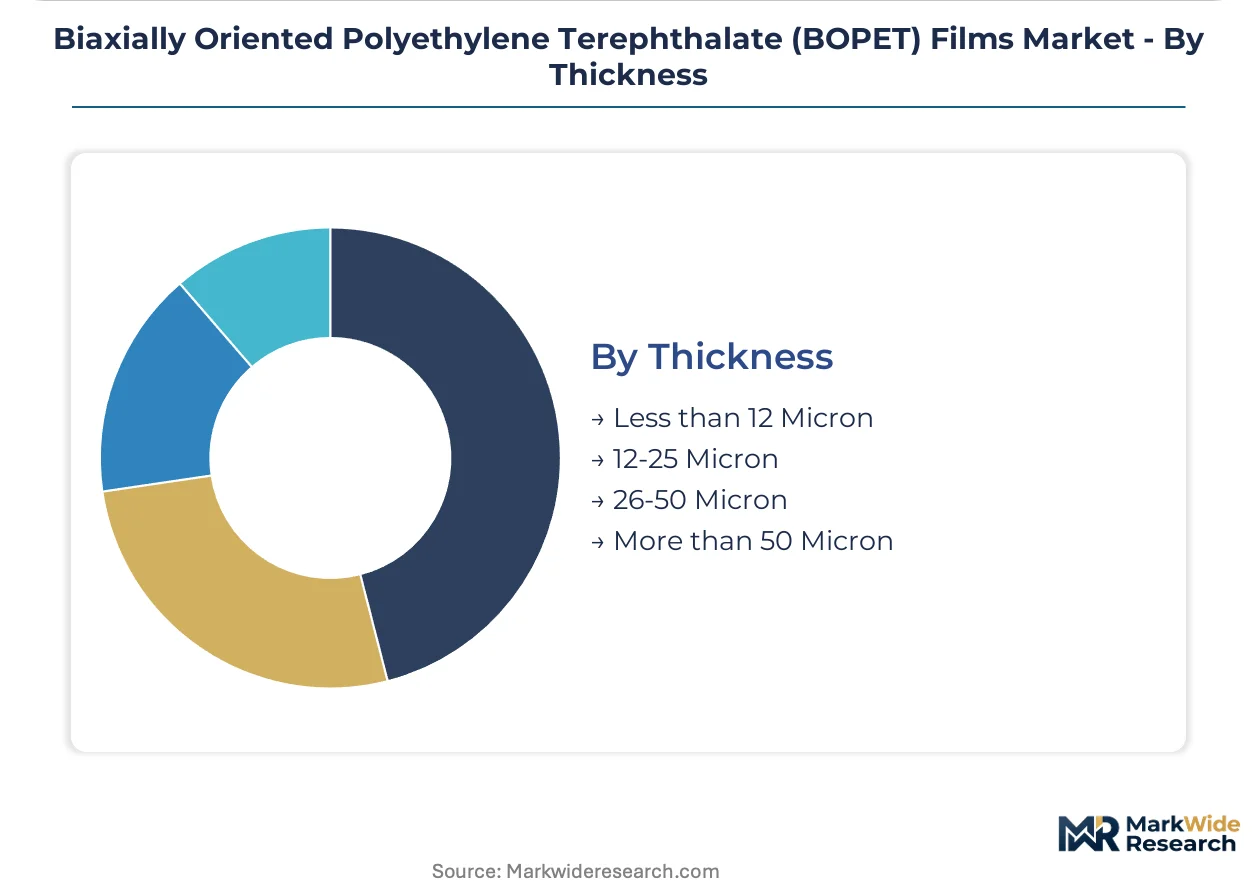
- Less than 12 Micron:Ultra-thin capacitor and battery separator films demand specialized simultaneous stretching lines with tension control precision scarce outside Japanese and German engineering centers.
- 12-25 Micron:The workhorse specification band for label, imaging, and lightweight packaging applications where die-cutting precision and thermal stability determine converter selection. This band captures dominant positioning across flexible packaging substrates where optical clarity and sealability command premium positioning.
- 26-50 Micron:Thermoformable pharmaceutical blister and industrial lamination grades requiring deeper draw ratios and puncture resistance.
- More than 50 Micron:Heavy-duty industrial tapes, roofing membranes, and specialty electrical insulation serving niche volume positions.
12-25 Micron thickness dominates installed capacity. Less than 12 Micron is expanding most quickly through electronics miniaturization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's western industrial corridor anchors the strongest demand concentration for BOPET films, with converters clustering near polymer supply nodes to minimize logistics friction and capture specification upgrades from domestic processed food brands.
India
Flexible food packaging specifications are absorbing metallized film volumes as brands replace multi-layer laminates with mono-material structures. BIS certification mandates under IS 9845 for food-grade plastics create compliance gates that favor domestic resin-integrated producers. The western industrial corridor spanning Gujarat and Maharashtra hosts the densest converter clustering near captive PET resin supply.
Germany
Pharmaceutical blister pack converters are adopting plasma-enhanced chemical vapor deposition barrier coatings at accelerated qualification cycles. REACH substance authorization frameworks are restricting perfluorinated chemistry across imported formulations, forcing reformulation of legacy coated products. The Baden-Württemberg and North Rhine-Westphalia regions concentrate precision coating capabilities for thermoformable drug packaging applications.
United States
Snack and ready-meal brand procurement specifications are rotating toward mono-material structures that simplify post-consumer sorting. FDA regulations under 21 CFR 177.1630 govern direct food-contact applications with migration limits on oligomers and additives. California's SB 54 extended producer responsibility rules are penalizing multi-layer complexity in flexible packaging formats.
Japan
Electronics applications for thin-gauge capacitor and battery separator films are demanding specialized simultaneous stretching lines with tension control precision. METI industrial standards guide substrate specifications for dielectric applications in 5G component miniaturization. The Kanto region around Tokyo and the Chubu region near Nagoya anchor precision film engineering centers.
Switzerland
Pharmaceutical packaging converters are qualifying coated BOPET variants for thermoformable blister applications previously served by PVC-PVDC laminates. Swissmedic drug master file submission requirements demand migration-tested substrates with documented oligomer compliance. The Basel region and Zurich industrial corridor concentrate barrier coating adoption for high-value drug delivery formats.
Biaxially Oriented Polyethylene Terephthalate (BOPET) Films Market Competitive Environment
Backward integration into PET resin production dominates the current landscape as cost discipline and supply security separate viable competitors from margin-pressured converters. The vendor base stratifies across resin-integrated majors, precision coating specialists, and regional volume players serving commodity transparent grades. Three archetypes define positioning: integrated resin-to-film operators controlling feedstock costs, barrier technology specialists commanding pharmaceutical premiums, and scale-driven converters capturing Asian snack packaging volume. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players align with EU recyclability mandates and Indian domestic content requirements.
Among Asia-Pacific resin-integrated operators, Toray Industries, Inc. and Jindal Poly Films Ltd. exemplify the backward integration archetype that sustains cost discipline across Japan and South Asian supply corridors. Mitsubishi Polyester Film GmbH occupies a position within the European precision coating tier, anchoring barrier technology capabilities for pharmaceutical applications. These three companies represent the structural segmentation between feedstock-controlled volume players and specification-driven specialists serving regulated end-uses.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Mitsubishi Polyester Film GmbH |
| Jindal Poly Films Ltd. |
| Dhunseri Poly Films |
| Terphane |
| Uflex Ltd. |
| SRF Limited |
| Cosmo Films Limited |
| Polyplex Corporation Ltd. |
| Others |
Value Chain & Pricing Dynamics
Simultaneous stretching line technicians concentrated in Japan and Germany create labor-cost differentials that widen pricing spreads between precision barrier films and commodity transparent grades. This workforce scarcity allows resin-integrated operators in Asia to undercut European coating specialists on standard specifications while commanding premiums for thin-gauge electronics substrates.
Pricing Analysis
Ethylene glycol pass-through from crude-linked PET resin pricing dominates BOPET film cost structures, with converters absorbing volatility through contract-based long-term offtake agreements. Pricing stratifies across premium, standard, and economy tiers based on barrier certification grade and volume scale, with pharmaceutical-grade coated variants commanding the widest spreads. Cost compression in transparent snack packaging intensifies as Indian resin-integrated producers expand capacity. Brand procurement officers in European flexible packaging show least price sensitivity for mono-material metallized formats meeting EU Packaging and Packaging Waste Regulation recyclability mandates.
Supply Chain Analysis
Biaxial orientation equipment operators with specialized tension-control expertise cluster in Japan, Germany, and South Korea, constraining global capacity expansion for sub-12 micron electronics grades. Raw material flows draw from purified terephthalic acid and ethylene glycol feedstocks anchored in Middle Eastern and Asian petrochemical complexes. Single-source vulnerability runs through simultaneous stretching line engineering centers in Nagoya and Stuttgart. Distribution runs through converter clusters in India's western industrial corridor and Germany's Baden-Württemberg precision coating corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation functions as a regulatory compounder, accelerating brand transitions from multi-layer laminates toward recyclable mono-material structures and reshaping procurement specifications across European flexible packaging.
For Market Incumbents: Deploy backward integration into PET resin production to defend margin position against ethylene glycol volatility and capture specification upgrades in India's western industrial corridor. Incumbents must accelerate plasma-enhanced chemical vapor deposition coating qualification cycles to offset threat from Swiss and German pharmaceutical blister converters adopting silicon oxide alternatives ahead of ECHA perfluorinated compound sunset dates. For New Entrants and Emerging Players: Digital direct-to-converter platforms offer the lowest-friction route to bypass established distributor relationships in Asian snack packaging segments. New entrants should target India's domestic processed food brands with BIS IS 9845-certified transparent grades, exploiting compliance gates that disadvantage imported film rolls. A technical service-led go-to-market angle emphasizing die-cutting precision support for 12-25 micron label applications accelerates converter qualification timelines. For Investors and Strategic Acquirers: Resin-integrated Asian film producers are the most active acquirer in this space, seeking European coating technology to complete mono-material barrier portfolios. Long-term viability hinges on exposure to pharmaceutical specifications climbing fastest through barrier coating adoption. Investors should monitor ECHA perfluorinated compound restriction implementation as the critical inflection signal for coated film reformulation spending and silicon oxide substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Captive ethylene glycol supply insulates Toray and Jindal from crude-linked volatility in Asian markets. |
| Plasma-Enhanced CVD Coating Adoption | Swissmedic-compliant barrier layers displace PVC-PVDC laminates in German pharmaceutical blister packs. |
| Simultaneous Stretching Line Expansion | Sub-12 micron capacity addition in Japan serves METI-guided 5G capacitor substrate specifications. |
| BIS IS 9845 Certification Investment | Domestic Indian compliance gates favor Gujarat-Maharashtra resin-integrated producers over imports. |
| Vacuum Metallization Technology Upgrade | Aluminum deposition paired with oxygen barrier coatings opens snack applications previously reserved for foil. |
Study Parameters
Direct dialogue with biaxial orientation line engineers, pharmaceutical packaging converters, flexible food brand procurement officers, and PET resin procurement leads grounded qualitative findings in operational reality. Secondary validation drew from FDA 21 CFR 177.1630 filings, ECHA REACH substance authorization databases, BIS IS 9845 certification records, and customs trade data on film roll imports. Bottom-up capacity estimates from identified production facilities were triangulated against top-down demand projections from end-use consumption patterns.
Segmented outputs across product type, application, end-use industry, and thickness gauge were generated through the projection horizon, with CAGRs derived from elasticity modeling of ethylene glycol price sensitivity and regulatory compliance cost absorption. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation implementation timelines, Indian BIS certification gate expansion, and electronics miniaturization-driven thin-gauge demand acceleration.
The model assumes a particular technology adoption path; alternative pathways for silicon oxide barrier coatings would alter the outlook if plasma-enhanced chemical vapor deposition yields prove commercially unviable at scale. Forecasts reflect assumptions on ECHA perfluorinated compound sunset adherence and Indian domestic content requirement enforcement. Material deviation in EU recyclability mandate stringency or Middle Eastern petrochemical supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
Cellulose Film Packaging Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
China BOPP Film Market
Poly film
Global BOPET Packaging Films Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
PVC Cling Film Market
Poly film
Synthetic and Bio Thermoplastic Polyurethane (TPU) Films Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
Polyvinyl Alcohol (PVA) Films Market
Poly film
Colombia Plastic Packaging Films Market
Poly film
PVC Films Market
Poly film
Europe Ethylene-Vinyl Alcohol Copolymer (EVOH) Packaging Films Market
Poly film
Timber Wrap Films Market