
 Foamed Polypropylene Films Market | 2026-2036
Foamed Polypropylene Films Market Size, Share, and Industry Trends Forecast 2026-2036
Foamed Polypropylene Films Market Foresight
China is fragmenting foamed polypropylene film capacity as domestic extrusion lines multiply across Jiangsu and Zhejiang provinces. Toray Industries sustains technology leadership through proprietary biaxial stretching platforms developed at its Chiba research center. Mitsui Chemicals anchors Asian supply chains with backward integration into propylene monomer production. ExxonMobil Chemical competes on metallocene catalyst formulations that yield narrower cell distributions in extruded sheet.
Foamed polypropylene films are cellular thermoplastic structures manufactured through controlled gas injection during extrusion, typically achieving densities between 0.20 and 0.70 g/cm³ depending on expansion ratio and cell morphology. These lightweight substrates provide thermal insulation, impact absorption, and printable surfaces for lamination across industrial and consumer applications. Biaxial oriented foamed films command premium positioning in automotive interiors where dimensional stability under thermal cycling defines specification compliance. Monoaxial grades dominate packaging film volumes due to lower capital intensity in extrusion lines and broader converter familiarity. Coated variants capture margin pools in electronics assembler applications where ESD-dissipative surface treatments prevent component damage during transit.
FDA food-contact regulations govern direct-use packaging films in the United States, while REACH compliance constrains additive packages across European converter operations. EPA emissions standards for vehicle weight reduction indirectly stimulate foamed polypropylene substitution for denser ABS and polyurethane substrates in automotive interiors. NHTSA crashworthiness protocols validate energy-absorbing foamed structures for interior trim applications. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and California that will penalize non-recyclable multi-layer constructions and reward mono-material foamed designs.
Market Dynamics
Automotive lightweighting mandates from NHTSA and EPA fuel economy standards are compressing material substitution cycles, forcing ABS and polyurethane substrates out of dashboard and door panel applications in favor of lower-density foamed polypropylene structures.
Growth Catalysts
- EU Green Deal circular economy requirements:Extended producer responsibility frameworks penalize multi-layer constructions and reward mono-material foamed designs, accelerating converter migration toward recyclable monoaxial grades.
- Acoustic damping specifications in electric vehicles:Biaxial film grades with controlled cell morphology address NVH (noise, vibration, harshness) requirements unique to battery-electric powertrains lacking internal combustion masking.
- Jiangsu and Zhejiang extrusion capacity expansion:Domestic Chinese lines multiply foamed film output, reducing import dependency for Asia-Pacific packaging and automotive supply chains.
Market Restraints
- Propylene monomer price volatility:Crude oil and naphtha feedstock swings compress converter margins, particularly for non-integrated processors lacking captive olefin supply.
- Metallocene catalyst supply concentration:Narrow cell distribution formulations depend on specialized catalyst systems controlled by a limited supplier base, creating input bottlenecks.
- Polyethylene terephthalate (PET) foam substitution:Higher compressive strength PET foams challenge polypropylene in structural automotive applications where load-bearing performance dominates density concerns.
Strategic Opportunities
- India automotive component localization:PLI scheme incentives for advanced chemistry cell and EV manufacturing create captive demand for thermal insulation substrates in battery pack housings.
- ESD-dissipative coated variants:Electronics assembler applications for semiconductor transit protection represent margin pools untapped by standard commodity grades.
- Digital twin extrusion control:Convergence of real-time rheology sensors and machine learning algorithms enables predictive cell structure optimization, reducing off-spec waste.
Industry Challenges
- Biaxial stretching technician scarcity:Proprietary platform operation requires specialized skill sets concentrated at Toray Industries' Chiba research center and similar facilities, limiting technology transfer.
- FDA food-contact certification timelines:Additive package approvals for direct-use packaging films extend 18-24 months, delaying product launches for converters serving US consumer markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foamed Polypropylene Films Market |
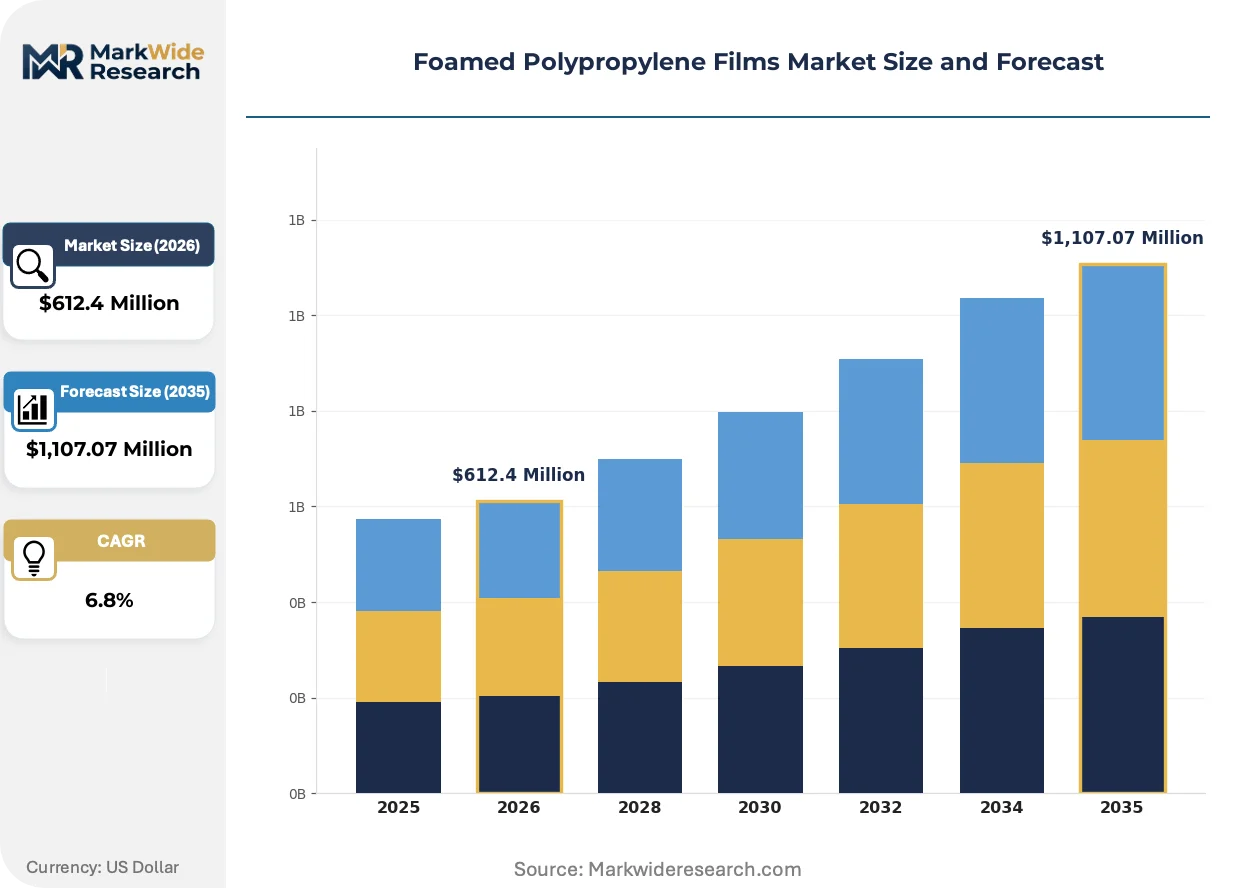
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoaxial, Biaxial, Coated, Laminated, Embossed Application: Packaging Films, Automotive Interiors, Construction Panels, Consumer Goods, Printing Substrates Manufacturing Technology: Extrusion, Injection Molding, Calendering, Thermoforming, Blow Molding End User Industry: Electronics Assemblers, Packaging Producers, Vehicle Component Makers, Building Material Suppliers, Consumer Product Manufacturers |
| Companies Covered | Toray Industries, Inc., 3M Company, ExxonMobil Chemical, SABIC, Mitsui Chemicals, Inc., Jindal Poly Films Ltd, Cosmo Films Ltd, Taghleef Industries, Uflex Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foamed Polypropylene Films Market Shifts & Advancements
Extrusion process control architectures are virtualizing quality assurance workflows, replacing offline laboratory cell morphology verification with inline spectroscopic monitoring that compresses specification drift response times.
Supercritical carbon dioxide physical foaming is virtualizing chemical blowing agent dependency in high-expansion ratio films. Automotive interior suppliers in Germany specify these grades for dashboard substrates requiring thermal cycling dimensional stability. The technology compresses volatile organic compound emissions profiles, aligning with REACH additive restrictions while maintaining cell uniformity.
REACH compliance constraints on additive packages are forcing European converter operations toward simpler, mono-material constructions. ECHA substance of very high concern listings restrict traditional flame retardant and nucleating chemistries. German BMW and Volkswagen suppliers respond by qualifying additive-free biaxial grades with inherent ignition resistance through cell structure engineering.
Specification-driven procurement now dominates automotive tier-one relationships, displacing spot-market volume purchasing. Converter qualification cycles extend 12-18 months for biaxial grades, locking supply positions before production ramp. Germany anchors this behavioral shift, with KBA type-approval documentation requirements forcing early-stage material commitment.
Foamed Polypropylene Films Market Segmentation
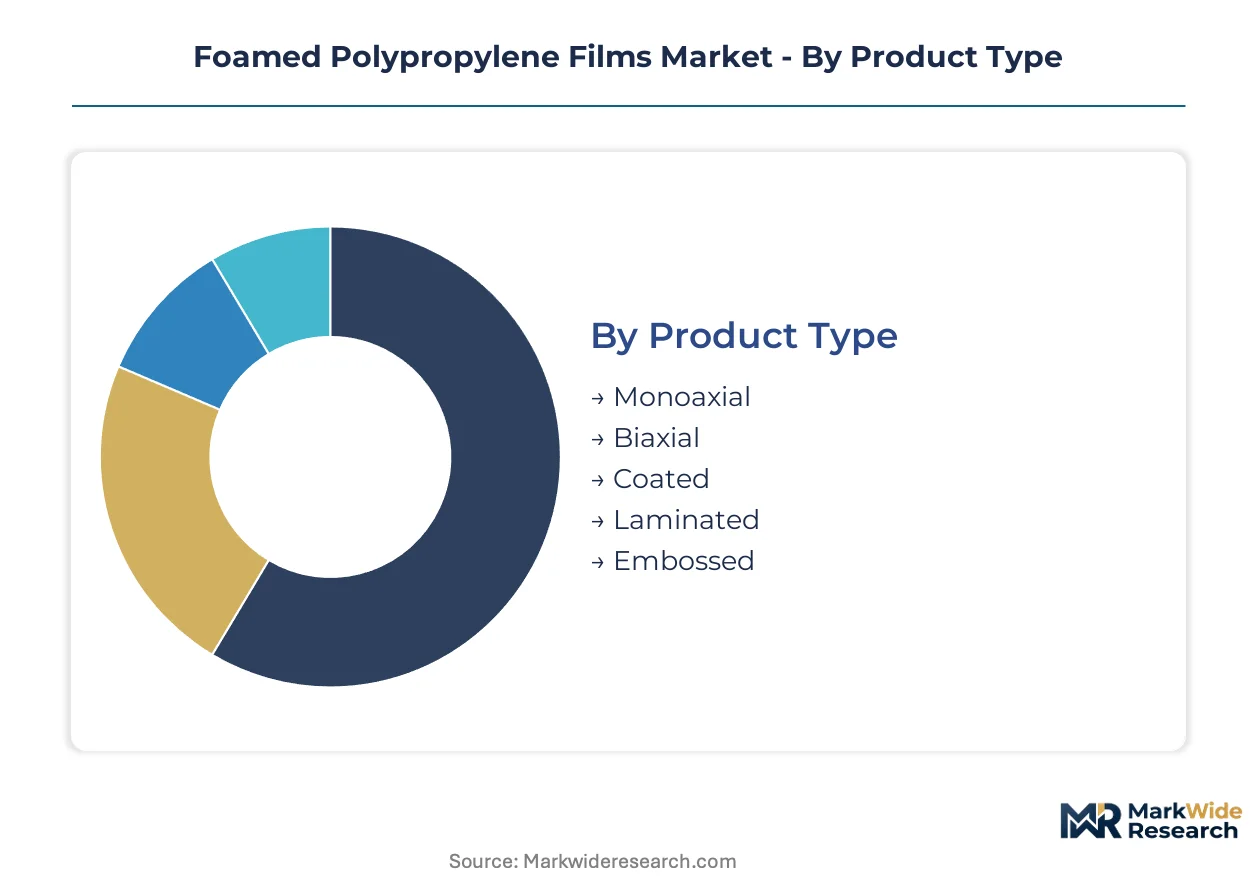
Segmentation in foamed polypropylene films reveals divergent margin structures and qualification timelines across manufacturing methods and end-use specifications. Converter procurement patterns vary dramatically by application, with automotive interiors demanding 12-18 month validation cycles while packaging films turn inventory monthly.
Product Type:
Cycle times stretch from weeks for commodity monoaxial grades to years for automotive-qualified biaxial structures, creating distinct working capital profiles and customer lock-in effects.
- Biaxial:Oriented stretching in machine and transverse directions yields dimensional stability under thermal cycling between minus 40°C and 120°C. BMW and Volkswagen suppliers in Germany specify these grades for dashboard substrates where KBA type-approval documentation mandates batch-level traceability.
- Monoaxial:Single-direction stretching reduces capital intensity in extrusion lines and broadens converter familiarity. Packaging film volumes concentrate here due to faster line speeds and broader additive flexibility under FDA food-contact regulations.
- Coated:ESD-dissipative surface treatments target electronics assembler applications for semiconductor transit protection.
- Laminated:Multi-layer constructions bond foamed cores to barrier films for modified atmosphere packaging.
- Embossed:Surface texturing enhances print adhesion and aesthetic differentiation in consumer goods wrapping.
Monoaxial dominates installed base. Biaxial is where expansion concentrates.
Application:
Margin tiers separate specification-driven automotive procurement from spot-market packaging purchasing, with construction panels occupying an intermediate position on project-based contracting.
- Automotive Interiors:NVH specifications for electric vehicles drive demand for acoustic damping substrates in battery pack housings and cabin trim. NHTSA crashworthiness protocols validate energy-absorbing foamed structures for interior applications, extending converter qualification cycles.
- Packaging Films:Lightweight, printable surfaces serve food-contact and industrial wrapping applications with rapid inventory turnover. FDA additive package approvals extend 18-24 months for direct-use formats, delaying product launches for US consumer markets.
- Construction Panels:Thermal insulation substrates compete with mineral wool and expanded polystyrene in building envelope applications.
- Consumer Goods:Impact absorption properties protect electronics and appliances during retail distribution.
- Printing Substrates:Cellular structures provide rigidity and ink holdout for wide-format graphics and labels.
Packaging Films dominates installed base. Automotive Interiors is climbing the fastest.
Manufacturing Technology:
Technology selection correlates with expansion ratio targets and cell morphology requirements, with extrusion capturing continuous film production and batch processes serving specialty geometries.
- Extrusion:Continuous gas injection during melt processing achieves densities between 0.20 and 0.70 g/cm³ depending on expansion ratio. Supercritical carbon dioxide physical foaming is displacing chemical blowing agents to compress volatile organic compound emissions under REACH restrictions.
- Thermoforming:Secondary shaping of extruded sheet produces three-dimensional automotive interior components with complex geometries.
- Injection Molding:Discontinuous processing suits thick-section structural parts with high expansion ratios.
- Calendering:Roll-based compression creates uniform gauge sheet for lamination and printing applications.
- Blow Molding:Hollow part formation serves specialty packaging and industrial container applications.
Extrusion dominates installed base. Thermoforming is where expansion concentrates.
End User Industry:
Customer concentration varies from fragmented packaging converters to consolidated automotive tier-ones, shaping pricing power and contract structures across the value chain.
- Vehicle Component Makers:Specification-driven procurement now dominates tier-one relationships, displacing spot-market volume purchasing. Early-stage material commitment locks supply positions before production ramp under EPA fuel economy standards.
- Electronics Assemblers:ESD-dissipative coated variants represent margin pools untapped by standard commodity grades, with semiconductor transit protection demanding surface resistivity between 10⁶ and 10⁹ ohms per square.
- Packaging Producers:Converter operations span food-contact, industrial, and consumer goods segments with varying regulatory burdens.
- Building Material Suppliers:Project-based contracting ties volumes to construction cycles and energy retrofit incentives.
- Consumer Product Manufacturers:Brand-owner specifications drive embossed and laminated variants for shelf differentiation.
Packaging Producers dominates installed base. Vehicle Component Makers is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion capacity clusters in three national manufacturing corridors, each shaped by distinct regulatory drivers and end-use procurement patterns. Germany anchors automotive specification demand. China multiplies domestic output for regional supply chains. The United States enforces food-contact and vehicle efficiency standards that filter material selection.
Germany
BMW and Volkswagen suppliers specify foamed polypropylene for dashboard substrates and door panels under KBA type-approval documentation requirements. REACH compliance constraints on additive packages push converters toward mono-material constructions with higher recyclability profiles. The Baden-Württemberg and Bavaria industrial corridors concentrate biaxial film qualification activity.
China
Jiangsu and Zhejiang provinces multiply domestic extrusion lines, reducing import dependency for Asia-Pacific packaging and automotive supply chains. MIIT industrial policy supports lightweight material substitution in electric vehicle manufacturing. The Yangtze River Delta anchors foamed film output expansion for regional battery pack housing demand.
United States
NHTSA crashworthiness protocols validate energy-absorbing foamed structures for interior trim applications, extending converter qualification cycles. EPA fuel economy standards compress material substitution cycles in favor of lower-density substrates. The Midwest automotive belt and Southeast packaging corridor concentrate thermoforming and lamination operations.
Japan
Toray Industries sustains technology leadership through proprietary biaxial stretching platforms developed at its Chiba research center. METI carbon neutrality roadmaps accelerate lightweight material adoption in transportation applications. The Kanto region around Tokyo anchors advanced film research and automotive tier-one supplier relationships.
India
PLI scheme incentives for advanced chemistry cell and EV manufacturing create captive demand for thermal insulation substrates in battery pack housings. BIS standards for automotive materials are tightening qualification requirements for imported films. Maharashtra and Gujarat industrial corridors attract extrusion line investments serving domestic vehicle component makers.
Foamed Polypropylene Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propylene monomer and catalyst supply. The vendor base organizes around three strategic archetypes: integrated petrochemical majors with backward control over olefin feedstock, specialized film extruders with proprietary stretching platforms, and regional converters serving packaging procurement cycles. Competitive moves concentrate on capacity expansion in Asia-Pacific extrusion corridors and technology licensing agreements that transfer biaxial process know-how.
Among integrated chemical majors, Mitsui Chemicals anchors Asian supply chains through captive propylene monomer production, while ExxonMobil Chemical occupies a position in metallocene catalyst formulations. Toray Industries exemplifies the specialized platform tier with concentrated biaxial stretching expertise. These three companies represent distinct competitive vectors: feedstock security, process technology, and catalyst chemistry control.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| 3M Company |
| ExxonMobil Chemical |
| SABIC |
| Mitsui Chemicals, Inc. |
| Jindal Poly Films Ltd |
| Cosmo Films Ltd |
| Taghleef Industries |
| Uflex Ltd |
| Others |
Supply & Pricing Matrix
Propylene monomer price volatility compresses converter margins and simultaneously widens pricing spreads between integrated petrochemical majors and non-integrated processors. This feedstock instability rewards backward integration into olefin production while forcing spot-market buyers toward shorter-term contracting structures.
Pricing Analysis
REACH compliance dictates the pricing tier structure across European converter operations. Three-tier pricing structure across premium, standard, and economy levels separates biaxial automotive grades with KBA type-approval documentation from commodity monoaxial packaging films and unqualified embossed variants. Certification tier and volume scale drive price differentiation, with FDA food-contact additive packages commanding premiums over industrial grades. Pricing pressure stems from polyethylene terephthalate foam substitution in structural automotive applications. Packaging producers exhibit highest price sensitivity due to monthly inventory turnover, while vehicle component makers accept premium positioning for 12-18 month qualification cycles.
Supply Chain Analysis
Extrusion capacity concentrates in Germany, China, and Japan, with Toray Industries' Chiba research center anchoring proprietary biaxial stretching platform deployment. Raw material flows draw from propylene monomer production, metallocene catalyst formulations, and supercritical carbon dioxide physical foaming systems. Single-source vulnerability sits with specialized catalyst suppliers controlling narrow cell distribution chemistries. Distribution runs through automotive tier-one supplier networks in Baden-Württemberg, Yangtze River Delta packaging converters, and Kanto region electronics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from polyethylene terephthalate foams challenging polypropylene in load-bearing automotive structures. Defense requires entrenching specification-driven relationships before qualification cycles lock in competitor materials.
For Market Incumbents: Entrench biaxial stretching platform control through technician training programs that replicate Toray Industries' Chiba center expertise. Capture backward integration into propylene monomer production to neutralize feedstock volatility compressing converter margins. Prioritize KBA type-approval documentation completion before PET foam suppliers achieve crashworthiness protocol validation. For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors offer underpenetrated extrusion capacity serving PLI scheme battery pack housing demand. Target ESD-dissipative coated variants for semiconductor transit protection where surface resistivity specifications between 10⁶ and 10⁹ ohms per square command margin premiums unavailable in commodity grades. Pursue digital twin extrusion control partnerships with real-time rheology sensor providers to bypass biaxial stretching technician scarcity. For Investors and Strategic Acquirers: The market sits at a substitution defense phase that favors integrated petrochemical majors with captive olefin supply and proprietary platform specialists. Long-term viability hinges on circular economy credentialing under EU Green Deal extended producer responsibility frameworks. Monitor ECHA substance of very high concern listings for flame retardant and nucleating chemistry restrictions that would accelerate additive-free grade qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Monomer | Mitsui Chemicals' captive olefin production anchors Asian supply chain resilience against naphtha feedstock swings. |
| Supercritical CO2 Physical Foaming Transition | REACH volatile organic compound restrictions favor this technology over chemical blowing agents in German automotive specifications. |
| Biaxial Stretching Platform Licensing | Technology transfer agreements address technician scarcity constraining Toray Industries' proprietary Chiba center expansion. |
| ESD-Dissipative Coating Development | Surface resistivity engineering targets electronics assembler margins untapped by standard commodity foamed grades. |
| Monoaxial Grade Recyclability Repositioning | EU Green Deal circular economy requirements penalize multi-layer constructions and reward mono-material designs. |
Research Methodology
A spread of perspectives from extrusion plant managers, automotive tier-one procurement leads, packaging converter technical directors, and metallocene catalyst R&D heads converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, ACC and Cefic chemical industry reports, SEC 10-K filings, and KBA type-approval documentation. Bottom-up capacity installation tracking across Jiangsu and Zhejiang provinces triangulated against top-down demand modeling from EPA fuel economy standard compliance schedules.
Demand-supply balance modeling anchored volume projections across the analysis window. Segmentation dimensions included film orientation type, end-use application, manufacturing technology, and regional production hub clustering. CAGRs derived from recursive substitution elasticity modeling against ABS and polyurethane substrate displacement rates in automotive interiors. Forecast inputs incorporated NHTSA crashworthiness protocol adoption timelines and MIIT electric vehicle lightweighting policy implementation.
Practitioners should monitor propylene monomer price volatility, ECHA substance of very high concern listing expansions, and PET foam compressive strength improvements for early signals of forecast revision. Quarterly review of KBA type-approval documentation issuance rates and Jiangsu province extrusion line commissioning data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Latin America Plastic Packaging Films Market
Poly film
Anti Fog Polycarbonate Films and Sheets Market
Poly film
Global Polyethylene Packaging Market
Poly film
Latin America Polypropylene (PP) Packaging Film Market
Poly film
PCR Lidding Films Market
Poly film
Polyolefin Films Market
Poly film
Chocolate Wrapping Films Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Colourless Polyimide Films Market
Poly film
Wrap Around Label Films Market
Poly film
PVC Cling Film Market
Poly film
Printed Plastic Films Market
Poly film
Polylaminate Capsules Market
Poly film
In-Mould Label Film Market
Poly film
Laminated Packaging Films Market
Poly film
Laminating Film Market