
 Global Blown Stretch Packaging Films Market | 2026-2036
Global Blown Stretch Packaging Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blown Stretch Packaging Films Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD), with its emphasis on circular economy principles, is recalibrating material selection criteria for blown stretch films. This shift favors producers with advanced recycling capabilities and transparent supply chains. Berry Global Group, Inc. leverages its scale in recycled content sourcing to meet these new demands. Amcor plc specializes in high-performance films with reduced material thickness, aligning with client sustainability goals.
Blown stretch packaging film is a plastic wrap produced via the blown film extrusion process, typically using Linear Low Density Polyethylene (LLDPE). This method imparts superior puncture resistance and bidirectional tear strength. Its primary purpose is to secure, bundle, and stabilize products on a pallet during transit and storage. Metallocene LLDPE films command a premium for their enhanced performance, while pallet bundling for industrial wrapping remains the core application by volume.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Union's REACH regulation govern chemical composition and food contact safety. China's GB standards also impose strict requirements on materials used in food packaging. Navigating these diverse, evolving standards for recycled content and material safety is a critical challenge for producers seeking market access across multiple jurisdictions. Stakeholders must balance performance, cost, and compliance with emerging circular economy mandates.
Market Dynamics
The market's central tension lies between the industrial need for high-performance films and intensifying regulatory pressures for circularity. Mandates like the EU Green Deal are forcing a re-evaluation of material science, balancing puncture resistance with increased recycled content specifications.
Growth Catalysts
- Food Sector Demand:Demand from the food and beverage industry for films with superior barrier properties is rising to extend product shelf life and reduce waste.
- Logistics Expansion:E-commerce growth in China's Pearl River Delta and Yangtze River Delta manufacturing hubs requires significantly more pallet bundling films for shipment consolidation.
- EU Sustainability Mandates:The European Union's Corporate Sustainability Reporting Directive (CSRD) incentivizes the adoption of films with verifiable recycled content, creating a premium market segment.
Market Restraints
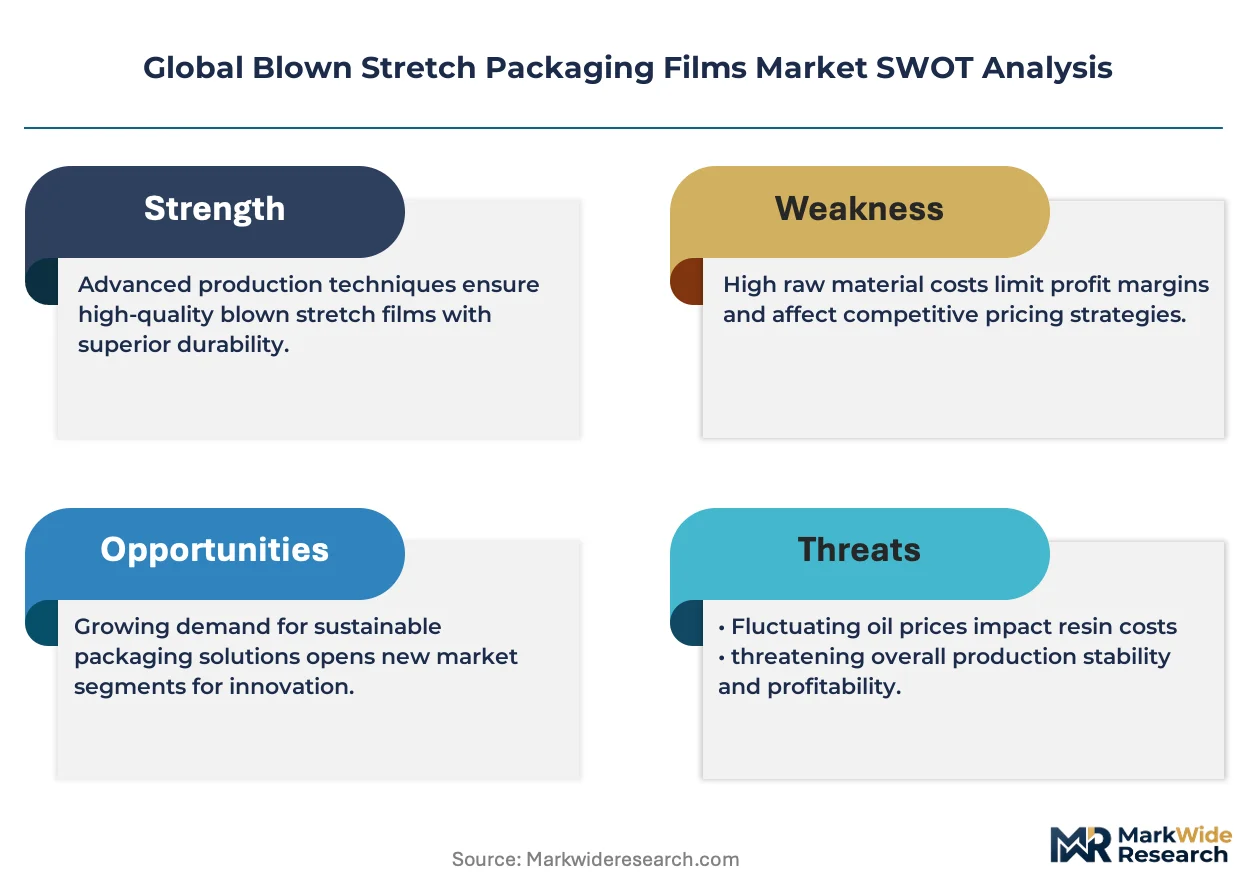
- Feedstock Volatility:Price fluctuations in Linear Low Density Polyethylene (LLDPE) feedstock, tied directly to crude oil markets, create significant margin instability for film converters.
- Performance Degradation:Incorporating high percentages of post-consumer recycled (PCR) content can degrade key film properties like clarity and tear strength, limiting its application.
- Substitution Threats:Alternative pallet stabilization methods, including reusable strapping and specialized adhesives, present a threat in closed-loop logistics systems seeking to eliminate single-use plastics.
Strategic Opportunities
- Specialized Applications:Development of high-strength films tailored for securing irregularly shaped and heavy loads within the construction and building materials transportation sector.
- Smart Packaging Integration:Embedding RFID tags or other sensor technologies into stretch films provides real-time tracking and condition monitoring for high-value pharmaceutical and electronics shipments.
- Geographic Expansion:Penetration into Southeast Asian markets, particularly Vietnam and Indonesia, aligns with the rapid scaling of their manufacturing and export-oriented economies.
Industry Challenges
- Regulatory Fragmentation:Navigating the complex and divergent requirements for food-contact materials across jurisdictions, including the US FDA, EU's REACH, and China's GB standards, is a major compliance hurdle.
- Capital Investment:The high capital expenditure needed for advanced blown film extrusion lines that can process high-recycled-content resins without compromising quality is a barrier for smaller producers.
- Content Certification:A lack of universal standards for measuring and certifying recycled content in films leads to market confusion and potential for unsubstantiated green claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blown Stretch Packaging Films Market |
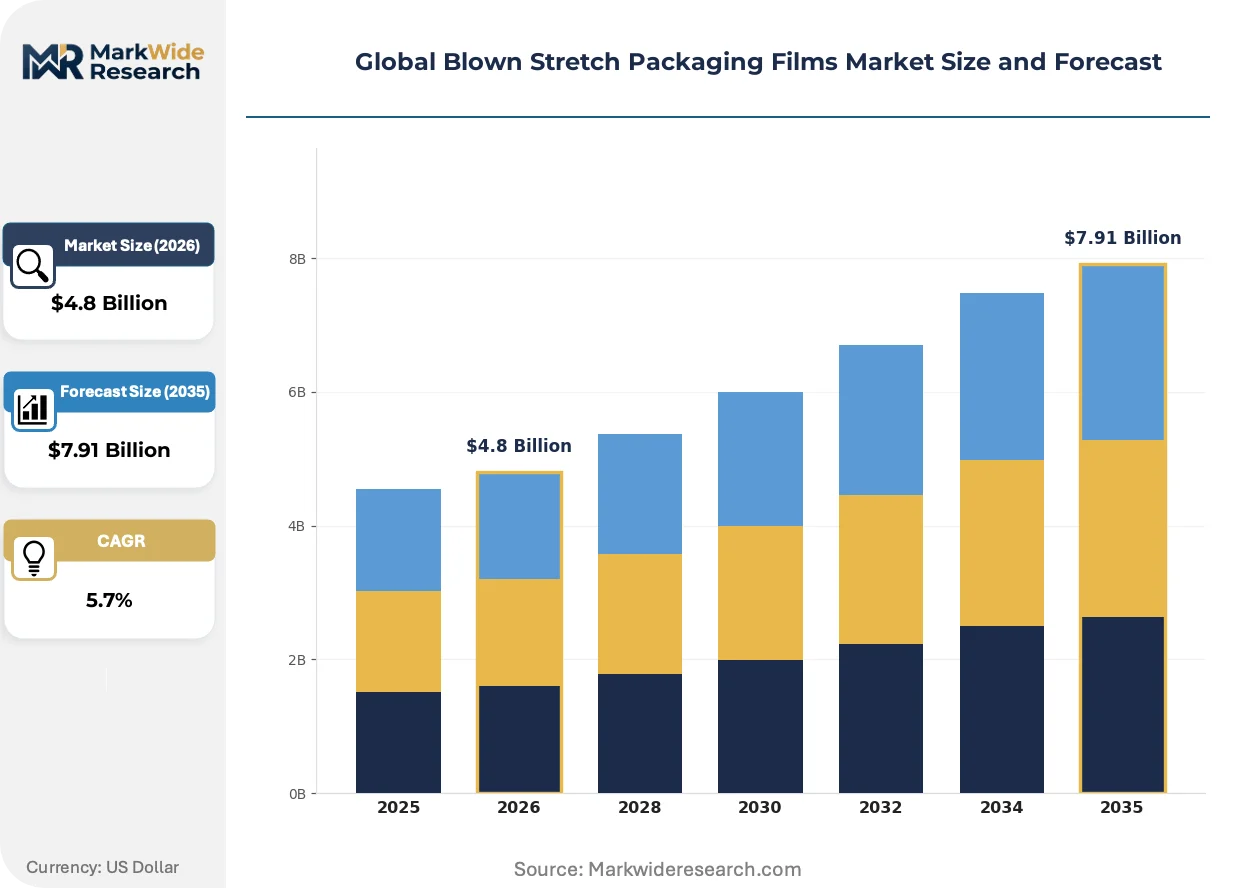
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density Polyethylene, Linear Low Density Polyethylene, Metallocene LLDPE, Polypropylene, Polyvinylidene Chloride, Ethylene Vinyl Acetate Application: Food Packaging, Industrial Wrapping, Pallet Bundling, Consumer Goods Packaging, Agricultural Produce, Pharmaceutical Protection End User: Manufacturing Plants, Warehouses, Logistics Providers, Retail Distribution Centers, Packaging Companies, Cold Storage Facilities Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Wholesalers, Retailers, Packaging Events |
| Companies Covered | Berry Global Group, Inc., Sigma Plastics Group, AEP Industries Inc., Intertape Polymer Group Inc., Paragon Films Inc., Amcor plc, Sealed Air Corporation, Novolex, Inteplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blown Stretch Packaging Films Market Strategic Shifts & Innovations
Material science and digital technologies are converging to redefine film performance and application efficiency. This integration enables more precise material usage and data-driven optimization of pallet wrapping, aligning with sustainability and cost-reduction goals.
Advanced co-extrusion produces multi-layer films, allowing a recycled core with virgin outer layers for performance. Logistics and manufacturing sectors adopt these films to meet sustainability targets without compromising load security. This precise control of layer composition is automating the balance between cost, performance, and recycled content mandates.
China's GB standards for food-contact materials are becoming more stringent, especially regarding recycled plastics. This regulation requires film producers to use segregated supply chains and rigorous testing to validate post-consumer resin safety. The food packaging segment is most affected, pivoting to certified virgin materials or advanced recycling for compliance.
Large end-users are moving from per-roll purchasing to total-cost-of-ownership models evaluating film use, load damage, and wrapping efficiency. This disrupts traditional distributor sales, favoring suppliers who offer on-site audits and performance guarantees. The trend is most visible within automated warehousing and 3PL sectors in North America and Europe.
Global Blown Stretch Packaging Films Market Segmentation
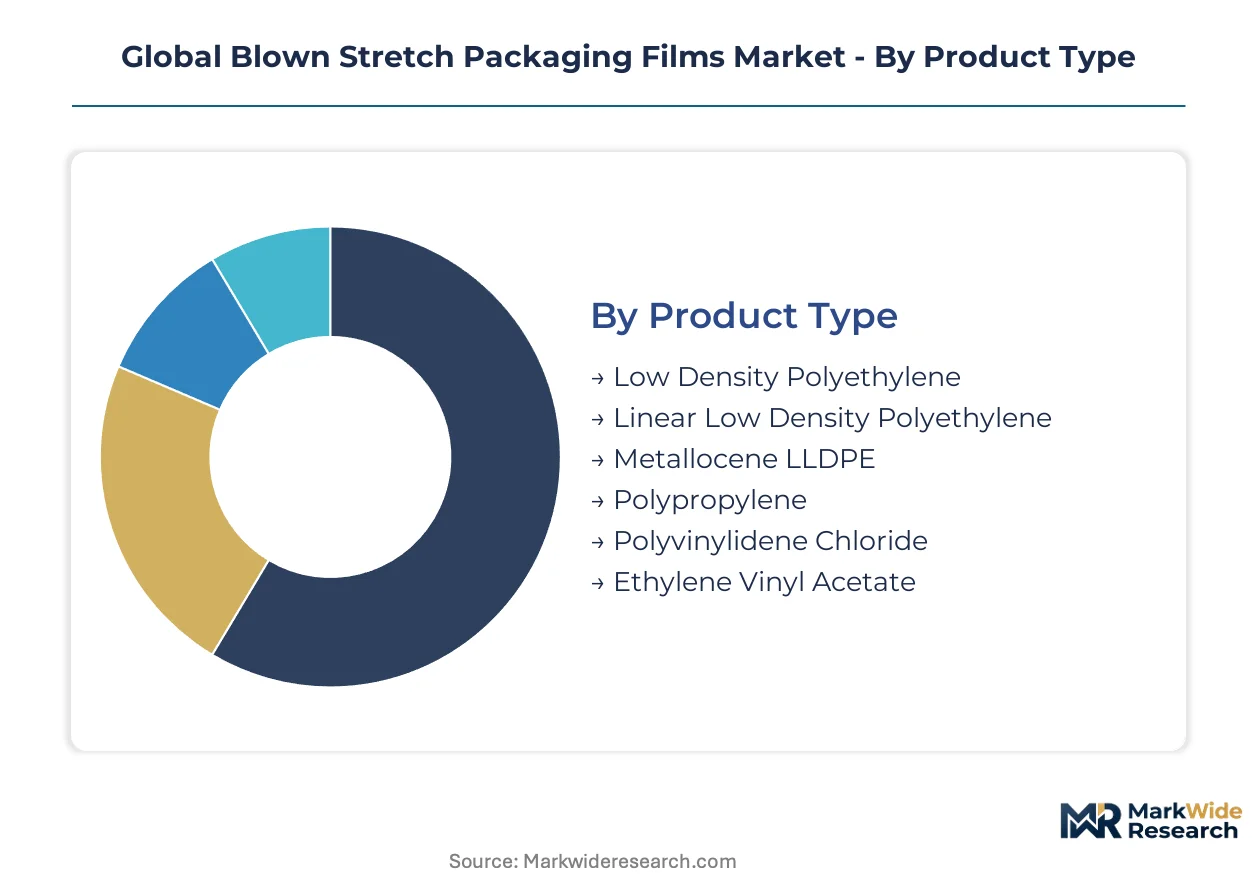
Segmentation analysis for blown stretch packaging films delineates the market's intricate structure, revealing how material innovations, diverse applications, and evolving distribution models influence demand. Understanding these distinct segments is crucial for stakeholders to align product development and market strategies with specific industry needs and regulatory shifts.
Product Type:
Blown stretch packaging films are categorized by the polymer resins used, each offering distinct mechanical and barrier properties essential for various packaging functions.
- Metallocene LLDPE:This advanced polymer offers superior puncture resistance, tear strength, and cling, commanding a premium for high-performance applications. Demand concentrates in specialized industrial and logistics sectors requiring robust load security, particularly in Europe.
- Linear Low Density Polyethylene:As the predominant material, LLDPE provides an excellent balance of strength, stretch, and cost-effectiveness for general-purpose pallet wrapping. Its demand is foundational across global manufacturing and warehousing operations, including those in China.
- Low Density Polyethylene:LDPE films are valued for their flexibility and clarity, typically used in lighter-duty packaging and consumer applications.
- Polypropylene:PP films offer high stiffness and excellent clarity, making them suitable for specific bundling and retail packaging solutions.
- Polyvinylidene Chloride:PVDC films are chosen for their exceptional barrier properties against oxygen and moisture, critical for sensitive food products.
- Ethylene Vinyl Acetate:EVA films provide enhanced elasticity and adhesion, often blended with other polymers to improve film performance.
Mature deployment sits with Linear Low Density Polyethylene. Newer deployment is concentrated in Metallocene LLDPE.
Application:
The diverse applications of blown stretch films reflect their utility in securing and protecting various goods across industrial and consumer sectors.
- Food Packaging:These films require superior barrier properties to extend product shelf life and prevent contamination, meeting strict regulations from the US FDA and China's GB standards. Demand is rising from global food processors seeking to reduce waste.
- Pallet Bundling:This remains the core application by volume, securing and stabilizing products on pallets during transit and storage. E-commerce growth in regions like China's Pearl River Delta drives significant demand for these films.
- Industrial Wrapping:Films protect heavy machinery, components, and raw materials from damage and environmental exposure during transport.
- Consumer Goods Packaging:Used for bundling multi-packs, protecting retail items, and providing tamper evidence for various products.
- Agricultural Produce:Films safeguard hay bales, silage, and other farm goods from weather and spoilage, preserving their quality.
- Pharmaceutical Protection:This segment demands high-purity films for sterile and sensitive medical products, adhering to stringent regulatory requirements.
Pallet bundling represents the largest volume application. Food packaging is currently expanding most quickly.
End User:
End-user segments highlight the varied operational environments where blown stretch films are indispensable for product protection and logistical efficiency.
- Manufacturing Plants:These facilities utilize films for internal product transfer, protecting finished goods, and preparing shipments for distribution. Demand is consistently high in industrial centers, including those across Germany.
- Logistics Providers:Companies specializing in transport and warehousing rely on stretch films for consolidating, securing, and protecting diverse shipments across complex supply chains. This is critical for e-commerce fulfillment in the United States.
- Warehouses:Films are employed for long-term storage stability, protecting inventory from dust and damage while facilitating efficient stock rotation.
- Retail Distribution Centers:These centers use films to secure and organize products efficiently before their final delivery to retail outlets.
- Packaging Companies:Firms specializing in packaging solutions integrate blown stretch films into their broader offerings for various client industries.
- Cold Storage Facilities:Films in this segment must maintain integrity and performance in low-temperature environments, protecting perishable goods.
Demand is highly concentrated among manufacturing plants and logistics providers.
Distribution Channel:
The distribution channels for blown stretch films reflect established supply networks and emerging digital avenues, connecting producers with a diverse customer base.
- Distributors:These intermediaries provide regional access, inventory management, and technical support for a wide range of end-users, consolidating demand from smaller buyers. They are crucial for market reach in countries like India.
- Direct Sales:This channel involves direct transactions between film manufacturers and large-volume end-users, often for customized film specifications and long-term contracts. Major industrial clients in Japan often prefer this approach.
- E-commerce Platforms:Online platforms offer convenient purchasing options for smaller quantities and specialized film types, reaching a broader customer base.
- Wholesalers:These entities supply films in bulk to various businesses, often complementing the reach of larger distributor networks.
- Retailers:Retail outlets provide films for consumer and small business use, typically in smaller roll formats for convenience.
- Packaging Events:Industry trade shows and specialized events facilitate direct engagement and sales between producers and niche buyers.
Traditional distribution through distributors and direct sales remains dominant. E-commerce platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Pearl River Delta manufacturing hubs drive significant demand for blown stretch packaging films. These industrial centers require robust pallet bundling solutions for their extensive export-oriented logistics. The region's rapid e-commerce expansion further intensifies film consumption.
China
E-commerce growth and expanding manufacturing sectors in China demand high volumes of pallet bundling films. China's GB standards enforce strict material quality and safety requirements for packaging, particularly for food contact. The Yangtze River Delta, with its dense industrial base, concentrates significant film consumption for goods consolidation.
United States
Logistics providers and e-commerce fulfillment centers in the United States require efficient stretch films for product security. The US FDA regulations dictate specific material compositions for food packaging applications, influencing film innovation. Major logistics corridors, including those around Chicago and Dallas, see substantial film use in automated warehousing.
Germany
Manufacturing plants across Germany utilize blown stretch films for internal transfers and preparing goods for distribution. The EU Green Deal and its Corporate Sustainability Reporting Directive (CSRD) mandates incentivize films with higher verifiable recycled content. Industrial centers within North Rhine-Westphalia drive consistent film demand for protecting diverse manufactured products.
India
Expanding manufacturing and growing distribution networks in India create substantial demand for general-purpose LLDPE films. The Bureau of Indian Standards (BIS) sets quality benchmarks for packaging materials for various industries. Large industrial zones like those in Gujarat and Maharashtra are key areas for film consumption by various industries.
Global Blown Stretch Packaging Films Market Key Industry Players
The competitive structure tilts toward a tiered landscape, featuring global integrated producers alongside specialized regional manufacturers. Larger entities leverage scale in raw material procurement and advanced recycling capabilities to meet sustainability mandates. Dominant competitive moves include strategic partnerships for material innovation and continuous capacity expansion to meet regional demand. Portfolio diversification into high-performance films also characterizes market competition.
Global scale players like Berry Global Group, Inc. and Amcor plc occupy positions emphasizing broad product portfolios and sustainability solutions, aligning with evolving regulatory demands across multiple jurisdictions. These entities often exemplify the integration of advanced material science and transparent supply chains to address circular economy principles. Sigma Plastics Group, another significant player, represents a large-volume provider focusing on diverse film offerings for industrial applications and widespread distribution networks, particularly in North America.
| Leading Market Players |
|---|
| Berry Global Group, Inc. |
| Sigma Plastics Group |
| AEP Industries Inc. |
| Intertape Polymer Group Inc. |
| Paragon Films Inc. |
| Amcor plc |
| Sealed Air Corporation |
| Novolex |
| Inteplast Group |
| Others |
Cost & Logistics Intelligence
Metallocene LLDPE's performance-driven pricing divergence from standard LLDPE films shapes distinct supply chain configurations. This bifurcation influences material sourcing and manufacturing complexity across the market.
Pricing Analysis
Value-based pricing for high-performance films anchors their market position. Premium-mid-economy pricing differentiation stratifies product offerings based on superior puncture resistance, tear strength, and certified recycled content. Pricing softness runs through standard LLDPE films due to persistent Linear Low Density Polyethylene feedstock volatility tied to crude oil markets. E-commerce logistics providers exhibit high price sensitivity for general-purpose films, while the pharmaceutical protection segment prioritizes film integrity and compliance over cost.
Supply Chain Analysis
Reverse logistics for post-consumer recycled content drives specific material flows back into the blown stretch film supply chain, particularly for Europe's circular economy mandates. Supply concentration for virgin Linear Low Density Polyethylene (LLDPE) draws from major petrochemical hubs in China and the Middle East. Raw material dependencies center on LLDPE, metallocene catalysts, and certified PCR resins for high-performance applications. Commodity price volatility for LLDPE presents a structural risk to film converters. Distribution runs through established distributor networks for regional access and direct sales to large industrial end-users like manufacturing plants in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blown stretch packaging films market presents a consolidation play. High capital expenditure for advanced blown film extrusion lines forces smaller, less capitalized producers out of the market.
For Market Incumbents: Lock in long-term supply agreements for certified post-consumer recycled (PCR) resins to meet EU Green Deal mandates and ensure material availability. Invest in advanced co-extrusion technology to blend high PCR content without compromising film performance, actively countering substitution threats from reusable strapping. Deepen vertical integration into recycling capabilities to control feedstock quality and reduce reliance on volatile virgin polymer markets. Expand capacity in high-growth regions like China to capture logistics expansion and strengthen market presence.
For New Entrants and Emerging Players: Small to medium-sized manufacturing plants in Southeast Asia represent an underserved buyer archetype with growing demand. Target specialized applications like construction materials packaging with high-strength films designed for irregular loads. Penetrate Vietnam and Indonesia by offering performance-guaranteed solutions for their rapidly scaling export economies, focusing on local distribution partnerships. Focus on on-site audits and total-cost-of-ownership models to differentiate against traditional per-roll purchasing and attract discerning clients.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated specialists with proprietary advanced recycling technology and strong intellectual property. The market offers favorable long-term viability over the next 5-10 years for players aligned with circular economy mandates and material innovation. Acquire firms demonstrating strong R&D in high-performance, high-recycled-content films that address diverse regulatory requirements. Monitor the adoption rate of certified recycled content in food packaging as a key inflection indicator for market transformation and sustainable growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports e-commerce growth in China's Pearl River Delta manufacturing hubs. |
| Advanced Co-extrusion Investment | Enables high post-consumer recycled content without compromising film properties. |
| Recycled Content Certification | Meets EU Corporate Sustainability Reporting Directive mandates for circular economy compliance. |
| Smart Packaging Integration | Provides real-time tracking for high-value pharmaceutical and electronics shipments. |
| Geographic Market Entry | Captures scaling manufacturing demand in Vietnam and Indonesia's export economies. |
Research Approach
Multi-period observation of LLDPE price trends, regulatory compliance rates, and end-user adoption of high-performance films anchored the trend analysis, supplemented by interviews. Primary research involved R&D directors from film manufacturers, logistics managers from 3PLs, food packaging procurement specialists, and regulatory affairs experts. Secondary data drew from US FDA guidance, EU REACH reports, China GB standards, and polymer resin customs data. This approach facilitated robust bottom-up and top-down triangulation for market sizing.
Segment-weighting across product type, application, end-user, and regional regulatory frameworks structured the quantitative modeling. This framework projected market evolution over the projection horizon, with Compound Annual Growth Rates derived from historical growth patterns and future adoption curves. Key industry-specific forecast inputs included LLDPE feedstock supply forecasts and e-commerce logistics volume projections. The model integrated these dimensions for comprehensive market outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and new material science breakthroughs. Forecasts reflect assumptions regarding regulatory stability and LLDPE supply chain continuity. Practitioners should monitor major regulatory updates and advanced recycling infrastructure investments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
APET Film Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Thermoplastic Polyurethane (TPU) Films Market
Poly film
Timber Wrap Films Market
Poly film
PE Foam Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Polyimide Films and Tapes Market
Poly film
Co Extruded Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
Polypropylene Film Market
Poly film
Mexico Plastic Packaging Films Market
Poly film
Bopet Films Market
Poly film
Poly Coated Paper Market
Poly film
Morocco Plastic Packaging Films Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market