
 Polyethylene Cast Film Market | 2026-2036
Polyethylene Cast Film Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Cast Film Market Analysis
Southeast Asia is tilting toward expanded polyethylene cast film capacity as converters respond to regional food export growth. Amcor PLC leverages its integrated global footprint to supply multilayer films for protein packaging across ASEAN markets. Jindal Poly Films anchors South Asian demand through specialized biaxial and cast film lines serving snack and dairy brands. Sigma Plastics Group competes on manufacturing scale in North America with dedicated cast film operations for industrial stretch and bundling applications.
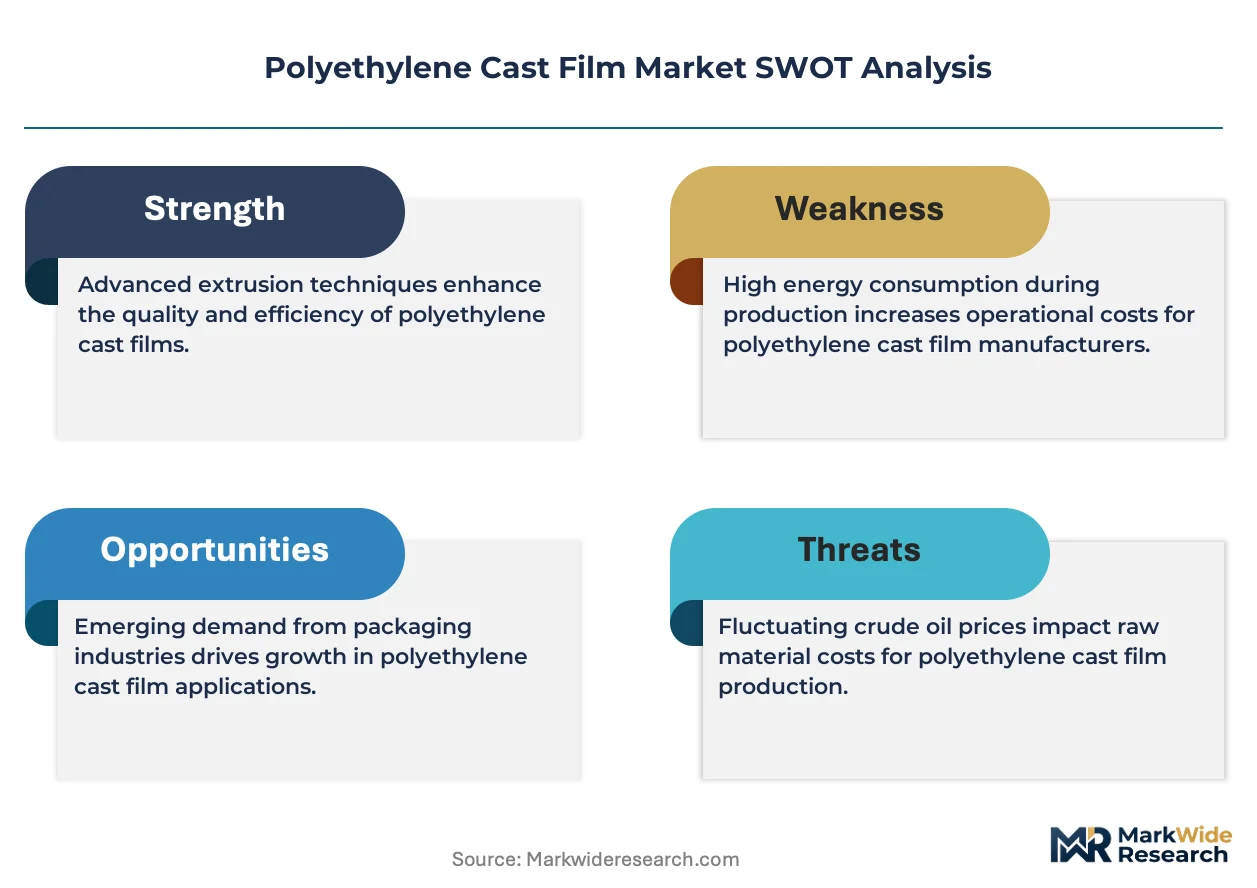
Polyethylene cast film is a flat-die extruded polymer sheet typically ranging from 12 to 150 microns in thickness, produced by melting polyethylene resin through a slit die and chilling it on polished rolls to achieve optical clarity and gauge uniformity. Its primary purpose is to deliver barrier protection, seal integrity, and mechanical strength for flexible packaging, medical sterilization, and load containment. Multilayer film configurations command margin pools where oxygen and moisture barriers justify premium positioning over monolayer alternatives. Stretch film segments within industrial packaging sustain volume leadership despite thinner-gauge trends that compress per-unit revenue.
FDA food-contact regulations and EU REACH restrictions on additive migration shape formulation choices and limit certain phthalate-based plasticizers in cast film destined for direct food contact. ISO 9001 and BRC packaging standards further govern quality systems for medical and food-grade film producers seeking multi-market access. Stakeholders must monitor evolving extended producer responsibility frameworks and mechanical recycling infrastructure build-outs to determine whether circular-content commitments alter resin sourcing strategies.
Market Dynamics
Converters across Southeast Asia are installing multilayer cast film lines to capture food export demand, while REACH and FDA migration limits force simultaneous reformulation of additive packages and resin blends.
Growth Catalysts
- ASEAN food export protocols:Vietnam and Indonesia mandate extended shelf-life packaging for seafood and fresh produce shipments to Japan and South Korea. Multilayer oxygen-barrier films satisfy these requirements where monolayer structures fail.
- EU REACH Article 33:Substance of Very High Concern disclosure rules are accelerating substitution of legacy plasticizers with bio-based alternatives in cast films destined for European supermarkets.
- Mechanical recycling infrastructure:Advanced sorting and reprocessing facilities in Germany and the Netherlands create offtake certainty for post-industrial film scrap, improving circular-economy economics for producers.
Market Restraints
- Ethylene feedstock volatility:Naphtha and ethane price spreads compress margin predictability for non-integrated cast film extruders in the US Gulf Coast and Rotterdam clusters.
- Linear low-density polyethylene supply concentration:Saudi Aramco, SABIC, and Dow control roughly half of global LLDPE capacity, creating procurement risk for independent film converters during force majeure events.
- Technical gauge floor:Stretch film below 8 microns exhibits elevated tear propagation and load containment failure, limiting downgauging potential in automated pallet-wrapping systems.
Strategic Opportunities
- Philippines converting base:Domestic flexible packaging capacity remains underdeveloped relative to food processing growth, creating first-mover advantage for cast film suppliers establishing local slitting and metallization operations.
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content targets for plastic packaging create premium positioning for film producers with verified mass-balance certification from ISCC PLUS schemes.
- Active packaging convergence:Integration of oxygen scavengers and moisture regulators into cast film substrates opens medical device and premium meat packaging segments previously served by rigid barrier formats.
Industry Challenges
- Multilayer coextrusion expertise:Seven-layer and nine-layer die configuration requires polymer rheology specialists scarce in emerging-market converting workforces, slowing technology transfer from European equipment suppliers.
- BRCGS Packaging certification timelines:Food-grade film plants require 12-18 month audit cycles for Issue 6 compliance, delaying market entry for greenfield facilities targeting major retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Cast Film Market |
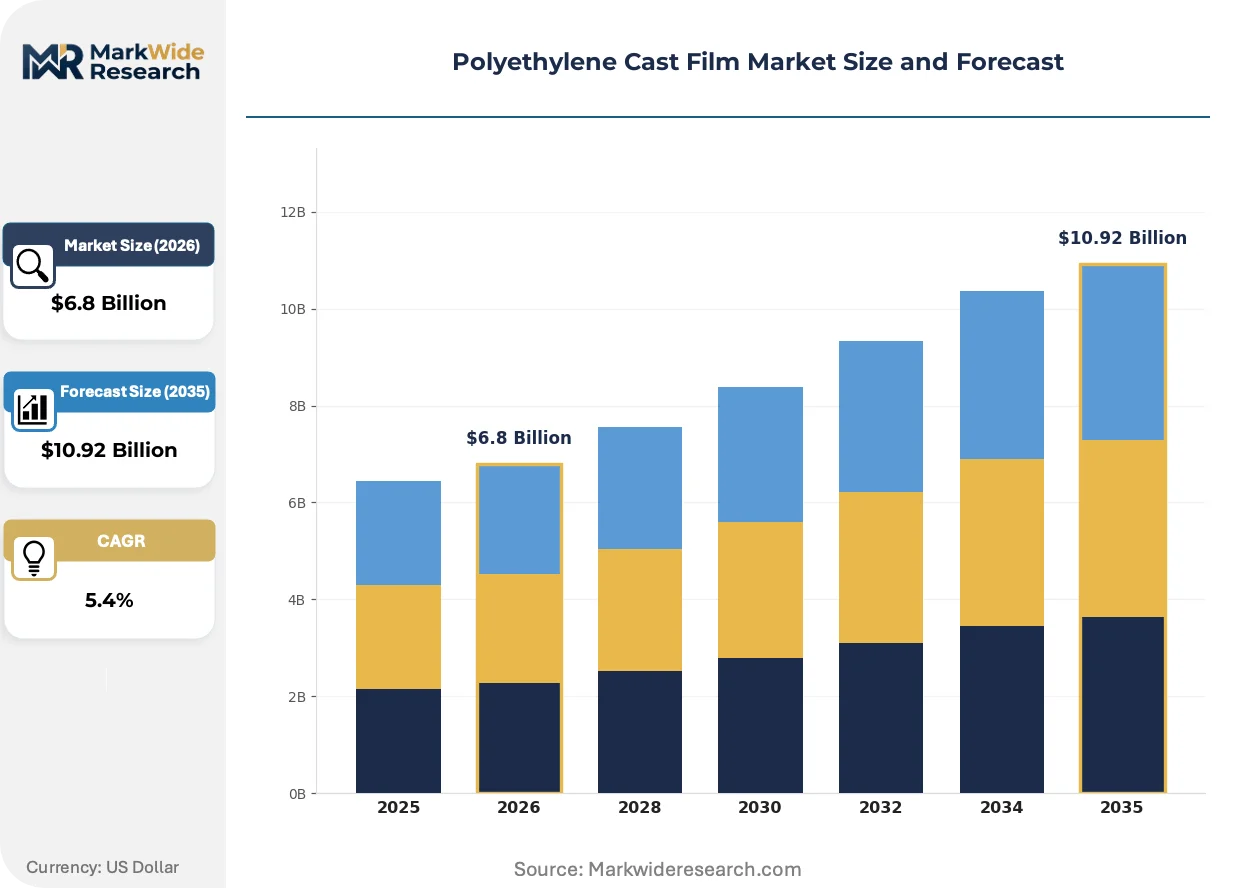
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monolayer Film, Multilayer Film, Co-extruded Film, Stretch Film End Use Industry: Food Packaging, Medical Applications, Consumer Goods, Industrial Packaging Thickness: Below 25 Microns, 25-50 Microns, 51-75 Microns, Above 75 Microns Manufacturing Process: Extrusion, Blown Film Production, Casting, Coating |
| Companies Covered | Amcor PLC, SABIC Innovative Plastics, Inteplast Group, Taghleef Industries, Jindal Poly Films, Sigma Plastics Group, Novolex Holdings, Copol International, Berry Global Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Cast Film Market Emerging Trajectories
Cast film producers are reconfiguring extrusion lines and resin formulations to satisfy simultaneous demands for thinner gauges, higher barrier performance, and mechanical recycling compatibility.
Metallocene polyethylene resins are collapsing the performance gap between conventional LLDPE and premium plastomers in stretch film applications. Automated distribution centers in the US and Germany are specifying these grades for high-speed wrapping equipment. The technology is collapsing unit revenue per pallet wrapped while extending roll footage and reducing changeover frequency.
EU F-Gas Regulation phase-down schedules are accelerating adoption of non-fluorinated barrier technologies in cast film for modified-atmosphere packaging. Producers are reformulating with ethylene vinyl alcohol and polyamide layers to maintain oxygen transmission rates without per- and polyfluoroalkyl substances. Medical sterilization film suppliers face the steepest compliance timeline, with 2025 deadlines forcing capital redeployment toward coextrusion barrier lines.
Brand-led packaging reduction commitments are compressing specification cycles from annual to quarterly review periods. Retailers in France and the UK are unbundling film procurement from historical converter relationships, issuing spot tenders for lightweighted formats. The shift is most visible in private-label fresh produce, where supermarket technical teams now specify micron targets directly rather than delegating to packaging distributors.
Polyethylene Cast Film Market Segmentation
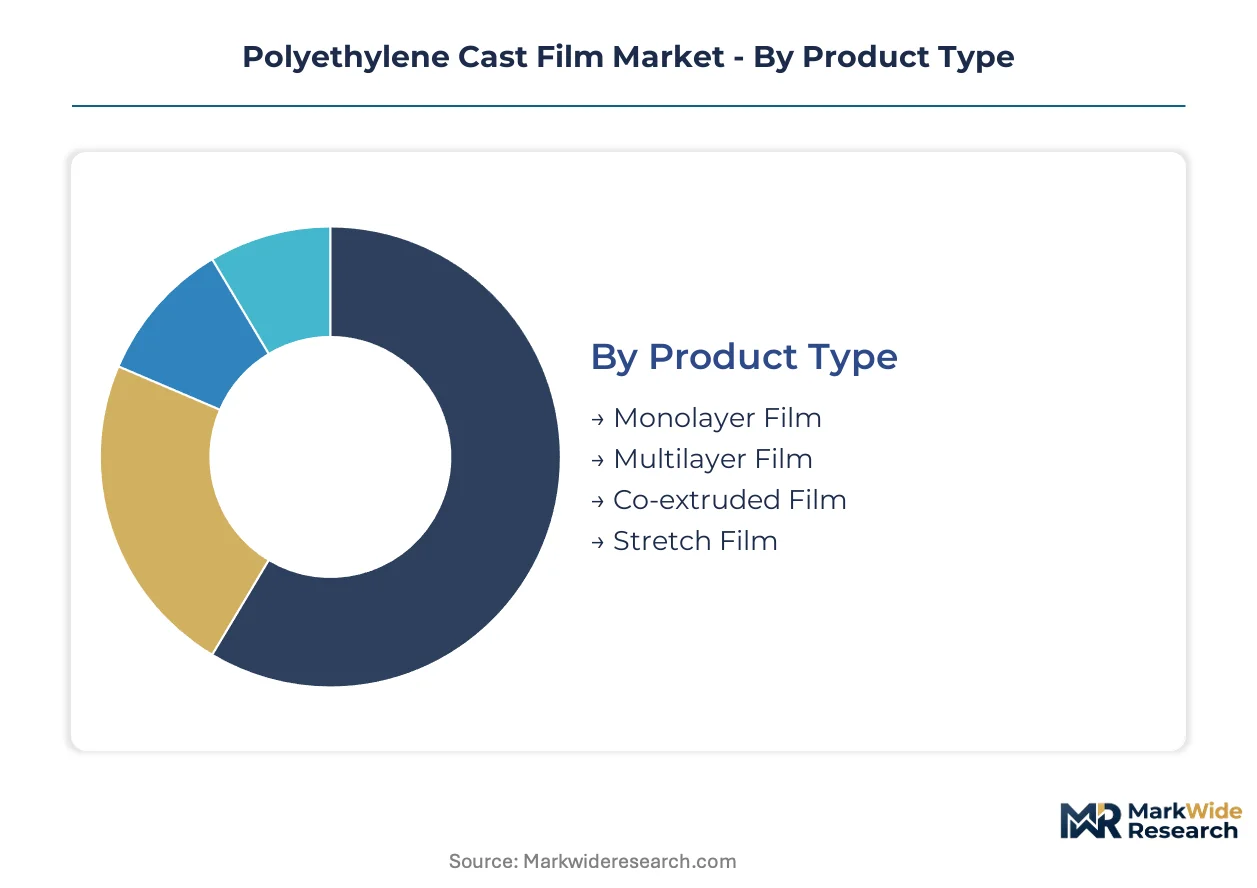
Polyethylene cast film segmentation reflects divergent margin pools across barrier complexity, end-use compliance burdens, and gauge engineering. Product architecture and thickness specifications determine resin selection and line configuration, while manufacturing process choice locks in optical clarity and barrier performance ceilings.
Product Type:
Cost tier stratification separates commodity monolayer supply from engineered multilayer configurations where oxygen transmission specifications command premium positioning.
- Monolayer Film:Single-resin extrusion delivers basic moisture protection and seal integrity for non-perishable goods. Demand concentrates in Vietnam's rice and grain export sector where cost minimization outweighs barrier requirements.
- Multilayer Film:Coextruded structures combine polyethylene with EVOH or polyamide layers to achieve oxygen transmission rates below 1 cc/m²/day. Japanese seafood importers mandate these specifications for sashimi-grade tuna shipments from Indonesian processors.
- Co-extruded Film:Simultaneous extrusion of multiple resins through a single die achieves layer adhesion without lamination steps. European medical sterilization pouch producers favor this architecture for ISO 11607 compliance.
- Stretch Film:Linear low-density polyethylene formulations with high tear resistance serve automated pallet-wrapping systems. German distribution centers specify metallocene grades for 250% stretch ratios at sub-12-micron gauges.
Multilayer Film holds installed capacity. Co-extruded Film is rotating up the share rankings.
End Use Industry:
Application-specific compliance burdens fragment formulation strategies across migration limits, sterilization validation, and load containment engineering.
- Food Packaging:Direct-contact films face FDA and EU REACH migration ceilings for additives and plasticizers. Vietnamese converters are scaling multilayer capacity to capture ASEAN seafood export demand.
- Medical Applications:Sterilization-grade films require validated ethylene oxide and gamma radiation compatibility. EU F-Gas Regulation deadlines are forcing fluorinated barrier substitution in pouch formats.
- Consumer Goods:Optical clarity and printability specifications govern overwrap applications for electronics and cosmetics. South Korean brand owners specify low-haze cast film for premium display packaging.
- Industrial Packaging:Unitization films prioritize puncture resistance and cling balance over barrier performance. US Gulf Coast petrochemical exporters drive volume through automated stretch-wrapping lines.
Food Packaging anchors volume demand. Medical Applications is climbing the fastest as regulatory substitution accelerates.
Thickness:
Volume stratification by gauge reflects downgauging pressure from brand-led reduction commitments against technical floors for mechanical integrity.
- Below 25 Microns:Ultra-thin gauges serve lightweight produce overwrap and secondary packaging. French supermarket technical teams now specify sub-20-micron targets directly in quarterly tenders.
- 25-50 Microns:Mid-range gauges balance barrier performance with material efficiency for modified-atmosphere protein packaging. Indonesian poultry processors are standardizing on 35-micron multilayer structures.
- 51-75 Microns:Heavy-duty specifications serve industrial bundling and medical device sterilization pouches requiring puncture resistance. German mechanical recycling facilities face sortation challenges with this gauge range.
- Above 75 Microns:Specialty gauges serve construction vapor barriers and agricultural greenhouse films. Saudi Arabian agribusiness operators specify UV-stabilized 150-micron grades for desert climate durability.
25-50 Microns holds installed capacity. Below 25 Microns is rotating up the share rankings.
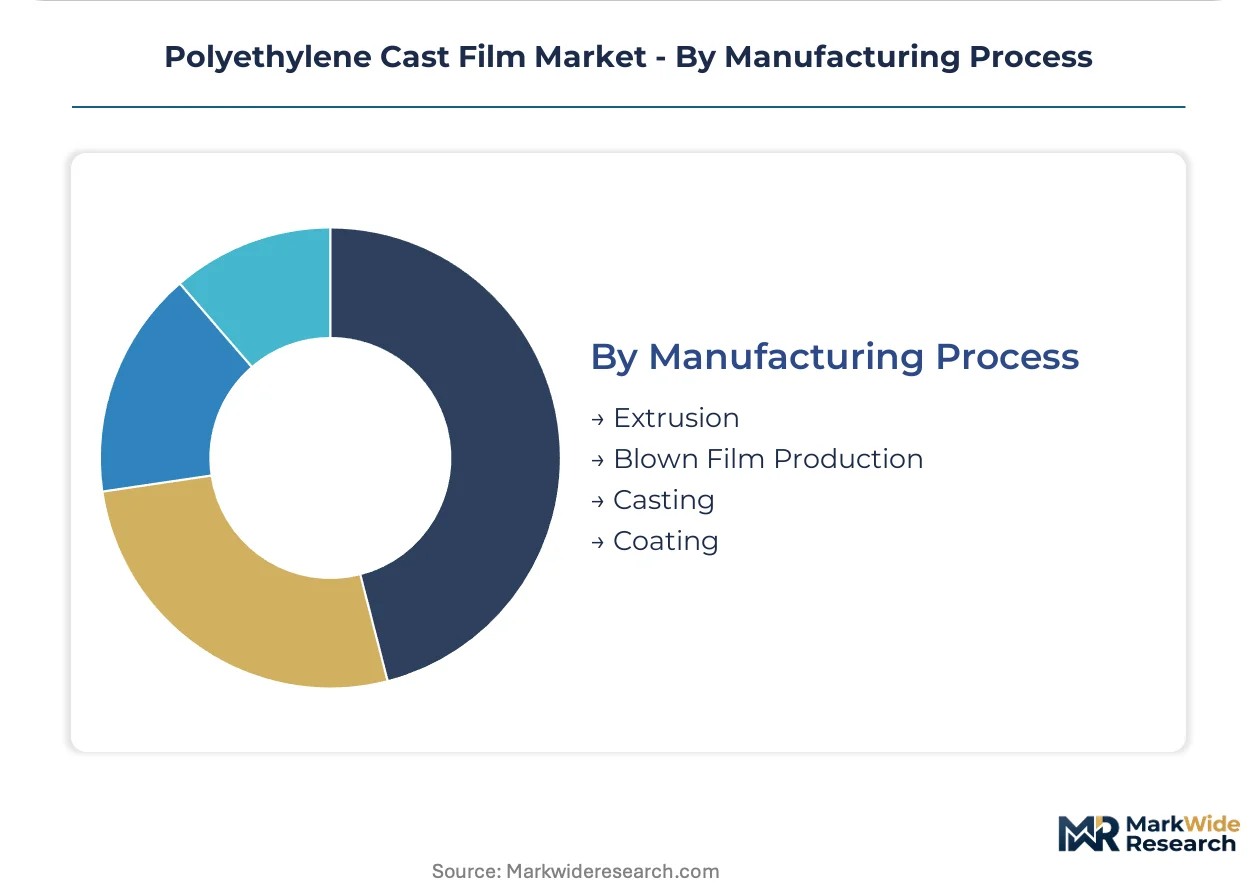
Manufacturing Process:
Process selection determines optical clarity, gauge uniformity, and barrier layer precision available to downstream converters.
- Extrusion:Flat-die cast extrusion delivers superior optical properties and thickness tolerance for food-contact applications. Dutch film producers leverage this platform for ISCC PLUS-certified circular-content supply.
- Blown Film Production:Bubble extrusion achieves biaxial orientation and higher toughness at equivalent gauges. Jindal Poly Films anchors South Asian supply through specialized blown and cast hybrid lines.
- Casting:Chill-roll solidification produces the gauge uniformity required for metallization and high-barrier lamination. Japanese equipment suppliers dominate nine-layer die configurations for this process.
- Coating:Surface deposition of barrier coatings enables functional enhancement without full coextrusion retrofit. Active packaging developers in the Netherlands apply oxygen scavenger coatings to standard cast substrates.
Extrusion holds installed capacity. Casting is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact regulations in the United States shape migration limits that cascade through export supply chains. REACH compliance in Europe and ASEAN food export protocols create divergent specification pressures across major converting clusters.
United States
Automated distribution centers in Illinois and Texas drive metallocene LLDPE specifications for high-speed pallet wrapping. FDA maintains strict additive migration ceilings for films contacting ready-to-eat proteins. Gulf Coast petrochemical corridors supply resin to independent extruders facing ethane price volatility.
Germany
Mechanical recycling facilities in North Rhine-Westphalia create offtake certainty for post-industrial film scrap. EU F-Gas Regulation deadlines force fluorinated barrier substitution in medical sterilization pouches. Dutch-German border clusters specialize in ISCC PLUS-certified circular-content supply.
Vietnam
Seafood exporters in Ho Chi Minh City and Da Nang mandate multilayer oxygen-barrier films for sashimi-grade tuna shipments to Japan. ASEAN protocols require extended shelf-life packaging for fresh produce exports. Converting capacity expansions in Binh Duong province target regional food processing growth.
Indonesia
Poultry processors in Java standardize on 35-micron multilayer structures for modified-atmosphere packaging. Domestic converting capacity lags behind food processing expansion, creating equipment investment opportunities. Batam and Surabaya industrial zones attract cast film line installations for export market access.
Japan
Equipment suppliers in Nagoya and Osaka dominate nine-layer die configurations for high-barrier cast film production. Importers mandate oxygen transmission specifications below 1 cc/m²/day for premium seafood shipments. Technical partnerships with Southeast Asian converters accelerate technology transfer for multilayer coextrusion.
Polyethylene Cast Film Market Vendor Landscape
Integrated multinational suppliers and regional specialists split the market between premium barrier specifications and commodity volume segments. The vendor base concentrates around three strategic archetypes: resin-integrated film producers, independent converters with equipment scale, and specialized barrier technology developers. M&A activity targets geographic whitespace in Southeast Asia, while capacity expansion focuses on multilayer coextrusion lines for food-contact applications.
Among integrated packaging suppliers, Amcor PLC exemplifies the global footprint archetype with integrated operations spanning resin procurement through converter relationships. Jindal Poly Films anchors South Asian supply through specialized film line configurations serving regional snack and dairy brands. Sigma Plastics Group occupies a position within the North American scale-driven tier, competing through dedicated cast film operations for industrial applications.
| Leading Market Players |
|---|
| Amcor PLC |
| SABIC Innovative Plastics |
| Inteplast Group |
| Taghleef Industries |
| Jindal Poly Films |
| Sigma Plastics Group |
| Novolex Holdings |
| Copol International |
| Berry Global Group |
| Others |
Supply Flow & Price Mechanics
Saudi Aramco, SABIC, and Dow control roughly half of global LLDPE capacity, concentrating resin pricing power upstream while margin pools accumulate downstream in multilayer coextrusion and ISCC PLUS-certified circular-content supply. This upstream oligopoly transmits cost volatility through to independent converters, forcing differentiation through barrier technology rather than commodity scale.
Pricing Analysis
US Gulf Coast ethane-based resin trades at persistent discounts to European naphtha-derived material, creating arbitrage windows that independent extruders exploit. Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS-certified circular-content film from conventional multilayer grades and commodity monolayer supply. Cost compression in standard-tier stretch film is intensifying because metallocene resin adoption extends roll footage while collapsing per-unit revenue. Vietnamese rice exporters exhibit highest price sensitivity, while Japanese seafood importers accept premium positioning for oxygen-barrier specifications below 1 cc/m²/day.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for Southeast Asian converters purchasing European nine-layer die equipment, stretching working capital requirements. Raw material supply concentrates in Saudi Arabia, the United States, and China for ethylene feedstock, with South Korea and Japan dominating specialized metallocene catalyst systems. Single-source vulnerability runs through catalyst supply, where limited qualified producers constrain formulation flexibility. Distribution runs through converter relationships in Vietnam and Indonesia, with direct technical specification increasingly managed by supermarket procurement teams in France and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and ISCC PLUS certification support are expanding faster than base film supply, creating recurring-revenue layers that offset commodity margin erosion. After-sales polymer rheology consulting and validation documentation for BRCGS Packaging compliance represent attach opportunities with 3-5 year contract structures.
For Market Incumbents: Pre-empt fluorinated barrier substitution deadlines by accelerating EVOH and polyamide coextrusion capacity in European medical sterilization corridors. Backward integration into post-industrial scrap collection in Germany and the Netherlands secures circular-content feedstock for ISCC PLUS-certified supply. Capacity addition in Binh Duong province captures Vietnamese seafood export growth before regional competitors establish local slitting operations. For New Entrants and Emerging Players: Build out Philippines converting capacity where domestic flexible packaging supply lags behind food processing expansion. First-mover advantage exists in local metallization and multilayer slitting operations serving Manila-based processors. Go-to-market through direct technical partnerships with Japanese equipment suppliers accelerates nine-layer die commissioning timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed North American industrial stretch film specialists facing metallocene-driven margin compression. Long-term viability hinges on circular-content certification and active packaging technology integration. Watch for EU Packaging and Packaging Waste Regulation recycled-content enforcement timelines as inflection indicators for mass-balance premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Industrial Scrap Collection | ISCC PLUS certification in Germany and the Netherlands secures circular-content feedstock premiums for EU compliance. |
| Multilayer Coextrusion Capacity Expansion | Nine-layer die installations in Vietnam and Indonesia capture ASEAN seafood export specification mandates. |
| Active Packaging Technology Licensing | Oxygen scavenger integration opens medical device segments previously served by rigid barrier formats. |
| Long-term Supply Agreement with Metallocene Resin Producers | Captive LLDPE supply from South Korean catalyst specialists insulates against force majeure procurement risk. |
| Joint Venture with Japanese Equipment Suppliers | Technology transfer partnerships accelerate multilayer coextrusion expertise development in emerging-market workforces. |
Methodological Framework
A spread of perspectives from extrusion plant managers, polymer procurement leads at downstream converters, distribution channel partners, and technical R&D directors converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and FDA food-contact regulation updates. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the polyethylene cast film value chain.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by product architecture, end-use compliance burden, thickness specification, and manufacturing process. CAGRs derived from installed capacity utilization rates, trade flow analysis, and substitution elasticity between monolayer and multilayer configurations. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules and ASEAN food export protocol evolution.
Stress conditions across ethylene feedstock price spreads, force majeure frequency at major resin producers, and mechanical recycling infrastructure build-out timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology transfer velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
EVOH Encapsulation Film Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Hexacomb Packaging Market
Poly film
Polyethylene Furanoate Films Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Printed Plastic Films Market
Poly film
Global Blown Stretch Packaging Films Market
Poly film
LDPE Films Market
Poly film
US Cleanroom Film and Bags Market
Poly film
Polyimide Films and Tapes Market
Poly film
Biaxially Oriented Polyamide (BOPA) Films Market
Poly film
Polylaminate Capsules Market
Poly film
North America Plastic Film Packaging Market
Poly film
Germany Plastic Packaging Films Market
Poly film
Polyester Film Market