
 Lidding Films Market | 2026-2036
Lidding Films Market Size, Share, and Industry Trends Forecast 2026-2036
Lidding Films Market Outlook
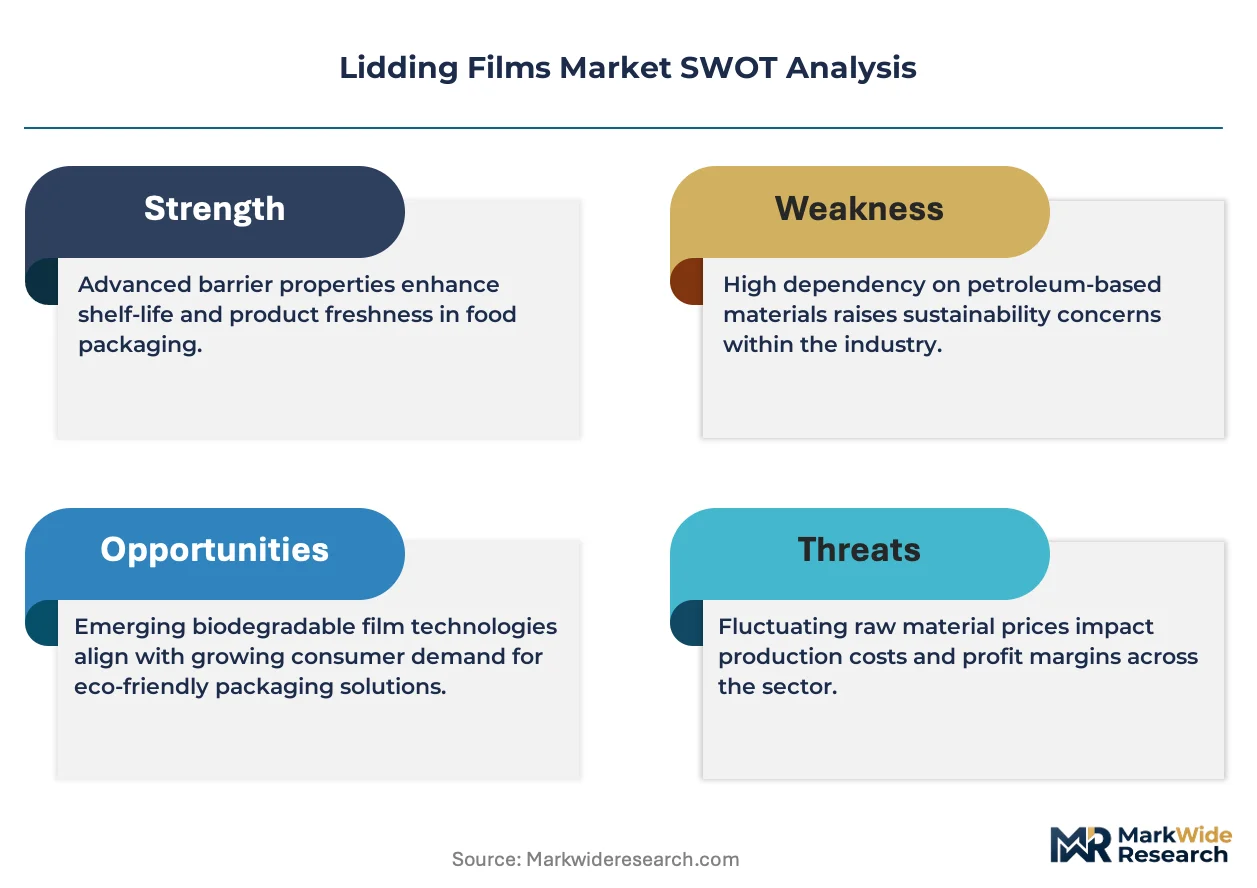
Modular lidding configurations that pair peelable films with resealable closures is restructuring how food processors specify packaging systems. Amcor Limited leverages its integrated film-to-tray platform to anchor large-format dairy contracts across Northern Europe. Constantia Flexibles Group GmbH sustains leadership in pharmaceutical lidding through specialized barrier certifications and cleanroom manufacturing scale. Sealed Air Corporation differentiates via controlled-atmosphere lidding systems for premium protein segments.
Lidding films are multilayer polymer structures, typically 25–150 micrometers thick, engineered to seal rigid or semi-rigid trays while permitting controlled peel, reseal, or high-barrier performance against oxygen and moisture ingress. Their primary purpose is to extend product shelf life, maintain organoleptic quality, and enable consumer convenience in packaged goods distribution. Peelable films dominate food service applications where easy-open functionality commands premium positioning, while barrier films concentrate margin pools in pharmaceutical blister packs where moisture vapor transmission rates below 0.1 g/m²/day are mandatory. Resealable films represent the fastest-growing configuration as snack and prepared-meal brands seek to replace secondary overwrap with integrated closure systems.
FDA food contact substance notifications govern material composition for US-bound lidding, while EU REACH and F-Gas Regulation restrict certain fluorinated barrier chemistries and mandate recyclability disclosures across European supply chains. These frameworks compel converters to reformulate seal layers and validate alternative barrier technologies ahead of compliance deadlines. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to invest in mono-material lidding platforms or maintain multilayer expertise with advanced sorting-compatible designs.
Market Dynamics
Europe's F-Gas Regulation is forcing converters to abandon fluorinated barrier chemistries before phase-down deadlines, triggering wholesale reformulation of multilayer seal structures and certification protocols across Central European packaging clusters.
Growth Catalysts
- Fresh food tray packaging:Retailers in Germany's food processing corridor specify extended shelf-life lidding to reduce spoilage in Central European distribution networks. This specification pull concentrates converter investment in high-barrier peelable configurations.
- EU Green Deal packaging mandates:Extended producer responsibility schemes in France and Italy now require recyclability disclosures, accelerating adoption of mono-material lidding platforms with compatible sorting infrastructure.
- Resealable closure integration:Snack and prepared-meal brands replace secondary overwrap with integrated closure systems, expanding addressable film surface area per retail unit.
Market Restraints
- Ethylene-vinyl alcohol supply concentration:High-barrier EVOH resin production clusters in Northeast Asia create input cost volatility and security-of-supply exposure for European converters.
- Multilayer incompatibility with mechanical recycling:Current barrier film architectures face technical limitations in achieving food-grade recycled content thresholds under EU Single-Use Plastics Directive implementation timelines.
- F-Gas regulatory friction:REACH restrictions on perfluorinated compounds eliminate proven ultra-low moisture vapor transmission chemistries before drop-in alternatives achieve equivalent performance validation.
Strategic Opportunities
- Pharmaceutical blister expansion:Moisture vapor transmission rates below 0.1 g/m²/day remain underpenetrated in Central and Eastern European generic drug packaging, creating specification windows for certified cleanroom producers.
- Controlled-atmosphere protein packaging:Premium meat and seafood segments in the Netherlands and Belgium adopt modified atmosphere lidding systems that integrate gas-scavenging layers with resealable functionality.
- Digital printing convergence:Variable-data print technologies enable lot-traceable, short-run lidding production for artisanal dairy and specialty food brands seeking regional differentiation.
Industry Challenges
- Barrier certification timeline compression:EFSA novel food contact substance approvals for bio-based seal layers now require 18-24 month validation cycles that misalign with F-Gas phase-down deadlines.
- Mono-material platform capex intensity:Retooling extrusion and metallization lines for polypropylene-dominant lidding architectures demands capital allocation that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidding Films Market |
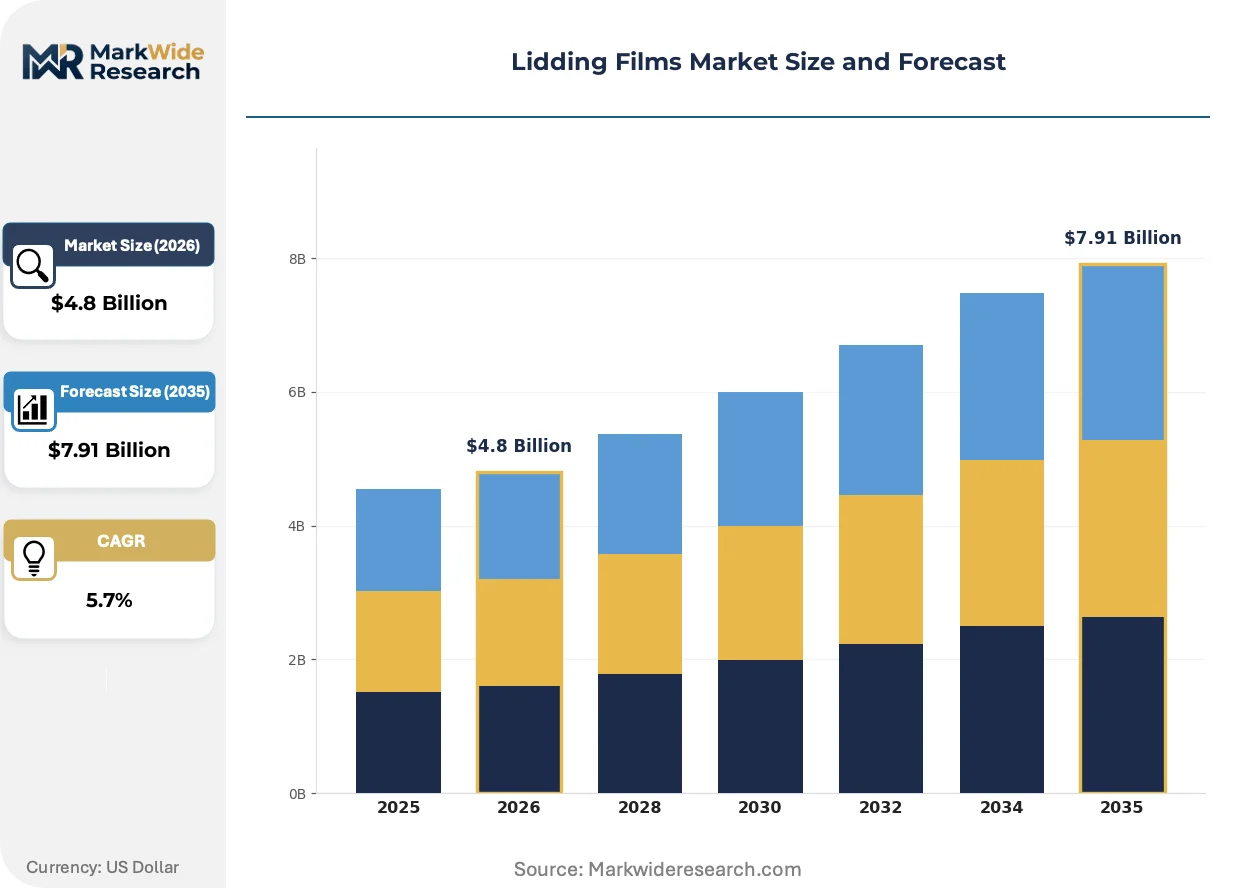
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peelable Films, Resealable Films, Rigid Films, Barrier Films Material: Polypropylene, Polyethylene, PVC, PET Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Electronic Packaging Technology: Flexographic Printing, Gravure Printing, Digital Printing, Coating Technology |
| Companies Covered | Sealed Air Corporation, Constantia Flexibles Group GmbH, Amcor Limited, Winpak Ltd., Uflex Limited, Mondi plc, Huhtamäki Oyj, ProAmpac LLC, Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidding Films Market Strategic Shifts
Active packaging functionalities are migrating from separate sachets and pads into lidding film structures, collapsing unit cost and simplifying line integration for food processors. This structural integration is reshaping converter R&D priorities and equipment supplier roadmaps simultaneously.
Barrier coating technology is converging with atomic layer deposition processes to achieve sub-micrometer inorganic oxide layers on polymer substrates. Pharmaceutical blister pack manufacturers in Switzerland and Germany adopt these films to replace aluminum foil while maintaining EMA-compliant moisture protection. The convergence is compressing material thickness requirements and enabling thermoformable lid-stock configurations previously impossible with metalized structures.
REACH authorization procedures for chromium-based packaging additives now restrict certain anti-fog and anti-static surface treatments used in fresh produce lidding. Converters serving French retail chains must validate silicone and bio-based alternatives before sunset date enforcement. The dairy segment faces the steepest compliance curve due to stringent organoleptic neutrality requirements for direct food contact layers.
Consolidated retail procurement in Northern Europe now specifies lidding films through integrated tray-and-lid platform contracts rather than discrete component sourcing. This purchasing pattern displaces spot-market film transactions and locks converters into multi-year supply agreements with volume-commitment clauses. The shift is most visible in German discount retail channels where private-label prepared meals command shelf space allocation decisions.
Lidding Films Market Segmentation
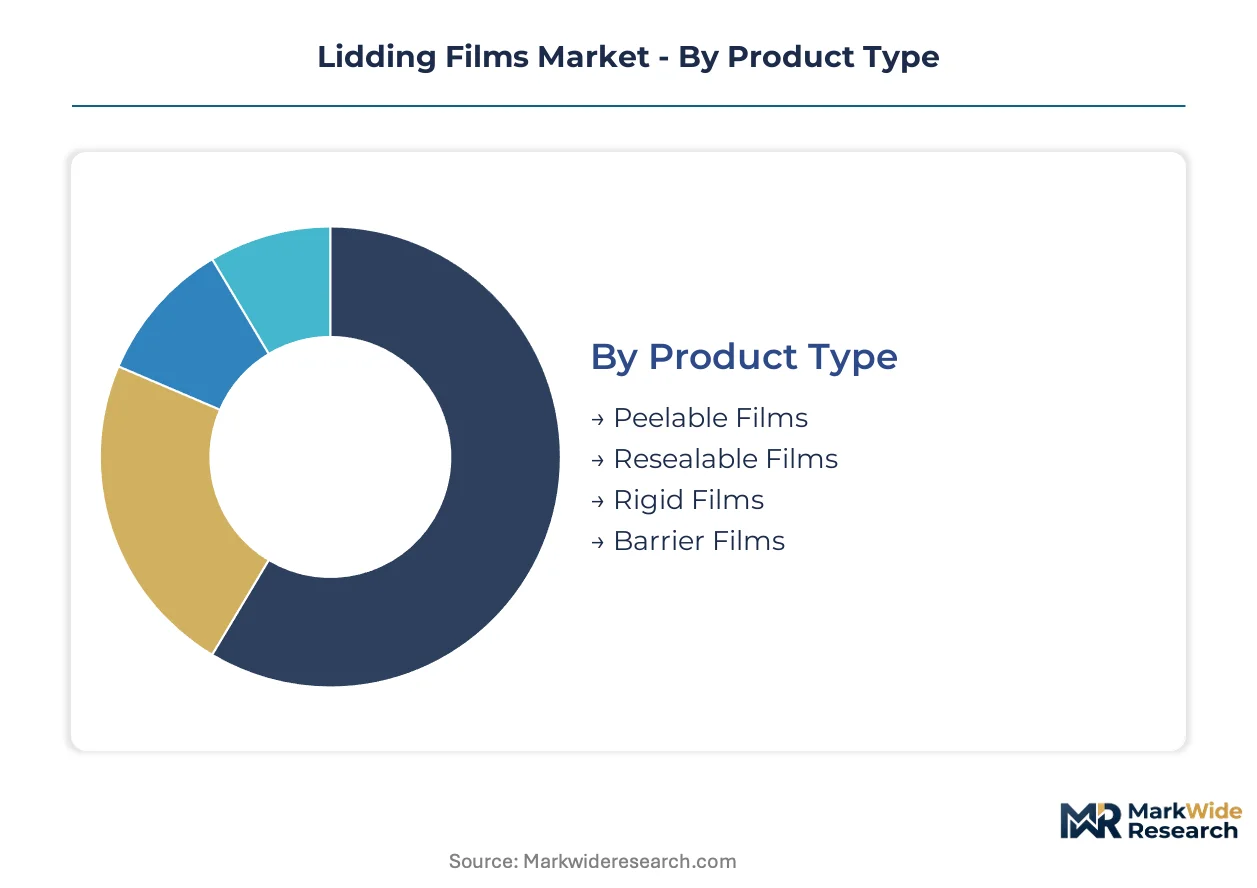
Lidding films serve divergent performance requirements across food safety, pharmaceutical integrity, and consumer convenience. Segmentation reveals where margin pools concentrate versus where volume commoditization pressures converter economics.
Product Type:
Peelable films command premium positioning through easy-open functionality, while barrier films extract value from ultra-low moisture transmission specifications. Resealable configurations are climbing fastest as brands eliminate secondary packaging.
- Peelable Films:Multilayer coextrusions with controlled delamination interfaces enable clean tray separation without tool assistance. German dairy processors specify these for fresh cheese formats distributed through discount retail channels where consumer convenience drives repeat purchase.
- Resealable Films:Integrated pressure-sensitive adhesive layers or zipper-profile welds replace separate clip closures. Snack brands in the Netherlands and Belgium adopt these for nut and dried fruit formats, expanding film surface area per unit while reducing plastic mass.
- Rigid Films:Thermoformable lid-stock with structural rigidity for shallow-draw applications. Pharmaceutical blister packs in Switzerland use these for unit-dose medications requiring child-resistant functionality.
- Barrier Films:EVOH or aluminum oxide-coated structures achieving oxygen transmission below 1 cc/m²/day. Central European meat processors specify these for modified atmosphere tray systems extending retail case life.
Today's leader: Peelable Films. Tomorrow's challenger: Resealable Films.
Material:
Polypropylene dominates fresh food applications through thermal stability and seal strength, while PET anchors pharmaceutical clarity requirements. Polyethylene serves cost-sensitive formats where barrier demands moderate.
- Polypropylene:Biaxially oriented and cast grades provide broad sealing windows and chemical resistance. France's extended producer responsibility schemes now mandate mono-material PP lidding for recyclability compliance in prepared meal trays.
- Polyethylene:Linear low-density variants offer puncture resistance for protein packaging with bone-in contact. Italian cured meat processors favor these for export formats requiring cold-chain flexibility.
- PVC:Declining share in food contact due to ECHA scrutiny of plasticizer migration, though pharmaceutical blister packs retain limited use where EMA has granted specific authorization.
- PET:Amorphous grades provide optical clarity for pharmaceutical visibility requirements. German generic drug manufacturers specify PET lid-stock for moisture-sensitive tablet formats.
Polypropylene holds current volume leadership. Polyethylene is gaining fastest in protein segment conversions.
Application:
Food packaging generates absolute volume throughput, while pharmaceutical applications sustain margin premiums through certification barriers. Cosmetic and electronic segments remain specialty niches with concentrated converter participation.
- Food Packaging:Tray lidding for fresh produce, dairy, and prepared meals constitutes the demand core. Retail consolidation in Northern Europe now specifies integrated tray-and-lid platforms rather than discrete component procurement.
- Pharmaceutical Packaging:Blister lidding with moisture vapor transmission below 0.1 g/m²/day protects hygroscopic APIs. Cleanroom manufacturing certifications in Germany and Switzerland limit qualified supplier pools.
- Cosmetic Packaging:Peelable films for single-use mask sachets and sample formats. French luxury brands specify these for premium positioning in travel retail channels.
- Electronic Packaging:Anti-static lidding for component trays in semiconductor distribution. Swiss precision manufacturing clusters generate concentrated specification demand.
Food Packaging anchors volume scale. Pharmaceutical Packaging sustains margin extraction through regulatory moats.
Technology:
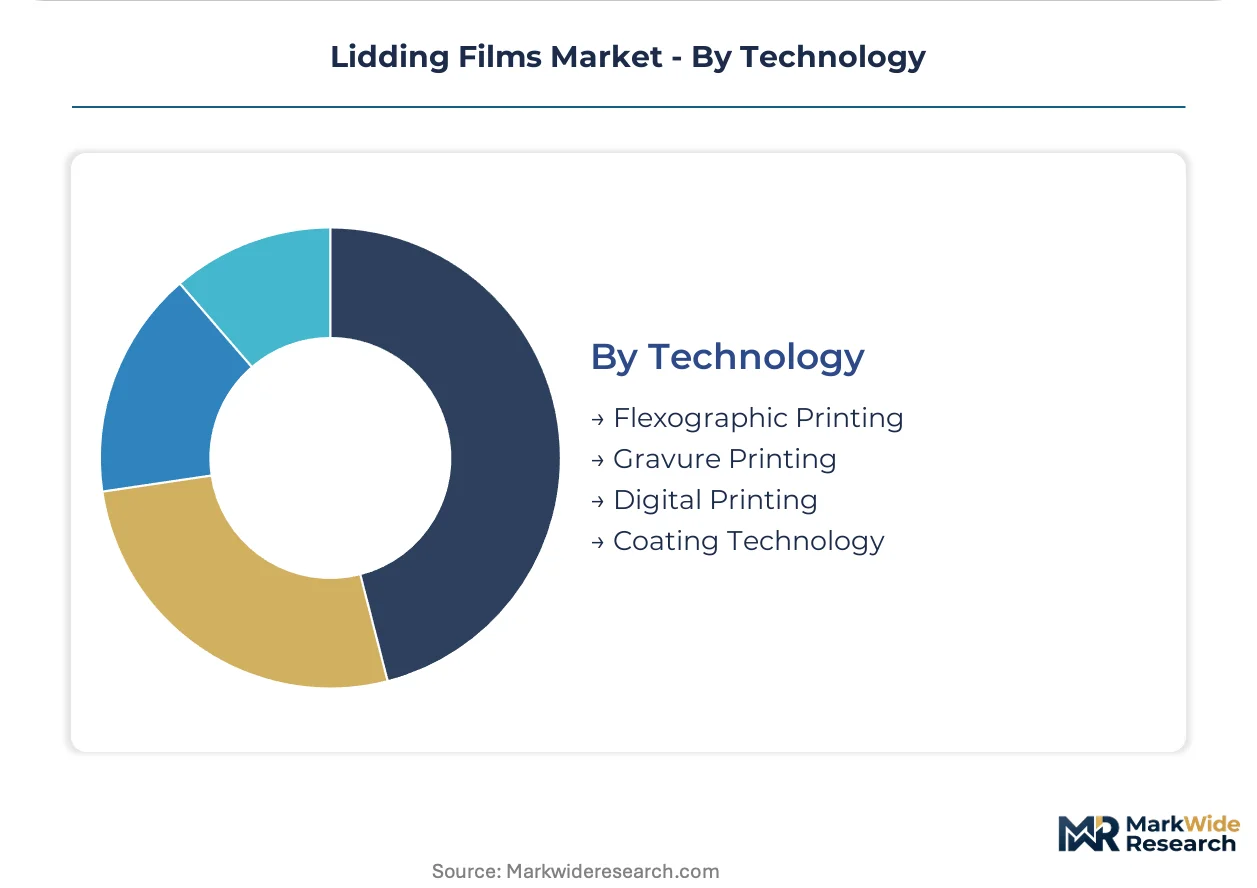
Gravure printing retains long-run efficiency for branded food applications, while digital printing enables lot-traceable short runs for artisanal producers. Coating technology underpins barrier performance differentiation.
- Flexographic Printing:Water-based ink systems serve high-volume dairy and produce segments where food contact compliance and line speed converge. Central European converters dominate this equipment base.
- Gravure Printing:Cell-based engraving achieves precise tonal reproduction for premium meat and seafood branding. German packaging clusters maintain gravure capacity for retail private-label contracts.
- Digital Printing:Inkjet and toner systems enable variable data including lot codes and regional language variants. Belgian specialty cheese producers adopt these for export formats with fragmented destination requirements.
- Coating Technology:Atomic layer deposition and plasma-enhanced chemical vapor deposition create sub-micrometer oxide barriers. Swiss pharmaceutical packagers specify these for aluminum replacement in thermoformable configurations.
Gravure Printing commands long-run economics. Digital Printing is expanding most quickly in regional brand portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lidding films production originated in post-war Germany's chemical corridor, where multilayer extrusion technology first scaled for dairy packaging. Industrial clusters in the Rhine-Ruhr and Upper Bavaria regions subsequently anchored European converter capacity.
Germany
Fresh cheese processors in Bavaria's dairy belt specify peelable lidding for discount retail distribution. EFSA novel food contact substance approvals now govern reformulation timelines for bio-based seal layers. Munich-based packaging clusters serve as specification gatekeepers for Central European meat and prepared meal contracts.
United States
FDA food contact substance notifications drive material composition standards for export-bound lidding films. Modified atmosphere protein packaging in the Midwest meatpacking corridor demands high-barrier configurations. Chicago-area converters supply dairy and snack brands across the Great Lakes distribution network.
Switzerland
Pharmaceutical blister manufacturers in Basel's life sciences cluster specify moisture vapor transmission rates below 0.1 g/m²/day. Swissmedic certifications limit qualified supplier pools for unit-dose medications. Atomic layer deposition adoption concentrates in Zurich-region cleanroom facilities replacing aluminum foil.
Netherlands
Controlled-atmosphere lidding for premium seafood exports drives specification complexity in Rotterdam's food processing corridor. EU Green Deal packaging mandates accelerate mono-material platform adoption. Wageningen-area research institutes validate alternative barrier coatings for circular economy compliance.
France
Extended producer responsibility schemes in Île-de-France now mandate recyclability disclosures for prepared meal trays. ANSM restrictions on chromium-based additives force anti-fog treatment reformulation. Lyon-based converters supply luxury cosmetic brands with peelable sachet formats for travel retail.
Lidding Films Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier certification and cleanroom manufacturing dimensions. The vendor base stratifies into three tiers: integrated film-to-tray platforms, specialized pharmaceutical barrier producers, and regional converters serving spot-market food contracts. Strategic archetypes include certification-anchored specialists, scale-driven integrated platforms, and agile short-run digital printers. Competitive moves concentrate on mono-material platform investments and pharmaceutical cleanroom capacity expansion.
Among integrated packaging platforms, Amcor Limited and Sealed Air Corporation exemplify scale-driven archetypes with film-to-tray system capabilities. Constantia Flexibles Group GmbH represents the certification-anchored specialist model, occupying a position within pharmaceutical barrier segments where cleanroom manufacturing requirements limit qualified competition. These three entities anchor the competitive structure across premium-margin and high-volume contract tiers.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Constantia Flexibles Group GmbH |
| Amcor Limited |
| Winpak Ltd. |
| Uflex Limited |
| Mondi plc |
| Huhtamäki Oyj |
| ProAmpac LLC |
| Berry Global Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between pharmaceutical barrier films and commodity food-service lidding creates parallel pricing architectures that reshape procurement patterns across European converter networks. Buyers in Germany's dairy corridor negotiate spot-market polyethylene pricing while Swiss pharmaceutical packagers lock in multi-year contracts for EVOH-based barrier specifications, fragmenting supplier relationships and inventory strategies.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs converter-customer relationships, with pharmaceutical cleanroom certifications and F-Gas-compliant barrier formulations commanding substantial premiums over food-grade alternatives. Price differentiation hinges on moisture vapor transmission certification tiers and volume commitment scale, with annual offtake contracts securing favorable terms. Cost compression in standard-grade polyethylene lidding is intensifying because EVOH resin supply concentration in Northeast Asia feeds input volatility. Discount retailers in Germany's food processing corridor exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers prioritize performance validation over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany's Rhine-Ruhr corridor and Upper Bavaria form hub-and-spoke patterns serving Central European food processing clusters, with satellite facilities in the Netherlands and Belgium supporting controlled-atmosphere protein packaging demand. Raw material sourcing draws from Saudi ethylene feedstock, Japanese biaxial orientation equipment, and Korean metallization technology, creating multi-continental dependencies. Single-source vulnerability concentrates in EVOH resin supply, where three Northeast Asian producers control global capacity. Distribution runs through integrated film-to-tray platform contracts rather than spot-market transactions, locking converters into volume-commitment structures with Northern European retail consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as retailer procurement shifts toward integrated tray-and-lid platforms with extended shelf-life specifications, favoring converters with certification depth and mono-material platform readiness.
For Market Incumbents: Anticipate margin compression in standard-grade polyethylene lidding as EVOH supply volatility transmits downstream, and prioritize backward integration into cast polypropylene extrusion to secure mono-material platform positioning ahead of EU Green Deal enforcement. Certification investment in EFSA novel food contact substance approvals offers defensive moats against mid-scale competitors lacking 18-24 month validation timelines.
For New Entrants and Emerging Players: Begin with digital printing capabilities serving Belgian and Dutch artisanal dairy brands requiring short-run, lot-traceable lidding for fragmented export markets, where gravure-dominated incumbents lack operational agility. Target controlled-atmosphere protein packaging in the Netherlands as the most penetrable premium segment, leveraging Wageningen-area research partnerships for barrier coating validation.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale converters struggle to finance mono-material platform capex demands, creating acquisition opportunities for specialists with cleanroom manufacturing scale and pharmaceutical barrier certifications. Long-term viability favors integrated film-to-tray platforms with backward extrusion control. Watch F-Gas phase-down deadline adherence as the critical inflection signal separating compliant converters from stranded asset risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Investment | Retooling extrusion lines for polypropylene-dominant architectures satisfies France's extended producer responsibility mandates. |
| Pharmaceutical Cleanroom Expansion | Swissmedic-certified capacity captures generic drug blister demand in Central and Eastern Europe. |
| Atomic Layer Deposition Adoption | Sub-micrometer oxide barriers enable aluminum replacement in thermoformable pharmaceutical lid-stock. |
| Digital Printing Capability Buildout | Variable-data production serves Belgian specialty cheese exporters with fragmented destination requirements. |
| Backward Integration into Seal Layer Production | In-house coextrusion of bio-based formulations reduces EFSA approval timeline exposure for German dairy contracts. |
Study Parameters
Coverage spans Germany, Switzerland, the Netherlands, France, and the United States, with primary inputs from each region's packaging converter clusters, food processor procurement directors, pharmaceutical packaging engineers, and regulatory affairs specialists at EFSA and FDA. Secondary validation draws from EU F-Gas Regulation implementation documents, REACH authorization databases, FDA food contact substance notifications, and trade association filings from Cefic and Flexible Packaging Europe. Bottom-up volume modeling triangulates against top-down value estimates from converter capacity assessments and retail procurement pattern analysis.
Granularity-level framing applies product type, material composition, application segment, and technology platform as core segmentation dimensions, with regional regulatory cluster and certification tier as cross-cutting variables. CAGRs derive from annualized progression rates applied across the projection horizon, calibrated to EVOH resin supply elasticity and mono-material platform adoption curves. Industry-specific inputs include F-Gas phase-down compliance timelines, EFSA novel food contact substance approval backlogs, and integrated retail procurement contract tenors.
Several conditions sit outside the modeled scope, including sudden EVOH supply disruptions from Northeast Asian production facilities, accelerated F-Gas enforcement beyond published deadlines, and breakthrough barrier coating technologies achieving commercial scale ahead of validation timelines. Forecasts reflect stated assumptions regarding regulatory adherence and substitution technology readiness. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
EVOH Encapsulation Film Market
Poly film
Bopet Films Market
Poly film
Middle East and Africa Plastic Packaging Films Market
Poly film
Chocolate Wrapping Films Market
Poly film
UAE Plastic Packaging Films Market
Poly film
Bi-Axially Oriented Polypropylene (BOPP) Market
Poly film
Twist Wrap Film Market
Poly film
France Plastic Packaging Films Market
Poly film
PE Foam Films Market
Poly film
Bio-PET Film Market
Poly film
Packaging Film Market
Poly film
Global Polyethylene Packaging Market
Poly film
United States Polycarbonate Sheets and Films Market
Poly film
PP Laminating Films Market
Poly film
Polyethylene Furanoate Films Market
Poly film
North America BOPP Films Market