
 Global Automotive Luggage Trim Market | 2026-2036
Global Automotive Luggage Trim Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Luggage Trim Market Intelligence
The European Union's Green Deal, with its emphasis on circular economy principles for automotive components, is repositioning material selection criteria for luggage trim. Faurecia specializes in developing lightweight composite materials to meet these new sustainability targets. Adient PLC leverages its extensive manufacturing footprint to supply large OEM programs with standardized trim components. Autoneum Holding Ltd. differentiates through its expertise in acoustic-dampening fabric molded products for the premium vehicle segment.
Automotive luggage trim includes components designed to finish and protect vehicle cargo areas, manufactured via processes like injection molding. Their primary functions are to provide an aesthetic surface, protect against wear, and dampen noise. Plastic molded products lead the market in volume, while composite materials are gaining share in electric vehicles due to weight reduction benefits. OEM manufacturers represent the dominant end-user channel, setting strict performance and cost specifications for trunk edge protection and load floor covers.
Regulations like the US EPA's standards on volatile organic compounds and China's GB standards for vehicle interior air quality directly impact material chemistry. These rules, alongside the EU's End-of-Life Vehicles Directive, force suppliers to innovate in low-emission and recyclable materials. Supplier success hinges on balancing cost-effective production with the development of lightweight, sustainable solutions that meet diverse OEM platform requirements.
Market Dynamics
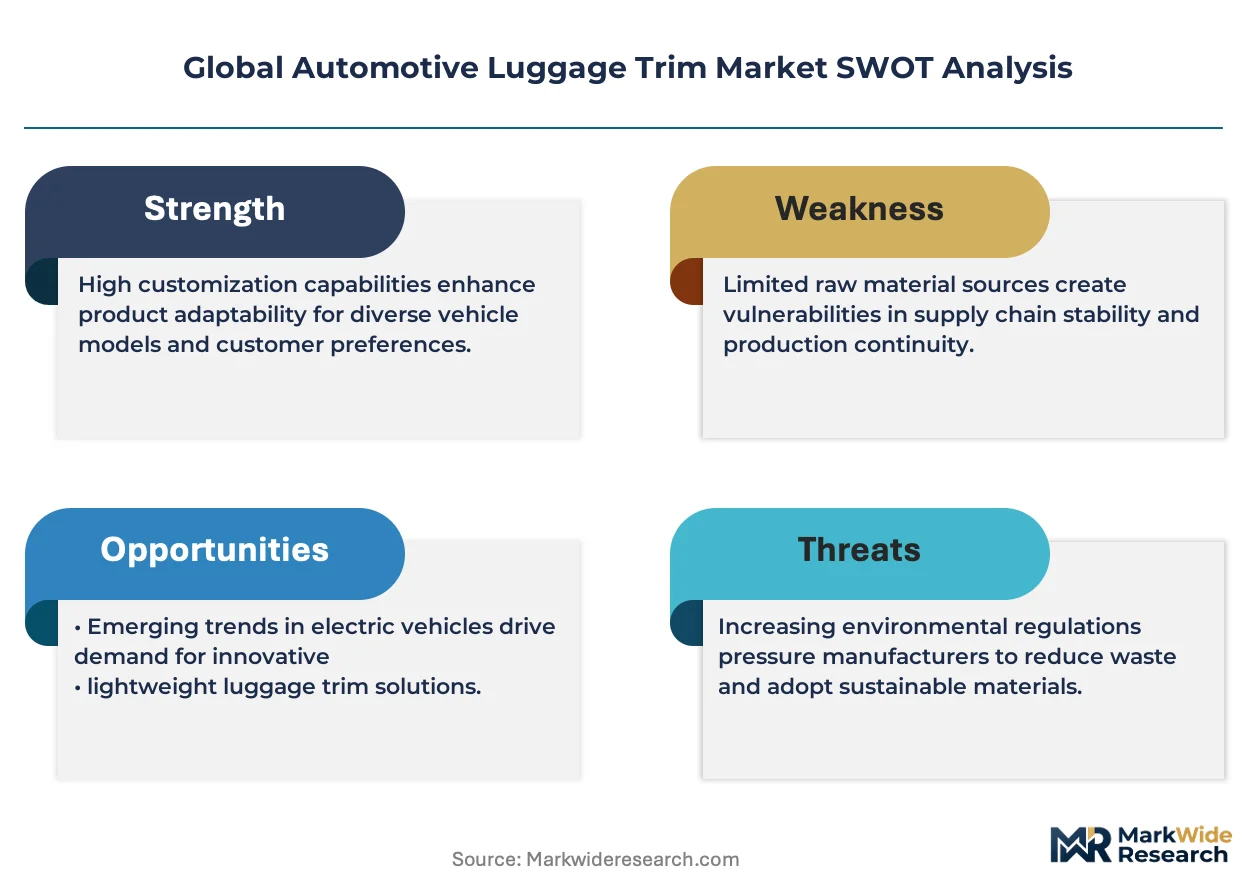
The central dynamic in the automotive luggage trim market is the direct conflict between OEM cost-down pressure and escalating regulatory mandates for sustainable, higher-cost materials. This forces suppliers to innovate in process efficiency to fund material science advancements demanded by circular economy goals.
Growth Catalysts
- Electric Vehicle Lightweighting:The push to extend battery range in electric vehicles accelerates the adoption of lightweight composite and natural fiber-based trim components to reduce overall vehicle mass.
- Regulatory Mandates for Recyclability:The EU's End-of-Life Vehicles Directive, which requires higher percentages of recycled and recoverable materials, directly stimulates demand for trim products designed for easier disassembly and material circularity.
- Vehicle Production in China:China's status as the world's largest vehicle producer creates a massive, concentrated demand base for all interior components, including luggage trim, sustaining high-volume production for suppliers in the region.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of polymers, resins, and natural fibers directly impact supplier profitability, as long-term OEM contracts often limit the ability to pass on increased input costs.
- High Recycling Costs:The cost and complexity of separating, cleaning, and reprocessing multi-material composite trim components at end-of-life remain a significant barrier to achieving true circularity at scale.
- Aesthetic and Durability Trade-offs:Using more sustainable or lightweight materials can sometimes compromise the scuff resistance, acoustic performance, or premium finish expected by consumers, particularly in luxury vehicle segments.
Strategic Opportunities
- Bio-Based and Natural Fiber Composites:Developing trim panels from renewable sources like hemp, flax, or kenaf offers a clear path for suppliers to meet OEM sustainability targets and differentiate on environmental performance.
- Modular Cargo Management Systems:There is an opportunity to design and supply higher-value, reconfigurable luggage trim systems with integrated dividers, nets, and storage solutions, especially for the popular SUV and crossover segments.
- Low-VOC Material Formulations:Suppliers who can engineer materials that comply with stringent interior air quality rules, such as China's GB standards and US EPA regulations, can gain preferred status with global automakers.
Industry Challenges
- Capital-Intensive Tooling:The shift to complex composite shapes and integrated trim features requires significant capital investment in new molding, forming, and cutting machinery for each new vehicle platform.
- Global Regulatory Harmonization:Suppliers face operational complexity in managing material formulations that must simultaneously comply with divergent chemical regulations like the EU's REACH and various national VOC standards.
- Integration of Smart Features:Incorporating elements like ambient lighting, power outlets, or sensors directly into trim panels demands new expertise in electronics and software integration, which is outside the core competency of traditional trim manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Luggage Trim Market |
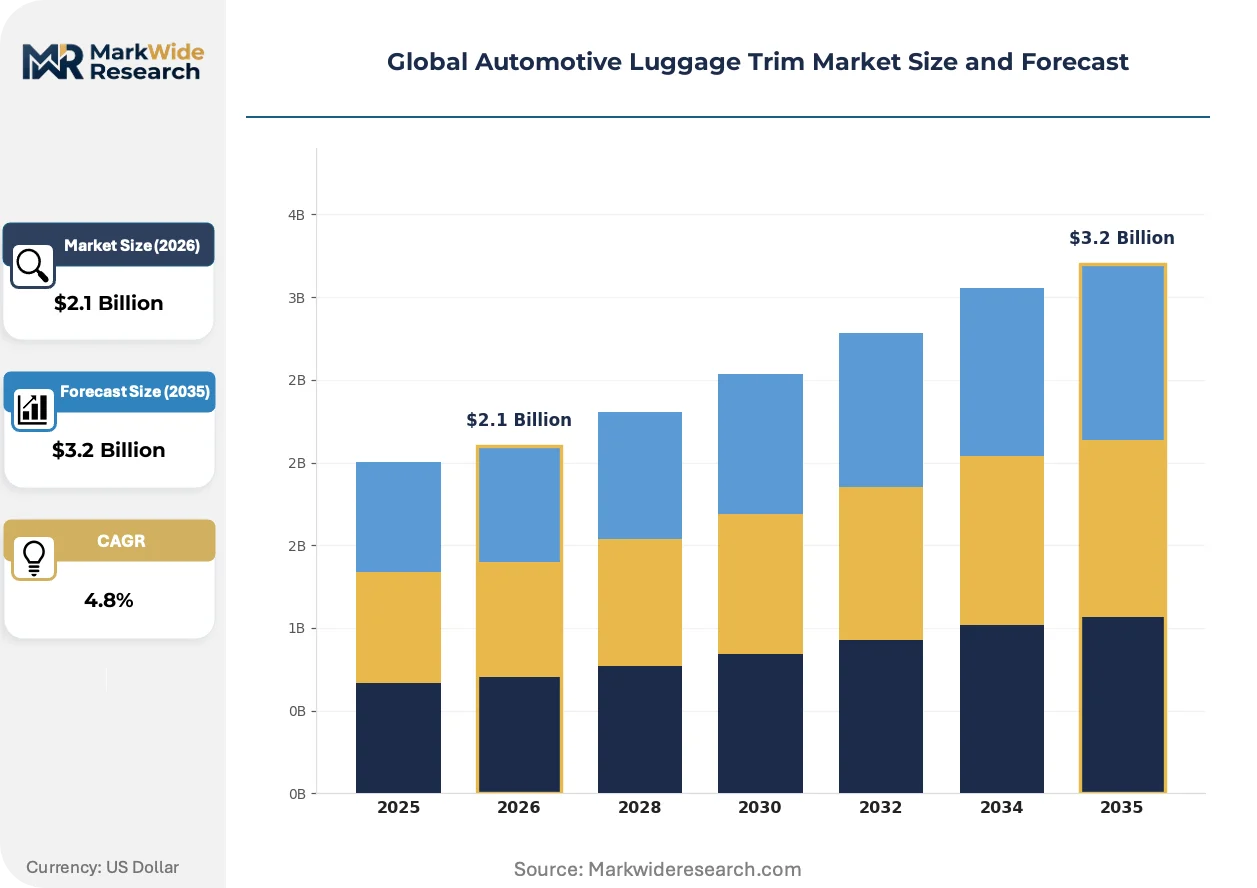
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Molded, Fabric Molded, Vinyl Trim, Rubber Edges, Aluminum Trim, Composite Materials Material: Thermoplastic Elastomers, Polypropylene, Polyurethane, PVC, Nylon Fibers, Metal Alloys Application: Trunk Edge Protection, Cargo Area Enhancement, Rear Door Trim, Seat Back Scuff, Load Floor Cover, Side Panel Protection End User: OEM Manufacturers, Aftermarket Suppliers, Vehicle Refurbishers, Replacement Parts Dealers, Specialty Auto Shops |
| Companies Covered | Toyota Boshoku Corporation, Benecke-Kaliko AG, Adient PLC, Hayashi Telempu, Eagle Ottawa, Autoneum Holding Ltd., Grupo Antolin, Seiren Co. Ltd, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Luggage Trim Market Strategic Shifts & Innovations
Material science is being fundamentally reoriented by the twin objectives of vehicle electrification and circular economy principles. This is compelling a shift from monolithic, cost-driven components toward integrated, lightweight systems designed for disassembly and reuse from their inception.
Multi-material composites, which combine different polymers and fibers, deliver tailored structural and acoustic properties in a single component. Electric vehicle manufacturers are the primary adopters of these materials to help offset heavy battery packs and improve vehicle efficiency. This integrated approach is decentralizing design, requiring suppliers to act as co-development partners on complex modules rather than as simple build-to-print vendors.
China's GB standards for vehicle interior air quality (VIAC) are setting a de facto global benchmark for material chemistry. The regulation forces the reduction or elimination of volatile organic compounds (VOCs) in adhesives, plastics, and textiles used inside the cabin. Premium and mid-market vehicle segments are most affected, driving innovation in low-emission polymers and water-based coatings to meet consumer and regulatory demands.
Automotive OEMs are increasingly adopting platform-based procurement strategies for standardized components like load floors and side panels. This model disrupts exclusive, long-term supplier relationships by creating competitive bidding scenarios for high-volume parts across multiple vehicle models. The shift is most prominent in Europe and North America, where automakers seek to leverage scale and drive down costs through component standardization.
Global Automotive Luggage Trim Market Segmentation
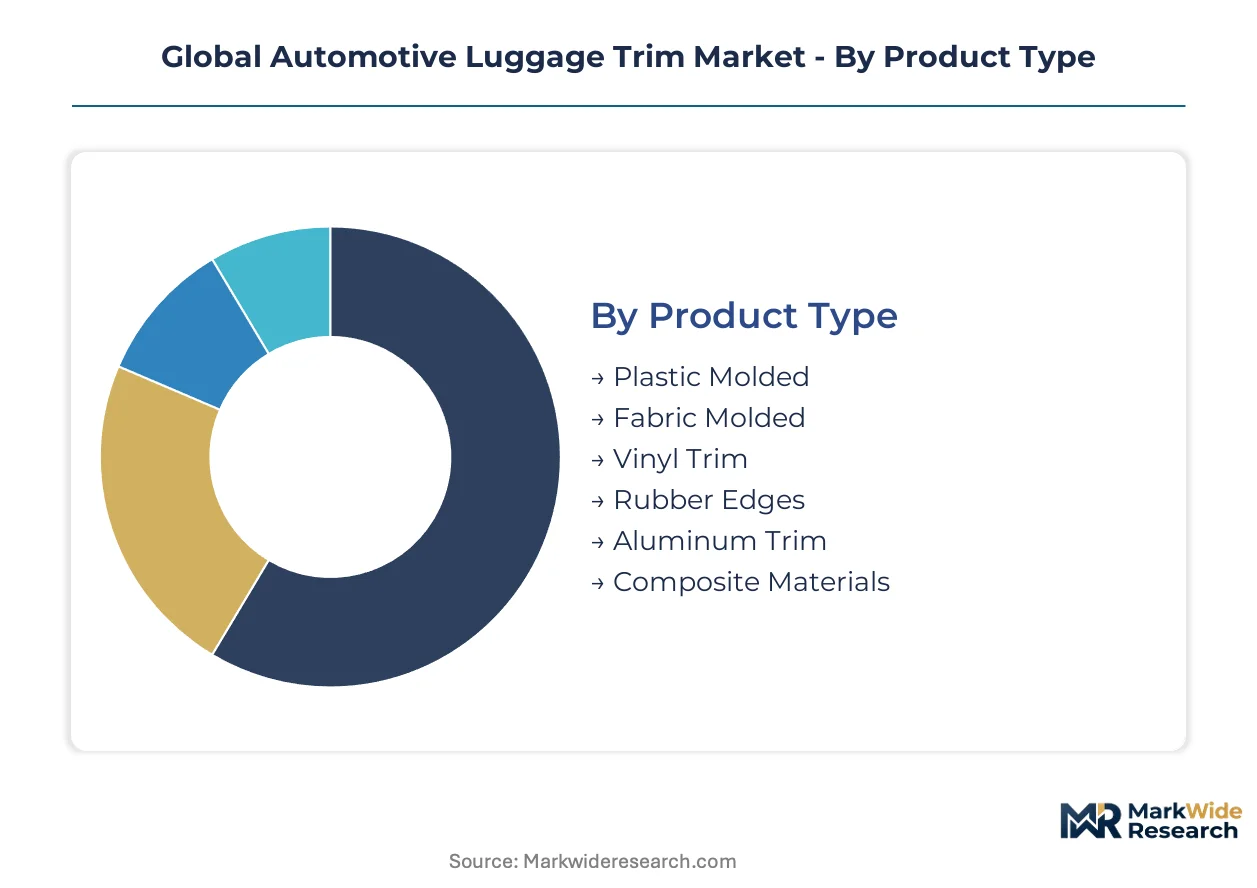
The global automotive luggage trim market’s segmentation reveals the diverse product offerings and strategic end-user channels driving industry evolution. Material innovations and application-specific designs cater to distinct vehicle requirements and regulatory pressures. Understanding these segments is crucial for suppliers aiming to align capabilities with OEM demands and emerging market trends.
Product Type:
Supply concentration for automotive luggage trim products largely centers on established manufacturing processes for high-volume components, while specialized production lines address niche material demands.
- Plastic Molded:Manufactured via injection molding, these components offer design flexibility and cost efficiency for high-volume vehicle platforms. Demand concentrates in mass-market vehicles produced in China and Europe, driven by OEM cost-down pressures.
- Composite Materials:Engineered from multiple polymers and fibers, these products deliver superior strength-to-weight ratios and acoustic dampening. Electric vehicle manufacturers in Germany and the United States adopt them to reduce vehicle mass and extend battery range.
- Fabric Molded:These products offer aesthetic finishes and noise absorption, common in premium vehicle segments.
- Vinyl Trim:Durable and easy to clean, vinyl trim suits utility vehicles and commercial vans.
- Rubber Edges:Used for protection against scuffs and impacts along cargo area perimeters.
- Aluminum Trim:Offers premium aesthetics and structural rigidity in luxury automotive brands.
Plastic Molded products absorb the bulk of installed capacity; Composite Materials are expanding most quickly.
Material:
Material selection for automotive luggage trim often reflects a tiered approach, balancing cost with performance requirements like durability, weight, and acoustic properties.
- Polypropylene:A cost-effective and versatile thermoplastic polymer, widely used for injection-molded components due to good mechanical properties and recyclability. Demand is significant across all vehicle segments, particularly in high-volume production facilities in China and India.
- Thermoplastic Elastomers:These materials combine processing advantages of plastics with functional properties of rubber, offering flexibility, impact resistance, and a soft-touch feel. European OEMs increasingly specify TPEs for trunk liners and edge protection due to durability and low VOCs.
- Polyurethane:Offers excellent abrasion resistance and cushioning, used in foam-backed trim.
- PVC:Provides good chemical resistance and low cost, though European regulations limit its use.
- Nylon Fibers:Utilized in fabric molded products for strength, abrasion resistance, and aesthetics.
- Metal Alloys:Employed for reinforcing structures or decorative accents in premium vehicle cargo areas.
The market favors Polypropylene for its cost-effectiveness, while Thermoplastic Elastomers deliver enhanced performance attributes.
Application:
Each application within the automotive luggage trim market serves a distinct functional role, from protecting vehicle structures to enhancing user convenience and aesthetic appeal.
- Load Floor Cover:These panels form the primary surface of the cargo area, providing a flat, durable, and often sound-dampening base. Demand is high in SUV and crossover segments across North America and Europe, requiring robust materials for heavy-duty use.
- Trunk Edge Protection:Components shield vehicle painted surfaces and interior from scratches and impacts during loading and unloading. OEMs in Germany and Japan prioritize durable, scuff-resistant materials for these critical high-wear areas.
- Cargo Area Enhancement:Includes accessories like nets, organizers, and dividers for improved functionality.
- Rear Door Trim:Interior panels covering tailgates or hatches, often integrating speakers or lighting.
- Seat Back Scuff:Protective coverings on seat backs, preventing damage from cargo or feet.
- Side Panel Protection:Linings for trunk side walls, offering aesthetic finish and impact resistance.
The broadest utility is observed in Load Floor Cover, with Trunk Edge Protection representing a growing area of design focus.
End User:
The end-user landscape for automotive luggage trim is shaped by distinct purchasing patterns, scale requirements, and specific demands for product integration and customization.
- OEM Manufacturers:Primary customers, integrating luggage trim components directly into new vehicle assembly lines according to strict design, performance, and cost specifications. Global automotive production hubs in China, Germany, and the United States drive significant volume demand.
- Aftermarket Suppliers:These companies provide replacement parts and upgrade options for existing vehicles, offering customization and material choices. Demand for aftermarket solutions is strong in markets with older vehicle fleets, such as Eastern Europe and Southeast Asia.
- Vehicle Refurbishers:Restore or upgrade vehicle interiors, requiring specialized trim for older models.
- Replacement Parts Dealers:Stock and sell individual trim components for repair and maintenance to shops and consumers.
- Specialty Auto Shops:Offer bespoke interior modifications and high-performance trim installations for unique projects.
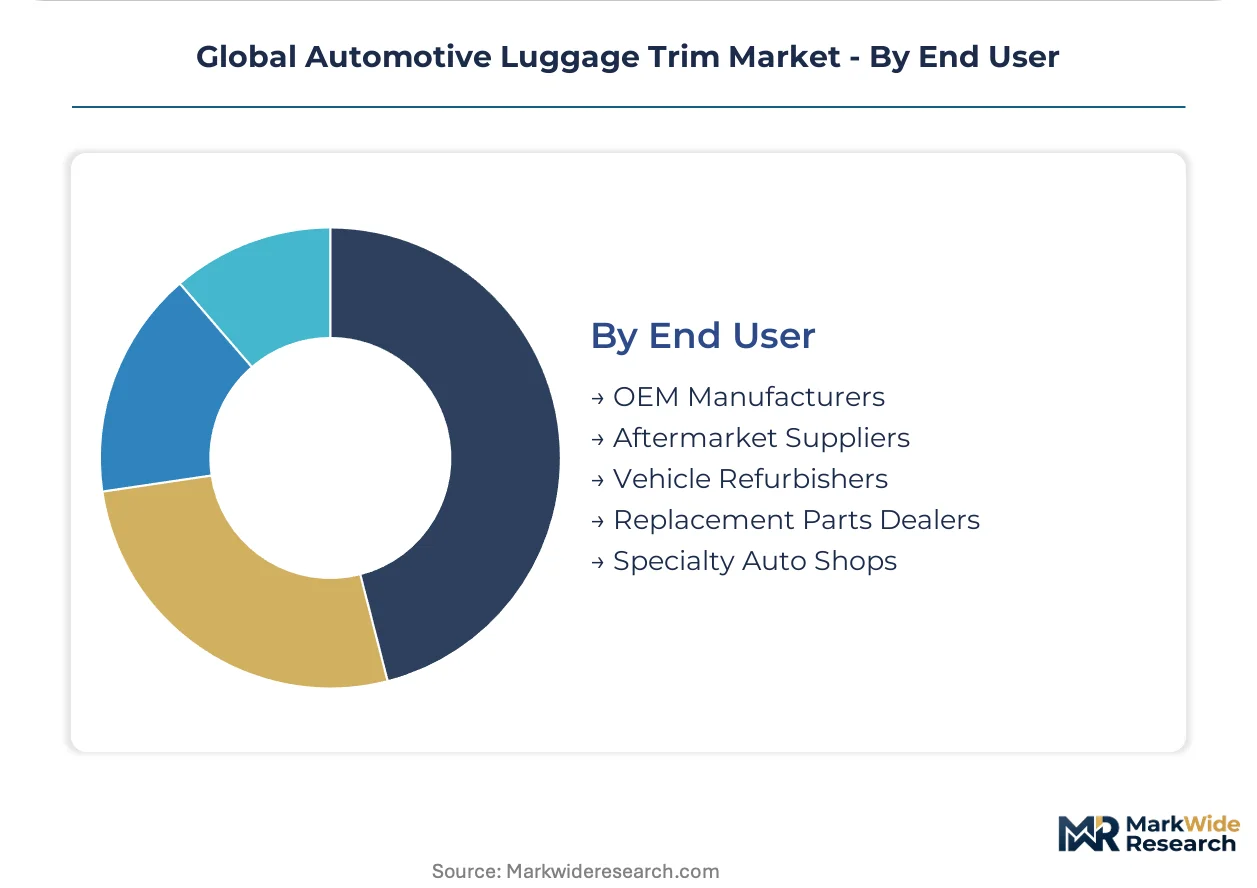
The primary purchasing power resides with OEM Manufacturers, while Aftermarket Suppliers offer diversification opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's expansive automotive manufacturing base serves as a primary hub for automotive luggage trim production and demand, driven by China's position as the world's largest vehicle market. This concentration of OEM activity in specific clusters shapes regional market dynamics. Material selection and production volumes are heavily influenced by local regulatory frameworks and consumer preferences across key global automotive regions.
China
China's vast vehicle production ecosystem drives immense demand for luggage trim components, particularly plastic molded products for mass-market vehicles. The country's GB standards for vehicle interior air quality directly influence material chemistry, mandating low-VOC formulations. Manufacturing facilities in the Yangtze River Delta, including Nanjing and Shanghai, represent significant production capacities for automotive interior components.
Germany
German OEMs prioritize lightweight composite materials for luggage trim, especially for electric vehicles, to extend battery range and enhance performance. The EU's End-of-Life Vehicles Directive mandates higher recycled content, pushing innovation in material circularity. Automotive clusters around Stuttgart and Munich are centers for advanced material development and premium vehicle integration.
United States
Demand for robust load floor covers and trunk edge protection is strong in the United States, particularly for SUV and crossover segments. US EPA standards on volatile organic compounds impact material choices, promoting low-emission solutions. The Detroit metropolitan area remains a critical hub for automotive R&D and manufacturing, influencing trim specifications for major platforms.
Japan
Japanese automakers emphasize durable, scuff-resistant materials for trunk edge protection and load floor covers, reflecting a focus on long-term vehicle quality. Strict internal OEM specifications drive continuous improvement in material performance and aesthetic finish. Production facilities in the Aichi Prefecture, home to major automotive giants, are at the forefront of these material and process innovations.
India
India's automotive market generates substantial demand for cost-effective polypropylene-based luggage trim, primarily for high-volume compact and entry-level vehicles. The country's evolving automotive regulations increasingly focus on material localization and sustainability. Manufacturing hubs in Chennai and Pune are expanding their capabilities to meet the growing domestic and export market for interior components.
Global Automotive Luggage Trim Market Key Industry Players
Premium-margin players sit above commodity-margin players across the automotive luggage trim value chain, leveraging specialized materials and advanced manufacturing processes. The market structure exhibits a tiered consolidation, with large Tier 1 suppliers dominating OEM programs and smaller specialists serving niche applications. Strategic archetypes include integrated solutions providers, material science innovators, and cost-efficient volume manufacturers. Dominant competitive moves involve strategic partnerships with OEMs for co-development and continuous investment in process efficiency.
Specialists in integrated interior solutions, such as Adient PLC, leverage extensive manufacturing footprints to supply large OEM programs with standardized trim components. Faurecia, a global automotive supplier, focuses on developing lightweight composite materials to meet new sustainability targets and electrification demands. Autoneum Holding Ltd., headquartered in Switzerland, differentiates through its expertise in acoustic-dampening fabric molded products, particularly for the premium vehicle segment.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Benecke-Kaliko AG |
| Adient PLC |
| Hayashi Telempu |
| Eagle Ottawa |
| Autoneum Holding Ltd. |
| Grupo Antolin |
| Seiren Co. Ltd |
| Faurecia |
| Others |
Cost & Logistics Intelligence
The EU's End-of-Life Vehicles Directive gates qualified supply and premium-tier pricing access for automotive luggage trim components. This regulation drives material innovation, impacting cost structures for suppliers.
Pricing Analysis
Value-based pricing for automotive luggage trim components centers on aesthetic finish and noise dampening performance. The dominant pricing structure remains per-unit transactional, heavily influenced by long-term OEM contracts. Price differentiation stems from material quality grade and customization level for specific vehicle platforms. Pricing softness reflects intense cost-down pressures from global OEM manufacturers, particularly for mass-market vehicles. Premium vehicle segments show less price sensitivity for advanced acoustic and lightweight solutions.
Supply Chain Analysis
OEM qualification for material chemistry and production process gates entry into the automotive luggage trim supply chain. Geographic supply concentration centers on China, Germany, and the United States, reflecting major automotive production hubs. Raw material dependencies include polypropylene, thermoplastic elastomers, and various natural fibers. A structural risk involves commodity price volatility for polymers, impacting supplier profitability under fixed OEM contracts. Distribution runs through a direct-to-OEM model for new vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive luggage trim market is a consolidation play, driven by escalating OEM demands for low-emission and recyclable materials. This pressure forces smaller, less innovative suppliers out of high-volume programs.
For Market Incumbents:Hedge against raw material price volatility through long-term procurement agreements for polypropylene and natural fibers. Invest in advanced R&D for multi-material composites to meet electric vehicle lightweighting targets, mitigating the threat of new material entrants. Expand production capacity in China to leverage the massive vehicle production ecosystem, securing high-volume OEM contracts. Seek vertical integration into key material processing steps to control costs and ensure material circularity.
For New Entrants and Emerging Players:The EU's End-of-Life Vehicles Directive in Europe opens a window for suppliers specializing in easily disassembled and recycled trim components. Target the premium vehicle segment with bio-based and natural fiber composites for differentiated environmental performance. Focus on modular cargo management systems for SUVs and crossovers in North America, offering higher-value solutions. A go-to-market angle involves co-development partnerships with innovative electric vehicle startups.
For Investors and Strategic Acquirers:OEM adoption of platform-based procurement for sustainable materials is the leading indicator that the market is shifting towards fewer, more capable suppliers. Long-term viability hinges on companies with robust material science capabilities and global manufacturing footprints. Acquisition targets should be mid-sized specialists possessing unique intellectual property in low-VOC formulations or advanced composite processing. A crucial signal to watch is the percentage of recycled content mandated in new vehicle platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Based Composites | Meets stringent EU sustainability targets and differentiates products for environmentally conscious OEMs. |
| Expand Global Production Footprint | Leverages high-volume production in China and secures supply for diverse OEM platforms. |
| Develop Low-VOC Material Formulations | Ensures compliance with China's GB standards and US EPA regulations, gaining preferred supplier status. |
| Partner for Modular Cargo Systems | Captures higher-value opportunities in SUV and crossover segments by offering integrated solutions. |
| Automate Injection Molding Processes | Reduces production costs and enhances efficiency to offset rising material expenses for mass-market components. |
Research Approach
Independent corroboration across automotive industry reports, OEM sustainability disclosures, and material science journals underwrites the qualitative findings. This study combined primary interviews with Tier 1 supplier executives, OEM platform engineers, and material procurement specialists. Secondary data sources included vehicle production databases, regulatory filings from the US EPA, and EU environmental directives. Bottom-up and top-down triangulation ensured data consistency and market sizing accuracy.
The forecast window was anchored to historical production volumes and material adoption rates from the past five years. The analytical framework modeled segmentation dimensions including product type, material, application, and end-user. Vehicle class and propulsion architecture served as industry-specific dimensions. Compound annual growth rates were derived from projected vehicle production, material innovation, and regulatory impact throughout the forecast period.
The model assumes a particular technology adoption path; alternative pathways for bio-based composites would alter the outlook. Forecasts reflect assumptions regarding raw material price stability and consistent regulatory enforcement. Geopolitical shifts impacting global supply chains represent a significant risk factor. A model refresh is warranted upon material change in OEM platform standardization strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Global Cabin Air Heater Market
Automotive Interior & Exterior
Automotive Active Grille Shutter (AGS) Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Cowl Screen Market