
 Global Automotive Chrome Accessories Market | 2026-2036
Global Automotive Chrome Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Chrome Accessories Market Intelligence
Specialized electroplating capacity in Europe is hardening due to stringent environmental regulations on hexavalent chromium. Magna International Inc. leverages its global manufacturing footprint to supply major OEMs with compliant components. Dorman Products specializes in the aftermarket segment with a broad catalog of replacement parts. Varroc Engineering Ltd. competes through its focus on exterior systems that integrate chrome elements.
Automotive chrome accessories are components with a chrome-plated finish used for aesthetic enhancement and corrosion protection. The process typically involves electroplating layers of nickel and chromium onto a substrate, such as ABS plastic or steel. Their primary purpose is to provide a durable, reflective surface for exterior and interior trim. Grilles and trim moldings constitute high-volume product types, while the passenger vehicle application accounts for the majority of consumption.
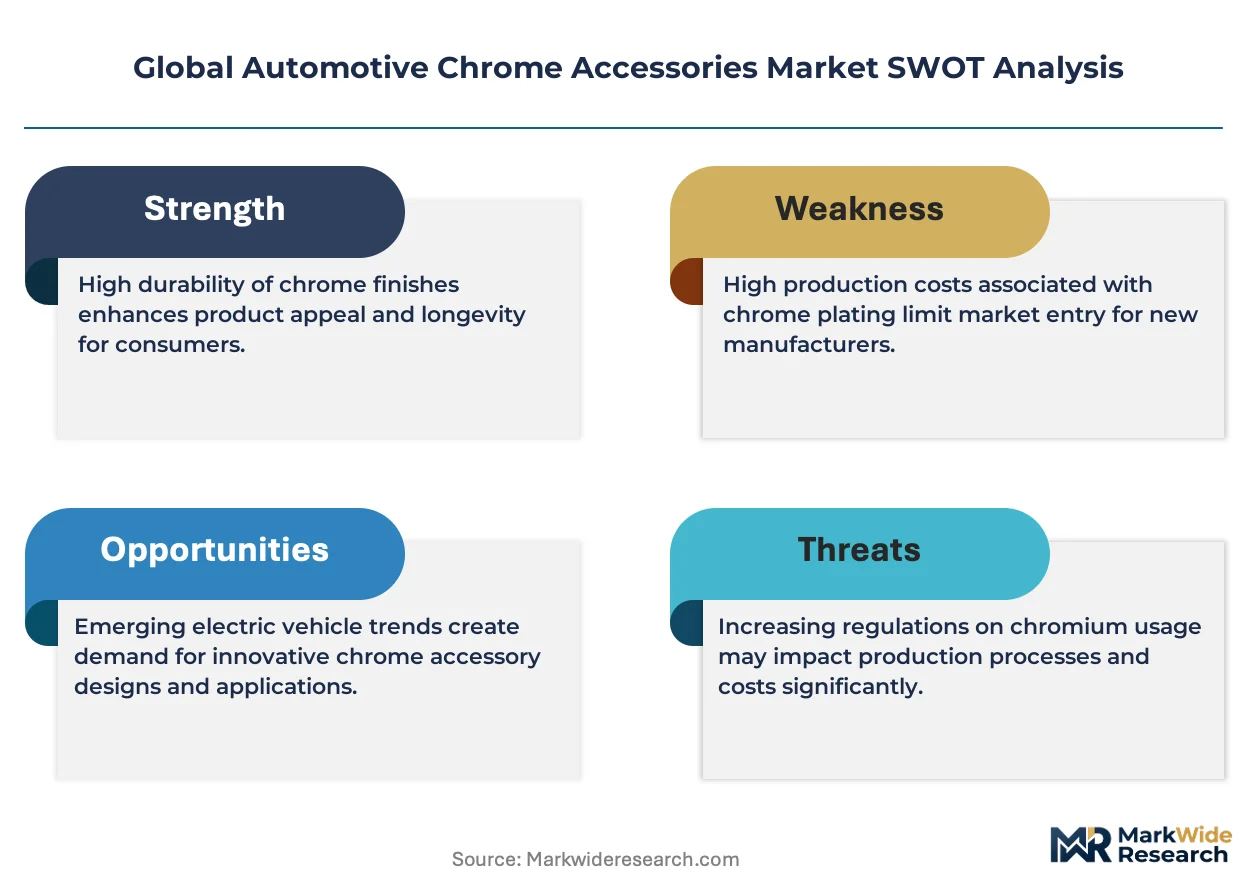
The European Union's REACH regulation, enforced by ECHA, restricts the use of hexavalent chromium, a major process constraint. In the United States, the EPA sets standards for hazardous air pollutants from plating and polishing operations. China's Ministry of Ecology and Environment (MEE) also imposes strict wastewater and emissions controls on finishing facilities. This regulatory pressure creates a clear imperative for suppliers to invest in alternative materials and coating processes to maintain market access.
Market Dynamics
The central structural force shaping the automotive chrome accessories market is the regulatory-driven obsolescence of hexavalent chromium. This pressure, originating from frameworks like the EU's REACH, compels a fundamental and capital-intensive shift in manufacturing processes toward compliant alternatives.
Growth Catalysts
- SUV and Premium Vehicle Demand:The sustained consumer preference for SUVs, crossovers, and premium sedans, particularly in China, directly increases the consumption of chrome accessories as these vehicles utilize more extensive exterior and interior brightwork for aesthetic differentiation.
- Advancements in Coating Technology:The development of viable alternatives such as trivalent chromium plating and Physical Vapor Deposition (PVD) provides pathways for manufacturers to meet both stringent environmental standards and OEM requirements for durability and appearance.
- Aftermarket Personalization Culture:A strong culture of vehicle customization and personalization, especially in North America and parts of Asia, fuels steady demand for aftermarket grilles, mirror covers, and door handles to upgrade or replace factory components.
Market Restraints
- High Capital Investment for Re-tooling:Transitioning from established hexavalent chromium lines to alternative processes like trivalent plating requires significant capital expenditure for new equipment, chemistry, and facility modifications, acting as a barrier for smaller suppliers.
- Supply Base Contraction:Stringent environmental enforcement, particularly in Europe, is leading to a consolidation and hardening of specialized electroplating capacity, creating potential supply chain bottlenecks and increasing costs for automotive OEMs.
- Threat from Alternative Finishes:The increasing popularity of non-chrome finishes, such as high-gloss black, satin silver, carbon fiber, and bronze, especially in the electric vehicle and performance segments, presents a direct substitution threat.
Strategic Opportunities
- Aftermarket Expansion in Emerging Economies:There is significant opportunity in developing aftermarket distribution networks in emerging automotive markets like India and Southeast Asia, where a growing middle class seeks to personalize used and new vehicles.
- Integration of Functional Electronics:Developing chrome-plated components with integrated functionalities, such as illuminated grilles for EVs or emblems that house sensors for ADAS, creates new, high-value product categories.
- Specialized Coatings for EV Components:The electric vehicle transition opens opportunities for developing specialized chrome finishes with enhanced corrosion resistance and specific dielectric properties for use on battery pack enclosures, charging port surrounds, and thermal management systems.
Industry Challenges
- Quality Consistency with New Processes:Achieving consistent color, brightness, and durability across global manufacturing sites using newer trivalent chromium chemistries is a significant operational challenge, risking costly quality control failures and OEM rejections. *Scarcity of Specialized Talent: The industry faces a shortage of chemical engineers and process technicians with expertise in the newer, compliant plating technologies, creating a bottleneck in process optimization and troubleshooting.
- Complex Waste Stream Management:Managing wastewater and solid waste from trivalent chromium and other alternative processes remains a complex and costly challenge, with disposal regulated by agencies like the EPA and China's MEE.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Chrome Accessories Market |
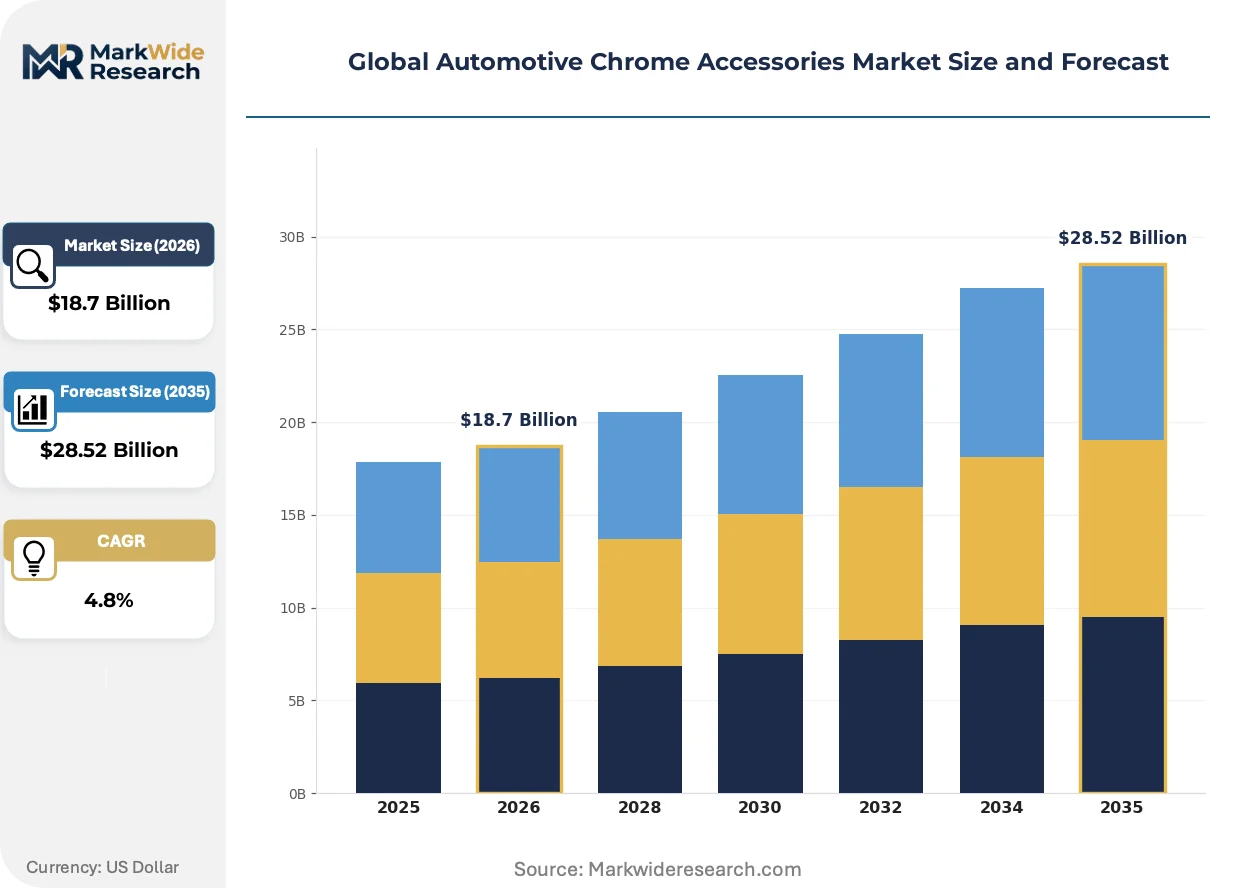
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
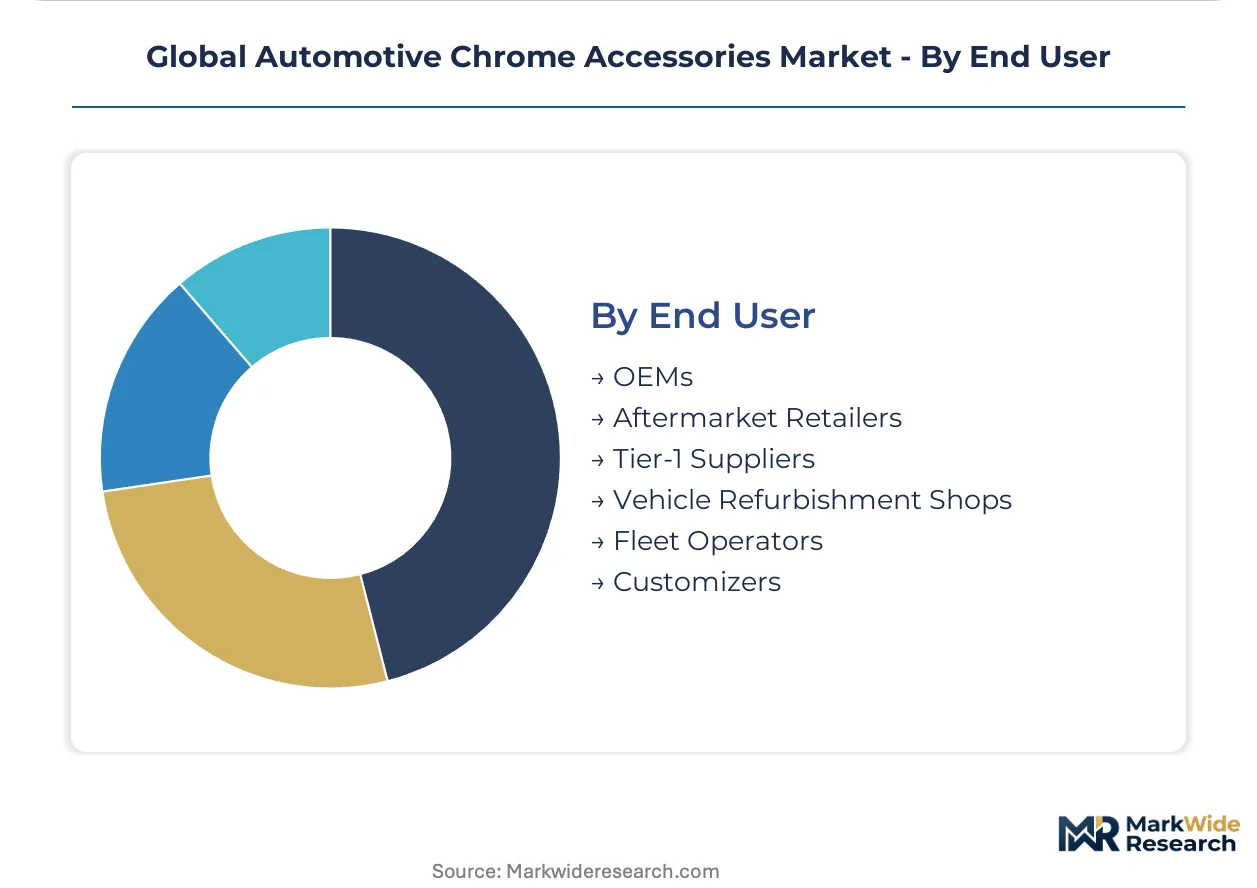
| Segmentation | Product Type: Bumpers, Grilles, Door Handles, Mirror Covers, Trim Moldings, Tailgate Handles Technology: Electroplating, Vacuum Metallization, Cold Spraying, PVD Coating, Anodizing, Powder Coating Application: Passenger Vehicles, Commercial Trucks, Two-wheelers, Specialty Vehicles, Recreational Vehicles, Heavy Equipment End User: OEMs, Aftermarket Retailers, Tier-1 Suppliers, Vehicle Refurbishment Shops, Fleet Operators, Customizers |
| Companies Covered | Varroc Engineering Ltd., Putco Inc., Magna International Inc., Dorman Products, Lund International, Plastic Omnium, Motherson Sumi Systems Ltd., Covercraft Industries LLC, Flex-N-Gate Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Chrome Accessories Market Strategic Shifts & Innovations
The market is defined by a necessary evolution in materials science and manufacturing, driven by the twin pressures of environmental regulation and shifting design preferences. This dynamic forces suppliers to innovate beyond traditional aesthetics and toward functional, compliant, and differentiated surface finishes.
Physical Vapor Deposition (PVD) is a coating process that creates a thin, durable, metallic finish on a substrate in a vacuum environment. Automotive designers and engineers in the premium and EV segments are increasingly specifying PVD for its environmental benefits over traditional plating. The technology's ability to produce a wide array of colors and finishes, including dark and satin chromes, is electrifying the aesthetic possibilities for exterior trim and branding elements.
The European Union's REACH regulation, administered by ECHA, is progressively restricting the use of hexavalent chromium, with a sunset date forcing a phase-out. This action compels a complete process substitution for suppliers wishing to maintain access to the significant European automotive market. Exterior component manufacturers are most impacted, accelerating their validation and adoption of trivalent chromium plating as the primary compliant alternative for high-volume production.
A demand-side shift toward muted and dark-themed aesthetics is altering trim package strategies. This trend away from traditional bright chrome disrupts the standard component catalog for many vehicle models, with "blackout packages" becoming a popular factory option. The shift is most pronounced in the North American and European markets, where automakers use dark chrome and high-gloss black accessories to define sport trims or create a more modern look for electric vehicles.
Global Automotive Chrome Accessories Market Segmentation
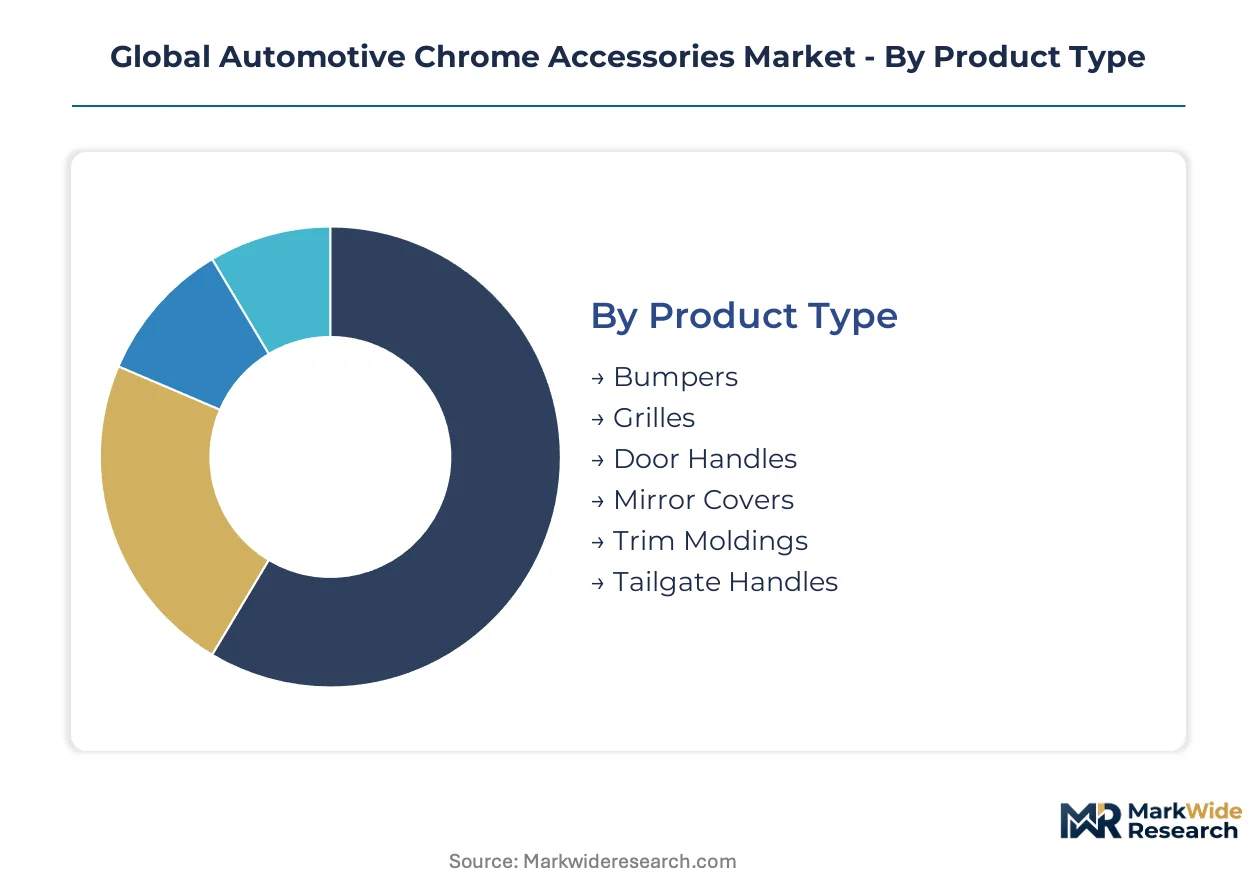
The global automotive chrome accessories market segments reflect the diverse requirements of vehicle manufacturers, aftermarket consumers, and specialized industries. Understanding these distinctions is essential for identifying strategic growth areas and navigating the complex regulatory landscape impacting surface finishing technologies.
Product Type:
The distinction between high-volume, functional chrome components and premium aesthetic brightwork defines the product type segment, influencing design and material choices.
- Grilles:These prominent front-end components often feature complex designs and are critical for vehicle branding and aesthetic differentiation, with demand concentrating in premium and SUV segments in China.
- Trim Moldings:Used extensively for exterior and interior accentuation, these components provide continuous chrome lines along windows, doors, and dashboards, seeing high consumption across all passenger vehicle categories globally.
- Bumpers:Chrome-plated bumpers and bumper accents offer both aesthetic appeal and corrosion resistance, particularly important for trucks and SUVs in North America.
- Door Handles:Providing both functionality and a touch of luxury, chrome door handles remain a popular feature on many vehicle models.
- Mirror Covers:These accessories enhance exterior styling and are frequently offered as an upgrade option for personalization in the aftermarket.
- Tailgate Handles:Often found on pickup trucks and SUVs, chrome tailgate handles combine durability with a premium appearance.
Today's leader: Grilles. Tomorrow's challenger: Trim Moldings.
Technology:
Compliance with evolving environmental regulations drives technology adoption across the market, influencing both cost structures and material selection for surface finishing.
- Electroplating:This traditional method applies multiple layers of nickel and chromium for durability and shine, facing significant regulatory pressure from REACH in Europe due to hexavalent chromium.
- PVD Coating:Physical Vapor Deposition creates a thin, durable metallic finish in a vacuum, increasingly specified by designers for its environmental benefits and versatility in color, particularly for electric vehicles in Germany.
- Vacuum Metallization:A process for applying a metallic layer by evaporation and condensation in a vacuum, offering a cost-effective solution for non-structural parts.
- Cold Spraying:This solid-state deposition process applies metallic coatings without melting the material, suitable for repair and specialized applications.
- Anodizing:Primarily used on aluminum, anodizing creates a durable, corrosion-resistant oxide layer, often for colored finishes rather than traditional chrome.
- Powder Coating:An alternative finishing process that applies a dry powder, then cures it with heat, offering a wide range of colors and textures without solvents.
PVD Coating represents the fastest-growing trajectory as manufacturers seek compliant and versatile finishing solutions.
Application:
The primary application for chrome accessories remains passenger vehicles, though specialized segments offer distinct growth opportunities for niche suppliers.
- Passenger Vehicles:This segment accounts for the majority of chrome accessory consumption, driven by consumer demand for aesthetic enhancement in SUVs and premium sedans across China and the United States.
- Commercial Trucks:Chrome accessories provide durability and branding for heavy-duty vehicles, with significant demand for grilles and bumper elements in North America.
- Recreational Vehicles:RVs utilize chrome for exterior trim and accents, contributing to a premium feel and long-term aesthetic appeal in leisure markets.
- Two-wheelers:Motorcycles and scooters incorporate chrome for exhaust components, mirrors, and engine covers, particularly in markets like India and Southeast Asia.
- Specialty Vehicles:This category includes custom builds, emergency vehicles, and unique automotive projects requiring bespoke chrome elements.
- Heavy Equipment:Agricultural and construction machinery use chrome for functional and protective components, demanding high corrosion resistance.
Demand concentration remains strongest within Passenger Vehicles, with Recreational Vehicles demonstrating a steep expansion trajectory.
End User:
Profitability and supply chain integration vary significantly across end-user segments, reflecting diverse procurement patterns and value chain positions.
- OEMs:Original Equipment Manufacturers integrate chrome accessories directly into new vehicle production lines, demanding high-volume, quality-consistent supply from Tier-1 partners.
- Aftermarket Retailers:These channels distribute replacement parts and personalization accessories to consumers, fueling demand for grilles, mirror covers, and trim upgrades in North America.
- Tier-1 Suppliers:These companies design and manufacture complex systems incorporating chrome elements for direct delivery to OEMs, requiring stringent quality control and regulatory compliance.
- Vehicle Refurbishment Shops:These establishments repair and restore vehicles, sourcing chrome components for collision repair and aesthetic restoration projects.
- Fleet Operators:Companies managing large vehicle fleets may procure chrome accessories for maintenance, repair, or to standardize vehicle appearance.
- Customizers:Enthusiasts and specialized shops purchase chrome parts for unique vehicle modifications and aesthetic upgrades.
OEMs drive the foundational demand for chrome accessories, while Aftermarket Retailers are evolving procurement strategies to meet personalization trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive chrome accessories market experiences a significant regulatory arbitrage, as stringent environmental standards in regions like Europe compel a shift in manufacturing processes and investment toward compliant technologies, influencing global supply chain configurations.
China
China's sustained demand for SUVs and premium sedans directly drives consumption of chrome accessories for aesthetic differentiation. The Ministry of Ecology and Environment (MEE) imposes strict wastewater and emissions controls on finishing facilities, pushing for cleaner production. Major automotive manufacturing hubs like the Yangtze River Delta continue to expand their capacity for chrome accessory production.
United States
The United States market sees strong demand from aftermarket personalization culture and for commercial trucks utilizing chrome elements. The Environmental Protection Agency (EPA) sets standards for hazardous air pollutants from plating and polishing operations. Aftermarket suppliers and customization shops in the Midwest cater to diverse consumer preferences for vehicle upgrades.
Germany
Germany's premium automotive segment and growing electric vehicle production increasingly specify advanced chrome finishes like PVD coating. The European Union's REACH regulation, enforced by ECHA, restricts hexavalent chromium use, accelerating technology adoption. Automotive R&D centers in Bavaria focus on developing compliant and high-performance surface finishes.
India
India's two-wheeler market and a growing middle class seeking vehicle personalization contribute to rising demand for chrome accessories. The Bureau of Indian Standards (BIS) guides manufacturing quality and environmental compliance. The Chennai automotive corridor sees increasing investment in component manufacturing for domestic and export markets.
Mexico
Mexico serves as a significant manufacturing base for automotive components, including chrome accessories, particularly for North American vehicle production. Local environmental regulations influence the adoption of sustainable plating practices. The Bajío region's automotive assembly plants integrate chrome parts into high-volume vehicle models.
Global Automotive Chrome Accessories Market Key Industry Players
European producers anchor one tier, focusing on advanced compliant technologies and premium applications; Asian manufacturers, particularly in China, hold another tier, emphasizing scale and cost-effective production for both OEM and aftermarket segments. The market structure is tiered, reflecting diverse regulatory pressures and customer requirements. Strategic archetypes include global Tier-1 suppliers, specialized aftermarket providers, and technology-focused coating innovators. Dominant competitive moves involve capacity expansion in trivalent chromium and PVD technologies, alongside strategic partnerships to secure market access.
Among global Tier-1 suppliers, Magna International Inc. leverages its extensive manufacturing footprint to supply compliant components to major OEMs worldwide. Dorman Products exemplifies a leading aftermarket specialist, offering a broad catalog of replacement and upgrade parts across North America. Varroc Engineering Ltd. represents a significant player focused on exterior systems that integrate chrome elements for various vehicle platforms.
| Leading Market Players |
|---|
| Varroc Engineering Ltd. |
| Putco Inc. |
| Magna International Inc. |
| Dorman Products |
| Lund International |
| Plastic Omnium |
| Motherson Sumi Systems Ltd. |
| Covercraft Industries LLC |
| Flex-N-Gate Corporation |
| Others |
Cost & Logistics Intelligence
Specialized electroplating talent in Europe influences pricing tiers, reflecting higher labor costs and investment in compliant technologies.
Pricing Analysis
Direct-to-OEM discount structures dominate the automotive chrome accessories market. Pricing models include contract-based long-term offtake for original equipment manufacturers and per-unit transactional sales for the aftermarket. Price differentiation drivers include regulatory compliance (like REACH), quality grade, and customization level. Upward pricing pressure stems from significant capital investment required for new compliant plating technologies. Aftermarket retailers exhibit higher price sensitivity compared to OEMs who prioritize validated, compliant components.
Supply Chain Analysis
Stringent regulatory certification for compliant plating technologies gates market access for suppliers. Supply concentration exists in China, Germany, and Mexico for various components. The industry draws from key raw material dependencies including ABS plastic, nickel, and trivalent chromium chemicals. Regulatory restrictions, particularly the hexavalent chromium phase-out, pose a structural supply chain risk. Downstream distribution typically flows direct to OEMs or through established aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion characterizes this market, justified by the premium-tier shift towards advanced PVD finishes for electric vehicles.
For Market Incumbents:Anticipate continued regulatory pressure by investing in compliant trivalent chromium plating capacity. Secure long-term OEM contracts for advanced PVD applications to counter the threat from alternative finishes like high-gloss black. Prioritize R&D into integrated functional electronics within chrome components to maintain differentiation.
For New Entrants and Emerging Players:Launch via specialized aftermarket distribution networks in emerging economies like India. Target white-space opportunities in integrated functional electronics for EVs and specialized coatings for battery enclosures. The aftermarket personalization segment offers the most penetrable entry point, leveraging e-commerce platforms for direct consumer engagement.
For Investors and Strategic Acquirers:Valuations sit cheapest among smaller, specialized electroplating firms struggling with hexavalent chromium transition. The market's long-term viability favors companies with validated compliant technologies over the next decade. Target specialized PVD coating innovators or Tier-1 suppliers with established OEM relationships. OEM adoption rates of trivalent chromium for high-volume models are a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Trivalent Chromium Capacity | Ensures compliance with EU REACH regulations, securing access to the European automotive market. |
| Expand PVD Coating R&D | Develops versatile, environmentally friendly finishes for premium vehicles and integrated EV components. |
| Secure Long-Term OEM Contracts | Provides stable demand and validates new compliant technologies for high-volume production. |
| Develop Aftermarket E-commerce Platforms | Captures growing personalization demand in North America and emerging Asian markets. |
| Integrate Functional Electronics | Creates high-value product categories for ADAS sensors and illuminated EV grilles. |
Research Approach
Direct dialogue with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and chemical process engineers provided primary insights. This was combined with extensive secondary research, including vehicle production databases, environmental agency reports, and trade association publications. A rigorous bottom-up market sizing approach was triangulated with top-down validation across all segments.
Bottom-up market sizing informed the analytical framework across the modeling period, validated by top-down industry trends. Segmentation dimensions included product type, technology, application, end user, and regional regulatory environment. Compound annual growth rates were derived from historical trends and anticipated shifts in material science. Vehicle production forecasts and regulatory compliance timelines served as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid regulatory shifts or material supply disruptions. The forecasts reflect assumptions regarding technological adoption and market demand. A model refresh is warranted upon material change in environmental legislation or OEM material specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Automotive Transaxle Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Australia Automotive Glass Fiber Composites Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Heater Core Market