
 Automotive Interior Leather Market | 2026-2036
Automotive Interior Leather Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Interior Leather Market Intelligence
The automotive interior leather supply base is recalibrating around a widening split between full-grain hides for luxury cabins and coated microfiber substrates for mainstream platforms. Lear Corporation leverages its seat systems integration to bundle leather procurement with frame and mechanism contracts, sustaining margin capture across the value chain. BOXMARK Leather GmbH & Co. KG anchors its position through captive tannery operations in Austria and Mexico, controlling hide sourcing through finished cut-and-sew delivery. Eagle Ottawa differentiates via color and grain design studios co-located with Detroit Three styling centers, occupying a niche in North American premium truck and SUV programs.
Automotive interior leather encompasses tanned and finished hides or coated polymer sheets engineered for abrasion resistance, UV stability, and seam strength in vehicle cabin applications, typically measured by Martindale cycle counts and fogging values per OEM specifications. The material serves both tactile luxury positioning and functional durability requirements across seating, steering wheels, and instrument panel surfaces. Synthetic leather categories are capturing volume growth in electric vehicle programs where weight reduction targets intersect with vegan positioning, while natural leather retains margin concentration in above-$60,000 vehicle segments where grain consistency and patina development justify per-meter premiums. The OEM end-user channel dominates absolute consumption, though aftermarket refurbishment demand for aging luxury fleets creates a secondary profit pool with less price sensitivity.
EPA enforcement of volatile organic compound limits under the Clean Air Act shapes finishing chemistry choices for suppliers serving US vehicle assemblers, while ECHA REACH Annex XVII restrictions on hexavalent chromium compel European tanneries to certify alternative tanning processes. The EU Green Deal's embodied carbon tracking requirements are beginning to flow through to leather lifecycle assessments, affecting sourcing decisions for hides and process chemicals. Stakeholders must monitor whether China's national standardization administration extends mandatory volatile substance testing from whole vehicles to interior material certificates, as this would reshape qualification timelines for both domestic and imported leather suppliers.
Market Dynamics
The automotive interior leather sector is bifurcating around a structural tension: luxury OEMs are deepening genuine leather specifications for flagship electric vehicles while mass-market assemblers accelerate synthetic substitution to meet weight and sustainability targets. This divergence is compressing mid-tier suppliers and rewarding those with dual-process capabilities.
Growth Catalysts
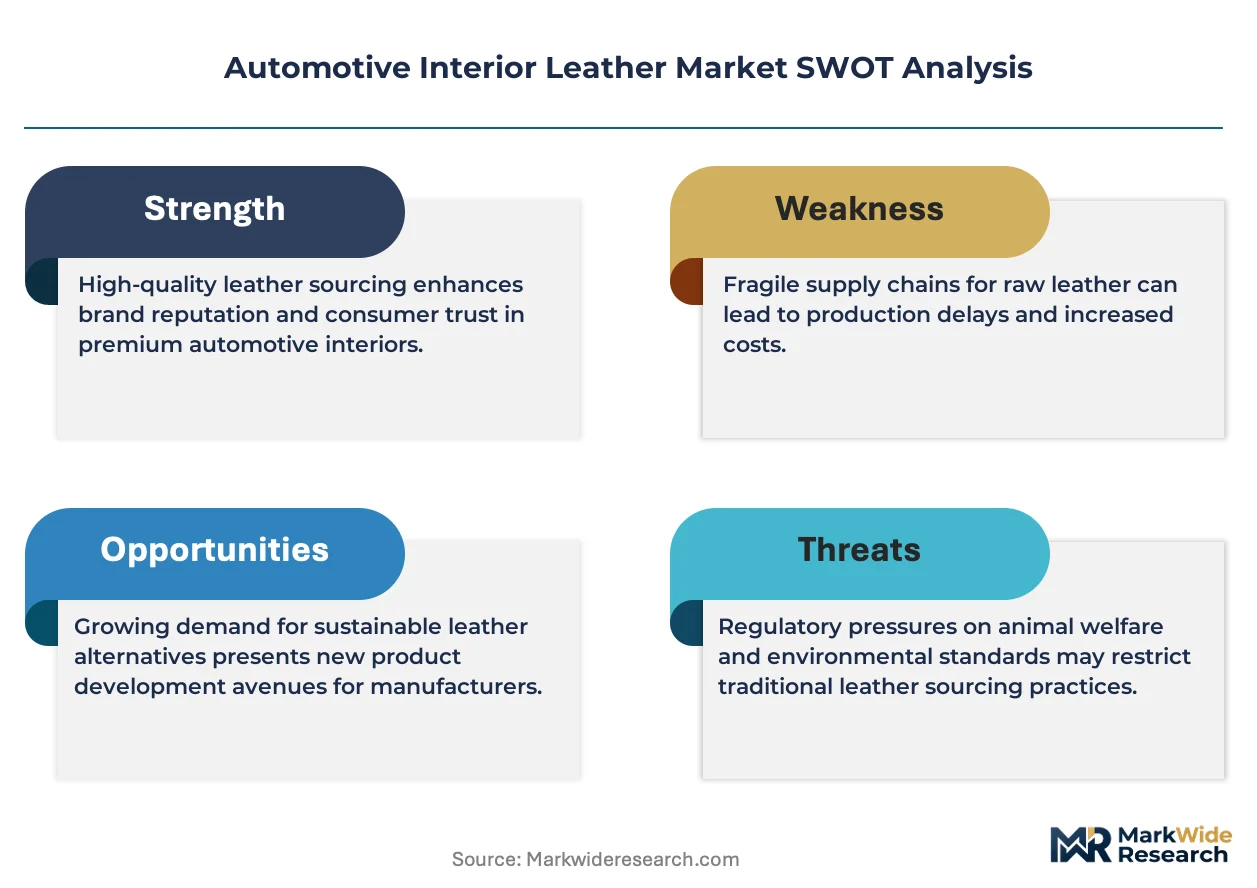
- REACH Annex XVII chromium restrictions:European tanneries are certifying vegetable-tanned and water-based alternatives, creating premium positioning for compliant suppliers in German and Italian luxury vehicle programs.
- Nappa leather specifications:Chinese domestic EV brands are mandating full-grain hides for flagship sedan and SUV interiors, concentrating procurement among tanneries with consistent grain-matching capabilities.
- California Proposition 65 enforcement:Leather finishers serving US West Coast assembly plants are reformulating chemistries to eliminate hexavalent chromium labeling requirements, accelerating compliant process adoption.
Market Restraints
- Hide supply volatility:Bovine raw material costs fluctuate with Brazilian and Argentinian cattle cycle conditions, compressing tannery margins during drought periods.
- Polyurethane microfiber substitution:Coated fabric suppliers in South Korea and Japan are achieving Martindale abrasion parity with split leather at 40% lower per-meter cost.
- ECHA SVHC disclosure requirements:Complex chemical traceability obligations are extending qualification timelines for European tanneries by 8-12 months.
Strategic Opportunities
- India premium passenger vehicle expansion:Domestic OEMs and joint ventures are specifying automotive leather for models above 2 million rupee price points, creating first-mover advantage for tanneries establishing local finishing.
- EU Green Deal embodied carbon tracking:Lifecycle assessment certification is becoming a procurement filter for leather sourced into European assembly, rewarding suppliers with verified low-carbon process chains.
- Blockchain-enabled provenance systems:Integration of hide-to-finished-goods traceability is creating contract differentiation for tanneries serving sustainability-positioned luxury brands.
Industry Challenges
- Chrome-free tanning expertise scarcity:Vegetable-tanning chemistry and process control skills are concentrated among aging workforces in Italian and Austrian tannery clusters, limiting capacity expansion.
- Multi-certification compliance burden:Suppliers must simultaneously maintain VDA 270 fogging, SAE J1885 colorfastness, and OEM-specific flame-retardant protocols, fragmenting quality engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Interior Leather Market |
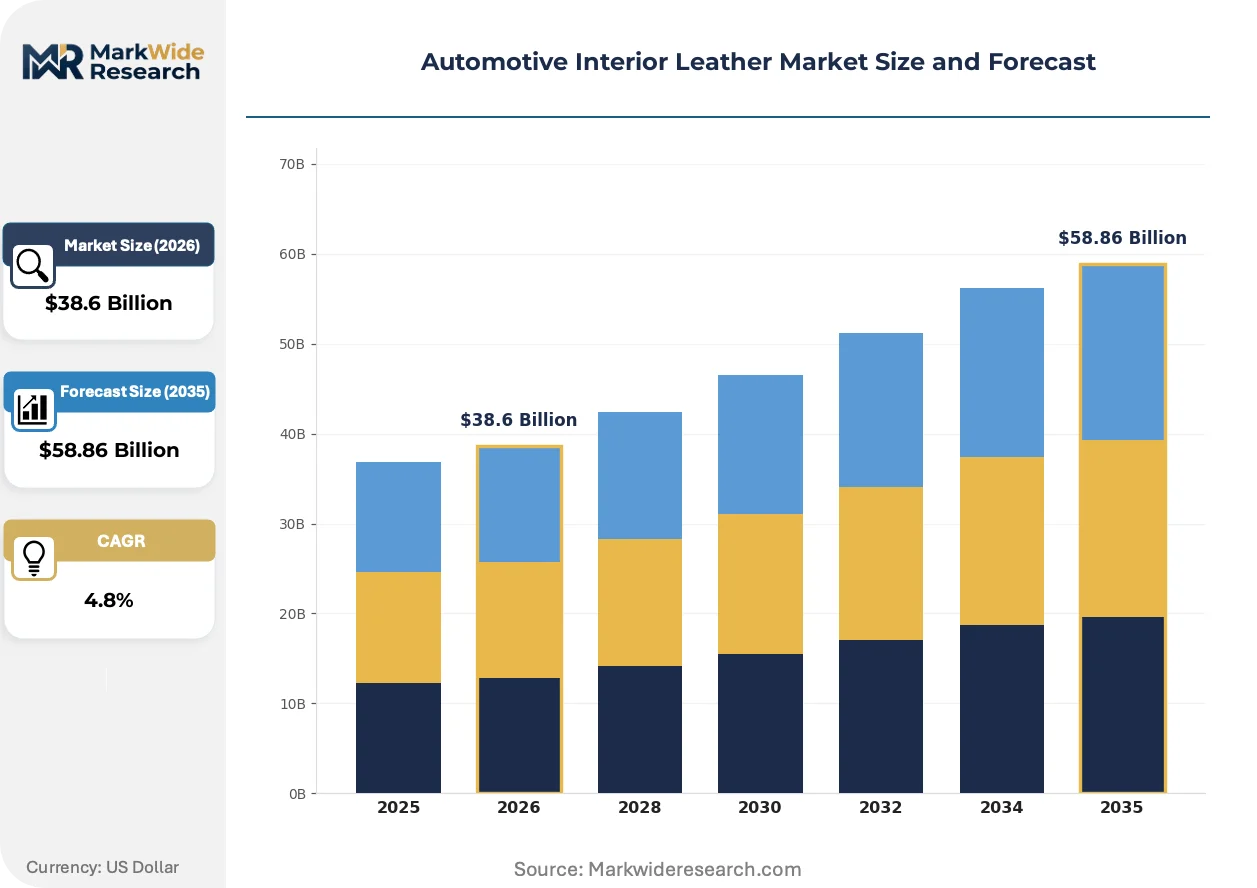
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Leather, Synthetic Leather, Faux Leather, Milled Leather Application: Seat Covers, Interior Trims, Door Panels, Headliners End User: OEMs, Aftermarket, Tier-1 Suppliers, Vehicle Assemblers Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | GST AutoLeather Inc., BOXMARK Leather GmbH & Co. KG, Bader GmbH & Co. KG, Eagle Ottawa, Lear Corporation, Seiren Co., Ltd., DK Leather Corporation, Scottish Leather Group, Wollsdorf Leder Schmidt & Co Ges.m.b.H., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Interior Leather Market Strategic Shifts & Innovations
Process chemistry and digital traceability are converging to redefine competitive advantage in automotive leather supply. Suppliers are repositioning around sustainability verification and material performance parity rather than traditional grain aesthetics alone.
Laser-perforation and embossed grain replication technologies are rewriting the tactile differentiation playbook. Synthetic substrate producers in Japan and Germany are achieving visual and haptic equivalence to full-grain hides at scale. Premium truck and SUV programs in North America are adopting these materials for secondary surfaces while reserving genuine leather for primary seating contact zones.
EPA Clean Air Act VOC enforcement is tightening permissible solvent content in finishing operations. US-based leather suppliers are investing in water-based coating lines and thermal drying recovery systems to maintain NHTSA safety certification eligibility. Cross-state regulatory fragmentation between California Air Resources Board standards and federal thresholds is complicating national distribution strategies.
Fleet refurbishment channels are capturing margin concentration as aging luxury vehicle populations in Germany and the United Kingdom sustain aftermarket leather replacement demand. Independent upholstery specialists are bypassing traditional OEM parts distribution to source directly from tannery cut-and-sew operations. This disintermediation is most advanced in Munich and Stuttgart metropolitan zones where classic vehicle restoration clusters concentrate purchasing power.
Automotive Interior Leather Market Segmentation
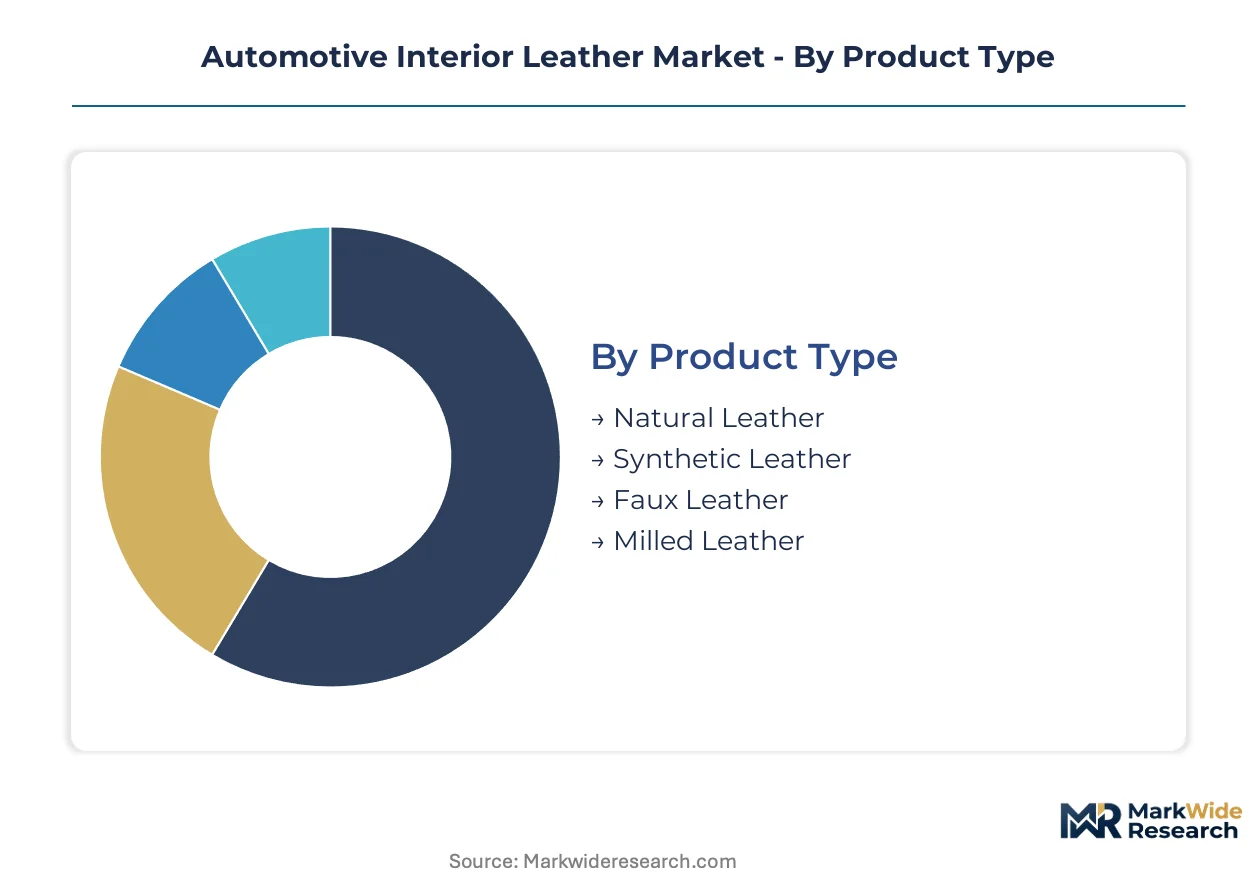
Segmentation in automotive interior leather reveals how certification requirements, cost structures, and supply chain configurations fragment procurement strategies across vehicle programs. Understanding these divides exposes where margin concentrates and where volume growth accelerates.
Product Type:
Certification burdens vary sharply by substrate chemistry. Natural leather demands REACH Annex XVII chromium compliance and VDA 270 fogging certification, while synthetics face SAE J1885 colorfastness and OEM-specific flame-retardant protocols.
- Natural Leather:Full-grain hides tanned with chromium, vegetable, or water-based processes. German luxury OEMs specify vegetable-tanned variants for flagship electric vehicle interiors to satisfy EU Green Deal embodied carbon tracking requirements.
- Synthetic Leather:Polyurethane-coated microfiber substrates engineered for Martindale abrasion parity with split leather. South Korean suppliers are capturing volume in Chinese domestic EV programs where weight reduction targets intersect with vegan positioning.
- Faux Leather:PVC-based coated fabrics with lower specification ceilings. Fleet refurbishment channels in Germany and the United Kingdom source these for cost-sensitive aging luxury vehicle reupholstery.
- Milled Leather:Corrected-grain hides with embossed surface texture. North American premium truck programs specify these for secondary surfaces where tactile differentiation matters less than durability.
Natural leather sits at the top of the volume ranking, with synthetic leather climbing the fastest.
Application:
Surface area exposure and passenger contact frequency determine which applications absorb premium material costs versus synthetic substitution.
- Seat Covers:Largest surface area application with direct skin contact requirements. Chinese EV brands above 2 million rupee price points mandate Nappa leather for flagship sedan and SUV primary seating.
- Interior Trims:Dashboard and console surfaces requiring UV stability and heat resistance. California Proposition 65 enforcement is driving reformulation of finish chemistries for West Coast assembly plant supply.
- Door Panels:Secondary contact zones where grain-matching consistency across vehicle cabin matters. Italian tannery clusters dominate supply for German luxury OEM programs.
- Headliners:Overhead surfaces with lower abrasion exposure. Synthetic substrates from Japanese producers are displacing leather in this application due to 40% lower per-meter cost.
Seat covers command the highest material specification intensity, with interior trims expanding most quickly as cabin digitization increases surface complexity.
End User:
Procurement authority and volume scale separate direct OEM relationships from intermediary-dependent channels.
- OEMs:Vehicle manufacturers with direct tannery contracts for flagship programs. BMW and Mercedes-Benz leverage genuine leather appointments to differentiate luxury electric vehicle interiors.
- Aftermarket:Independent refurbishment specialists bypassing traditional parts distribution. Munich and Stuttgart restoration clusters concentrate purchasing power for classic vehicle leather replacement.
- Tier-1 Suppliers:Seat systems integrators bundling leather procurement with frame and mechanism contracts. Lear Corporation sustains margin capture across the value chain through this model.
- Vehicle Assemblers:Contract manufacturers with specification authority delegated by brand owners. Mexican assembly plants serving US markets face dual EPA and California Air Resources Board compliance obligations.
OEMs dominate absolute consumption value, with aftermarket channels gaining share fastest as aging luxury fleets sustain refurbishment demand.
Distribution Channel:
Channel selection reflects order scale, customization requirements, and geographic proximity to tanning operations.
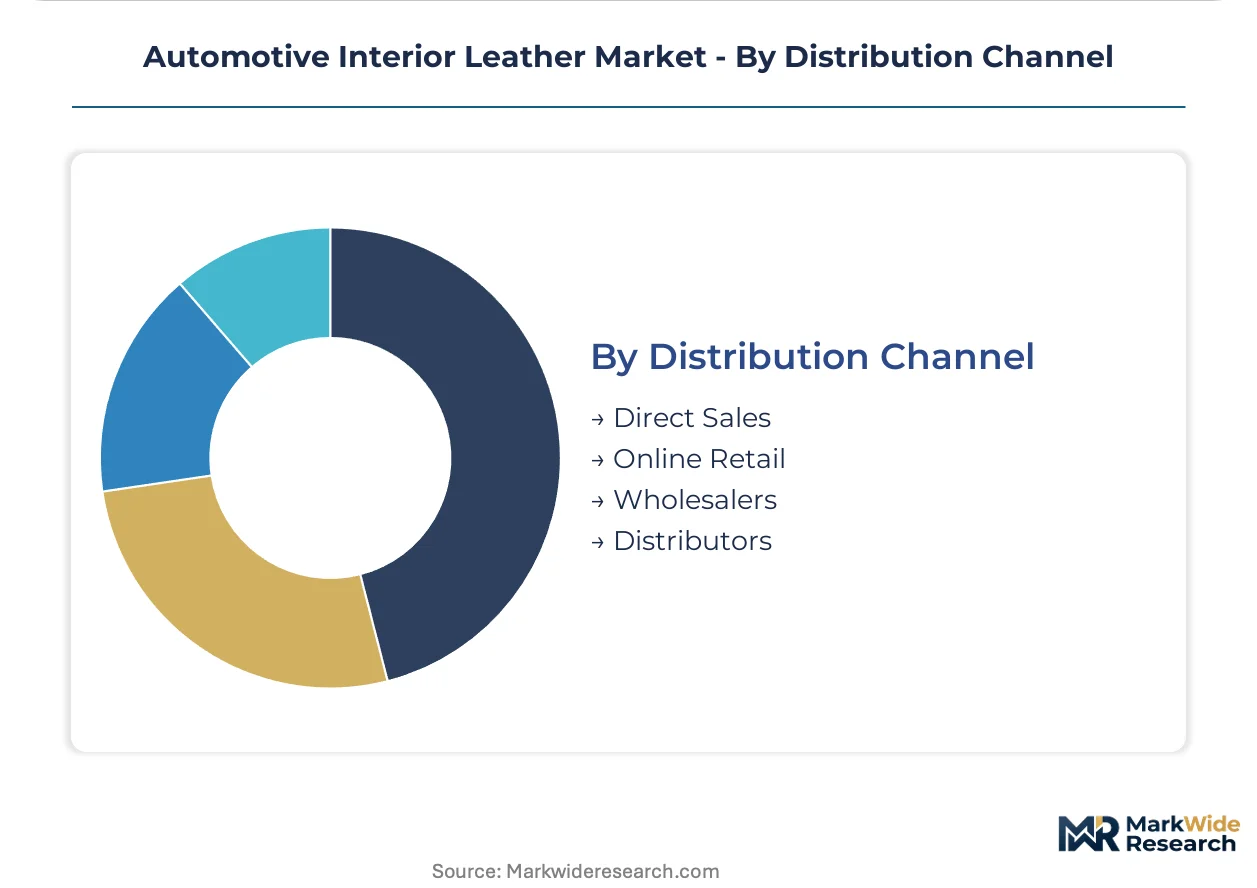
- Direct Sales:Tannery-to-OEM contracts for high-volume programs with dedicated grain and color specifications. BOXMARK Leather operates captive tannery direct delivery from Austria and Mexico.
- Online Retail:Digital platforms serving independent upholstery specialists and restoration shops. Blockchain-enabled provenance systems are creating contract differentiation for sustainability-positioned suppliers.
- Wholesalers:Inventory-holding intermediaries for standard grain and color lots. Indian premium passenger vehicle expansion is creating first-mover opportunity for tanneries establishing local finishing partnerships.
- Distributors:Regional logistics specialists managing multi-OEM fulfillment. Cross-state regulatory fragmentation between US federal and California standards complicates national distribution strategies.
Direct sales anchor the highest value flows, with online retail expanding most quickly as disintermediation accelerates in European restoration clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium leather specification authority while China absorbs the fastest volume expansion, creating divergent sourcing dynamics across the automotive interior leather value chain.
United States
Domestic EV manufacturers and premium truck assemblers sustain demand for full-grain hides in above-$60,000 vehicle segments. EPA Clean Air Act VOC enforcement shapes finishing chemistry choices for suppliers serving assembly plants in Michigan, Ohio, and the Southeast. Detroit maintains its historic role as a styling coordination hub where color and grain design studios cluster near OEM engineering centers.
Germany
BMW and Mercedes-Benz luxury electric vehicle programs are deepening genuine leather appointments for flagship interiors. ECHA REACH Annex XVII chromium restrictions compel tanneries to certify vegetable-tanned and water-based alternatives, accelerating compliant process adoption. Bavaria and Baden-Württemberg host the dominant tannery clusters supplying German luxury OEM programs with consistent grain-matching capabilities.
China
Domestic EV brands above 2 million yuan price points mandate Nappa leather for flagship sedan and SUV primary seating. The national standardization administration is evaluating whether to extend mandatory volatile substance testing from whole vehicles to interior material certificates. Yangtze River Delta manufacturing zones concentrate procurement activity among tanneries serving premium passenger vehicle expansion.
India
Domestic OEMs and joint ventures are specifying automotive leather for models above 2 million rupee price points, creating first-mover advantage for establishing local finishing operations. BIS certification requirements govern material qualification timelines for suppliers entering the market. Tamil Nadu and Maharashtra automotive manufacturing corridors attract tannery investment seeking proximity to assembly plant demand.
Mexico
Assembly plants serving US markets face dual EPA and California Air Resources Board compliance obligations for leather finishing operations. BOXMARK Leather operates captive tannery direct delivery from Mexican facilities to support North American supply chain integration. Nuevo León and the Bajío Region concentrate seat systems manufacturing that bundles leather procurement with frame and mechanism contracts.
Automotive Interior Leather Market Key Industry Players
Top-tier vendors anchor premium OEM direct contracts, while mid-scale specialists occupy refurbishment and regional assembly niches. The supply base stratifies around tanning process capabilities, grain design coordination proximity, and seat systems integration depth. Three archetypes dominate: captive tannery operators controlling hide-to-finished-goods chains, styling-integrated specialists co-located with OEM design centers, and systems integrators bundling material procurement with mechanism supply. Consolidation pressure favors M&A among chrome-free tanning capability holders, while geographic expansion targets Indian and Mexican manufacturing corridors.
Among European captive tannery operators, BOXMARK Leather GmbH & Co. KG and Wollsdorf Leder Schmidt & Co Ges.m.b.H. exemplify the integrated production archetype with Austria-based operations. Lear Corporation represents the systems integration model, leveraging seat assembly contracts to capture leather procurement margin across the value chain. Eagle Ottawa occupies a position within the styling-proximity tier, maintaining design studio coordination with North American premium truck and SUV programs.
| Leading Market Players |
|---|
| GST AutoLeather Inc. |
| BOXMARK Leather GmbH & Co. KG |
| Bader GmbH & Co. KG |
| Eagle Ottawa |
| Lear Corporation |
| Seiren Co., Ltd. |
| DK Leather Corporation |
| Scottish Leather Group |
| Wollsdorf Leder Schmidt & Co Ges.m.b.H. |
| Others |
Cost & Logistics Intelligence
EU Green Deal embodied carbon tracking gates both qualified supply and premium-tier pricing access, forcing tanneries to certify low-carbon process chains before bidding on German luxury EV programs. Buyers without verified lifecycle assessments face exclusion from flagship procurement, while compliant suppliers command per-meter premiums for vegetable-tanned hides.
Pricing Analysis
Capacity additions in South Korea and Japan are reshaping price floors for synthetic substrates, compressing mid-tier natural leather margins. Pricing stratifies across full-grain Nappa specifications, corrected-grain milled alternatives, and polyurethane-coated microfiber tiers. Cost compression in mass-market applications is intensifying because South Korean suppliers achieve Martindale abrasion parity at lower per-meter cost. Fleet refurbishment specialists in European restoration clusters show least price sensitivity, while Chinese domestic EV assemblers drive hardest volume negotiations.
Supply Chain Analysis
Bovine hide supply rests on Brazilian and Argentinian cattle cycle conditions, with Italian and Austrian tannery clusters controlling premium finishing expertise. Raw material dependencies include chromium sulfate for conventional tanning, vegetable tannins from mimosa and quebracho extracts, and water-based polyurethane resins for synthetic substrates. Single-source vulnerability concentrates in chrome-free tanning chemistry knowledge held by aging workforces. Distribution runs through captive tannery direct delivery for OEM programs and wholesaler intermediaries for aftermarket refurbishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story: Nappa leather specifications for Chinese flagship EVs concentrate procurement among grain-matching specialists, rewarding process control investments over volume scale.
For Market Incumbents: Lock in chrome-free tanning capacity through targeted acquisition of Italian and Austrian tannery clusters facing workforce succession gaps. Defend margin position by embedding blockchain-enabled provenance systems into OEM direct contracts before sustainability verification becomes table stakes. For New Entrants and Emerging Players: Independent upholstery specialists in Munich and Stuttgart restoration clusters represent the most penetrable buyer archetype, bypassing traditional OEM parts distribution. Establish cut-and-sew partnerships with Austrian tanneries to source compliant hides, then build direct digital channels to capture aftermarket margin concentration. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale chrome-free tanning specialists because ECHA REACH Annex XVII compliance timelines extend qualification barriers for new entrants. Target tanneries with verified vegetable-tanning process chains and existing VDA 270 fogging certification. Watch for China's national standardization administration extending mandatory volatile substance testing to interior material certificates as the inflection signal triggering consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tanning Certification | ECHA REACH Annex XVII compliance opens German luxury EV procurement to certified tanneries. |
| Blockchain Provenance Integration | Hide-to-finished-goods traceability creates contract differentiation for sustainability-positioned suppliers. |
| Indian Local Finishing Expansion | BIS certification proximity captures premium passenger vehicle demand above 2 million rupee price points. |
| Mexican Captive Tannery Operations | Dual EPA and California Air Resources Board compliance supports North American supply chain integration. |
| Laser-Perforation Technology Deployment | Embossed grain replication achieves tactile equivalence to full-grain hides at secondary surface applications. |
Research Approach
Coverage spans Germany, China, the United States, India, and Mexico, with primary inputs from each market cluster. The analysis combines structured interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, tannery operations managers, and dealership refurbishment specialists with secondary validation from vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from listed seat systems integrators. Bottom-up volume modeling triangulates against top-down value estimates derived from OEM program specifications and tannery capacity disclosures.
Granularity extends to vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by average selling price evolution. Industry-specific forecast inputs include hide supply cycle conditions in Brazil and Argentina, REACH Annex XVII compliance adoption curves among European tanneries, and Chinese domestic EV brand platform rollout schedules.
Underlying measurement precision varies by segment; OEM direct sales carry tighter precision than aftermarket refurbishment channels due to contract visibility. Forecasts reflect assumptions about regulatory enforcement continuity, hide supply cycle stability, and synthetic substrate performance parity advancement. Material deviation in Chinese standardization administration testing mandates, Brazilian drought severity, or South Korean microfiber capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
USA Automotive and Aircraft Interior Genuine Leather Aftermarket Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Flooring Market