
 Global Automotive Power Sliding Door Market | 2026-2036
Global Automotive Power Sliding Door Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Power Sliding Door Market Intelligence
Software integration and sensor-based feature development is rewriting the value chain for vehicle access systems. This shift moves margin away from purely mechanical hardware toward intelligent control modules. Magna International Inc. leverages its full-system expertise to capitalize on this trend. Continental AG specializes in the electronic control units and sensor technologies that underpin these advanced features. Brose Group competes by offering highly integrated mechatronic solutions for vehicle doors and liftgates.
An automotive power sliding door is an automated system comprising a motor, drive mechanism, electronic control unit (ECU), and safety sensors. The system's core function is to provide hands-free or one-touch operation for vehicle side doors, often incorporating anti-pinch technology to prevent injury. While Minivans and MPVs constitute a mature base, the luxury SUV segment represents a significant growth vector. Electromechanical technology remains the standard, but newer motorized systems are gaining share in the premium vehicle category.
Safety and performance standards are governed by regulations from bodies like the NHTSA in the United States and through directives such as the EU's General Safety Regulation. These rules mandate features like anti-pinch force limits and obstruction detection, directly influencing system design and component choice. For suppliers, the strategic imperative is navigating the choice between developing sophisticated sensor fusion capabilities for autonomous-ready vehicles and optimizing cost-effective drive units for high-volume platforms.
Market Dynamics
The fundamental market dynamic is the value chain's pivot from mechanical hardware to software-defined features. This transition prioritizes intelligent control modules and advanced sensor integration, shifting profit pools toward suppliers with deep electronics and software expertise over traditional metal-forming specialists.
Growth Catalysts
- Luxury Segment Adoption:The expansion of power sliding doors into high-margin luxury SUVs and premium electric vehicles provides a significant growth vector beyond the mature minivan market.
- Safety Regulation Mandates:Stricter anti-pinch and obstruction detection requirements, such as those outlined in the EU's General Safety Regulation, compel the integration of more sophisticated sensor systems.
- Chinese Consumer Demand:Strong consumer preference in China for vehicles with advanced convenience features and high-tech content directly stimulates OEM adoption on new platforms.
Market Restraints
- High System Cost:The combined expense of motors, electronic control units, and sensor arrays limits the application of these systems in cost-sensitive, high-volume economy vehicle segments.
- Increased Vehicle Weight:The addition of drive mechanisms, motors, and structural reinforcements for power sliding doors adds mass, which can negatively impact vehicle fuel efficiency or electric range.
- Semiconductor Dependencies:A heavy reliance on microcontrollers and specific sensor ICs creates supply chain vulnerabilities, exposing production schedules to component shortages in the global electronics market.
Strategic Opportunities
- Light Commercial Vehicle (LCV) Integration:Adapting power sliding door technology for urban delivery vans and commercial shuttles presents an opportunity to improve driver ergonomics and operational efficiency.
- Advanced Accessibility Solutions:Developing systems tailored to meet emerging accessibility standards for elderly and disabled users in markets like Japan and Europe could open a specialized, high-value segment.
- Sensor Fusion for Autonomy:Integrating door sensor data with the vehicle's central ADAS processor enables context-aware actions, such as preventing a door from opening into traffic.
Industry Challenges
- Software Integration Complexity:Ensuring secure, reliable, and bug-free operation of the door control module within increasingly complex vehicle operating systems is a major software engineering hurdle for suppliers.
- Navigating Divergent Standards:Component suppliers face added development costs and testing cycles to certify systems that comply with differing regulatory requirements from the NHTSA in the US and various authorities in Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Power Sliding Door Market |
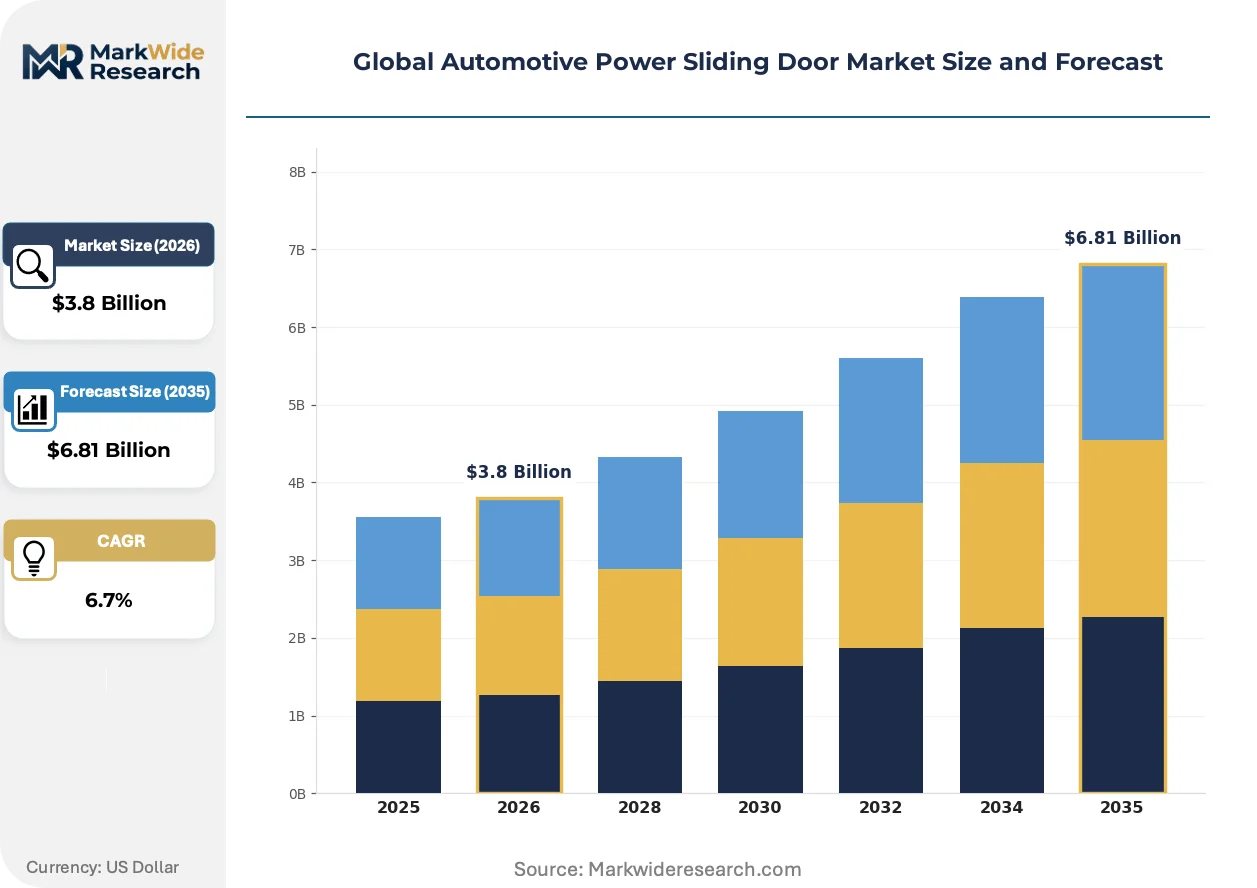
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Sliding Door, Double Sliding Door, Dual Sliding Door, Convertible Door Technology: Electromechanical, Electromagnetic, Hydraulic, Pneumatic, Motorized Vehicle Type: Minivan, MPV, Commercial Van, Luxury Vehicle, Electric Vehicle, SUV End User: Vehicle Manufacturers, Tier-1 Component Suppliers, Aftermarket Dealers, Automotive Repair Shops |
| Companies Covered | Magna International Inc., Continental AG, Brose Group, Kiekert AG, BorgWarner Inc., Lear Corporation, Aisin Seiki Co., Ltd., Johnson Electric Holdings Limited, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Power Sliding Door Market Strategic Shifts & Innovations
The evolution of vehicle access is being defined by the fusion of sensors with intelligent software. This creates a shift from simple automated actuation to context-aware systems that anticipate user needs and integrate seamlessly with the vehicle's broader digital ecosystem.
Gesture recognition and capacitive touch surfaces are key product innovations. These non-contact interfaces allow users to operate doors with a simple hand wave or touch, and are being adopted rapidly by premium automotive brands. This technology is rendering obsolete traditional physical handles and push-button switches, enabling cleaner vehicle exterior designs and a more modern user experience.
Regulatory frameworks are directly influencing system architecture. The EU's General Safety Regulation, for instance, imposes strict force limitations and detection capabilities for automated systems to prevent injury. This is forcing suppliers to invest heavily in more reliable sensor technologies, including ultrasonic and non-contact capacitive sensors, particularly for vehicles like MPVs and SUVs sold within the European Union.
Consumer expectations for seamless digital integration are altering system requirements. This shift disrupts the concept of a standalone door module, demanding connectivity with smartphone applications for remote operation, status checks, and personalization. The trend is most visible in technologically advanced markets such as South Korea and China, where digital key functionality is a powerful purchasing consideration for new car buyers.
Global Automotive Power Sliding Door Market Segmentation
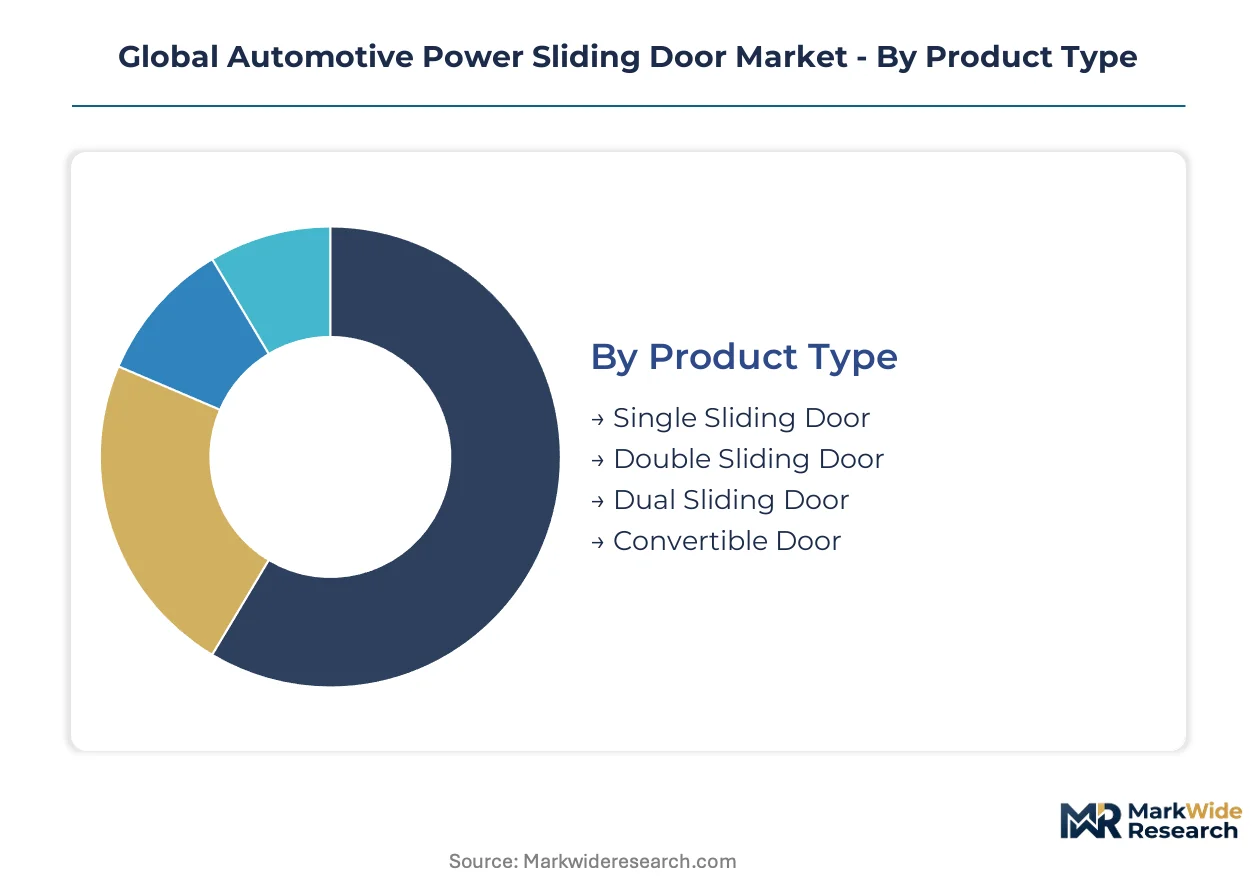
The automotive power sliding door market exhibits diverse operational characteristics across its various segments. Understanding these distinctions allows for targeted product development and strategic market penetration. Each segment presents unique engineering challenges and consumer expectations.
Product Type:
The intensity of after-sales service requirements often distinguishes product types, with more complex door configurations demanding specialized maintenance and diagnostics. These systems integrate multiple sensors and actuators, necessitating precise calibration. Regulatory compliance for safety features also varies by door type.
- Single Sliding Door:This system features one automated door, typically on one side of the vehicle, providing convenient access for passengers or cargo. Demand concentrates in compact MPVs and some commercial vans in Europe, where space efficiency is a primary design consideration.
- Double Sliding Door:Vehicles feature automated sliding doors on both sides, enhancing passenger entry and exit flow, particularly for larger families or shuttle services. This configuration sees strong demand in Asian markets like China and South Korea, driven by consumer preference for maximum convenience.
- Dual Sliding Door:This configuration refers to vehicles with two automated doors, often on opposite sides, allowing for flexible loading and unloading.
- Convertible Door:This advanced design offers multiple opening modes, such as sliding and hinging, providing enhanced versatility for vehicle access.
Single Sliding Door holds the largest share; momentum sits with Double Sliding Door.
Technology:
Cost tiering significantly influences technology adoption, as advanced systems command higher prices but offer superior performance and integration capabilities. Manufacturers balance initial investment with long-term reliability and component availability. System complexity directly impacts manufacturing costs.
- Electromechanical:This technology relies on electric motors and mechanical linkages to operate the door, offering a balance of reliability and cost-effectiveness. Electromechanical systems dominate the mainstream minivan and MPV segments globally, providing robust functionality for high-volume platforms.
- Electromagnetic:Electromagnetic systems use magnetic forces for smooth, silent operation, often found in premium applications where noise reduction is critical. This technology gains traction in luxury vehicles and high-end electric SUVs in markets like Germany and Japan.
- Hydraulic:Hydraulic systems utilize fluid pressure to actuate doors, known for their high force output and smooth motion in heavy-duty applications.
- Pneumatic:Pneumatic systems employ compressed air for door operation, offering rapid response times and suitability for specific commercial vehicle designs.
- Motorized:This broad category encompasses various motor-driven systems, emphasizing automation and often integrating advanced control units for enhanced functionality.
Electromechanical technology retains the largest share, but Motorized systems are expanding most quickly.
Vehicle Type:
Application diversity shapes demand across vehicle types, with specific design requirements driving technology choices. Each vehicle segment prioritizes different attributes, from passenger capacity to cargo volume. Safety regulations also vary by vehicle category.
- Minivan:Minivans represent a mature segment for power sliding doors, where these systems are a standard feature for family convenience and accessibility.
- MPV:Multi-Purpose Vehicles (MPVs) heavily integrate power sliding doors to facilitate passenger loading and unloading, particularly in urban settings across Europe and Asia.
- Commercial Van:Power sliding doors enhance operational efficiency for commercial vans, improving access for delivery personnel in logistics fleets.
- Luxury Vehicle:Luxury vehicles incorporate power sliding doors as a premium convenience feature, often paired with advanced sensor integration and aesthetic finishes. Demand for this feature is strong in high-end SUVs and luxury sedans in markets like the United States and China.
- Electric Vehicle:Electric vehicles leverage power sliding doors to emphasize futuristic design and enhanced user experience, often integrating with digital key systems. This segment's growth in Europe and North America drives innovation in lightweight and energy-efficient door mechanisms.
- SUV:Sport Utility Vehicles increasingly adopt power sliding doors to differentiate premium models and offer greater accessibility for families.
Minivans hold a significant market share, while Electric Vehicles show the steepest expansion trajectory.
End User:
Customer type dictates procurement patterns and service expectations, influencing supplier engagement strategies. Different end-users require varied levels of integration support and after-sales service. The distribution channels also diverge based on the end-user's operational model.
- Vehicle Manufacturers:These entities procure power sliding door systems for integration into new vehicle production lines, requiring high-volume supply and stringent quality control.
- Tier-1 Component Suppliers:Tier-1 suppliers develop and assemble complete power sliding door modules, delivering integrated solutions directly to vehicle manufacturers.
- Aftermarket Dealers:Aftermarket dealers provide replacement parts and installation services for power sliding door systems in existing vehicles.
- Automotive Repair Shops:These shops perform diagnostics, maintenance, and repair on power sliding door components for vehicle owners.
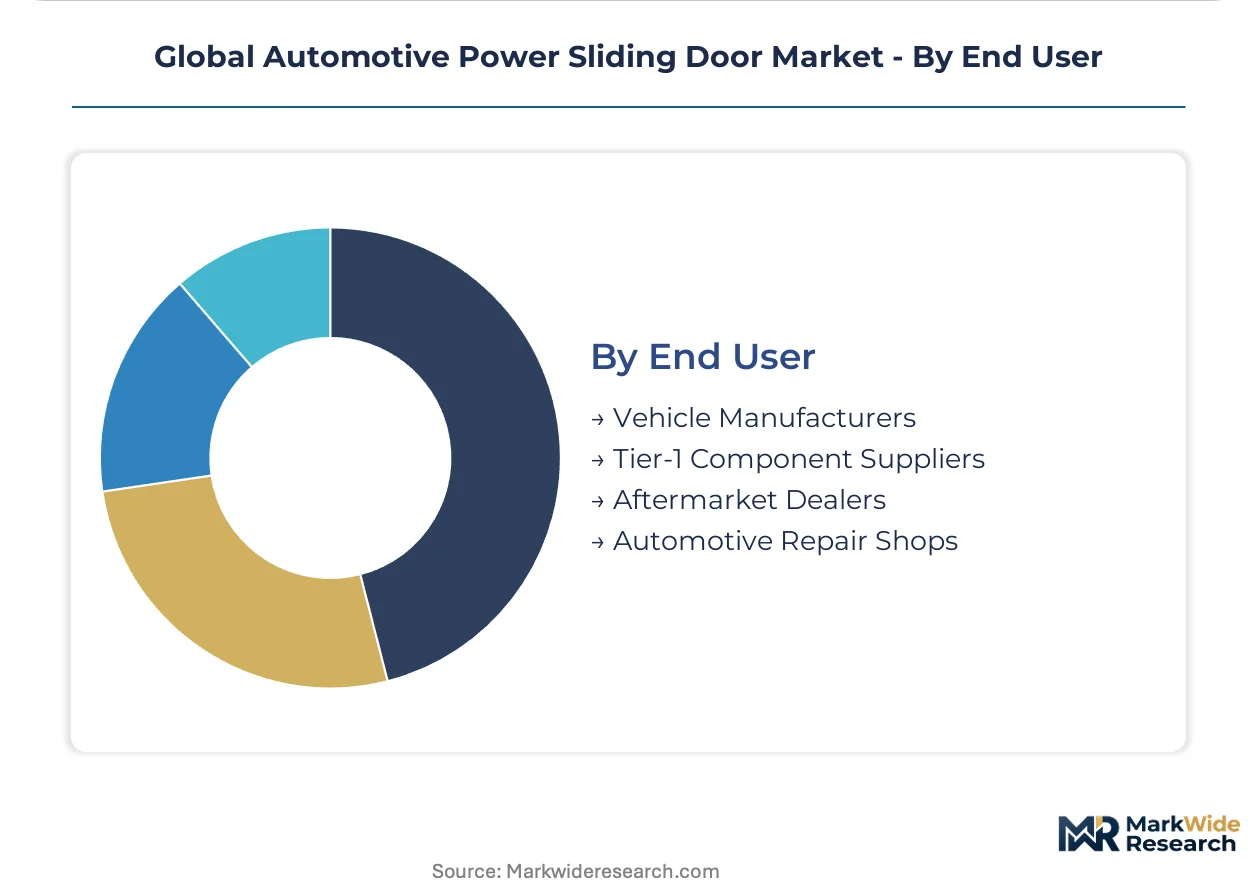
Vehicle Manufacturers command the largest portion of the market, with Tier-1 Component Suppliers gaining share through integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in premium segments demonstrate lower price elasticity for advanced features, contrasting sharply with high price sensitivity in economy vehicle markets. This dynamic shapes regional demand for automotive power sliding doors, with luxury-focused economies driving feature integration. Consumer preferences for convenience and safety also vary significantly by geography.
China
Strong consumer preference for feature-rich vehicles drives demand for double sliding doors in MPVs and luxury SUVs. GB standards mandate specific safety features, influencing local design. Manufacturing hubs like Shanghai and Guangzhou are experiencing rapid integration of advanced door systems into new electric vehicle platforms.
Germany
The market prioritizes sophisticated engineering and silent operation, favoring electromagnetic systems in premium and luxury car segments. The EU's General Safety Regulation sets strict anti-pinch force limits, fostering sensor innovation. Automotive clusters in Bavaria and Baden-Württemberg develop high-precision mechatronic door solutions.
United States
Demand is strong in the minivan and luxury SUV segments, where convenience and safety are paramount for families. NHTSA regulations govern door system performance, including obstruction detection and force limitations. Detroit and its surrounding areas innovate in vehicle access systems, particularly for electric vehicle applications.
Japan
Accessibility solutions for an aging population boost demand for advanced power sliding doors, especially in MPVs and commercial shuttles. METI directives encourage the development of user-friendly and safe automotive components. The Tokyo metropolitan area and Kansai region integrate gesture control and smart access technologies.
South Korea
Technologically advanced consumers drive demand for seamless digital integration and features like digital key functionality. The country's national automotive safety standards influence the adoption of advanced sensor systems. Manufacturing centers in Ulsan and Gyeonggi Province develop next-generation door modules for export and domestic premium vehicles.
Global Automotive Power Sliding Door Market Key Industry Players
Vertically integrated suppliers and specialized mechatronics providers split the market for automotive power sliding doors, reflecting a focus on both component depth and system breadth. This structure favors entities with deep expertise in both hardware and software integration. Three strategic archetypes emerge: full-system integrators offering comprehensive solutions, electronic control unit specialists, and mechatronic component manufacturers. Strategic partnerships and targeted technology licensing are dominant competitive moves to secure market share.
Within the full-system integrator archetype, Magna International Inc. exemplifies a broad portfolio approach, offering comprehensive automotive solutions. Germany-based Continental AG represents a leading position in electronic control units and sensor technologies, crucial for advanced door systems. Brose Group, also from Germany, anchors the highly integrated mechatronic solutions segment, providing comprehensive door and liftgate systems for various vehicle platforms. These entities collectively demonstrate the diverse specialization required in the evolving vehicle access market.
| Leading Market Players |
|---|
| Magna International Inc. |
| Continental AG |
| Brose Group |
| Kiekert AG |
| BorgWarner Inc. |
| Lear Corporation |
| Aisin Seiki Co., Ltd. |
| Johnson Electric Holdings Limited |
| Denso Corporation |
| Others |
Cost & Logistics Intelligence
Shanghai's advanced manufacturing clusters, integrating electronic components and mechatronic systems, significantly influence downstream pricing power for power sliding door modules. This concentration of specialized production capacity dictates cost structures for global automotive OEMs.
Pricing Analysis
After-sales service and spare parts sales constitute a significant revenue tier, contributing to the lifetime value of power sliding door systems. Transactional per-unit pricing dominates new vehicle integration, with price differentiation driven by component quality grades and customization levels for luxury applications. Pricing pressure stems from OEM demands for cost optimization in high-volume minivan segments. Economy vehicle segments exhibit the highest price sensitivity, while luxury vehicle buyers demonstrate lower elasticity for advanced features.
Supply Chain Analysis
Specialized Tier-1 component suppliers like Magna International and Brose Group hold significant contract manufacturing capacity across Germany, China, and Japan. The supply chain relies heavily on microcontrollers, sensor ICs, and specialized motors as critical raw material dependencies. Single-source vulnerability for specific electronic components represents a structural supply chain risk. Distribution runs through direct supply agreements with vehicle manufacturers and their assembly plants globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is currently experiencing a high-growth disruption, driven by the rapid expansion of power sliding door technology into luxury SUVs and electric vehicles. The integration of advanced anti-pinch sensors, mandated by evolving safety regulations, further accelerates this transformation.
For Market Incumbents: Entrench core market share by investing in next-generation sensor fusion capabilities for autonomous-ready vehicles. Focus on deepening vertical integration of critical electronic control units to mitigate semiconductor dependencies, a named threat. Consolidate relationships with key OEM partners through joint development programs for advanced accessibility solutions, leveraging existing production footprints in Europe and Asia.
For New Entrants and Emerging Players: The Light Commercial Vehicle (LCV) segment in emerging markets presents significant underpenetration for power sliding door technology. Target urban delivery vans and commercial shuttles with cost-effective, robust motorized systems. A go-to-market angle could involve offering modular, easily customizable solutions that prioritize operational efficiency and driver ergonomics for fleet operators.
For Investors and Strategic Acquirers: Long-term, this sits as a technology integration play because intelligent control modules and advanced sensor systems are redefining vehicle access. Target specialized mechatronic component manufacturers or software houses with deep expertise in sensor fusion and digital key integration. The signal to watch is the widespread adoption of Level 3 autonomous driving features, which will necessitate highly integrated and context-aware door systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Develop common door module architectures across vehicle platforms for cost efficiency. |
| Software-Defined Vehicle Investment | Integrate door control modules seamlessly into central vehicle operating systems. |
| Geographic Manufacturing Footprint | Expand production capabilities in high-growth regions like China for electric vehicles. |
| Sensor Fusion Development | Advance anti-pinch and obstruction detection using multi-modal sensor data. |
| Aftermarket Service Network | Build a robust global network for diagnostics and replacement of complex door systems. |
Research Approach
The analysis maps power sliding door systems across minivan, SUV, and commercial vehicle sub-sectors, each validated through extensive primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, and automotive aftermarket distributors. Secondary data sources include vehicle production databases, IHS Markit registration data, and relevant regulatory body publications such as NHTSA and the EU's General Safety Regulation. This approach ensures robust bottom-up and top-down triangulation of market figures.
The forecast holds current regulatory trajectories and technological adoption rates fixed, while varying economic growth scenarios and consumer preference shifts across the analysis window. The analytical framework models market volume and value across product type, technology, vehicle type, end-user, and regional production clusters. Compound Annual Growth Rates were derived through a regression analysis of historical data and projected future trends, with key inputs including electric vehicle production forecasts and luxury SUV sales projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by new technology entrants or vertically integrated OEMs would shift outcomes. Component shortages, particularly for semiconductors, represent a specific risk factor that could revise forecasts. Quarterly review of electric vehicle production rates and new safety regulation implementations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market