
 Truck Parking Air Conditioner Market | 2026-2036
Truck Parking Air Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Parking Air Conditioner Market Insights
Direct current inverter technology is reconfiguring compressor efficiency standards for truck parking air conditioners, enabling variable-speed cooling without engine idling. Thermo King leverages its transport refrigeration heritage to sustain premium positioning in North American fleet channels. Webasto anchors European aftermarket distribution through integrated heating and cooling platforms. Midea competes aggressively on manufacturing scale, supplying cost-optimized rooftop units to Asian logistics operators.
Truck parking air conditioners are self-contained climate control systems designed for sleeper cab cooling during mandated rest periods, typically operating on 12V/24V DC or battery banks with cooling capacities between 2,000 and 8,000 BTU. Rooftop units dominate fleet procurement due to space efficiency and factory integration compatibility, while split systems attract retrofit demand from owner-operators seeking discrete compressor placement. Battery-powered configurations represent the fastest-expanding power source segment as lithium-ion pack costs decline and truck OEMs pre-wire electric architectures.
The EPA SmartWay program and state-level anti-idling statutes in California, New York, and Texas directly shape product certification requirements and fleet procurement criteria for parking air conditioners. NHTSA sleeper berth regulations and European Union CO2 standards for heavy-duty vehicles create parallel compliance obligations that manufacturers must satisfy for market access. Stakeholders should monitor battery energy density improvements and charging infrastructure deployment along major freight corridors to anticipate shifts in unit specification and power source preference.
Market Dynamics
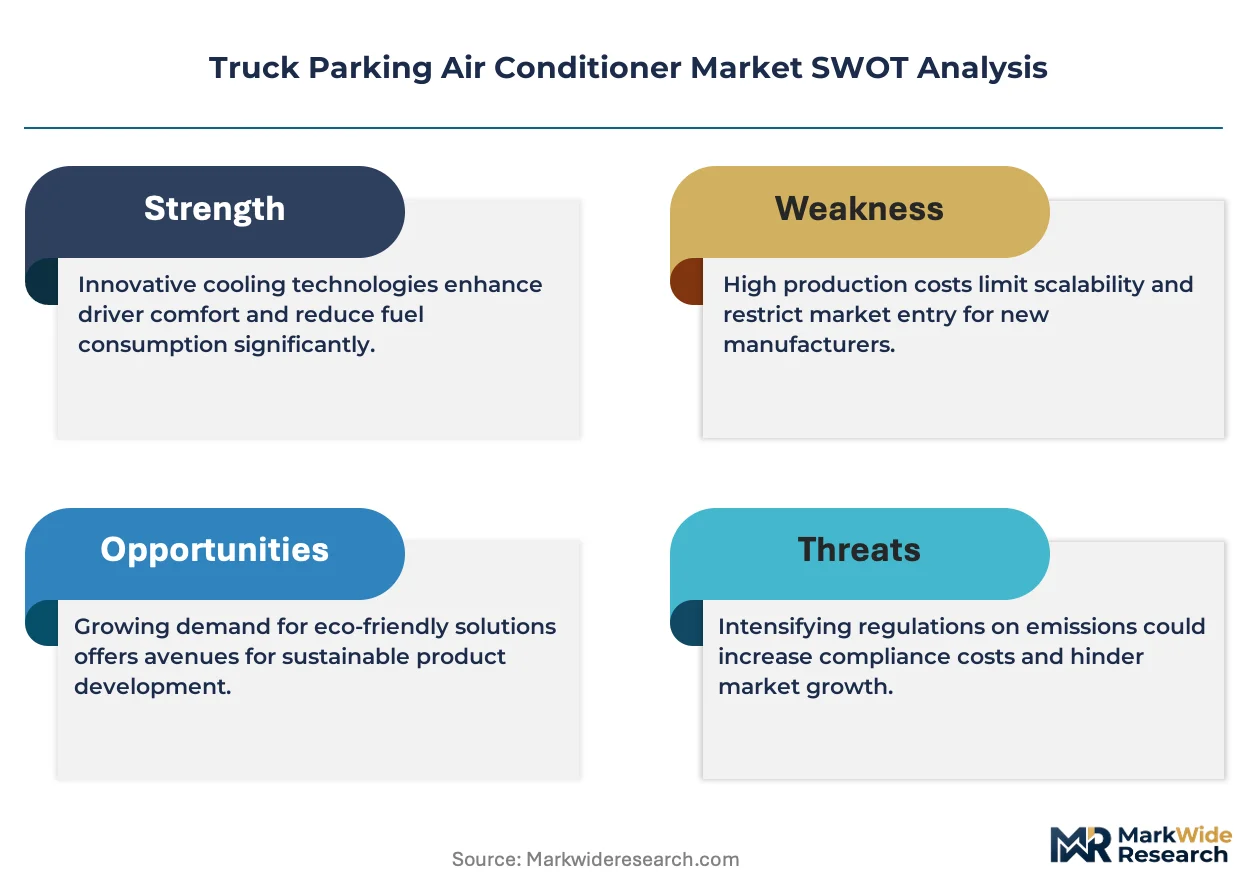
Idle-reduction mandates from the EPA and state-level agencies are compressing diesel auxiliary power unit demand while battery-electric architectures create new specification requirements for sleeper cab climate systems.
Growth Catalysts
- EPA SmartWay Certification:Fleet procurement criteria now prioritize verified idle-reduction technologies, accelerating replacement cycles for legacy diesel APUs in long-haul trucking operations across the United States.
- Lithium-Ion Cost Decline:Battery pack economics below critical thresholds enable viable all-electric cooling configurations for owner-operators previously locked out of electrified alternatives.
- California Air Resources Board (CARB):The state's Advanced Clean Trucks regulation creates compliance deadlines that force fleet operators to pre-specify zero-emission parking HVAC on new tractor orders.
Market Restraints
- Copper and Rare Earth Volatility:Compressor motor windings and permanent magnet materials expose manufacturers to commodity price swings that compress margin structures on fixed-price fleet contracts.
- Integrated OEM Pre-Wiring:Factory-installed electrical architectures from Freightliner, Volvo, and PACCAR create switching costs that lock aftermarket suppliers out of new vehicle specification channels.
- Range Anxiety in Cold Climates:Battery degradation during sub-zero overnight cooling cycles limits addressable market penetration in northern tier states and Canadian provinces.
Strategic Opportunities
- Texas Interstate Corridors:Underpenetrated fleet density along I-10 and I-35 freight routes offers first-mover positioning for charging-infrastructure-integrated cooling service models.
- Solar-Assisted Hybrid Systems:Photovoltaic roof integration converges with DC inverter compressors to extend battery autonomy without shore power dependency at rest stops.
- Inflation Reduction Act Tax Credits:Commercial clean vehicle incentives reduce effective acquisition costs for battery-electric units, accelerating payback calculations against diesel APUs.
Industry Challenges
- Thermal Management Engineering Talent:Scarce expertise in refrigerant circuit design for variable-speed DC compressors constrains product development velocity at mid-tier suppliers.
- Multi-Standard Certification Burden:Simultaneous SAE, UL, and CARB verification timelines extend time-to-revenue for new product introductions by 8-14 months.
- Legacy Fleet Retrofit Integration:Electrical load calculations and alternator upgrades for 2015-2019 model year sleeper cabs create installation complexity that slows aftermarket penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Parking Air Conditioner Market |
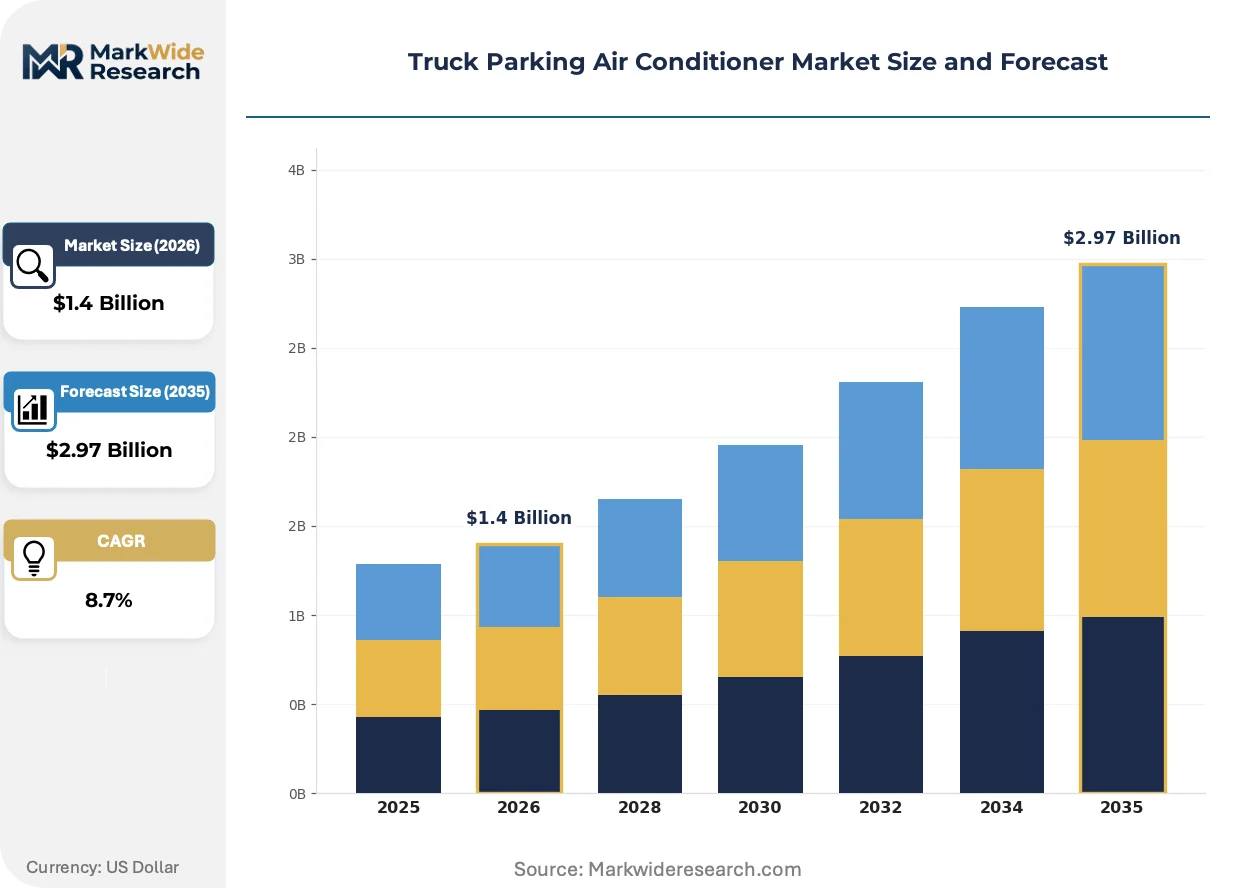
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Split System, Rooftop Unit, Portable Unit, Direct Expansion End User: Fleets, Owner-Operators, Logistics Companies, Transportation Services Installation Type: Onboard Installation, Standalone Installation, Retrofit Installation, Integrated Systems Power Source: Electricity, Solar Power, Battery-Powered, Hybrid Systems |
| Companies Covered | Midea, Thermo King, Haier, Eberspächer, Webasto, Hisense, Dometic, Bergstrom, Gree, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Parking Air Conditioner Market Trends and Innovations
Power source diversification and intelligent thermal management are redefining product architectures, with software-controlled variable-speed operation displacing binary on-off compressor cycling across fleet and aftermarket channels.
Direct current inverter compressors are hybridizing conventional refrigeration cycles with automotive-grade motor control algorithms. Thermo King and Webasto have integrated these units into rooftop packages that modulate cooling output against battery state-of-charge. Long-haul fleets operating California-Texas lanes are specifying these systems at accelerating rates, compressing the addressable market for fixed-speed legacy units.
The EPA's updated heavy-duty greenhouse gas standards and companion state anti-idling statutes in New York and Texas are forcing refrigerant selection changes. Manufacturers must transition from high-GWP hydrofluorocarbons to lower-impact alternatives to maintain fleet eligibility under SmartWay partnership agreements. This regulatory pressure most acutely affects split-system suppliers serving the owner-operator retrofit segment, where certification documentation gaps previously allowed non-compliant installations.
Fleet procurement departments are consolidating vendor relationships around full-lifecycle service agreements rather than transactional unit purchases. Large operators now demand predictive maintenance telemetry and guaranteed uptime clauses that transfer operational risk to suppliers. This behavioral shift is most visible among refrigerated carriers in the Midwest, where cargo spoilage exposure amplifies cooling system reliability premiums in contract negotiations.
Truck Parking Air Conditioner Market Segmentation
Product architecture and power source selection in truck parking air conditioners determine compliance pathways, installation economics, and fleet procurement criteria. Segmentation reveals how specification choices cascade through regulatory certification, aftermarket service models, and total cost of ownership calculations for long-haul operators.
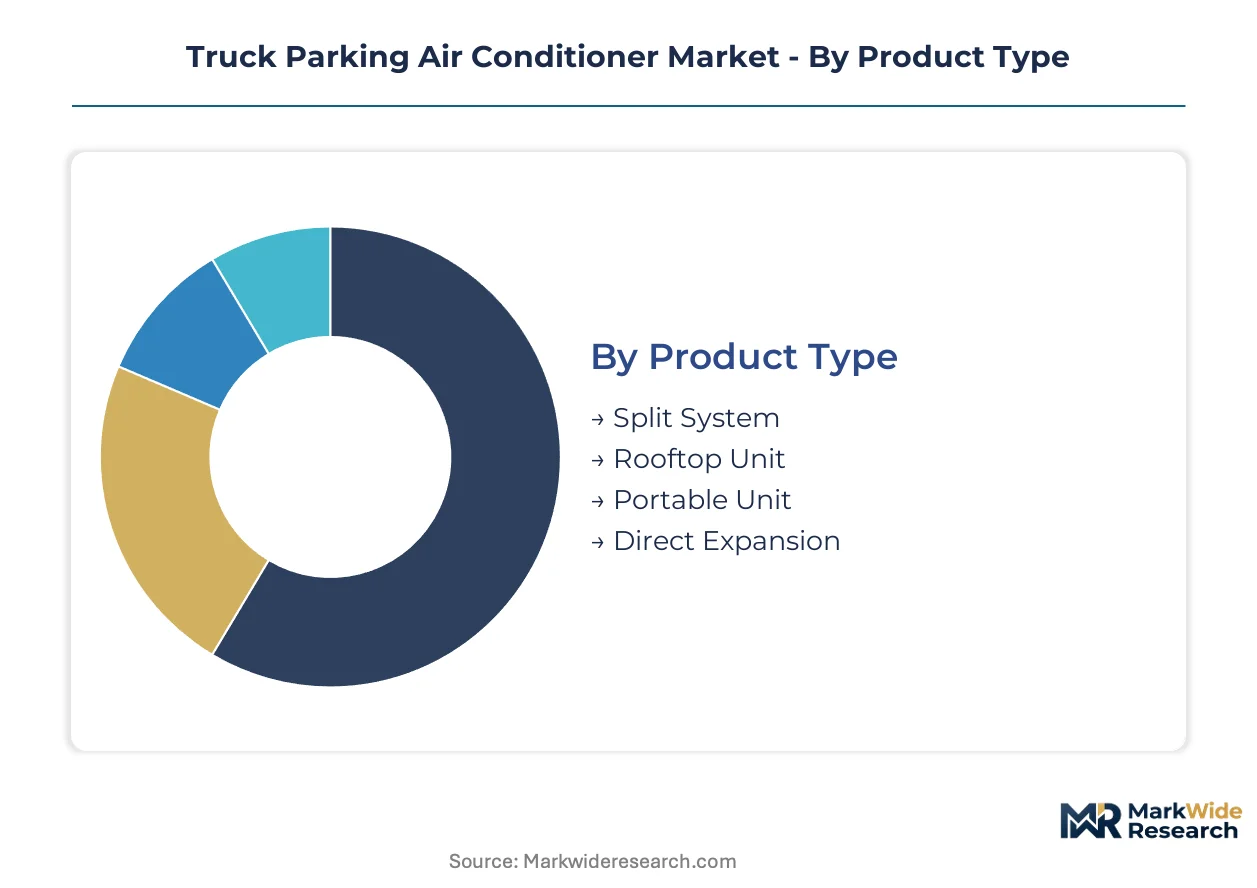
Product Type:
Physical form factors span factory-integrated rooftop assemblies through field-retrofit split configurations, each carrying distinct spatial trade-offs and electrical integration requirements.
- Rooftop Unit:Self-contained weatherproof housings mount directly to sleeper cab roof structures with sealed refrigerant circuits. Factory pre-wiring compatibility from Freightliner and Volvo Trucks concentrates procurement in North American fleet channels seeking warranty-aligned installations.
- Split System:Separated evaporator and condenser modules enable flexible compressor placement in chassis compartments or external lockers. Demand concentrates among German and California owner-operators retrofitting legacy vehicles where rooftop load limits or height restrictions apply.
- Portable Unit:Temporary cooling devices with shore power dependency or internal battery packs for intermittent cab conditioning.
- Direct Expansion:Refrigerant-based systems with minimal air handling for space-constrained sleeper berths in regional delivery trucks.
Established volume favors rooftop units; emerging adoption favors split systems.
End User:
Procurement authority and capital deployment patterns separate centralized fleet purchasing from dispersed individual operator decisions.
- Fleets:Large-scale operators with standardized vehicle specifications and consolidated vendor agreements. EPA SmartWay certification requirements and CARB compliance deadlines in California drive replacement cycles for diesel APUs with verified idle-reduction alternatives.
- Owner-Operators:Independent drivers purchasing single-unit installations with personal capital or equipment financing. Lithium-ion cost thresholds below critical price points are unlocking battery-electric configurations previously inaccessible to this segment.
- Logistics Companies:Third-party carriers managing temperature-sensitive cargo with reliability premiums in contract negotiations.
- Transportation Services:Passenger-oriented operators with distinct duty cycles and cab occupancy patterns.
Fleet procurement dominates unit volumes; owner-operators are expanding most quickly as battery economics improve.
Installation Type:
Integration timing relative to vehicle lifecycle creates diverging technical requirements and margin structures for suppliers.
- Integrated Systems:Factory-installed during tractor assembly with OEM electrical architectures and warranty alignment. Pre-wiring from PACCAR and Volvo Trucks creates switching costs that lock aftermarket suppliers out of new vehicle specification channels.
- Retrofit Installation:Aftermarket deployment to in-service vehicles requiring alternator upgrades and load calculations. Complexity with 2015-2019 model year sleeper cabs slows penetration in legacy fleet segments.
- Onboard Installation:Permanent mounting with dedicated electrical feeds and structural reinforcement.
- Standalone Installation:Self-powered units with minimal vehicle integration for temporary or transferable deployment.
Integrated systems capture premium pricing; retrofit installations offer volume depth in aging fleet replacement.
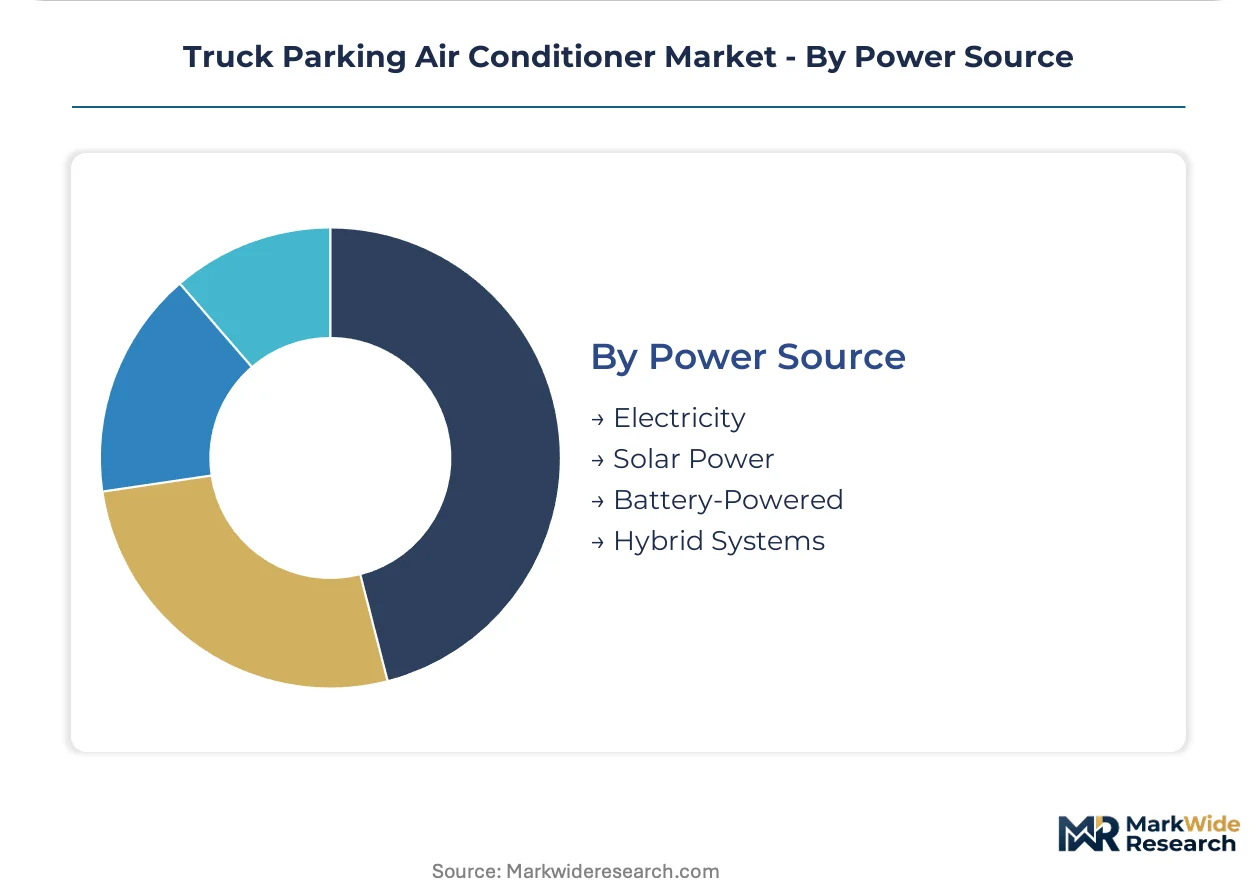
Power Source:
Energy architecture selection determines regulatory compliance, operational autonomy, and infrastructure dependency for overnight cooling.
- Battery-Powered:Lithium-ion packs with DC inverter compressors enabling variable-speed cooling without engine operation or shore power. Declining cell costs and truck OEM pre-wiring of electric architectures are accelerating specification on new tractor orders.
- Hybrid Systems:Dual-source configurations combining battery storage with solar photovoltaic or auxiliary generator input. Photovoltaic roof integration extends autonomy without rest stop infrastructure dependency.
- Electricity:Shore power dependency at equipped truck stops with limited operational flexibility.
- Solar Power:Direct photovoltaic-to-compressor systems with weather-dependent output consistency.
Battery-powered configurations gain share fastest; hybrid systems attract solar-assisted demand in sun-belt freight corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export idle-reduction cooling systems to California and Texas freight corridors, while Chinese producers supply cost-optimized rooftop units to Southeast Asian logistics operators expanding refrigerated transport capacity.
United States
Long-haul fleet density along I-10 and I-35 corridors drives specification of battery-electric parking HVAC on new tractor orders. EPA SmartWay certification requirements and CARB compliance deadlines in California force accelerated diesel APU replacement cycles. Dallas-Fort Worth freight terminals concentrate procurement authority for national fleet operators standardizing zero-emission cooling configurations.
Germany
Owner-operators in Baden-Württemberg and Bavaria retrofit split-system units to comply with diesel auxiliary power restrictions tightening across federal transport regulations. KBA vehicle certification mandates shape product development timelines for European aftermarket channels. Stuttgart automotive supplier networks feed component specialization into DC inverter compressor manufacturing for export markets.
China
Yangtze River Delta logistics operators specify rooftop units for factory-integrated installation on domestic heavy-duty truck production lines. MIIT new energy vehicle standards and dual carbon goals accelerate battery-electric architecture adoption in sleeper cab designs. Shanghai port freight concentration creates demand clusters for solar-assisted hybrid cooling systems serving container haulage corridors.
India
Maharashtra and Gujarat long-haul operators adopt portable and split-system configurations for aftermarket retrofit of legacy sleeper cabs lacking factory electrical pre-wiring. BIS appliance certification requirements and state-level anti-idling enforcement in Delhi-NCR shape product compliance specifications. Mumbai-Pune expressway freight density concentrates owner-operator demand for cost-optimized cooling alternatives to engine idling.
Japan
Kanto region refrigerated carriers specify integrated rooftop units with predictive maintenance telemetry for temperature-sensitive cargo protection. METI energy efficiency standards and JIS certification requirements filter supplier participation in fleet procurement channels. Tokyo-Osaka freight corridor operators consolidate vendor relationships around full-lifecycle service agreements transferring operational risk to equipment suppliers.
Truck Parking Air Conditioner Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement authority split between fleet procurement departments and dispersed owner-operator decisions. The vendor base clusters around three strategic archetypes: transport refrigeration heritage brands, integrated heating-cooling platform suppliers, and manufacturing-scale cost optimizers. Consolidation pressure intensifies through strategic partnerships linking battery suppliers with compressor specialists, plus geographic expansion into underpenetrated interstate freight corridors.
Within the manufacturing-scale tier, Midea and Gree represent cost-optimized production capabilities serving Asian logistics operators with high-volume rooftop specifications. Thermo King anchors the transport refrigeration heritage archetype, leveraging cold-chain expertise into premium fleet channel positioning. Webasto occupies the integrated platform specialist position, bundling heating and cooling functions for European aftermarket distribution networks.
| Leading Market Players |
|---|
| Midea |
| Thermo King |
| Haier |
| Eberspächer |
| Webasto |
| Hisense |
| Dometic |
| Bergstrom |
| Gree |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese lithium-ion cell manufacturing is compressing module pricing and enabling battery-electric parking air conditioner configurations previously locked at premium tiers, while simultaneously pressuring margin structures for compressor suppliers in Germany and Japan who face utilization-driven pricing aggression from integrated Asian producers.
Pricing Analysis
DC inverter compressor technology commands a 25-35% premium over fixed-speed legacy units, while next-generation variable-speed algorithms with predictive battery management are pricing at a further 15-20% markup. Three-tier pricing structure across premium, standard, and economy levels separates fleet-certified rooftop units with full-lifecycle service agreements from retrofit split systems and portable shore-power alternatives. Pricing pressure stems from copper and rare earth commodity volatility that compresses fixed-price contract margins. Owner-operators exhibit highest price sensitivity due to single-unit capital deployment constraints, while refrigerated carriers prioritize reliability premiums over acquisition cost.
Supply Chain Analysis
Permanent magnet materials for compressor motors draw from Chinese rare earth processing, Japanese magnet fabrication, and German motor winding specialization. Lithium-ion cells, copper tubing, and aluminum heat exchangers constitute critical input dependencies. Single-source vulnerability concentrates in rare earth separation and refining capacity. Distribution runs through OEM factory-direct channels for integrated systems and specialized aftermarket distributors for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of thermal management engineers fluent in refrigerant circuit design for variable-speed DC compressors is constraining product development velocity and creating acquisition premiums for specialist engineering teams, particularly as fleet procurement consolidates around predictive maintenance capabilities.
For Market Incumbents: Harden service agreement capabilities by embedding predictive maintenance telemetry into fleet contracts, transferring operational risk and creating switching costs against emerging competitors. Deepen backward integration into lithium-ion pack assembly to secure cell supply and capture margin compression from commodity volatility. Threat substitution from integrated OEM pre-wiring architectures demands channel control investment in factory specification relationships. For New Entrants and Emerging Players: Establish a beachhead in Texas interstate corridor fleet retrofits where charging infrastructure deployment lags and battery-electric configurations face range anxiety headwinds in summer heat. Target split-system demand among California owner-operators navigating CARB compliance deadlines with legacy vehicle fleets. Go-to-market through specialized HVAC distributors with installation training capabilities rather than direct fleet sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet service agreement providers with predictive maintenance platforms and guaranteed uptime clauses. Long-term viability centers on suppliers with certified compliance across EPA SmartWay, CARB, and emerging state anti-idling statutes. Acquisition target archetype: mid-tier compressor specialists with DC inverter engineering talent and UL/SAE certification completion. Signal to watch: battery energy density improvements enabling overnight cooling without shore power dependency in sub-zero climates.| Strategic Initiative | Industry Significance |
|---|---|
| DC Inverter Platform Standardization | Thermo King and Webasto consolidate variable-speed compressor architectures across fleet and aftermarket channels. |
| Battery Supply Agreement | Long-term lithium-ion cell offtake secures cost positioning against commodity volatility for electric architecture suppliers. |
| Predictive Maintenance Telemetry Integration | Fleet procurement departments now demand uptime guarantees transferring operational risk to equipment vendors. |
| Solar-Assisted Hybrid Development | Photovoltaic roof integration extends battery autonomy without rest stop infrastructure dependency in sun-belt corridors. |
| Multi-Standard Certification Investment | Simultaneous EPA SmartWay, CARB, and UL verification accelerates time-to-revenue for new product introductions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, CARB certification databases, and fleet procurement documentation. Primary interviews engaged product managers at transport refrigeration suppliers, fleet maintenance directors at refrigerated carriers, and aftermarket distributors serving owner-operator channels. Secondary validation drew from NHTSA sleeper berth regulations, EU heavy-duty CO2 standards, and SmartWay partnership agreements. Bottom-up unit shipment estimates triangulate against top-down fleet replacement cycle analysis.
Forecast inputs span power source migration from diesel APUs to battery-electric architectures, product type evolution from fixed-speed to variable-speed compressor platforms, and installation timing between factory-integrated and retrofit deployment. Segmentation dimensions modeled include product architecture, end-user procurement authority, power source configuration, and regional regulatory cluster. CAGRs derive from fleet replacement cycle compression under state anti-idling deadlines and lithium-ion cost trajectory assumptions. Industry-specific inputs incorporate truck OEM pre-wiring penetration rates and charging infrastructure deployment along major freight corridors.
Macroeconomic conditions sit as an overlay; deviation in freight volume indices, diesel-electric fuel spreads, or battery raw material costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology cost curves. Cross-checking against fleet capital expenditure surveys and truck stop electrification deployment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market