
 Automotive Cowl Screen Market | 2026-2036
Automotive Cowl Screen Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cowl Screen Market Outlook
Electric vehicle platform architecture is pivoting toward integrated thermal-acoustic modules that merge cowl screens with HVAC intake systems. Valeo leverages its climate-system expertise to anchor integrated cowl-HVAC contracts with European EV platforms. Magna International sustains manufacturing scale across North American light-truck programs where cowl screen durability requirements exceed passenger-car specifications. Denso competes on thermal-management technology leadership, extending its powertrain cooling know-how into cabin air-path components.
An automotive cowl screen is a protective panel positioned at the base of a vehicle's windshield that seals the engine compartment from the passenger cabin while directing airflow into the HVAC intake and preventing debris infiltration; modern variants incorporate multi-layer polymer composites with acoustic-damping densities of 1,200-1,600 g/m² and integrated water-management channels to meet NVH targets below 40 dB at highway speeds. Plastic cowl screens lead volume across mass-market platforms where injection-molded PP-EPDM blends balance cost and weather resistance, while composite segments capture margin pools in luxury architectures that specify carbon-fiber-reinforced thermoplastics for stiffness-to-weight optimization. The installation dimension reveals structural tension: integrated factory-fit assemblies dominate OEM procurement, yet replacement demand through aftermarket providers accelerates as vehicle aging fleets expand serviceable unit opportunities.
The EPA enforces noise emission thresholds under 40 CFR Part 205 that compel acoustic-optimized cowl designs, while the EU's REACH regulation restricts phthalate plasticizers in polymer formulations and the ECE R118 framework governs fire-resistance properties of passenger-compartment materials. NHTSA's FMVSS 302 flammability standard shapes material selection for US-bound production, creating divergence in regional specification sheets that suppliers must navigate. Stakeholders should monitor how battery-electric vehicle thermal-management architectures redefine cowl screen functional requirements as cabin heating loads shift from engine-waste heat to active heat-pump systems.
Market Dynamics
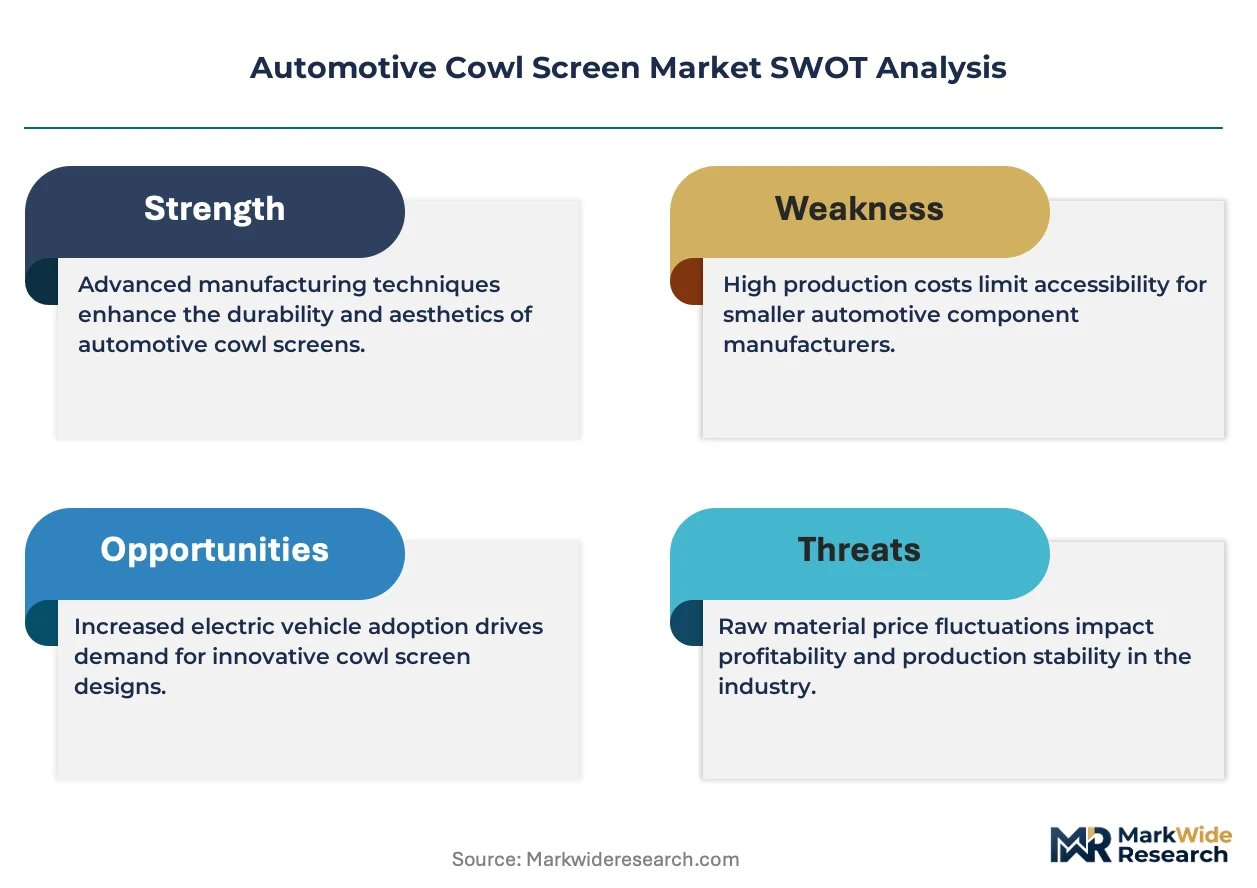
Electric vehicle thermal architectures are eliminating engine-bay waste heat, forcing cowl screens to integrate active heating elements and heat-pump air-path management that legacy designs never required.
Growth Catalysts
- EPA Noise Emission Mandates:The 40 CFR Part 205 threshold enforcement compels acoustic-optimized multi-layer polymer designs across US-bound vehicle programs.
- EV Platform Thermal Integration:Battery-electric architectures require cowl-HVAC module convergence, expanding functional specifications and per-unit value capture.
- Germany Supplier Clustering:Stuttgart and Munich Tier-1 ecosystems concentrate specialized acoustic-thermal engineering talent and integrated assembly capability.
Market Restraints
- Polypropylene-EPDM Feedstock Volatility:Propylene monomer pricing swings directly compress margin on mass-market injection-molded cowl screen production.
- REACH Phthalate Restrictions:ECHA's plasticizer limitations force reformulation cycles that extend qualification timelines by 12-18 months for European supply contracts.
- Structural Substitution Risk:Full front-end module integration by large Tier-1s threatens to absorb cowl screen functionality into broader thermoplastic assemblies.
Strategic Opportunities
- India Passenger Vehicle Localization:PLI scheme incentives for automotive component manufacturing create first-mover advantage for acoustic-thermal module suppliers establishing Pune and Chennai operations.
- Active Heat-Pump Convergence:Integration of PTC heating elements and refrigerant routing channels into cowl structures opens premium pricing tiers for thermal-management specialists.
- Aftermarket Service Channel Expansion:Aging vehicle fleets in the United States and Germany accelerate replacement demand through independent service networks and digital parts platforms.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:NVH-acoustic coupled with CFD thermal modeling requires specialized CAE engineers that OEM engineering centers and suppliers compete to recruit.
- Dual-Certification Burden:Parallel FMVSS 302 and ECE R118 fire-resistance testing extends validation costs and timeline for suppliers serving both US and EU markets.
- Legacy ICE-EV Platform Parallelism:Engineering teams must maintain distinct cowl screen specifications for internal-combustion and electric programs simultaneously, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cowl Screen Market |
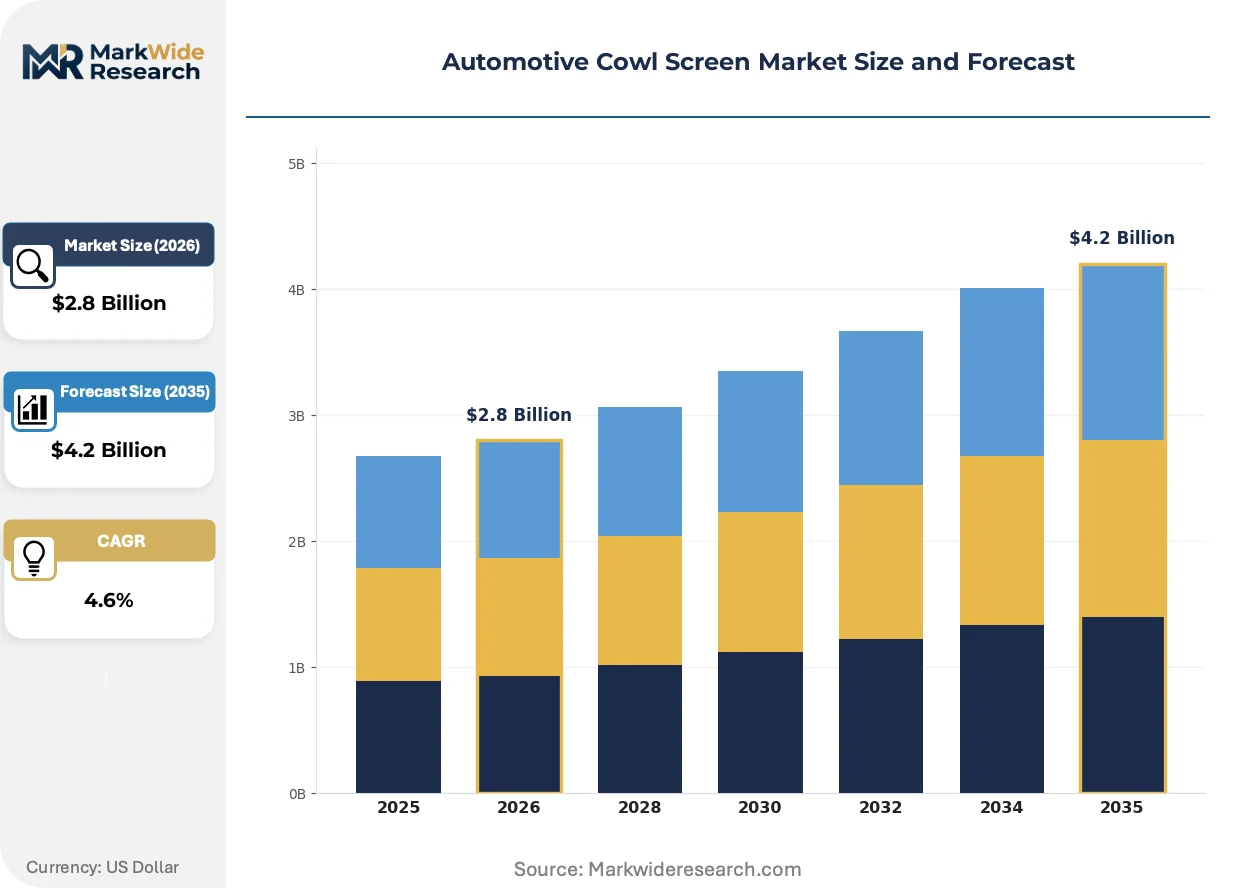
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Composite, Glass End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Installation: Integrated, Semi-Integrated, Add-on, Replacement Distribution Channel: Online, Retail Stores, Distributors, Direct Sales |
| Companies Covered | Plastic Omnium, Toyoda Gosei, Valeo, Montaplast, CIE Automotive, Magna International, Futaba Industrial, Inoac Corporation, Denso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cowl Screen Market Strategic Shifts
Material science breakthroughs and regulatory compression are converging to redefine cowl screen architecture, with acoustic performance and thermal functionality now inseparable design requirements rather than additive features.
Multi-layer polymer composites with tuned acoustic-damping densities are consolidating around integrated water-management and air-path routing functions that previously required separate components. Premium EV platforms in Germany and the United States specify these consolidated modules as standard, compressing supplier tier structures and elevating engineering-content barriers for mid-scale competitors. The technology is consolidating thermal-acoustic-NVH engineering into single-source contracts that favor vertically integrated climate-system specialists.
REACH chemical compliance frameworks and EPA emission thresholds are tightening material specifications simultaneously across Atlantic markets. ECHA's phthalate restrictions and 40 CFR Part 205 noise mandates force dual-track reformulation and acoustic engineering that smaller suppliers struggle to fund. European luxury OEMs are responding fastest, embedding compliance-driven material selection into platform architecture decisions earlier in development cycles than mass-market manufacturers.
Buyer concentration among EV-native OEMs is compressing supplier negotiation leverage and accelerating specification lock-in earlier in program development. Direct platform partnerships with climate-system integrators are displacing discrete component procurement through traditional Tier-1 intermediaries. This pattern is most visible in California and Bavaria, where Tesla and BMW Group exercise consolidated sourcing authority over acoustic-thermal module specifications.
Automotive Cowl Screen Market Segmentation
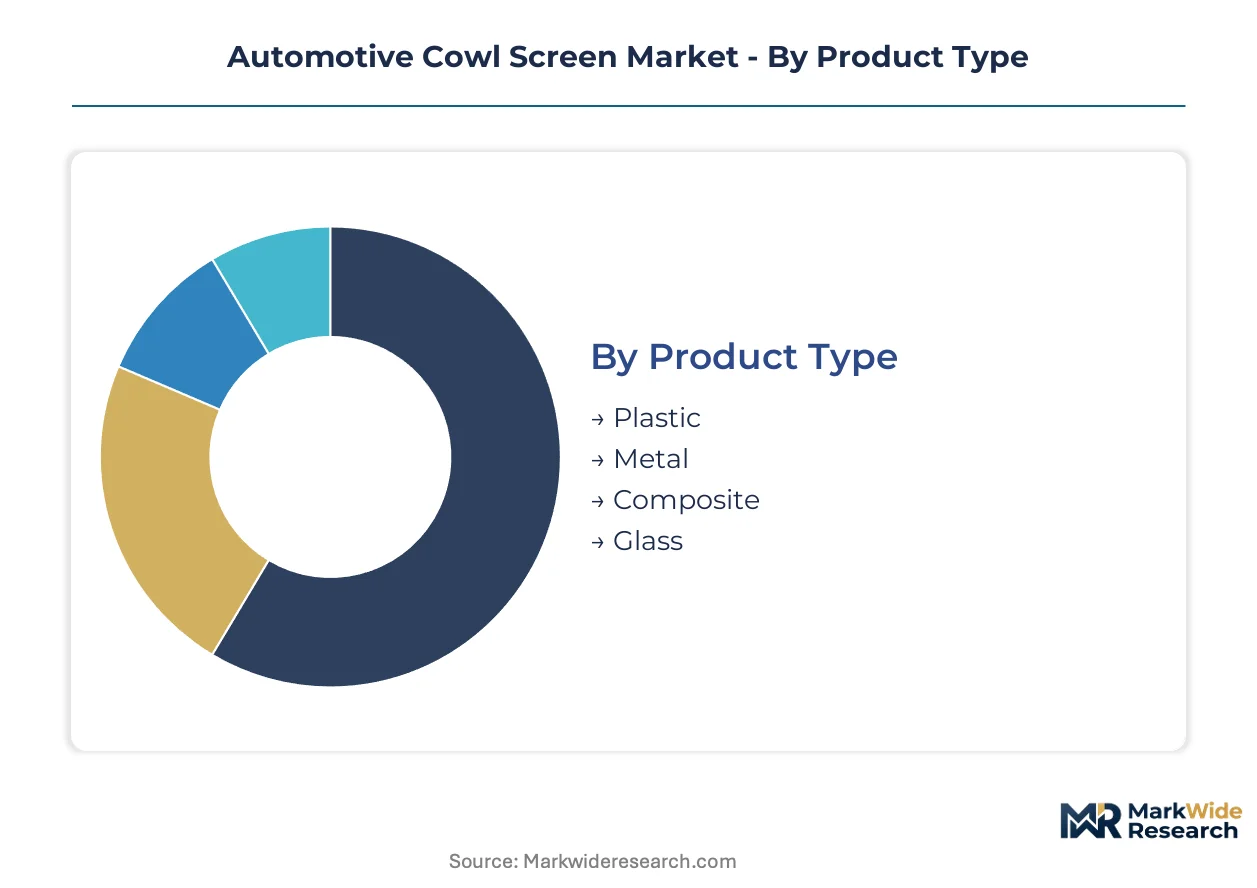
Cowl screen procurement patterns fragment sharply across product grades and channel structures. Understanding these splits reveals where acoustic-thermal engineering investments concentrate versus where price competition dominates.
Product Type:
Volume production concentrates in injection-molded grades, while premium architectures command engineered composites with NVH-tuned densities.
- Plastic:Polypropylene-EPDM blends dominate mass-market platforms through injection-molded weather resistance at scale. Procurement concentrates with North American light-truck programs where durability specifications exceed passenger-car thresholds.
- Composite:Multi-layer polymer constructions integrate acoustic-damping layers at 1,200-1,600 g/m² densities with water-management channels. Demand clusters in Germany around Stuttgart and Munich supplier ecosystems serving premium EV platforms with NVH targets below 40 dB.
- Metal:Stamped aluminum and steel variants persist in commercial vehicle applications requiring structural rigidity.
- Glass:Specialized transparent cowl panels serve niche autonomous sensor integration requirements.
Today's leader: Plastic. Tomorrow's challenger: Composite.
End User:
Factory-fit procurement governs revenue concentration, though aftermarket channels expand as aging fleets create replacement pull-through.
- OEMs:Integrated acoustic-thermal module contracts dominate value capture, with European EV platforms consolidating sourcing through climate-system specialists.
- Aftermarket Providers:Independent service networks and digital parts platforms accelerate as vehicle aging in the United States and Germany expands addressable unit volume.
- Dealerships:Authorized service channels handle warranty-related cowl screen replacements under OEM parts programs.
- Fleet Operators:Commercial vehicle managers source direct for high-utilization assets requiring accelerated maintenance cycles.
Primary volume: OEMs. Expansion vector: Aftermarket Providers.
Installation:
Engineering complexity stratifies from module-integrated architectures to simple replacement panels.
- Integrated:Factory-fit assemblies merge cowl screens with HVAC intake systems and thermal management modules, commanding highest per-unit engineering content.
- Semi-Integrated:Partial module convergence accommodates mid-tier platform cost constraints while retaining some functional consolidation.
- Add-on:Supplementary acoustic treatments attach to existing cowl structures for retrofit NVH improvement.
- Replacement:Standalone panel swaps serve collision repair and wear-related maintenance through aftermarket channels.
Specification lock-in favors: Integrated. Service opportunity opens: Replacement.
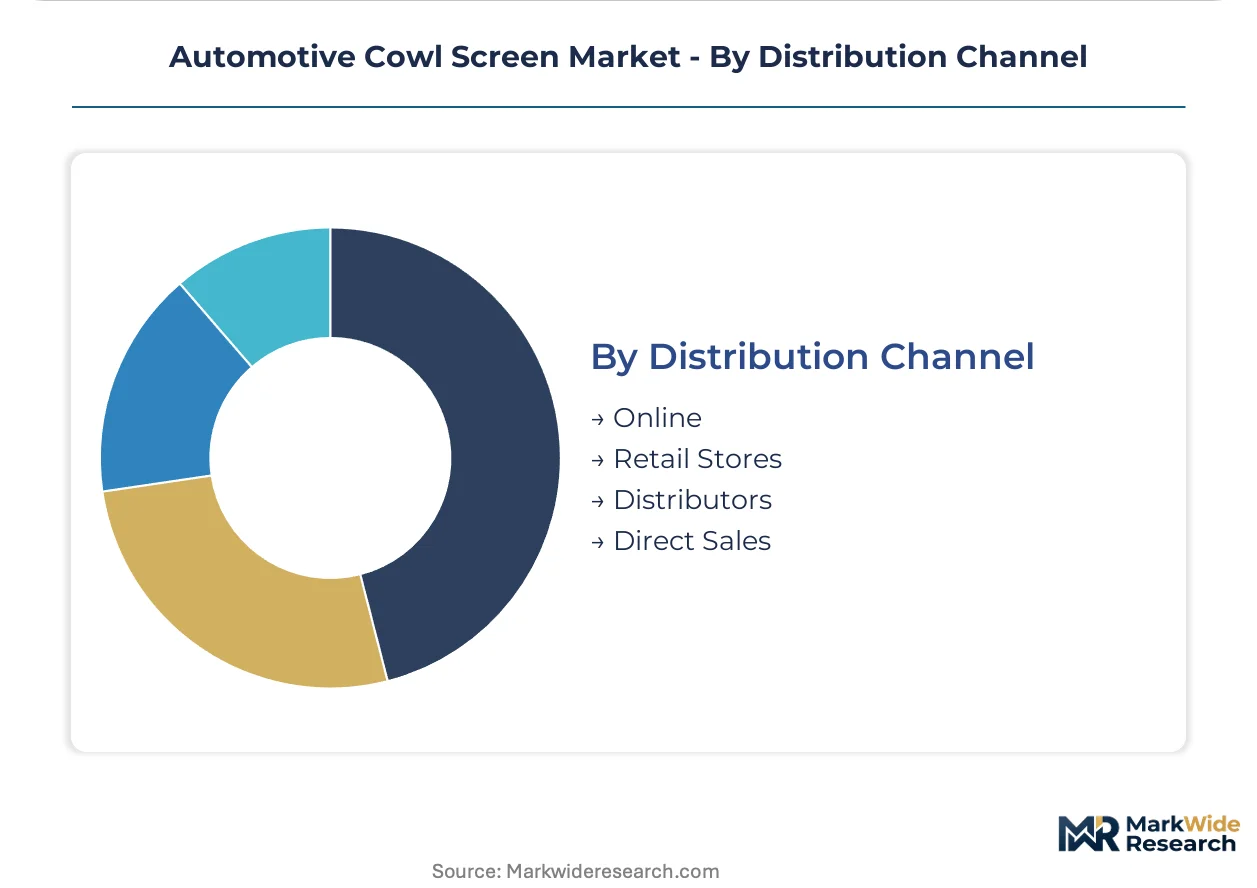
Distribution Channel:
Channel selection tracks buyer sophistication and order scale, with direct relationships dominating OEM procurement.
- Direct Sales:Tier-1 suppliers maintain platform-specific engineering relationships with OEM engineering centers, bypassing intermediaries for integrated module contracts.
- Distributors:Wholesale networks aggregate demand from independent repair shops and smaller fleet operators seeking inventory breadth.
- Online:Digital parts platforms capture DIY installers and price-sensitive replacement demand, particularly in the United States.
- Retail Stores:Brick-and-mortar auto parts chains serve immediate-need replacement with limited technical specification depth.
Engineering-intensive procurement: Direct Sales. Volume scaling path: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart-Munich supplier corridors anchor acoustic-thermal engineering concentration for integrated cowl modules serving premium EV architectures.
Germany
Baden-Württemberg and Bavaria house specialized Tier-1 ecosystems where Valeo and Plastic Omnium maintain integrated module engineering centers. ECHA's REACH phthalate restrictions force reformulation cycles extending qualification timelines. Stuttgart supplier parks concentrate acoustic-damping composite production for NVH targets below 40 dB.
United States
EPA's 40 CFR Part 205 noise thresholds compel multi-layer polymer designs across Detroit and Southern automotive corridors. NHTSA's FMVSS 302 flammability standard shapes material selection diverging from European specifications. Michigan and Tennessee manufacturing clusters serve light-truck programs with durability requirements exceeding passenger-car thresholds.
China
Yangtze River Delta and Pearl River Delta EV platform expansion drives cowl-HVAC module convergence demand. MIIT's GB standards for vehicle noise emissions tighten acoustic specifications for domestic and export-bound production. Shanghai-Suzhou supplier networks scale injection-molded PP-EPDM capacity for mass-market electric vehicle programs.
Japan
METI's carbon neutrality roadmaps accelerate thermal-management component localization for next-generation EV architectures. Kanto and Kansai manufacturing belts concentrate precision molding expertise for acoustic-integrated cowl assemblies. Toyota City and Nagoya supplier clusters serve hybrid and battery-electric platform thermal module requirements.
India
PLI scheme incentives for automotive component manufacturing attract first-mover acoustic-thermal module suppliers. Maharashtra and Tamil Nadu vehicle production hubs expand procurement for integrated cowl assemblies. Pune and Chennai supplier parks develop injection-molding capacity serving Maruti Suzuki and Hyundai Motor India localization programs.
Automotive Cowl Screen Market Competitive Environment
Strategic partnerships dominate the current landscape as climate-system integrators consolidate sourcing authority over acoustic-thermal modules. The vendor structure tiers between vertically integrated automotive suppliers and specialized exterior component fabricators. Three archetypes occupy distinct positions: integrated module specialists, scale-driven polymer processors, and regional component suppliers. M&A activity and geographic expansion represent the primary competitive vectors as suppliers chase EV platform contracts.
Among integrated module specialists, Valeo exemplifies climate-system convergence expertise, while Magna International represents North American manufacturing scale. Denso occupies a position bridging thermal-management technology with cabin air-path component integration. These three anchors illustrate how engineering-content barriers favor suppliers with upstream climate-system capabilities over discrete component manufacturers.
| Leading Market Players |
|---|
| Plastic Omnium |
| Toyoda Gosei |
| Valeo |
| Montaplast |
| CIE Automotive |
| Magna International |
| Futaba Industrial |
| Inoac Corporation |
| Denso |
| Others |
Value Chain & Pricing Dynamics
Propylene monomer pricing swings cascade through injection-molded PP-EPDM cowl screen production, compressing margins on mass-market tiers while premium composite segments capture value through acoustic-damping density specifications that commodity grades cannot replicate. The cost path from petrochemical feedstock to finished component splits procurement economics between volume-driven North American light-truck programs and NVH-optimized European EV architectures.
Pricing Analysis
Distributor markups widen replacement channel spreads versus direct OEM contracts that trade volume commitment for engineering-content premiums. Three-tier pricing structure across premium, standard, and economy levels tracks acoustic performance certification, with NVH targets below 40 dB commanding substantial premiums over baseline weather-resistance grades. Cost compression in mass-market injection-molded tiers intensifies because of polypropylene feedstock volatility, while aftermarket providers exhibit highest price sensitivity due to undifferentiated product substitution.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for acoustic-thermal module suppliers establishing Pune and Chennai operations. Manufacturing gravity draws from Germany, China, and the United States, with Stuttgart-Munich supplier corridors feeding premium EV platforms and Yangtze River Delta clusters scaling injection-molded capacity. Feedstock exposure to propylene monomer and carbon-fiber-reinforced thermoplastic resins creates commodity price volatility risk. Distribution runs through direct Tier-1 platform relationships for OEM procurement, with aftermarket channels aggregating through wholesale networks and digital parts platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as EPA 40 CFR Part 205 noise thresholds and ECHA REACH phthalate restrictions simultaneously tighten material and acoustic specifications, forcing supplier investment in multi-physics engineering capabilities that smaller competitors cannot fund.
For Market Incumbents: Cement integrated module contracts by deepening climate-system convergence expertise before full front-end module integration by large Tier-1s absorbs cowl screen functionality. Add capacity in Stuttgart-Munich supplier corridors to anchor European EV platform sourcing. Invest in dual FMVSS 302 and ECE R118 certification infrastructure to defend against qualification-timeline fragmentation. For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for acoustic-thermal module localization, targeting Pune and Chennai supplier parks where first-mover engineering talent remains uncommitted. The aftermarket service channel offers penetrable white space as aging vehicle fleets in the United States and Germany expand replacement demand. Pursue digital parts platform partnerships to bypass entrenched wholesale distributor relationships. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale polymer processors lack capital for REACH reformulation cycles and NVH-acoustic coupled CFD thermal modeling talent scarcity. Long-term viability favors vertically integrated climate-system specialists with captive HVAC integration capabilities over discrete component fabricators. Watch battery-electric platform thermal-architecture standardization as the inflection signal—heat-pump convergence into cowl structures will elevate engineering-content barriers and compress supplier counts.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces engineering overhead for suppliers serving parallel ICE and EV programs. |
| Battery Supply Agreement | Secures thermal-management component allocation for next-generation EV architectures. |
| Software-Defined Vehicle Investment | Enables predictive maintenance integration for aftermarket service channel capture. |
| Geographic Manufacturing Footprint | Positions capacity within PLI scheme zones to access India passenger vehicle localization. |
| Charging Infrastructure Partnership | Creates thermal-system cross-selling opportunities with EV ecosystem integrators. |
Study Parameters
Direct dialogue with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers grounded qualitative findings in operational reality. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA 40 CFR Part 205 enforcement records, and ECHA REACH restriction documentation. Bottom-up segment sizing and top-down market reconciliation triangulated volume and value estimates.
Segment-level outputs across the analysis window reflect modeled splits by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs were derived from regression analysis against vehicle production forecasts and thermal-management module penetration curves. Forecast inputs incorporated OEM platform thermal-architecture roadmaps and regulatory milestone timing.
Inputs from Tier-1 engineering centers and regulatory filing databases were available through the study window; gaps in pre-announcement EV platform specifications introduce uncertainty bands around integrated module adoption timelines. Forecasts reflect documented assumptions regarding propylene monomer price stability and REACH reformulation qualification durations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Drawer Slides Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
India Automotive Door Seals Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market