
 Capacitive Touch Switch Panels for Vehicle Interiors Market | 2026-2036
Capacitive Touch Switch Panels for Vehicle Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Touch Switch Panels for Vehicle Interiors Market Insights
Automotive SPICE compliance is collapsing the supplier qualification cycle for interior electronics, forcing tier-1 vendors to demonstrate software process maturity before platform integration. Continental leverages its systems integration depth to sustain multi-zone panel programs across German OEM architectures. Alps Alpine anchors Japan's supply base with specialized projected capacitive designs for premium dashboard controls. Robert Bosch competes through manufacturing scale that extends across European and North American vehicle assembly networks.
Capacitive touch switch panels for vehicle interiors are thin-film electronic interfaces that detect finger proximity through dielectric field disruption, typically operating at 3.3V to 5V with response thresholds below 100 milliseconds to enable haptic-free command inputs for climate, lighting, and infotainment systems. Their primary commercial purpose is replacing mechanical switches to reduce part count, enable flush surface designs, and support programmable interface layouts that adapt across vehicle trim levels. Multi-zone panels dominate current OEM specifications due to consolidated control surface requirements, while projected capacitive technology leads technology adoption because of its tolerance for overlay materials and glove-friendly detection. Waterproof panels represent the fastest-growing product configuration as electric vehicle architectures demand ingress protection for open-cabin and utility vehicle applications.
NHTSA distraction guidelines and ECE R10 electromagnetic compatibility standards shape product development timelines by mandating tactile feedback alternatives and radiated emission limits for cabin electronics. China's GB standards for automotive electromagnetic compatibility, administered by MIIT, create parallel certification requirements for suppliers serving domestic EV manufacturers. ISO 26262 functional safety classifications increasingly gate market access for center console and dashboard interfaces where erroneous activation carries operational risk. Stakeholders must monitor how software-defined vehicle architectures redistribute interface ownership between tier-1 panel suppliers and OEM captive electronics divisions.
Market Dynamics
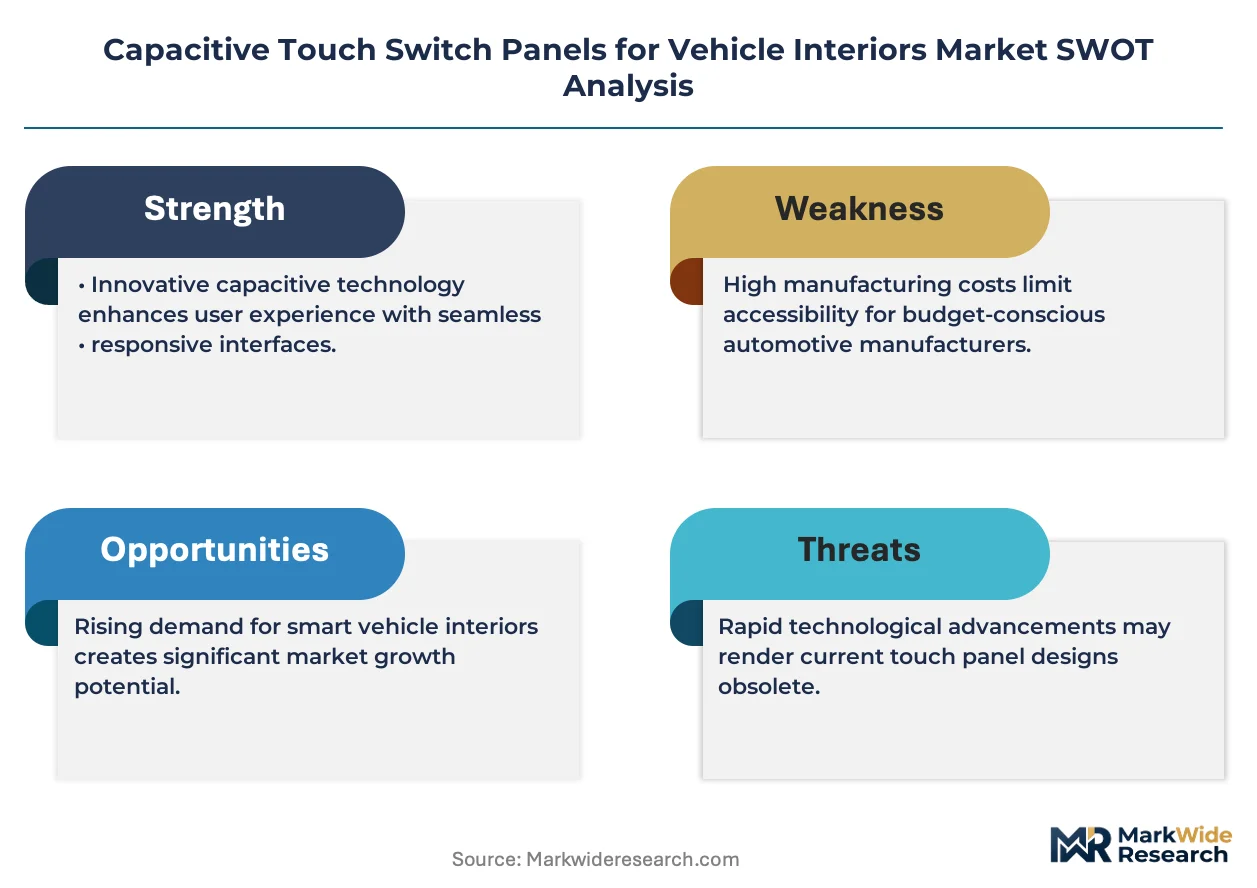
Software-defined vehicle architectures are redistributing interface ownership between tier-1 panel suppliers and OEM captive electronics divisions, compressing traditional supplier qualification timelines and forcing process maturity demonstrations before platform integration.
Growth Catalysts
- Luxury EV platform expansion:Mercedes-Benz and BMW architectures are consolidating control surfaces into multi-zone capacitive panels that reduce mechanical part counts while enabling programmable layouts across trim levels.
- ECE R10 electromagnetic compatibility tightening:Europe's radiated emission limits for cabin electronics are accelerating certification investments that filter out lower-tier competitors and concentrate procurement among qualified suppliers.
- Projected capacitive technology maturation:Tolerance for thick overlay materials and glove-friendly detection is displacing resistive alternatives in premium dashboard and center console specifications.
Market Restraints
- Indium tin oxide supply concentration:Transparent conductor sourcing depends heavily on East Asian refining capacity, creating input cost volatility for projected capacitive layer manufacturing.
- ISO 26262 functional safety gates:ASIL classification requirements for center console interfaces where erroneous activation carries operational risk extend development timelines and qualification costs.
- Mechanical switch residual demand:Commercial vehicle and budget passenger segments continue specifying tactile feedback alternatives that resist full capacitive conversion.
Strategic Opportunities
- Open-cabin EV waterproofing gap:Electric utility vehicles and beach-ready passenger configurations lack adequate ingress protection standards, creating specification white space for IP-rated panel designs.
- MIIT GB standards harmonization:China's automotive electromagnetic compatibility administration is converging toward ECE R10 technical baselines, simplifying dual-certification burdens for export-oriented suppliers.
- Haptic feedback convergence:Integration of piezoelectric actuators with capacitive sensing layers addresses NHTSA distraction guidelines while preserving flush surface aesthetics.
Industry Challenges
- Automotive SPICE software maturity gaps:Tier-1 vendors face capability scarcity in embedded firmware process documentation required before German OEM architecture integration.
- Multi-zone calibration complexity:Consolidated control surfaces demand sophisticated crosstalk suppression algorithms that extend validation cycles and strain analog design talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Touch Switch Panels for Vehicle Interiors Market |
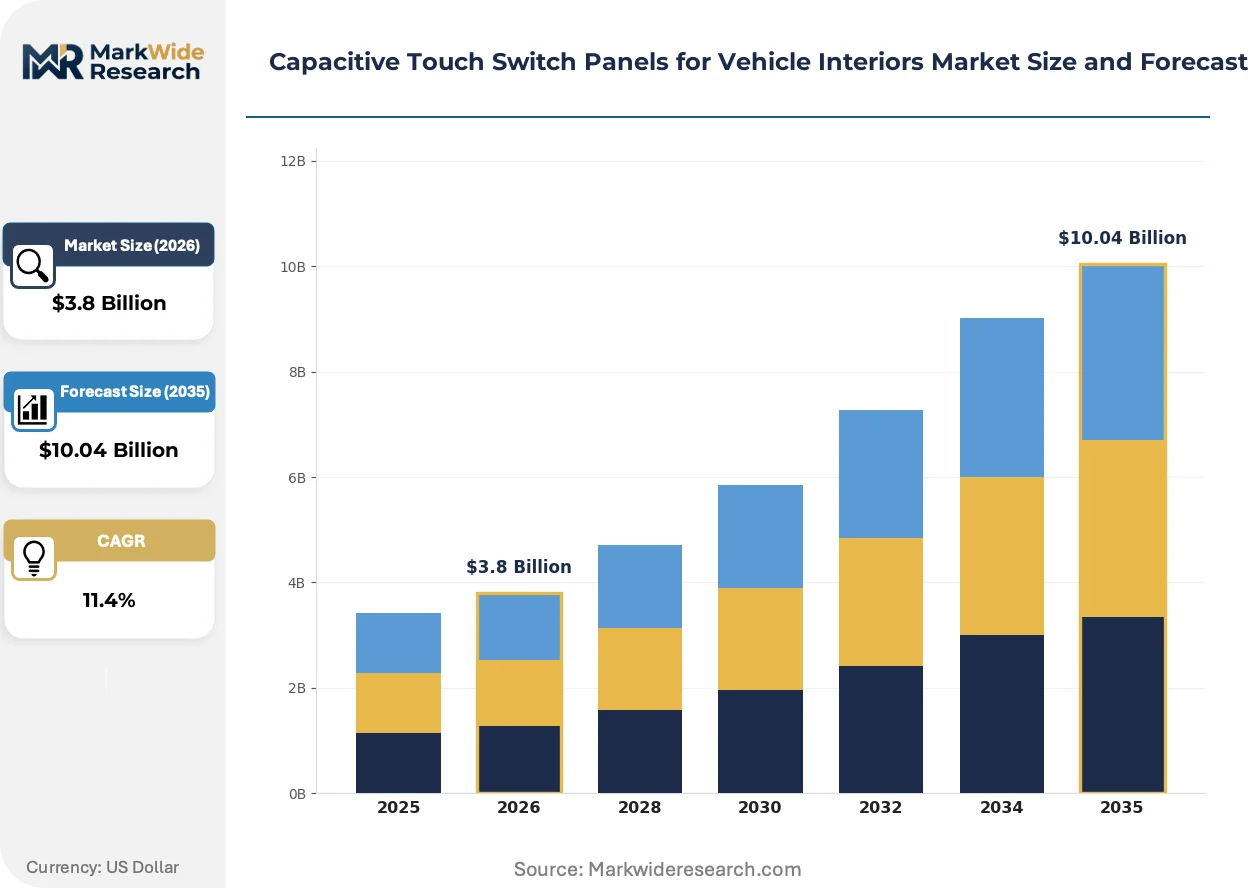
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Zone Panels, Multi-Zone Panels, Customizable Panels, Waterproof Panels Technology: Projected Capacitive, Surface Capacitive, Mutual Capacitive, Self-Capacitive Application: Dashboard Controls, Center Console Interfaces, Door Panel Inputs, Overhead Console Switches End User: OEMs, Vehicle Assembly Plants, Aftermarket Suppliers, Tier-1 Vendors |
| Companies Covered | Alps Alpine, Continental, Preh, AUO Mobility Solutions, BHTC, Tokai Rika, Valeo, Leopold Kostal, Robert Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Touch Switch Panels for Vehicle Interiors Market Trends and Innovations
Capacitive interface technology is fragmenting along performance-versus-cost axes as software-defined vehicles enable over-the-air reconfiguration of control layouts without hardware replacement cycles.
Force-sensing resistor integration with projected capacitive layers is bifurcating the premium panel segment. Luxury German OEMs are adopting pressure-sensitive inputs for accidental touch rejection. This capability compression is eliminating discrete mechanical confirmation switches while raising firmware complexity thresholds for supplier qualification.
Europe's ECE R10 electromagnetic compatibility enforcement is tightening radiated emission limits for cabin electronics. German KBA type approval timelines have extended by four to six months for non-compliant submissions. Center console interface suppliers are responding with shielding layer redesigns and conducted immunity testing investments.
Fleet procurement departments are consolidating interior electronics sourcing through direct OEM negotiations rather than tier-1 mediated programs. Rental and commercial vehicle operators in the United States are demanding standardized interface layouts across multiple vehicle platforms. This specification uniformity is most visible in airport shuttle and last-mile delivery vehicle configurations where driver training costs dominate total ownership economics.
Capacitive Touch Switch Panels for Vehicle Interiors Market Segmentation
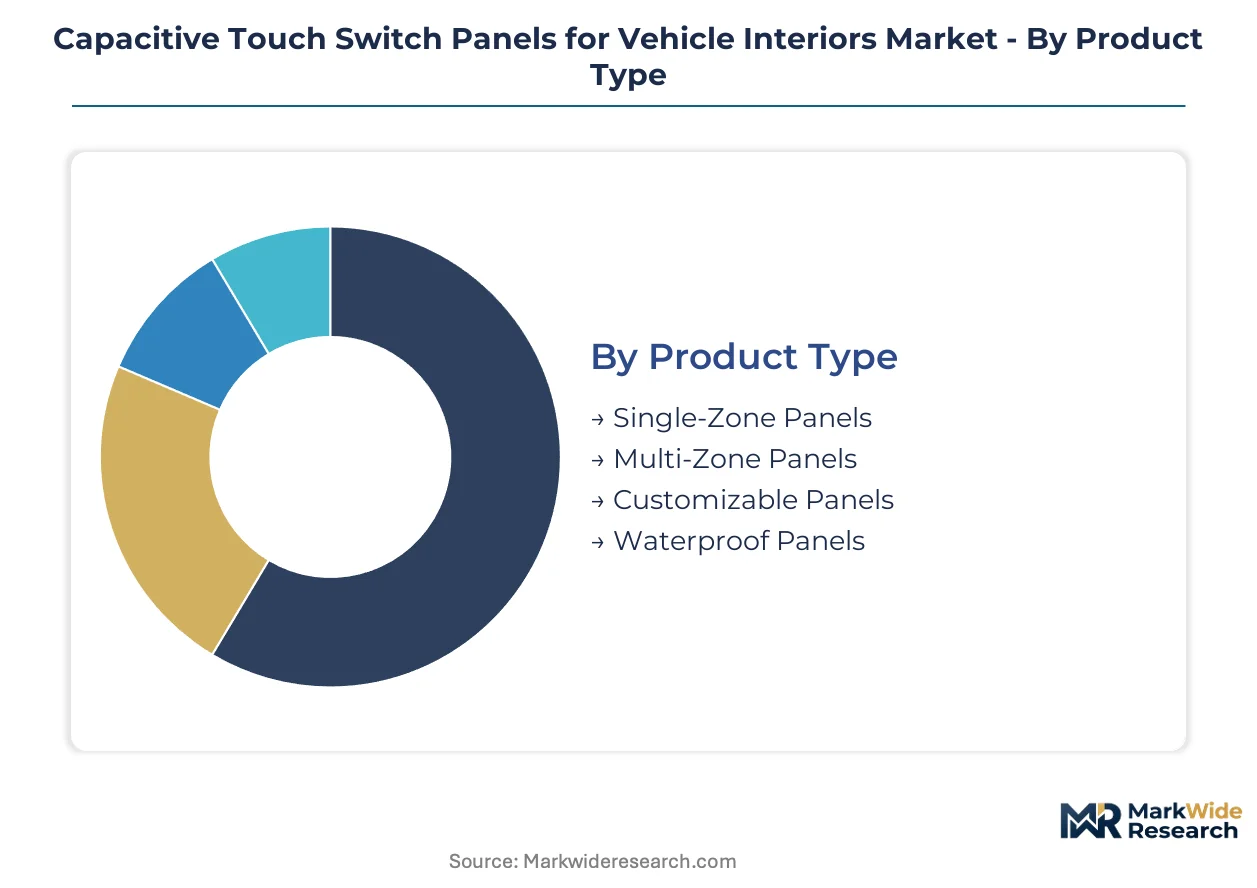
Segmentation in capacitive touch switch panels reveals how procurement patterns split between standardized high-volume programs and specialized configurations. Technology choices and end-user channel structures determine margin profiles and qualification barriers differently across each dimension.
Product Type:
Geographic demand concentration varies sharply—waterproof and customizable panels track export-led electric vehicle programs, while single-zone and multi-zone variants serve domestic fleet replacement cycles.
- Multi-Zone Panels:Consolidated control surfaces integrate climate, lighting, and infotainment commands within single dielectric substrates. German and Chinese OEM architectures specify these for premium dashboard layouts where programmable trim-level differentiation reduces mechanical part proliferation.
- Waterproof Panels:IP-rated sealing layers protect sensing electrodes from moisture ingress in open-cabin electric utility vehicles. Beach-ready passenger configurations and last-mile delivery fleets in coastal United States markets drive specification intensity for this configuration.
- Single-Zone Panels:Discrete function controls serve budget passenger segments and commercial vehicle retrofits where consolidated interfaces exceed cost targets.
- Customizable Panels:Programmable layout substrates enable OEM-specific branding and control reconfiguration without hardware replacement.
Multi-zone panels hold the largest share; momentum sits with waterproof configurations.
Technology:
Cost tier stratification separates premium projected capacitive deployments from surface capacitive alternatives in price-sensitive applications.
- Projected Capacitive:Field-shielded electrode arrays tolerate thick overlay materials and glove-friendly detection thresholds. European ECE R10 compliance investments favor this technology for center console specifications where electromagnetic immunity gates market access.
- Mutual Capacitive:Transmitter-receiver electrode pairs enable multi-touch recognition and gesture detection for advanced infotainment interfaces.
- Surface Capacitive:Single-layer conductive coatings serve cost-optimized dashboard controls with limited overlay thickness requirements.
- Self-Capacitive:Individual electrode measurement circuits reduce component count for simple switch replacement applications in door panel and overhead console positions.
Projected capacitive dominates revenue; self-capacitive is climbing the fastest among budget-tier programs.
Application:
Volume concentration centers on dashboard and center console positions where control surface consolidation delivers maximum part-count reduction.
- Center Console Interfaces:Climate and drive-mode command clusters integrate haptic feedback layers to satisfy NHTSA distraction guidelines. ISO 26262 ASIL classifications extend development timelines for these positions where erroneous activation carries vehicle operational risk.
- Dashboard Controls:Instrument panel proximity sensors replace mechanical stalks and rotary encoders in Mercedes-Benz and BMW architectures.
- Door Panel Inputs:Window and mirror adjustment surfaces adopt capacitive alternatives for flush interior surface aesthetics.
- Overhead Console Switches:Dome lighting and sunroof controls represent lower-specification entry points for capacitive conversion.
Center console interfaces command premium positioning; door panel inputs are gaining share fastest through platform standardization.
End User:
Customer type determines procurement channel structure—OEM captive programs versus tier-1 mediated supply shape contract terms and technical specification ownership.
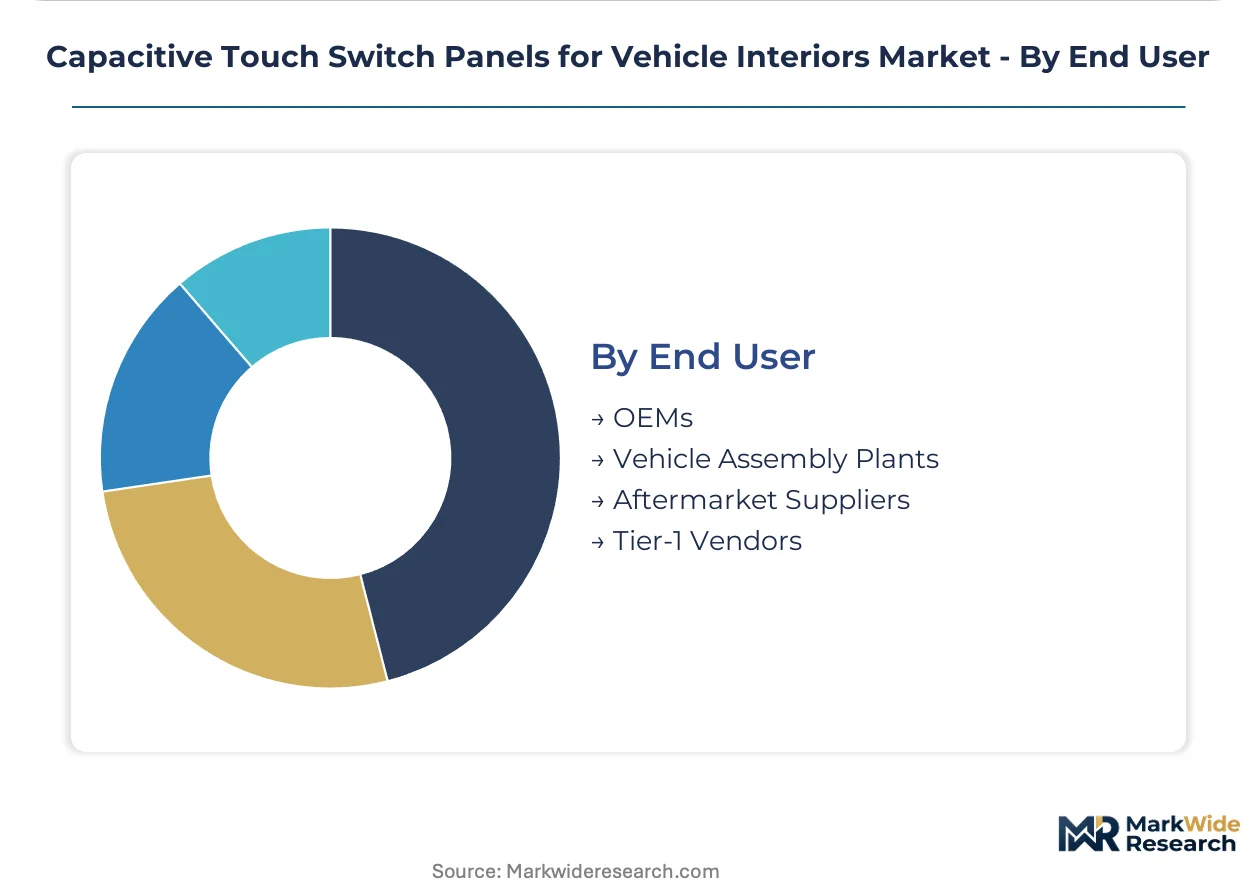
- OEMs:Mercedes-Benz, BMW, and domestic Chinese electric vehicle manufacturers maintain direct panel specification authority for flagship architectures. Software-defined vehicle roadmaps redistribute interface ownership toward captive electronics divisions, compressing traditional tier-1 supplier roles.
- Tier-1 Vendors:Continental and Robert Bosch integrate multi-zone panels across German and North American assembly networks.
- Vehicle Assembly Plants:Contract manufacturing facilities in China and Mexico receive pre-qualified panel modules for just-in-sequence installation.
- Aftermarket Suppliers:Replacement and retrofit channels serve collision repair and commercial vehicle upgrade segments with simplified calibration requirements.
OEMs hold the largest share; tier-1 vendors face the steepest margin pressure from architecture consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs and Chinese electric vehicle manufacturers dominate procurement volumes for capacitive touch switch panels, with tier-1 suppliers calibrating regional production footprints to match platform launch timelines and electromagnetic compliance requirements.
Germany
Mercedes-Benz and BMW architectures drive multi-zone panel specifications for premium dashboard consolidation. KBA type approval timelines under ECE R10 have extended four to six months for non-compliant submissions, filtering supplier pools. Stuttgart and Munich industrial clusters concentrate systems integration capabilities for German OEM captive programs.
China
Domestic EV manufacturers BYD and NIO expand capacitive interface adoption across mass-market and premium vehicle lines. MIIT administration of GB standards for automotive electromagnetic compatibility creates parallel certification tracks for export-oriented suppliers. Yangtze River Delta manufacturing bases around Shanghai and Suzhou host the highest concentration of panel module assembly for both domestic consumption and European export.
United States
Detroit Three OEMs and Tesla specify center console interfaces with haptic feedback layers to satisfy NHTSA distraction guidelines. Fleet procurement departments for rental and last-mile delivery operators demand standardized layouts across multiple vehicle platforms. Southeast assembly corridors in Tennessee and South Carolina receive pre-qualified panel modules for just-in-sequence installation.
Japan
Toyota and Honda maintain conservative capacitive adoption curves, prioritizing mechanical switch retention for commercial vehicle segments. METI industrial policy supports domestic component sourcing for automotive electronics. Kansai and Nagoya manufacturing belts specialize in projected capacitive designs for premium dashboard controls serving both domestic OEMs and export markets.
South Korea
Hyundai-Kia Group accelerates capacitive interface deployment across Genesis luxury architectures and Ioniq electric platforms. MFDS does not directly regulate automotive electronics, leaving OEMs to self-certify against ISO 26262 functional safety benchmarks. Seoul Capital Area suppliers concentrate on mutual capacitive technology for advanced infotainment gesture detection.
Capacitive Touch Switch Panels for Vehicle Interiors Market Competitive Landscape
Player mix skews toward diversified automotive electronics conglomerates with systems integration depth, compressing opportunities for standalone panel specialists. Market structure concentrates procurement authority among tier-1 vendors capable of multi-zone program delivery across German, Chinese, and North American OEM architectures. Two strategic archetypes dominate: diversified conglomerates leveraging manufacturing scale across continental assembly networks, and specialized projected capacitive designers with premium dashboard expertise. Competitive moves center on software process maturity demonstrations for Automotive SPICE compliance and shielding layer redesigns for ECE R10 electromagnetic compatibility certification.
Among diversified conglomerates, Continental and Robert Bosch occupy positions anchored by manufacturing scale that extends across European and North American vehicle assembly networks. Alps Alpine sits within the specialized tier, representing Japanese supply base capabilities for projected capacitive designs. Preh exemplifies the mid-tier systems integrator archetype, calibrating between scale-driven conglomerates and component specialists.
| Leading Market Players |
|---|
| Alps Alpine |
| Continental |
| Preh |
| AUO Mobility Solutions |
| BHTC |
| Tokai Rika |
| Valeo |
| Leopold Kostal |
| Robert Bosch |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-week qualification cycles for ECE R10 electromagnetic compatibility certification concentrate procurement leverage among German and Chinese OEMs while compressing margin buffers for tier-1 panel suppliers. This lead-time band couples with indium tin oxide sourcing concentration to reshape pricing power across projected capacitive layer manufacturing.
Pricing Analysis
Cost-plus contracts with indium tin oxide price indexation dominate multi-zone panel procurement between tier-1 vendors and German OEMs. Three-tier pricing structure across ASIL-certified, ECE R10-compliant, and standard-grade configurations separates premium dashboard specifications from economy door panel alternatives. Pricing pressure stems from fleet procurement departments demanding standardized layouts across multiple vehicle platforms, forcing volume discounts for center console interfaces. Commercial vehicle and budget passenger segments exhibit highest price sensitivity, while luxury EV platforms tolerate premium positioning for force-sensing resistor integration.
Supply Chain Analysis
China and Japan anchor transparent conductor refining and projected capacitive electrode manufacturing respectively. Indium tin oxide sputtering targets, polyimide substrate films, and piezoelectric actuator layers constitute critical input dependencies. Single-source vulnerability concentrates in East Asian rare earth processing capacity for transparent conductor alloys. Distribution runs through just-in-sequence module delivery to vehicle assembly plants in Tennessee, South Carolina, and the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures fragment interface ownership between tier-1 suppliers and OEM captive divisions, creating specialist niches for firmware-qualification services and shielding-layer engineering. This demand-side redistribution rewards agile entrants while pressuring legacy integrators.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into indium tin oxide sputtering target production, securing input cost stability against East Asian refining volatility. Prioritize Automotive SPICE compliance investments ahead of German OEM platform integration windows, as software process documentation gaps now filter supplier pools more aggressively than hardware performance metrics. For New Entrants and Emerging Players: ECE R10 certification fast-track services for tier-2 suppliers represent the most penetrable service niche, given KBA type approval timeline extensions of four to six months for non-compliant submissions. Target waterproof panel specifications for open-cabin electric utility vehicles, where IP-rated sealing standards remain undefined and beach-ready passenger configurations lack established supply relationships. Lead with haptic feedback convergence engineering as the go-to-market angle, addressing NHTSA distraction guidelines while preserving flush surface aesthetics. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because tier-1 vendor margin compression from OEM captive electronics expansion will force mid-tier systems integrators toward acquisition. Target acquisition candidates with established MIIT GB standards compliance for China export positioning and existing force-sensing resistor firmware stacks. Watch for inflection when German OEMs announce software-defined vehicle roadmaps redistributing center console interface specification authority.| Strategic Initiative | Industry Significance |
|---|---|
| ECE R10 Shielding Layer Redesign | KBA type approval timeline compression filters supplier pools toward qualified incumbents. |
| Automotive SPICE Compliance Investment | German OEM architecture integration now gates on embedded firmware process maturity documentation. |
| Waterproof IP-Rating Development | Open-cabin EV specifications lack ingress protection standards, creating first-mover specification authority. |
| Indium Tin Oxide Backward Integration | East Asian refining concentration creates input cost volatility for projected capacitive manufacturing. |
| Haptic Feedback Convergence Engineering | Piezoelectric actuator integration addresses NHTSA distraction guidelines while preserving flush aesthetics. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-1 supplier procurement documentation anchors the qualitative findings on interface ownership redistribution. Primary interviews with automotive electronics procurement managers, embedded firmware architects, ECE R10 certification consultants, and MIIT standards administrators combined with secondary validation from vehicle production databases, IHS Markit registration data, KBA type approval filings, and SEC automotive segment disclosures. Bottom-up panel shipment estimates and top-down vehicle content-per-unit assumptions triangulate market sizing.
Sensitivity analysis across indium tin oxide price volatility bands and ECE R10 compliance timeline scenarios stress-tests projection robustness. The analytical framework models vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the analysis window. CAGRs derive from segment-level shipment trajectories weighted by average selling price movements, with electric vehicle platform launch calendars and fleet procurement standardization mandates as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of continued software-defined vehicle architecture deployment and stable East Asian transparent conductor supply; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in OEM captive electronics division staffing announcements and MIIT GB standards harmonization progress toward ECE R10 baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Train Seat Materials Market