
 Automotive Wooden Interior Decorative Market | 2026-2036
Automotive Wooden Interior Decorative Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wooden Interior Decorative Market Outlook
Digital veneer patterning and laser-etched grain replication is tilting production economics toward hybrid wood-composite substrates that preserve tactile authenticity at reduced material intensity. NBHX Trim Management Services leverages captive forestry partnerships across Central Europe to sustain cost-advantaged walnut and oak supply chains. FormWood Industries anchors its competitive position through specialized thermoforming expertise for complex dashboard geometries. Mata Automotive differentiates via integrated finishing capabilities that control lacquer application consistency across high-volume programs.
Automotive wooden interior decorative components encompass machined, molded, or laminated wood elements applied to vehicle cabins for aesthetic enhancement, tactile refinement, and brand-positioning purposes; typical specifications include veneer thicknesses of 0.5–1.2 mm, substrate bonding through polyurethane hot-melt adhesives, and surface finishing with UV-cured polyurethane coatings achieving 90+ gloss units. Dashboard applications command the deepest value pools due to engineering complexity and visibility centrality, while electric vehicle application demand is expanding fastest as cabin differentiation replaces powertrain distinction in buyer perception. Oak material selection leads volume given favorable workability and regional availability, though bamboo is gaining share in sustainability-weighted procurement frameworks.
FDA indirect food contact guidelines, EPA formaldehyde emission standards under TSCA Title VI, and ECHA REACH substance restrictions collectively govern adhesive systems, surface coatings, and volatile organic compound thresholds for cabin-grade wood components. OEMs must navigate multi-jurisdictional compliance matrices to secure type approval across production regions, with particular scrutiny on phenol-formaldehyde resin content in laminated substrates. Stakeholders should monitor evolving biogenic carbon accounting methodologies and deforestation-free supply chain mandates, as these frameworks are poised to reshape supplier qualification criteria and material traceability investments without warning.
Market Dynamics
EU F-Gas Regulation and REACH compliance frameworks are compressing supply chain configurations, forcing tier-one suppliers to consolidate forestry partnerships and captive finishing capabilities to maintain margin structures against synthetic interior alternatives.
Growth Catalysts
- REACH substance restrictions:Stringent ECHA limits on volatile organic compounds in cabin-grade coatings are accelerating demand for UV-cured polyurethane systems that wooden trim suppliers can certify more readily than composite competitors.
- Electric vehicle cabin differentiation:Luxury EV manufacturers are expanding real wood applications as powertrain homogenization eliminates traditional performance distinctions in buyer perception.
- Digital veneer patterning:Laser-etched grain replication technology is reducing material intensity requirements while preserving tactile authenticity, opening volume programs to wooden trim previously priced out of mid-tier segments.
Market Restraints
- Walnut and oak supply concentration:Central European forestry partnerships control premium hardwood flows, creating bottleneck risk for suppliers without captive sourcing arrangements.
- Formaldehyde emission standards:EPA TSCA Title VI and overlapping state-level California Air Resources Board limits add compliance layers that laminated substrate producers must absorb or pass through.
- High-performance polymer substitution:Advanced thermoplastic composites with wood-grain surfacing are capturing dashboard applications where engineering complexity once exclusively favored machined veneer.
Strategic Opportunities
- Bamboo procurement frameworks:Sustainability-weighted OEM sourcing guidelines are elevating fast-growth grass alternatives to oak in volume programs, rewarding early movers with biogenic carbon accounting advantages.
- Integrated finishing capabilities:Lacquer application consistency controls represent a service layer that tier-one suppliers can monetize separately from component supply.
- India premium vehicle production:Domestic assembly of luxury nameplates is expanding addressable demand for cabin-grade wooden trim beyond traditional German, Japanese, and United States manufacturing clusters.
Industry Challenges
- Thermoforming expertise scarcity:Complex dashboard geometries require specialized tooling knowledge concentrated among a limited supplier base, constraining capacity expansion timelines.
- Multi-jurisdictional type approval:OEMs must synchronize FDA indirect food contact guidelines, EPA emission standards, and ECHA substance restrictions across production regions, extending qualification cycles.
- Deforestation-free traceability mandates:Emerging supply chain verification requirements demand IT infrastructure investments that mid-cap suppliers struggle to fund without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wooden Interior Decorative Market |
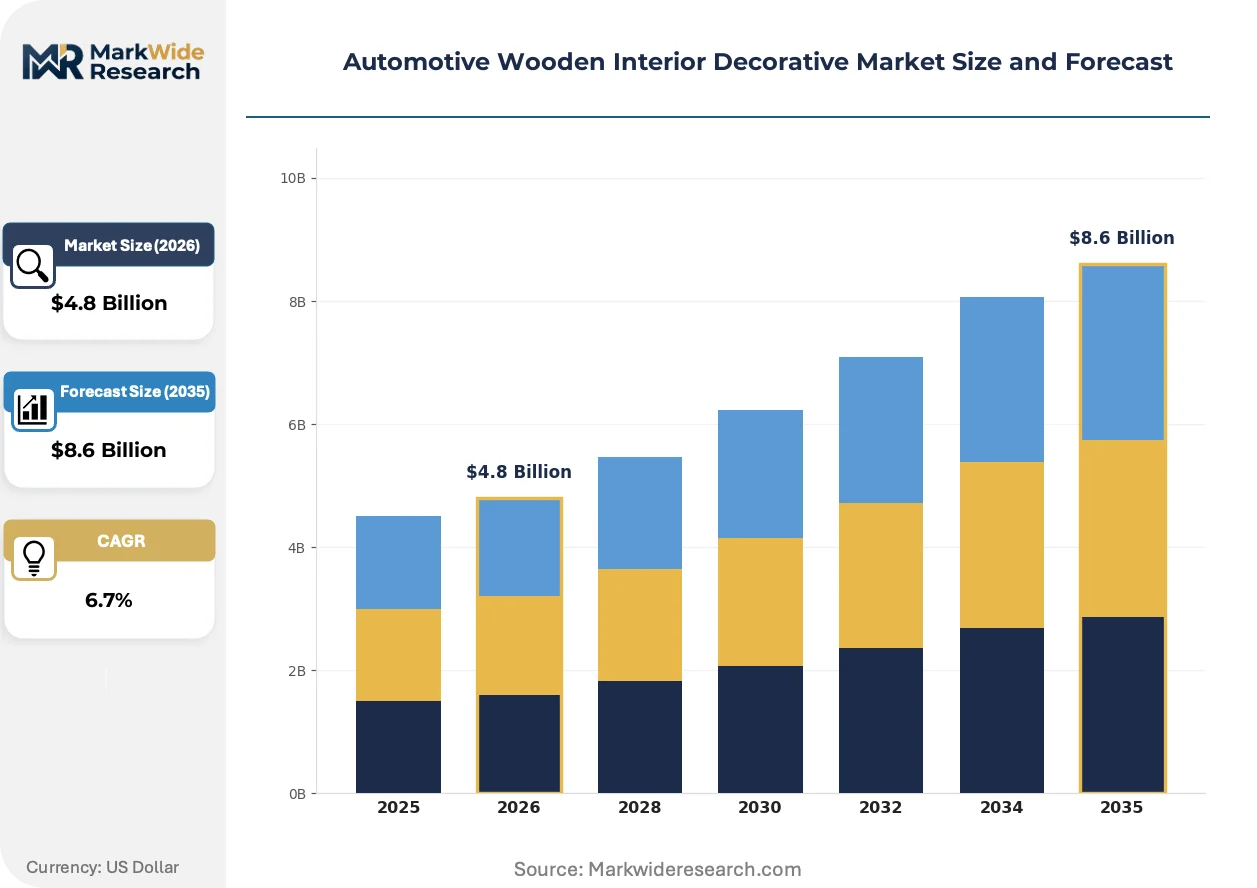
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboards, Door Panels, Console Trims, Steering Wheel Covers Material: Oak, Walnut, Maple, Bamboo Application: Luxury Vehicles, SUVs, Sedans, Electric Vehicles End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Customization Shops |
| Companies Covered | NAS Northern Automotive Systems, NBHX Trim Management Services, FormWood Industries, Sage Automotive Interior Trim, Luxwood Trim, Mata Automotive, ATD Coventry, Neaton Auto Products Manufacturing, Novem Car Interior Design, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wooden Interior Decorative Market Strategic Shifts
Production economics are tilting toward hybrid substrates that preserve authentic grain presentation while compressing material throughput, with regulatory pressure and buyer preference convergence accelerating technology adoption curves.
Laser-etched grain replication is virtualizing traditional veneer manufacturing by capturing natural wood patterns in digital archives for precise mechanical reproduction. Luxury EV cabin programs are adopting these systems fastest as they seek differentiation without the weight and cost penalties of solid wood construction. This virtualization is compressing the premium-mass-market price gap that historically protected natural veneer suppliers.
EU F-Gas Regulation restrictions on hydrofluorocarbon propellants are reshaping coating application technologies across interior component supply chains. Surface finishing operations are retrofitting production lines to accommodate waterborne and UV-cured alternatives that eliminate regulated substances. Dashboard applications face the steepest compliance burden given their visibility centrality and OEM quality specifications.
Buyer concentration among luxury EV nameplates is compressing traditional tiered supplier relationships into direct OEM-finisher partnerships. Long-standing distribution through interior system integrators is giving way to co-development agreements that lock in volume commitments against dedicated capacity investments. This restructuring is most visible in Germany and Japan, where premium vehicle engineering headquarters maintain closest proximity to specialized trim suppliers.
Automotive Wooden Interior Decorative Market Segmentation
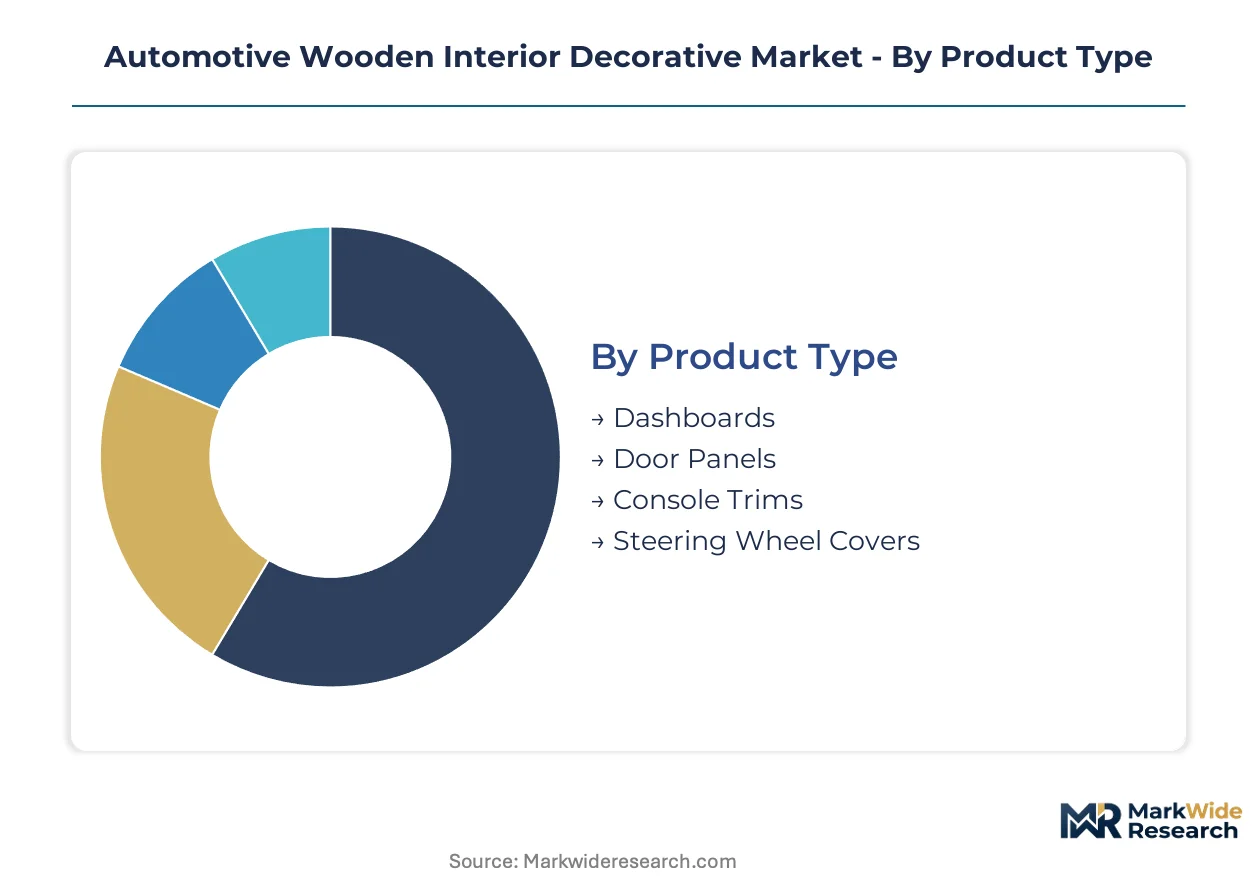
Automotive wooden interior decorative components demand precise segmentation because specification standards, regulatory compliance burdens, and value chain relationships differ sharply across cabin locations and material grades. Tier-one suppliers configure production cells around these segment boundaries to optimize tooling amortization and finishing consistency.
Product Type:
After-sales service intensity varies dramatically by installation location, with dashboard replacements requiring full cabin disassembly compared to door panel swaps that independent shops handle routinely.
- Dashboards:These components integrate multiple veneer segments around instrument clusters and infotainment screens, demanding 0.5–1.2 mm veneer thickness tolerances and polyurethane hot-melt adhesive bonding. Demand concentrates in Germany and Japan where premium vehicle engineering headquarters specify complex curved geometries. Dashboard programs generate the deepest value pools due to visibility centrality and OEM quality specifications that exclude most aftermarket competition.
- Door Panels:Door applications utilize simpler flat-surface geometries with lower engineering complexity, enabling broader supplier participation. Demand clusters in United States manufacturing where pickup truck and SUV platforms specify extensive wood trim packages. Door panel specifications allow faster qualification cycles and higher aftermarket penetration than dashboard programs.
- Console Trims:Center console applications balance visibility with moderate complexity, typically involving smaller veneer surfaces with integrated switch cutouts.
- Steering Wheel Covers:These components face the most stringent safety compliance due to airbag integration requirements and driver contact intensity.
Dashboards hold the largest share; momentum sits with console trims as electric vehicle platforms reconfigure cabin architectures.
Material:
Raw material selection determines procurement geography, carbon accounting methodology, and finishing protocol compatibility across supplier operations.
- Oak:European white oak dominates volume programs due to favorable workability, consistent grain structure, and established supply chains across Central European forestry partnerships. Oak accepts UV-cured polyurethane coatings readily, achieving 90+ gloss unit specifications that OEMs require for dashboard visibility zones. Demand concentrates in German premium vehicle production where traditional craftsmanship associations reinforce specification loyalty.
- Bamboo:Fast-growth grass alternatives are gaining procurement share under sustainability-weighted OEM frameworks that reward biogenic carbon accounting advantages. Bamboo matures in 3–5 years versus 40–60 years for hardwoods, compressing working capital cycles for suppliers with captive cultivation partnerships. Demand expansion is steepest in electric vehicle programs where environmental credentials substitute for powertrain differentiation.
- Walnut:Dark grain patterns command premium positioning in ultra-luxury nameplates with limited production volumes.
- Maple:Lighter tone specifications serve Scandinavian-influenced interior design trends and specific Japanese OEM palettes.
Oak maintains volume leadership; bamboo is climbing the fastest as ESG procurement frameworks harden.
Application:
Vehicle platform architecture dictates veneer specification grade, with electric vehicle programs rewriting traditional material intensity assumptions.
- Luxury Vehicles:Ultra-premium nameplates specify solid wood construction and hand-finished lacquer applications that resist digital veneer patterning substitution. These programs concentrate in German and Japanese manufacturing clusters where tier-one suppliers maintain dedicated finishing capacity. Luxury vehicle buyers accept weight penalties and cost premiums that mid-tier segments reject.
- Electric Vehicles:Cabin differentiation has replaced powertrain distinction as the primary buyer decision factor, expanding real wood adoption beyond traditional luxury boundaries. Laser-etched grain replication technology enables EV manufacturers to specify authentic tactile surfaces without solid wood weight penalties. Demand expansion is fastest in United States and Chinese electric vehicle programs targeting premium market positioning.
- SUVs:Sport utility platforms specify extensive wood trim packages across multiple cabin zones to justify price positioning.
- Sedans:Traditional passenger car applications face compression as SUV and EV platforms capture buyer preference shifts.
Luxury vehicles retain the highest specification intensity; electric vehicles are gaining share fastest.
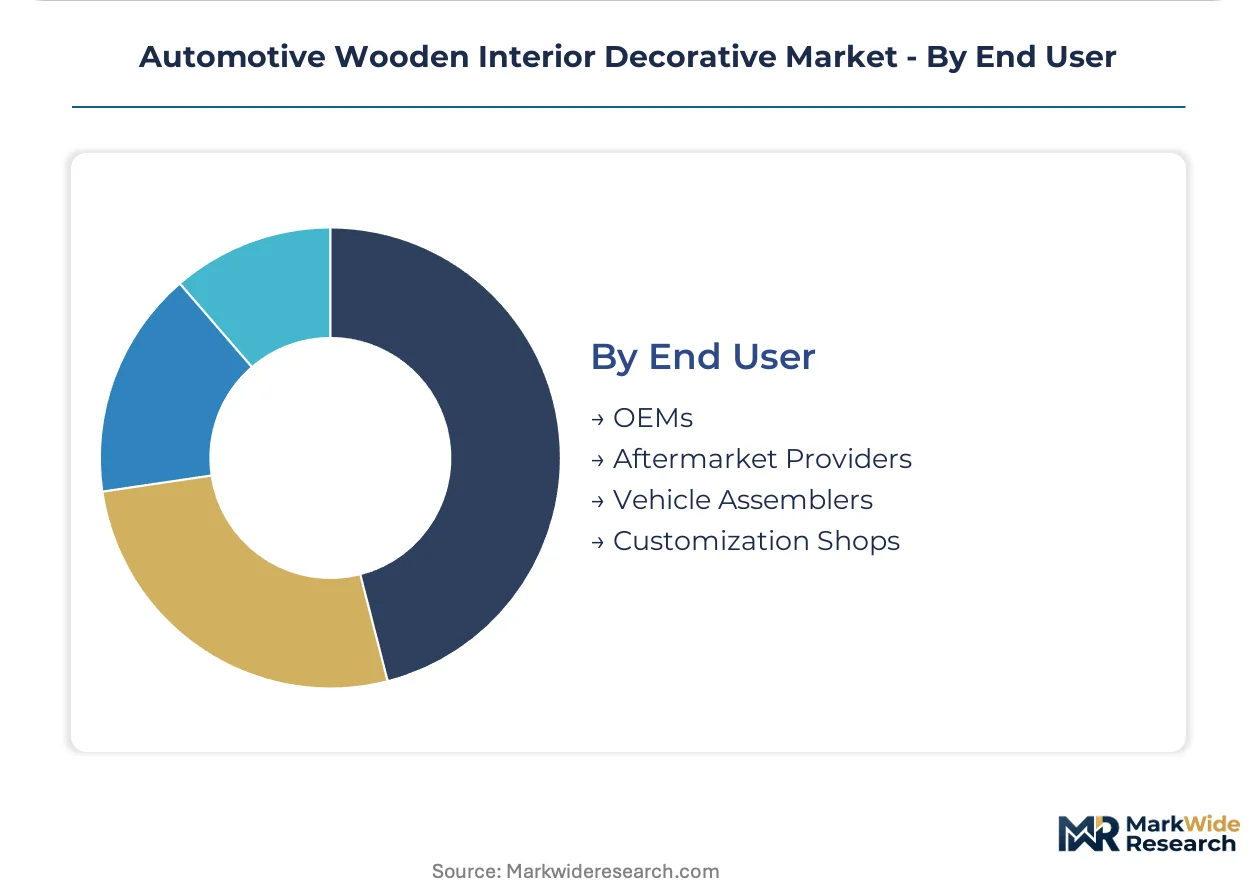
End User:
Customer type determines contract structure, with OEM direct relationships demanding dedicated capacity investments that aftermarket channels avoid.
- OEMs:Original equipment manufacturers specify co-development agreements with tier-one suppliers that lock in volume commitments against dedicated finishing line investments. These contracts span multi-year vehicle programs with stringent ECHA REACH and EPA TSCA Title VI compliance documentation requirements. OEM relationships concentrate qualification risk but generate predictable revenue streams.
- Aftermarket Providers:Independent distribution channels serve vehicle owners seeking cabin upgrades or collision repair replacements, with lower specification tolerances and faster fulfillment expectations. Aftermarket demand clusters in United States and Germany where premium vehicle parc density supports specialized trim retailers. These channels avoid the multi-jurisdictional type approval burdens that constrain OEM supply.
- Vehicle Assemblers:Contract manufacturing operations for emerging EV brands purchase pre-finished trim modules for final cabin integration.
- Customization Shops:Boutique operators serve ultra-high-net-worth buyers with bespoke veneer selection and artisan finishing protocols.
OEMs dominate volume; customization shops command the highest unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-luxury vehicle buyers concentrate in Germany, Japan, and the United States, where premium automotive engineering headquarters maintain proximity to specialized veneer finishing capacity. Electric vehicle manufacturers in these markets deploy real wood trim as cabin differentiation supersedes powertrain distinction. Regulatory frameworks across multiple jurisdictions reshape supplier qualification requirements and material traceability investments.
Germany
Mercedes-Benz, BMW, and Audi specify complex curved dashboard geometries requiring 0.5–1.2 mm veneer thickness tolerances. ECHA REACH substance restrictions on volatile organic compounds accelerate UV-cured polyurethane adoption. Stuttgart and Munich engineering clusters drive co-development agreements that consolidate tier-one supplier relationships around dedicated finishing lines.
Japan
Lexus and Toyota premium platforms emphasize traditional craftsmanship associations reinforcing oak specification loyalty. METI industrial standards govern adhesive systems and surface coating protocols for cabin-grade components. Nagoya and Tokyo manufacturing corridors concentrate thermoforming expertise for intricate instrument cluster integrations.
United States
Tesla, Rivian, and Lucid Motors expand real wood applications across electric vehicle cabins as powertrain homogenization intensifies. EPA TSCA Title VI formaldehyde emission standards add compliance layers for laminated substrate producers. Detroit and California premium vehicle assembly operations anchor demand for extensive SUV and pickup truck wood trim packages.
China
Domestic EV brands NIO, Li Auto, and XPeng specify laser-etched grain replication technology to compress premium-mass-market pricing gaps. GB standards and MIIT regulations govern interior material safety and volatile organic compound thresholds. Yangtze River Delta manufacturing zones attract tier-one suppliers establishing captive finishing capacity for volume programs.
India
Mercedes-Benz India, BMW India, and Jaguar Land Rover domestic assembly operations expand addressable demand beyond traditional manufacturing clusters. BIS certification requirements and DGFT import regulations shape material sourcing strategies for luxury vehicle components. Maharashtra and Gujarat automotive corridors develop supplier ecosystems for premium cabin trim integration.
Automotive Wooden Interior Decorative Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that consolidates around tier-one suppliers with captive forestry partnerships and integrated finishing capabilities. The vendor base stratifies into three archetypes: forestry-integrated processors commanding cost-advantaged walnut and oak supply chains, thermoforming specialists controlling complex dashboard geometry production, and finishing-integrated operators monetizing lacquer application consistency as a separate service layer. Dominant competitive moves include strategic partnerships securing deforestation-free traceability certifications and capacity expansion into electric vehicle platform co-development agreements.
Among forestry-integrated processors, NBHX Trim Management Services exemplifies the captive supply chain archetype through its Central European partnerships. FormWood Industries occupies a position within the thermoforming specialization tier, while Mata Automotive represents the finishing-integrated model controlling lacquer application consistency across high-volume programs. These three entities anchor distinct competitive vectors that reshape traditional tiered supplier relationships into direct OEM-finisher partnerships locking volume commitments against dedicated capacity investments.
| Leading Market Players |
|---|
| NAS Northern Automotive Systems |
| NBHX Trim Management Services |
| FormWood Industries |
| Sage Automotive Interior Trim |
| Luxwood Trim |
| Mata Automotive |
| ATD Coventry |
| Neaton Auto Products Manufacturing |
| Novem Car Interior Design |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine freight corridor's container rate volatility transmits directly into Central European veneer supply economics, compressing margin structures for suppliers without captive forestry partnerships while amplifying price differentiation between oak-sourced dashboard programs and bamboo-alternative console trims.
Pricing Analysis
Cost-plus contracts indexed to FOB Hamburg hardwood futures dominate OEM supply agreements, with polyurethane adhesive and UV-cured lacquer costs passed through via quarterly adjustments. Price differentiation hinges on veneer thickness certification tiers and ECHA REACH compliance documentation depth, with ultra-luxury solid wood construction commanding premiums against laser-etched hybrid substrates. Cost compression in mid-tier electric vehicle programs is intensifying because synthetic composite competitors exploit thermoforming scale advantages. Fleet procurement teams at volume EV manufacturers exhibit highest price sensitivity, while ultra-luxury nameplate buyers remain least responsive to unit cost fluctuations.
Supply Chain Analysis
EU dual-use export controls on precision laser-etching equipment constrain technology transfer to emerging finishing operations, preserving capability concentration among established Central European suppliers. Geographic supply concentration centers on Germany, Croatia, and Romania for oak veneer, with bamboo cultivation anchored in Zhejiang and Anhui provinces. Raw material dependencies encompass polyurethane hot-melt adhesives, UV-cured coating resins, and formaldehyde-scavenging substrates. Single-source vulnerability pervades thermoforming tooling for complex dashboard geometries. Distribution runs through tier-one interior system integrators co-located with German and Japanese OEM engineering headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermoforming expertise for instrument cluster integration represents the scarcest production capability, constraining capacity expansion timelines and consolidating pricing power among incumbents with dedicated tooling knowledge.
For Market Incumbents: Pre-empt synthetic composite substitution by deepening captive forestry partnerships in Croatia and Romania while accelerating UV-cured polyurethane certification under evolving ECHA substance restrictions. Lock in multi-year co-development agreements with luxury EV platforms before thermoforming capacity scarcity forces OEMs toward polymer alternatives. For New Entrants and Emerging Players: India's Maharashtra and Gujarat automotive corridors offer underpenetrated access as Mercedes-Benz India and BMW India expand domestic assembly operations. Target vehicle assembler relationships for emerging EV brands purchasing pre-finished trim modules, bypassing tier-one supplier qualification barriers through direct module supply contracts. For Investors and Strategic Acquirers: Forestry-integrated processors with Central European walnut partnerships and existing EUDR traceability infrastructure present the most defensible acquisition profile. Monitor biogenic carbon accounting methodology adoption rates as the inflection indicator for bamboo procurement framework expansion versus traditional hardwood retention.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forestry Partnership Expansion | Secures cost-advantaged oak supply chains against REACH-compliant competitors in Croatia and Romania. |
| UV-Cured Coating Line Retrofit | Eliminates hydrofluorocarbon propellants under EU F-Gas Regulation for dashboard finishing operations. |
| Laser-Etching Technology Licensing | Enables hybrid substrate production preserving tactile authenticity without solid wood weight penalties. |
| India Manufacturing Footprint Establishment | Positions suppliers for domestic luxury vehicle assembly growth in Maharashtra and Gujarat corridors. |
| EUDR Traceability System Investment | Qualifies suppliers for deforestation-free procurement mandates reshaping OEM qualification criteria. |
Study Parameters
Cross-validation between primary interviews with tier-one supplier procurement directors, OEM platform engineers, and aftermarket distributors anchors the qualitative findings against secondary validation from vehicle production databases, IHS Markit registration data, customs hardwood trade records, and ECHA substance restriction updates. Bottom-up segment sizing triangulates against top-down market value reconstruction across the analysis window.
Calibration against historical CAGRs in adjacent automotive interior component markets informs the projection framework, with segmentation modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. Growth rate derivation incorporates veneer thickness specification trends, electric vehicle platform launch schedules, and sustainability-weighted procurement framework adoption curves without year-specific binding.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by synthetic composite specialists or sudden EUDR enforcement acceleration would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market