
 PVC and PU Leather for Automotive Market | 2026-2036
PVC and PU Leather for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
PVC and PU Leather for Automotive Market Insights
Asian synthetic leather production is decoupling from European petrochemical feedstock dependence as regional polyol and plasticizer capacity expands. Benecke-Kaliko leverages its German engineering heritage to sustain premium OEM contracts for dashboard and door panel surfaces. Mayur Uniquoters anchors South Asian supply through integrated PVC calendering and embossing operations that compete on cost for seat cover programs.
PVC and PU leather for automotive refers to coated fabric materials manufactured from polyvinyl chloride or polyurethane resins bonded to textile substrates, typically achieving abrasion resistance above 100,000 Martindale cycles and flame retardancy meeting FMVSS 302 standards for vehicle interiors. These materials serve as engineered substitutes for natural leather in passenger compartments where weight reduction, design flexibility, and cost control are prioritized. PU leather applications in upholstery lead segment value due to softer hand-feel and lower VOC emissions that align with cabin air quality protocols. Dashboard trim represents a faster-growing application as curved display integration demands thermoformable surface materials with uniform grain reproduction.
EPA tailpipe and interior air quality rules, alongside REACH substance restrictions on phthalates and isocyanates, are forcing reformulation of traditional PVC plasticizers and PU curing agents across supplier tiers. China's GB standards for automotive interior emissions and the EU's F-Gas Regulation on blowing agents for PU foams add compliance layers that favor producers with in-house chemical testing laboratories. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation specialization or universal low-emission platforms offer superior capital efficiency.
Market Dynamics
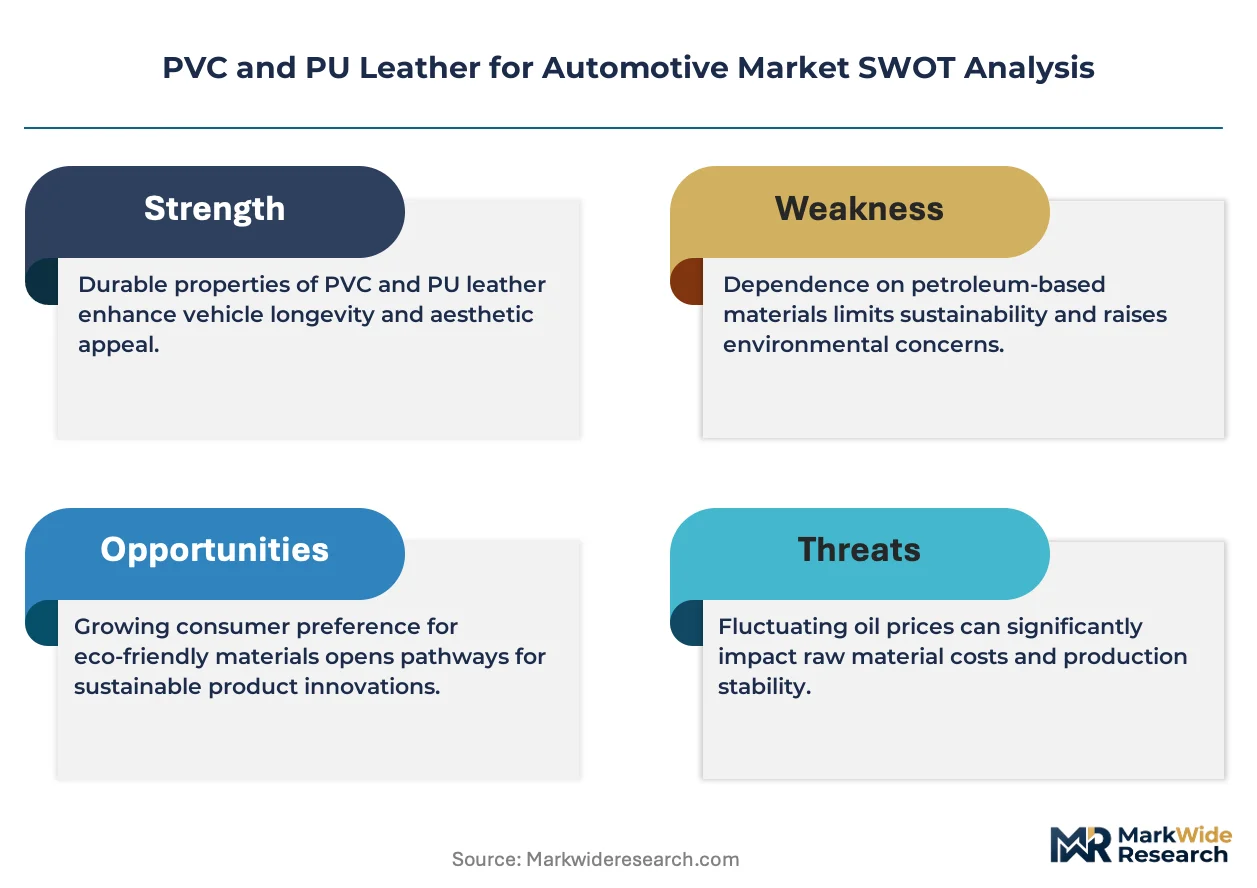
REACH substance restrictions on phthalates and isocyanates are forcing reformulation across PVC plasticizer and PU curing agent supply chains, compressing margins for suppliers without in-house chemical testing infrastructure.
Growth Catalysts
- Electric vehicle seating programs:OEMs specify synthetic leather for mass-market EV platforms to achieve weight targets and design flexibility unavailable with natural hides.
- REACH compliance deadlines:European volatile organic compound thresholds for interior finishes are accelerating adoption of waterborne PU systems with lower solvent content.
- China's GB standards:Domestic vehicle assemblers scale synthetic leather sourcing to meet mandatory cabin air quality protocols for new vehicle certifications.
Market Restraints
- Petrochemical feedstock volatility:Polyol and plasticizer input costs fluctuate with crude oil derivatives, squeezing compounder margins during price spikes.
- Regional supply concentration:Asian polyol capacity expansion creates dependency on a limited geography for critical resin intermediates.
- Natural leather substitution threat:Premium OEM segments retain hide-based materials for tactile differentiation in luxury vehicle lines.
Strategic Opportunities
- Dashboard display integration:Curved screen architectures demand thermoformable surface materials with uniform grain reproduction across complex geometries.
- EU F-Gas Regulation:Blowing agent restrictions for PU foams favor producers with low-GWP formulation platforms and captive chemical R&D.
- Aftermarket refurbishment channels:Independent upholstery specialists seek certified synthetic leather rolls for vehicle interior renewal programs.
Industry Challenges
- Formulation chemist scarcity:Expertise in low-VOC plasticizer substitution and bio-based polyol blending resides with a narrow talent pool concentrated in Germany and Japan.
- Dual certification timelines:Suppliers must parallel-track EPA and REACH compliance documentation, extending product launch cycles by 8-14 months.
- Legacy equipment retrofit costs:Calendering lines require capital-intensive upgrades to process waterborne PU coatings without solvent recovery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC and PU Leather for Automotive Market |
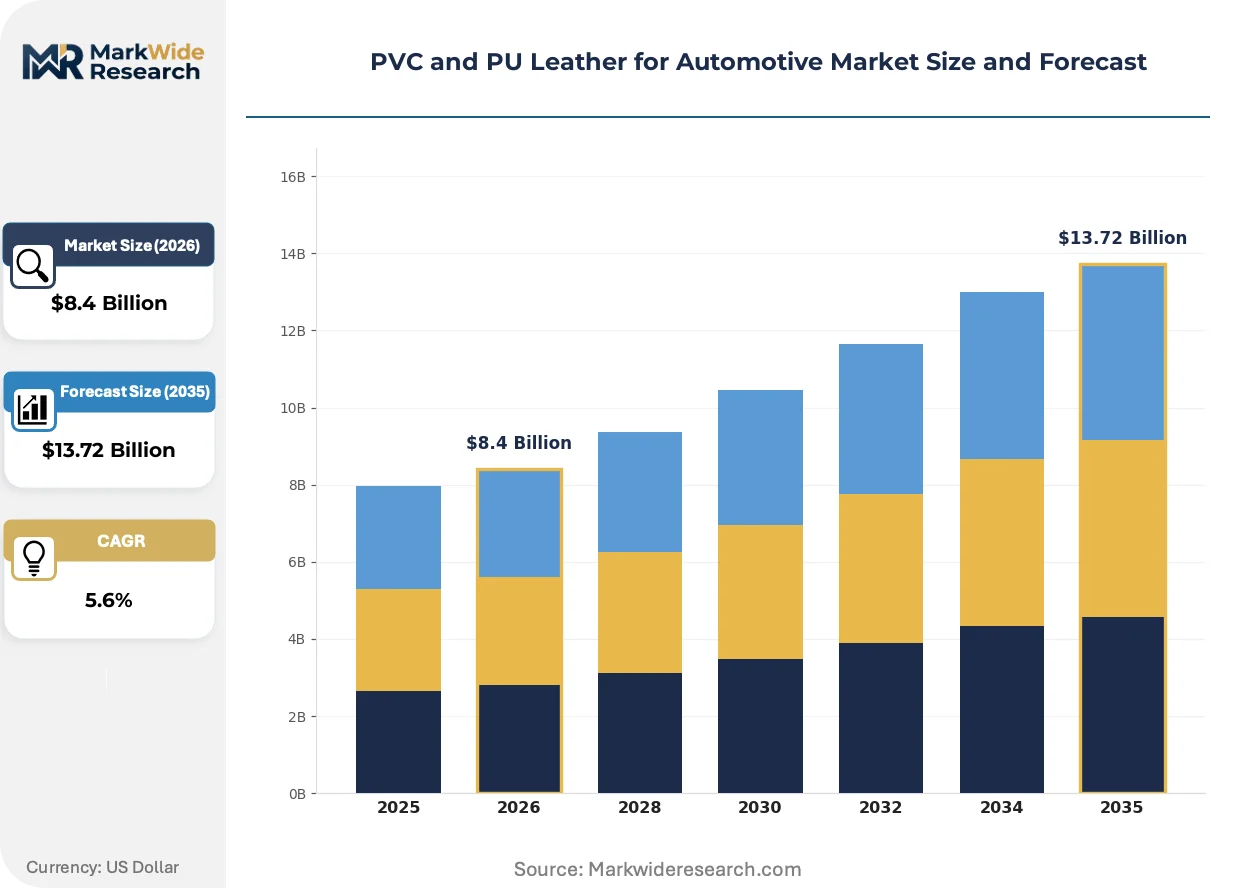
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.72 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVC Leather, PU Leather, Synthetic Leather, Natural Leather Application: Upholstery, Dashboard, Trim, Seat Covers End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Suppliers Manufacturing Stage: Raw Materials, Finished Goods, Semi-Finished Products, Custom Solutions |
| Companies Covered | Benecke-Kaliko, Kyowa Leather Cloth, CGT, Archilles, Vulcaflex, Mayur Uniquoters, Scientex Berhad, Fujian Polyrech Technology, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC and PU Leather for Automotive Market Trends and Innovations
Material science advances are compressing the performance gap between synthetic and natural leather while regulatory chemistry constraints are locking in formulation winners.
Waterborne polyurethane coating technology is converging with textile substrate engineering to produce soft-touch surfaces that meet FMVSS 302 flame retardancy without solvent-based processing. Tier 1 seating suppliers in Germany and South Korea are adopting these systems for premium EV programs. The technology is converging with curved dashboard manufacturing to enable seamless grain continuity across display-integrated panels.
EPA interior air quality rules are tightening formaldehyde and VOC thresholds for vehicle cabin materials, forcing compounders to validate every plasticizer lot through third-party emissions testing. Suppliers without captive laboratories face outsourcing costs that erode project economics. Dashboard trim applications face the steepest compliance burden due to larger surface area-to-volume ratios in passenger compartments.
Fleet operators and mobility service providers now specify synthetic leather based on total cost of ownership metrics rather than upfront material cost. Rental vehicle procurement departments in the United States prioritize abrasion resistance above 150,000 Martindale cycles to minimize seat replacement frequency. This specification-driven purchasing is visible most acutely in airport shuttle and ride-hail vehicle programs where interior durability directly impacts residual value calculations.
PVC and PU Leather for Automotive Market Segmentation
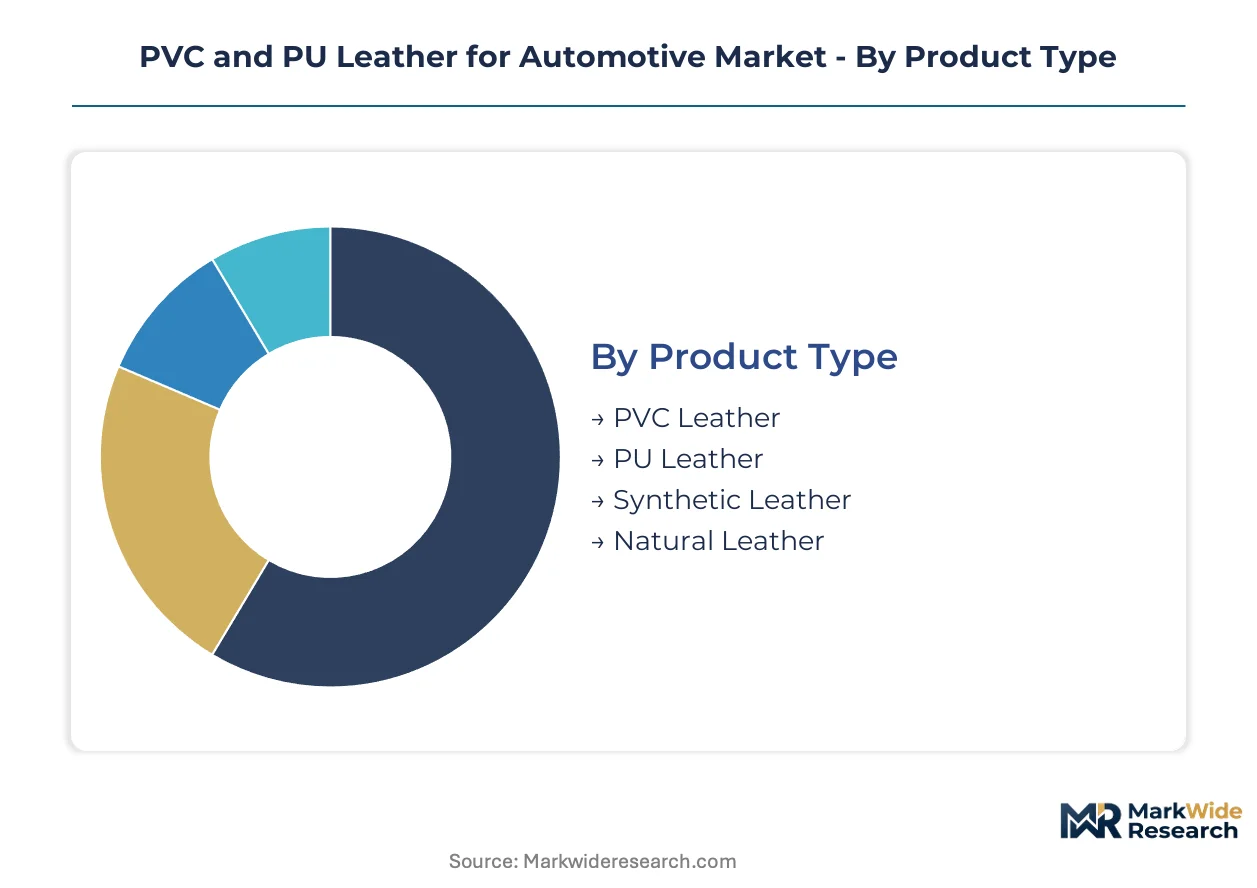
Material specification hierarchies in automotive interiors segment demand across performance tiers, manufacturing complexity, and regulatory compliance pathways. Each dimension reveals distinct competitive dynamics between incumbent suppliers and emerging challengers.
Product Type:
Technical performance thresholds separate synthetic formulations from natural alternatives across abrasion resistance, VOC emissions, and thermoformability specifications.
- PU Leather:Polyurethane resin systems bonded to textile substrates deliver softer hand-feel and lower solvent content that aligns with REACH-compliant cabin air quality protocols. Demand concentrates in European and South Korean premium EV seating programs where OEMs specify waterborne coating systems.
- PVC Leather:Polyvinyl chloride calendered coatings achieve cost positioning for mass-market vehicle platforms while facing reformulation pressure from phthalate restrictions under EPA and ECHA guidelines. Chinese domestic assemblers scale PVC sourcing for entry-level EV interiors where GB standard compliance remains achievable with modified plasticizer packages.
- Synthetic Leather:Umbrella category spanning bio-based polyol formulations and recycled content variants serves sustainability-positioned vehicle lines. Procurement runs through specialized compounders with captive emissions testing laboratories.
- Natural Leather:Hide-based materials retain specification in luxury vehicle segments where tactile differentiation commands price premiums. Sourcing concentrates with Italian and German tanneries serving heritage OEM brands.
Mature deployment sits with PVC Leather. Newer deployment is concentrated in PU Leather.
Application:
Surface area-to-volume ratios and passenger contact frequency determine compliance burden intensity across interior zones.
- Upholstery:Seat and headliner applications dominate segment value through direct skin contact requirements that elevate VOC testing rigor. Fleet operators in the United States specify abrasion resistance above 150,000 Martindale cycles for ride-hail vehicle programs.
- Dashboard:Curved display integration demands thermoformable substrates with uniform grain reproduction across complex geometries. German Tier 1 suppliers pioneer seamless surface technologies for premium EV architectures.
- Trim:Door panel and pillar applications balance aesthetic flexibility with FMVSS 302 flame retardancy requirements. Cost pressure is most acute in this category due to lower visibility relative to seating.
- Seat Covers:Aftermarket refurbishment channels seek certified synthetic leather rolls with matched grain patterns for interior renewal programs. Independent upholstery specialists in North America drive specification diversity.
Volume leadership resides with Upholstery. Technology differentiation concentrates in Dashboard.
End User:
Procurement authority and specification control vary dramatically across the value chain, fragmenting supplier relationship strategies.
- OEMs:Brand-holding manufacturers dictate material specifications through platform engineering teams that validate every plasticizer lot through third-party emissions testing. Compliance documentation requirements extend product launch cycles significantly.
- Vehicle Assemblers:Contract manufacturers in China scale synthetic leather sourcing through consolidated procurement functions serving multiple domestic EV platforms. Cost optimization dominates supplier selection criteria.
- Suppliers:Tier 1 seating and interior module producers maintain formulation expertise in low-VOC plasticizer substitution concentrated in German and Japanese engineering centers. Talent scarcity constrains expansion timelines.
- Aftermarket Providers:Independent channels seek certified material rolls with batch consistency for vehicle interior refurbishment. Specification authority is limited to durability and color-matching requirements.
Specification control concentrates with OEMs. Volume scaling is most visible with Vehicle Assemblers.
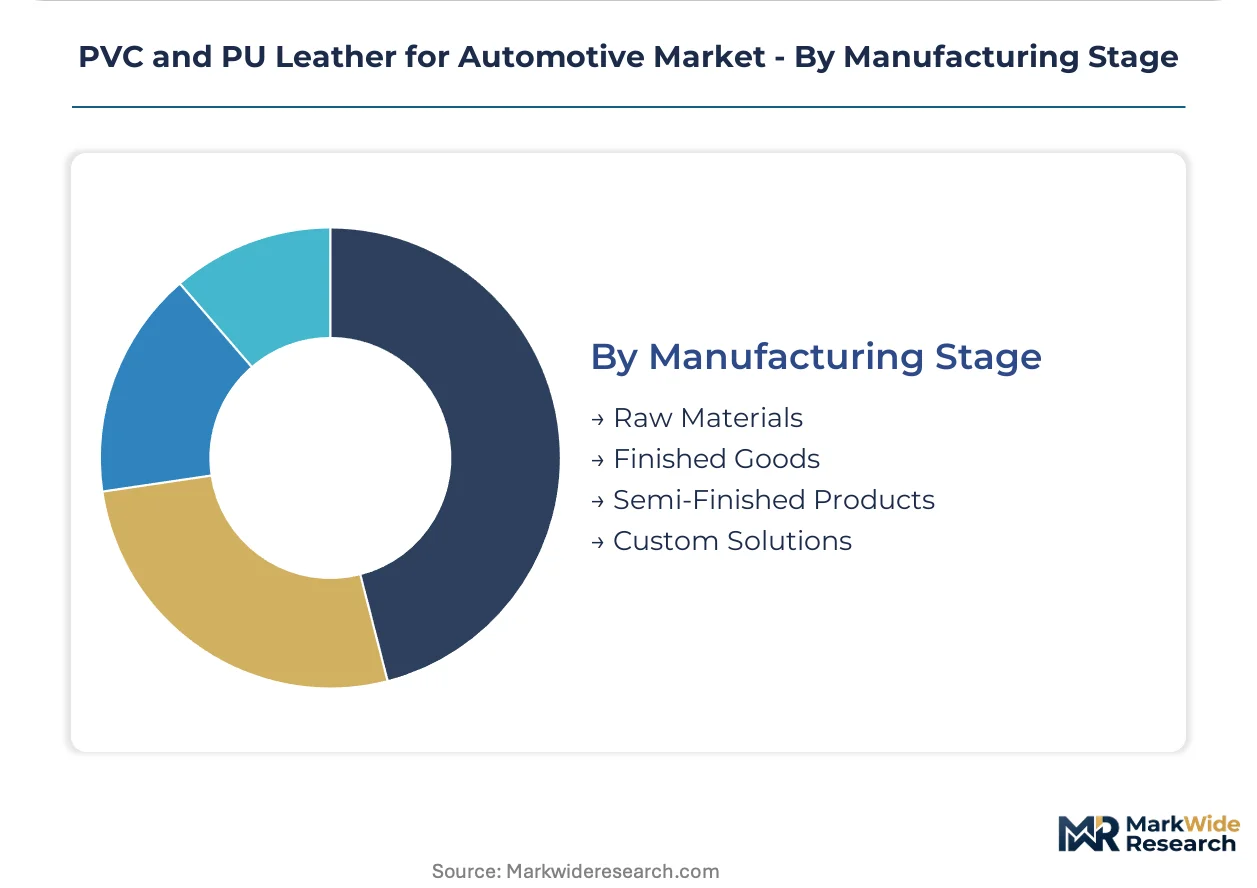
Manufacturing Stage:
Value capture and margin profile shift dramatically across the transformation curve from commodity resin to finished interior component.
- Raw Materials:Polyol and plasticizer intermediates face petrochemical feedstock volatility that squeezes compounder margins during crude oil derivative price spikes. Asian capacity expansion is decoupling regional production from European feedstock dependence.
- Semi-Finished Products:Coated fabric rolls and embossed substrates require capital-intensive calendering lines with solvent recovery systems or waterborne coating upgrades. Equipment retrofit costs burden suppliers without captive capital.
- Finished Goods:Cut-and-sewn seat covers and formed dashboard skins command premium positioning through design integration and just-in-sequence delivery capabilities. Proximity to vehicle assembly plants determines competitive viability.
- Custom Solutions:Bespoke grain development and color matching for limited-production vehicle lines serve heritage luxury OEMs. Margins are highest in this category but volumes are constrained.
Capital intensity peaks with Semi-Finished Products. Margin expansion is steepest in Custom Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock concentration in East Asia anchors synthetic leather production networks, while regulatory divergence across major automotive markets fragments formulation standards and compliance pathways.
China
Domestic EV assemblers in Shanghai and Guangzhou scale PVC sourcing for mass-market platforms where GB standards for cabin air quality apply mandatory emissions testing. MIIT oversees vehicle certification protocols that synthetic leather suppliers must satisfy through third-party laboratory validation. The Yangtze River Delta hosts integrated calendering operations serving BYD, NIO, and XPeng seating programs.
Germany
Premium OEM engineering teams in Munich and Stuttgart specify waterborne PU systems for curved dashboard architectures in electric vehicle lineups. ECHA enforces REACH substance restrictions on phthalates and isocyanates that force reformulation of traditional plasticizers and curing agents. The Stuttgart region concentrates Tier 1 seating supplier R&D facilities developing low-VOC coating technologies.
United States
Fleet operators and ride-hail procurement departments prioritize abrasion-resistant seat covers exceeding 150,000 Martindale cycles for total cost of ownership optimization. EPA interior air quality rules tighten formaldehyde thresholds that compounders must validate through emissions testing documentation. The Southeast automotive corridor spanning Tennessee, South Carolina, and Alabama attracts cut-and-sew operations proximal to BMW, Mercedes-Benz, and Volkswagen assembly plants.
Japan
Automotive interior module producers in Nagoya and Osaka maintain formulation expertise in bio-based polyol blending and low-VOC plasticizer substitution. METI coordinates with JIS standard committees on flame retardancy specifications for passenger compartment materials. The Chubu region hosts specialized compounders serving Toyota, Honda, and Nissan platform engineering teams.
South Korea
Hyundai and Kia seating programs in Asan and Gwangmyeong adopt waterborne PU coating systems for premium EV interiors targeting European export markets. MFDS alignment with international chemical safety protocols influences supplier qualification requirements for plasticizer packages. The Seoul Capital Area concentrates textile substrate engineering facilities integrating Korean woven backing with polyurethane surface layers.
PVC and PU Leather for Automotive Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and OEM relationship depth, producing a tiered structure where scale-driven compounders, specialized coating technology developers, and integrated textile-substrate producers occupy distinct competitive positions. The market structure fragments across three strategic archetypes: European engineering-led premium suppliers, Asian cost-optimized volume producers, and integrated calendering-to-embossing operators. Dominant competitive moves include geographic expansion through licensing arrangements and backward integration into polyol and plasticizer intermediates to secure margin control.
Among European engineering-led suppliers, Benecke-Kaliko occupies a position exemplifying premium OEM contract retention through German technical heritage in dashboard and door panel surface development. Asian volume producers include Mayur Uniquoters, which anchors South Asian supply through integrated PVC operations competing on cost for seat cover programs, and Kyowa Leather Cloth, representing Japanese formulation expertise concentrated in automotive textile coating.
| Leading Market Players |
|---|
| Benecke-Kaliko |
| Kyowa Leather Cloth |
| CGT |
| Archilles |
| Vulcaflex |
| Mayur Uniquoters |
| Scientex Berhad |
| Fujian Polyrech Technology |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Formulation chemist scarcity in Germany and Japan widens pricing-tier spreads as labor-cost differentials between these engineering centers and Asian manufacturing clusters amplify spreads between premium waterborne PU systems and economy-grade PVC alternatives.
Pricing Analysis
Warranty-backed emissions certification separates bundled from unbundled offerings, with premium OEM contracts validating every plasticizer lot through third-party laboratory documentation while mass-market programs strip out testing costs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with REACH-compliant waterborne systems commanding spreads over phthalate-modified PVC. Pricing pressure stems from petrochemical feedstock volatility squeezing compounder margins during crude oil derivative spikes. Fleet operators exhibit highest price sensitivity through total cost of ownership metrics, while luxury OEMs prioritize tactile performance over unit economics.
Supply Chain Analysis
China's GB standard compliance requirements and domestic-content preferences for MIIT vehicle certification are reshaping sourcing patterns toward Yangtze River Delta calendering operations. Polyol and plasticizer intermediates draw from Chinese, South Korean, and German petrochemical networks, with textile substrates and coating resins as critical inputs. Single-source vulnerability concentrates in Asian polyol capacity expansion creating geographic dependency for resin intermediates. Distribution runs through Tier 1 seating suppliers and direct OEM platform engineering channels with just-in-sequence delivery requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market functions as a vertical-integration race where captive control over emissions-testing laboratories and polyol formulation expertise determines margin retention against reformulation cost pressures.
For Market Incumbents: Anticipate REACH substance restriction expansions by securing in-house chemical testing infrastructure before compliance documentation requirements extend product launch cycles. Backward integration into waterborne PU coating technology and bio-based polyol blending capabilities defends position against emerging Asian compounders with cost-optimized volume production. Priority rests on German and Japanese R&D facility expansion to retain formulation chemist talent concentration. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap offers white-space targeting through certified aftermarket refurbishment channels seeking batch-consistent synthetic leather rolls with matched grain patterns. Aftermarket seat cover programs for ride-hail vehicle fleets represent the most penetrable segment given specification authority limited to durability and color-matching. Go-to-market execution should leverage direct relationships with independent upholstery specialists bypassing consolidated OEM procurement functions. For Investors and Strategic Acquirers: Re-rating potential sits with integrated calendering-to-embossing operators given waterborne PU coating technology adoption accelerating across premium EV seating programs. Long-term viability over the projection horizon favors producers with captive chemical R&D and low-GWP formulation platforms serving European export markets. Acquisition target archetype encompasses South Asian PVC compounders with cost positioning and laboratory-upgrade runway. Signal to watch is EPA formaldehyde threshold tightening forcing emissions testing infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Production | Captive resin supply secures margin control against petrochemical feedstock volatility from crude oil derivatives. |
| Waterborne PU Coating Technology Adoption | REACH-compliant systems align with ECHA phthalate restrictions while serving premium Hyundai and Kia EV programs. |
| Emissions Testing Laboratory Certification | Third-party validation capability satisfies MIIT GB standard requirements for Chinese domestic EV platform sourcing. |
| Dashboard Display Integration Partnership | Thermoformable substrate expertise enables seamless grain continuity across curved screen architectures for German OEMs. |
| Aftermarket Distribution Channel Expansion | Independent upholstery specialist networks capture fleet operator procurement for ride-hail vehicle refurbishment programs. |
Research Methodology
Independent corroboration across OEM platform engineering teams, Tier 1 seating supplier procurement directors, and aftermarket distribution channel managers underwrites the qualitative findings. Primary interviews with formulation chemists, calendering operations managers, and automotive interior module producers combined with secondary validation from vehicle production databases, customs and trade data on polyol imports, and SEC filings from listed compounders. Bottom-up segment sizing and top-down market triangulation cross-verify volume estimates across the analysis window.
Comparable-period anchoring to historical EV platform launches and synthetic leather specification adoption curves structured the forecast framework. Segmentation dimensions modeled include material type, application surface area-to-volume ratio, end-user procurement authority, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating OEM seating program pipelines and fleet operator replacement cycle data. Industry-specific inputs encompass Martindale cycle durability specifications and FMVSS 302 flame retardancy compliance rates.
Underlying measurement precision varies by segment; PU leather and dashboard applications carry tighter precision than aftermarket refurbishment channels given consolidated OEM procurement data availability. Forecasts reflect assumptions on regulatory timeline adherence and EV platform scaling trajectories. Petrochemical price volatility, REACH substance restriction scope expansion, and natural leather substitution resilience in luxury segments constitute primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Glass for Electric Vehicle Glass Roof Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
All Plastic Front End Module Market