
 Global Cabin Air Heater Market | 2026-2036
Global Cabin Air Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cabin Air Heater Market Analysis
ISO 26262 functional safety certification is bifurcating the competitive landscape for cabin air heater suppliers serving automotive OEM channels. Webasto leverages its captive electronics manufacturing to sustain compliance leadership across European passenger vehicle programs. Eberspaecher Climate Control Systems anchors its position through deep backward integration into burner and heat exchanger production. BorgWarner Inc. competes by extending its thermal management portfolio from powertrain into cabin comfort systems.
A cabin air heater is a thermal management device that warms the interior compartment of vehicles or vessels through combustion, electric resistance, or heat transfer from engine coolant, typically operating across voltage ranges from 12V to 800V depending on platform architecture. Its primary purpose is to maintain occupant comfort and defrost critical surfaces during cold ambient conditions without requiring continuous engine operation. Electric heaters now lead product type segmentation as battery electric vehicle platforms eliminate engine waste heat, while hydronic heaters retain structural importance in commercial vehicle segments where engine-coupled systems remain cost-effective. The OEM installation channel dominates value capture due to embedded control software and warranty integration, though aftermarket retrofit kits represent a concentrated margin pool in regions with aging commercial fleets.
FCC electromagnetic emissions standards, EPA Clean Air Act mobile source provisions, and EU Ecodesign requirements collectively constrain heater combustion efficiency and wireless control module certification pathways. These frameworks elevate engineering barriers for new entrants while compelling incumbents to redesign burner architectures and filter systems. Stakeholders must monitor evolving zero-emission vehicle mandates across California, Germany, and China to determine the pace of electric heater displacement versus hybrid thermal system coexistence.
Market Dynamics
The electrification of vehicle platforms is compressing heater architectures from multi-kilowatt combustion units toward compact high-voltage PTC and heat pump modules, forcing suppliers to rebuild thermal management competencies around 400V-800V electrical systems.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is accelerating OEM migration toward CO2-based heat pump systems that integrate cabin heating with battery thermal management.
- Commercial fleet electrification:Last-mile delivery operators in Germany and the United States are retrofitting electric vans with auxiliary electric heaters to maintain driver productivity during winter routes.
- High-voltage silicon carbide inverters:These power electronics are enabling faster thermal response in electric heaters, reducing energy draw from traction batteries during cold-start conditions.
Market Restraints
- Copper and nickel price volatility:Electric heater coils and battery thermal interface materials expose manufacturers to commodity swings that compress margin on fixed-price OEM contracts.
- Single-source dependency for ceramic PTC elements:Japanese and South Korean suppliers control specialized semiconductor-grade ceramics, creating concentration risk for European heater assemblers.
- Range degradation in extreme cold:Battery electric vehicle operators in Canada and Scandinavia experience 30-40% winter range loss, slowing fleet conversion timelines and extending demand for hybrid thermal solutions.
Strategic Opportunities
- India commercial vehicle market:Stringent BS-VI emission norms and expanding cold-chain logistics are creating first-time demand for auxiliary cabin heaters in medium-duty trucks previously unequipped with thermal comfort systems.
- Vehicle-to-grid thermal storage:Bidirectional charging infrastructure allows parked electric vehicles to sell stored heat back to building HVAC systems, opening new revenue streams for fleet operators.
- California Advanced Clean Trucks regulation:The mandate for zero-emission medium and heavy-duty vehicles is pulling forward demand for integrated battery-cabin thermal management systems from 2024 compliance deadlines.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 ASIL-D certification for high-voltage heater control units requires specialized embedded systems talent that automotive suppliers compete aggressively to secure.
- Legacy combustion heater service network stranding:Decades of technician training in diesel-fired unit maintenance creates capability gaps as electric systems displace familiar burner architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cabin Air Heater Market |
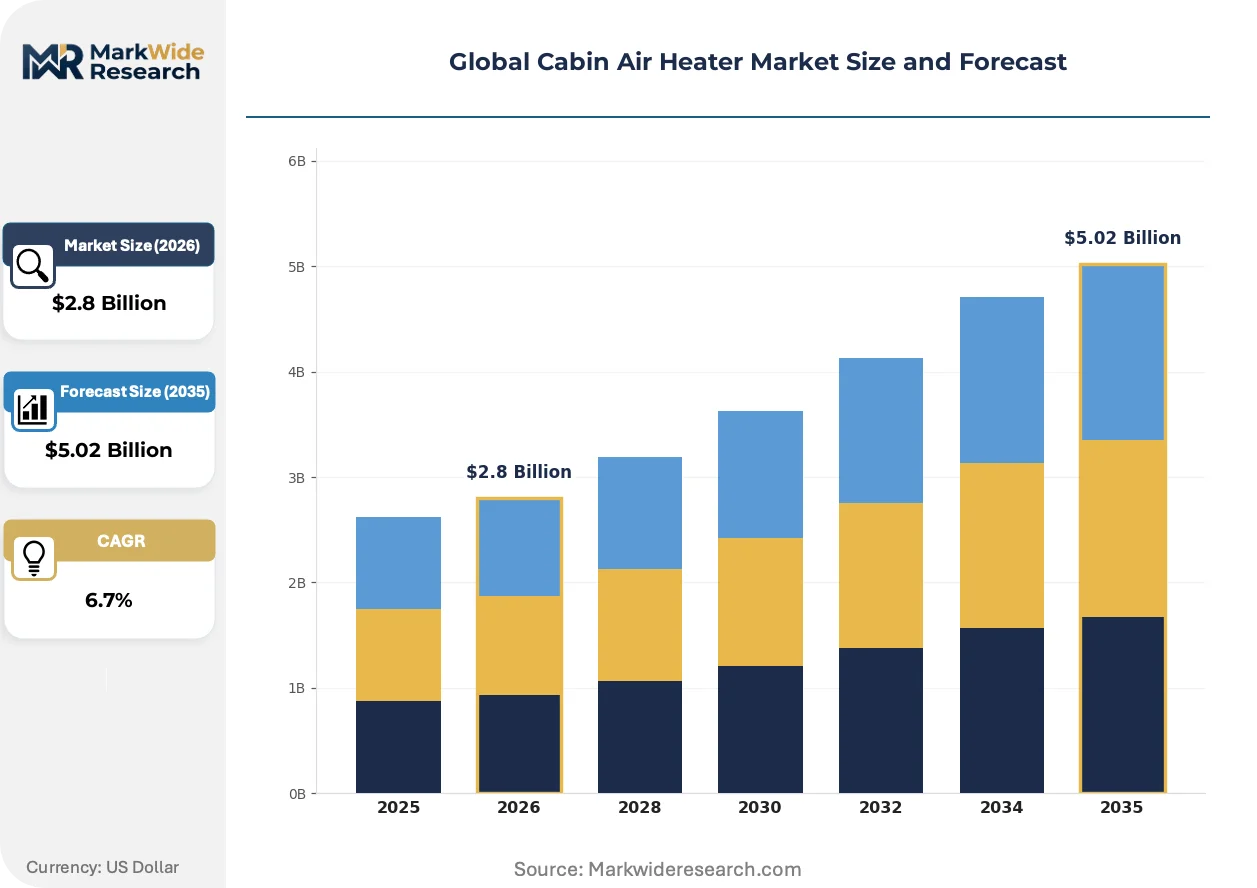
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heaters, Gas Heaters, Hydronic Heaters, Heat Exchangers End User: Passenger Vehicles, Commercial Vehicles, Aviation, Rail Transport Installation Type: OEM, Aftermarket, Retrofit Kits, Custom Installations Control Technology: Manual Control, Automatic Control, Digital Thermostats, Remote Control |
| Companies Covered | Webasto, Eberspaecher Climate Control Systems, Krueger Ltd., BorgWarner Inc., Eberspaecher group, Yachting Partners Malta LTD, Zhengzhou Yusenn Auto Technology Co., Ltd., Planar Marine & Truck Air Heaters Ltd., Webasto Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cabin Air Heater Market Emerging Trajectories
Heater system architecture is converging with battery thermal management, compressing discrete components into unified climate modules that serve both occupant comfort and powertrain protection functions.
Thin-film PTC heating elements are miniaturizing from bulk ceramic discs toward deposited metal-oxide layers on flexible polymer substrates. Electric vehicle battery pack designers are adopting these conformable heaters to eliminate thermal dead zones between cylindrical cells. This form-factor shift is miniaturizing the physical envelope of cabin heaters from glovebox-sized units to dashboard-integrated films that reduce HVAC duct complexity.
EPA Phase 2 greenhouse gas standards for medium and heavy-duty vehicles are tightening idle-time exemptions for sleeper cab climate control. The regulation is compelling long-haul truck manufacturers to specify battery-electric auxiliary power units with integrated cabin heating rather than engine-idle or diesel-fired alternatives. Fleets operating cross-border routes between the United States and Canada face the most acute compliance pressure due to divergent provincial and state enforcement timelines.
Commercial vehicle fleet managers are consolidating heater procurement under total-cost-of-ownership frameworks that weight energy efficiency, warranty duration, and technician training burden against upfront hardware price. This analytical purchasing behavior is displacing the traditional aftermarket parts-counter relationship where independent operators selected heaters based on immediate availability and brand familiarity. The shift is most pronounced among refrigerated transport fleets in Germany and the Netherlands where fuel costs dominate operating economics.
Global Cabin Air Heater Market Segmentation
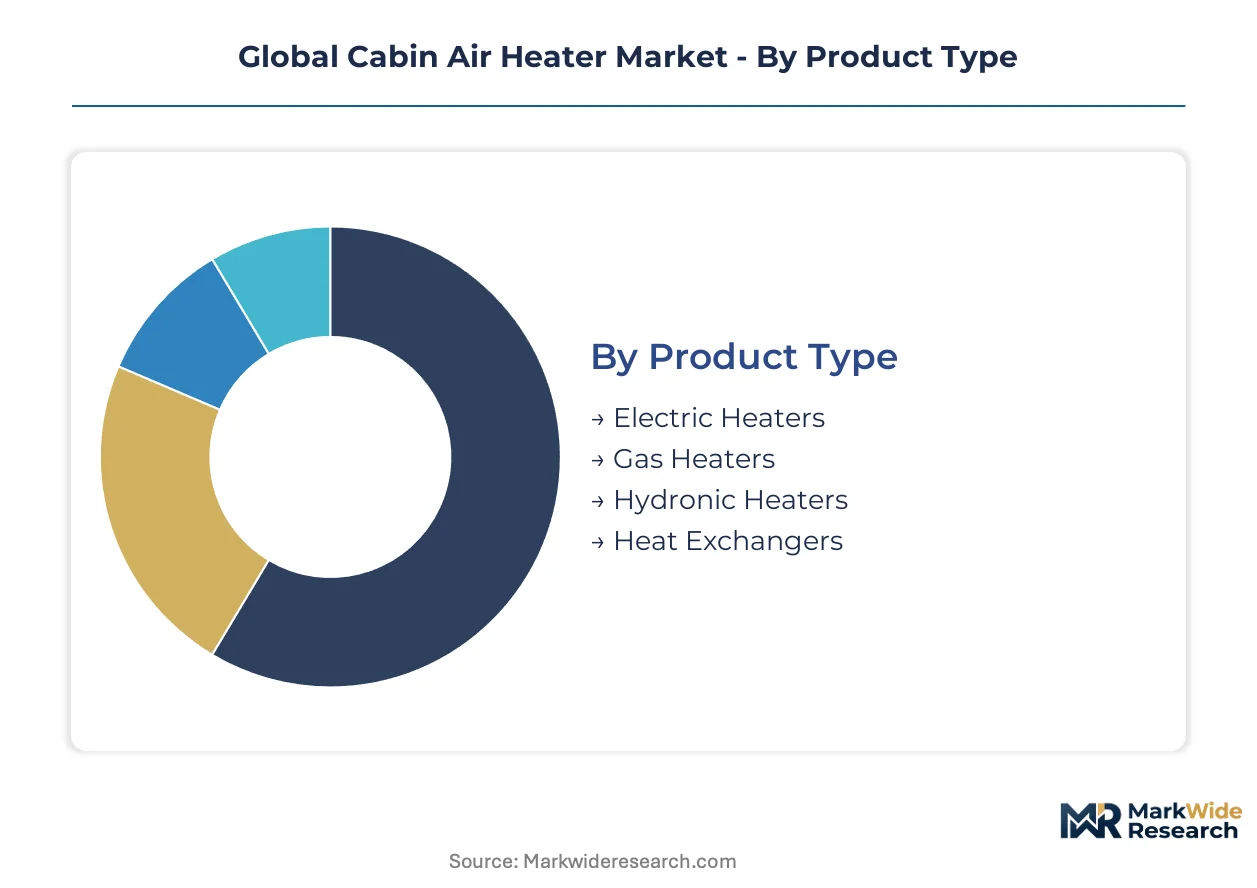
Cabin air heater market segmentation reflects divergent thermal management requirements across electrification pathways and regulatory compliance regimes. Product architecture choices carry direct implications for vehicle platform integration costs and certification burden under evolving emissions frameworks.
Product Type:
EU F-Gas Regulation and EPA Phase 2 standards differentiate compliance pathways across combustion and electric architectures, reshaping supplier R&D allocation and manufacturing footprints.
- Electric Heaters:PTC ceramic and thin-film resistance elements operate across 12V-800V architectures, enabling direct integration with battery electric vehicle platforms. Demand concentrates in Germany and China where OEMs face binding zero-emission vehicle mandates and cold-climate range degradation concerns. Silicon carbide inverter adoption is reducing thermal response latency, improving winter range retention for Scandinavian fleet operators.
- Gas Heaters:Liquid propane and natural gas combustion units serve off-grid applications and remote commercial operations lacking electrical infrastructure. Demand concentrates in Canadian resource extraction fleets and United States recreational vehicle segments where grid independence outweighs emissions compliance costs. EPA Clean Air Act mobile source provisions are tightening particulate emissions thresholds, forcing burner redesigns.
- Hydronic Heaters:Engine coolant circulation systems retain cost advantages in medium-duty commercial segments.
- Heat Exchangers:Passive thermal transfer devices recover waste heat from powertrain and battery systems.
Established volume favors gas heaters; emerging adoption favors electric heaters.
End User:
Application-specific thermal loads and duty cycles drive divergent heater specifications across mobility platforms.
- Passenger Vehicles:OEM-integrated cabin comfort systems prioritize compact envelope and rapid defrost performance. Battery electric architectures in Germany and China are eliminating engine waste heat, mandating auxiliary electric heating for occupant comfort and windshield clearing. Heat pump integration with battery thermal management is consolidating discrete components into unified climate modules.
- Commercial Vehicles:Sleeper cab and cargo compartment heating face stringent idling restrictions under EPA Phase 2 and provincial Canadian regulations. Demand concentrates in United States long-haul fleets and German refrigerated transport operators where fuel costs dominate total cost of ownership calculations. Battery-electric auxiliary power units are displacing engine-idle and diesel-fired alternatives.
- Aviation:Auxiliary ground power units and pre-flight cabin conditioning require FAA-certified combustion and electric systems.
- Rail Transport:Passenger coach heating operates across electrified and diesel locomotive configurations with varying auxiliary power availability.
Commercial vehicle procurement is climbing the fastest; passenger vehicle integration carries the steepest specification burden.
Installation Type:
Channel economics separate embedded control software opportunities from concentrated margin aftermarket retrofit demand.
- OEM:Factory-integrated systems embed heater control logic within vehicle electronic architectures, capturing warranty and software update revenue streams. German and United States automotive OEMs specify ISO 26262 ASIL-D certified control units, elevating engineering barriers for non-captive suppliers. Long-term supply agreements lock in volume commitments across platform lifecycles.
- Aftermarket:Distributor and service center channels address aging fleet replacement demand and geographic expansion of cold-chain logistics. India BS-VI emission compliance is creating first-time auxiliary heater demand in medium-duty trucks previously unequipped with thermal comfort systems. Margin concentration reflects technician training requirements and parts availability premiums.
- Retrofit Kits:Modular packages enable fleet electrification conversions without platform redesign.
- Custom Installations:Specialty vehicle and marine applications require application-specific thermal engineering.
OEM integration captures structural value; aftermarket retrofit kits gain share in emerging commercial vehicle markets.
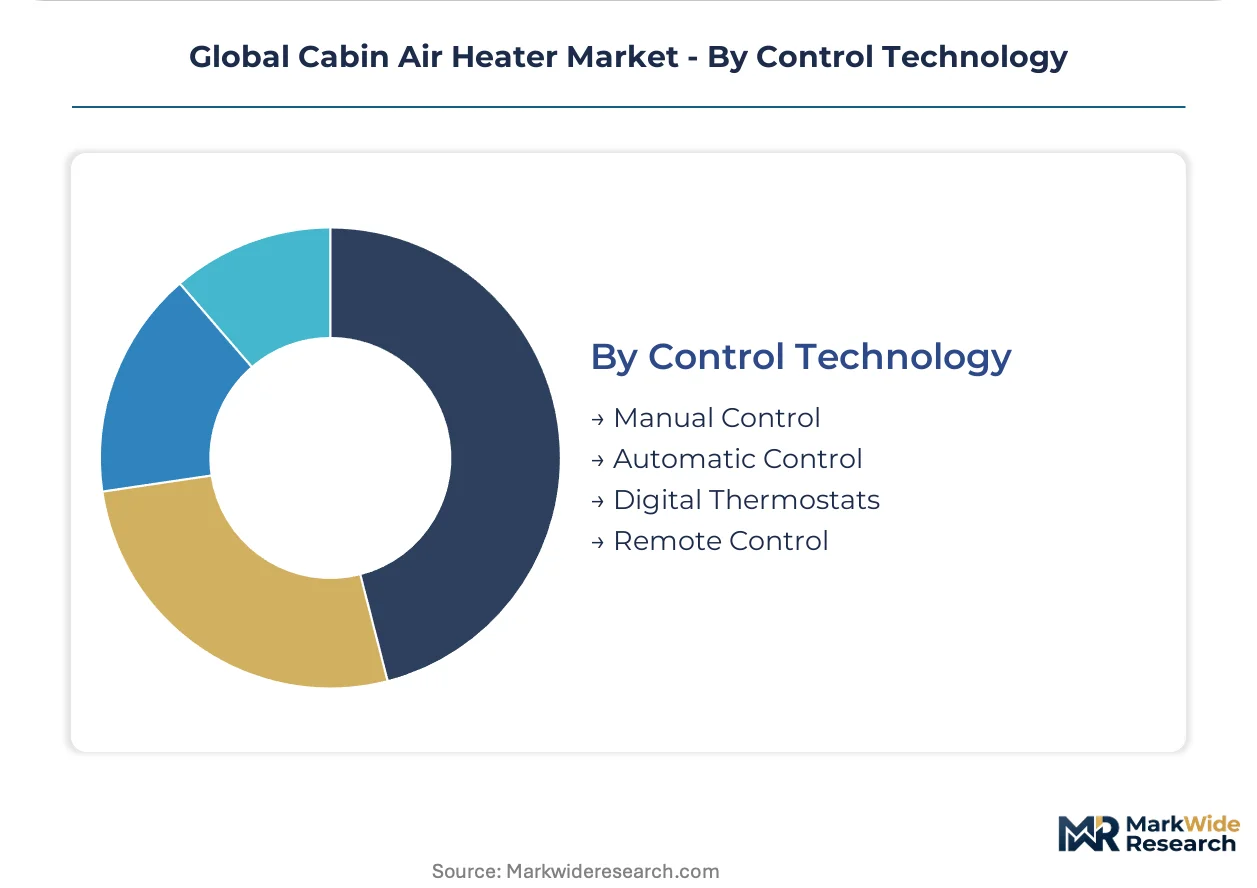
Control Technology:
Functional safety certification and wireless connectivity standards differentiate control system value capture across price tiers.
- Automatic Control:Sensor-driven temperature modulation optimizes energy consumption across varying ambient conditions. German OEM programs specify predictive algorithms that precondition cabin temperature during charging cycles, reducing traction battery draw. FCC electromagnetic emissions standards constrain wireless module certification pathways, elevating compliance costs for control module suppliers.
- Digital Thermostats:Precision temperature setpoint management enables zone-specific cabin comfort configuration. United States premium passenger vehicle segments specify touchscreen-integrated climate interfaces that consolidate heater control within unified infotainment architectures. Semiconductor supply constraints for specialized microcontrollers have extended lead times for thermostat module procurement.
- Manual Control:Basic switch and dial interfaces serve cost-sensitive commercial vehicle segments.
- Remote Control:Smartphone and key fob activation enables pre-conditioning for fleet operator productivity.
Automatic control dominates premium platform specification; digital thermostats are expanding most quickly across mid-market electric vehicle programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stringent idling restrictions and zero-emission vehicle mandates across multiple jurisdictions are redrawing geographic demand patterns for cabin air heater technologies.
United States
Commercial fleet operators face mounting pressure from EPA Phase 2 greenhouse gas standards and state-level anti-idling laws. The California Air Resources Board's Advanced Clean Trucks regulation mandates zero-emission medium and heavy-duty vehicle adoption from 2024. Detroit-based thermal management suppliers are scaling battery-electric auxiliary power unit production to serve cross-border long-haul routes.
Germany
Automotive OEMs confront binding EU F-Gas Regulation compliance deadlines that accelerate heat pump system integration. The KBA enforces stringent certification requirements for high-voltage cabin heating modules. Stuttgart and Munich engineering clusters concentrate development of unified battery-cabin thermal management architectures for premium electric vehicle platforms.
China
Domestic battery electric vehicle manufacturers drive demand for 400V-800V PTC heating systems under MIIT dual carbon goals. The NMPA regulates electromagnetic compatibility for vehicle-integrated climate modules. Shanghai and Shenzhen electronics corridors host specialized semiconductor-grade ceramic suppliers for thin-film heating element production.
Canada
Fleet operators in Alberta and Saskatchewan experience acute range degradation during extreme cold conditions, sustaining demand for hybrid thermal solutions. Environment and Climate Change Canada enforces provincial idling restrictions that vary across Ontario, Quebec, and western provinces. Calgary-based energy extraction fleets maintain specialized procurement for off-grid liquid propane heating systems.
India
BS-VI emission compliance and expanding cold-chain logistics create first-time auxiliary heater demand in medium-duty commercial vehicles. The Central Pollution Control Board enforces stringent particulate standards that elevate thermal management system costs. Pune and Chennai automotive manufacturing corridors integrate cabin heating into export-oriented commercial vehicle platforms.
Global Cabin Air Heater Market Vendor Landscape
Listed leaders compete with private specialists across certification barriers and manufacturing scale. The supplier base organizes around three functional tiers: integrated thermal management conglomerates with captive electronics production, combustion-focused specialists with deep backward integration into burner engineering, and regional assemblers serving aftermarket retrofit demand. Strategic moves center on ISO 26262 functional safety certification acquisition and high-voltage platform competency development.
Within the integrated systems tier, Webasto and BorgWarner Inc. exemplify divergent pathways—Webasto through European passenger vehicle program penetration, BorgWarner through powertrain-to-cabin portfolio extension. Eberspaecher Climate Control Systems anchors the combustion-specialist archetype with German GmbH structure and heritage burner architecture expertise. Zhengzhou Yusenn Auto Technology Co., Ltd. represents the China-based regional assembler segment serving commercial vehicle aftermarket channels.
| Leading Market Players |
|---|
| Webasto |
| Eberspaecher Climate Control Systems |
| Krueger Ltd. |
| BorgWarner Inc. |
| Eberspaecher group |
| Yachting Partners Malta LTD |
| Zhengzhou Yusenn Auto Technology Co., Ltd. |
| Planar Marine & Truck Air Heaters Ltd. |
| Webasto Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for semiconductor-grade ceramic PTC elements from Japanese suppliers concentrate pricing power among tier-1 automotive OEMs with locked volume commitments, while aftermarket distributors absorb margin compression from spot-market nickel and copper volatility. This inventory-to-pricing linkage forces European heater assemblers into strategic stockpile positions against single-source dependencies.
Pricing Analysis
Certification level creates the primary spread across the cabin air heater market, with ISO 26262 ASIL-D certified control modules commanding premium positioning over CE-marked aftermarket alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects functional safety investment, silicon carbide inverter integration, and warranty duration bundling. Cost compression in mid-tier electric heater assemblies is intensifying because fixed-price OEM contracts expose manufacturers to commodity swings in copper coil and nickel thermal interface materials. Fleet procurement teams at refrigerated transport operators in Germany demonstrate highest price sensitivity, while premium passenger vehicle OEMs in Stuttgart and Munich prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy as heater manufacturers buffer against eighteen-week lead times for specialized ceramics and silicon carbide power electronics. Supply concentrates in Japan, South Korea, and China for semiconductor-grade PTC elements and high-voltage inverter components, while burner assembly and heat exchanger fabrication centers on Germany and the United States. Raw material dependencies rest on copper for resistance coils, nickel for battery thermal interfaces, and aluminum for heat exchanger housings. Single-source vulnerability from Japanese and South Korean ceramic suppliers creates concentration risk for European heater assemblers lacking backward integration. Distribution runs through captive OEM supply agreements for factory-integrated systems, with aftermarket channels serving aging fleet replacement demand through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cabin air heater market represents a high-growth disruption as 400V-800V platform electrification eliminates engine waste heat and mandates auxiliary thermal management investment under binding zero-emission vehicle mandates.
For Market Incumbents: Compound ISO 26262 functional safety certification leadership into long-term OEM supply agreements before emerging Asian electronics suppliers close the ASIL-D competency gap. Deepen backward integration into burner and heat exchanger production to defend margin position against commodity volatility in copper and nickel inputs. Prioritize captive silicon carbide inverter sourcing through power electronics partnerships to secure thermal response latency advantages. For New Entrants and Emerging Players: CE marking fast-track for 12V-48V auxiliary heaters opens immediate aftermarket penetration in India's BS-VI commercial vehicle retrofit segment, where cold-chain logistics expansion creates first-time thermal comfort demand. White-space concentration sits in medium-duty truck auxiliary heating previously unequipped with cabin comfort systems. Target fleet electrification conversion programs in California and Germany with modular retrofit kits that bypass embedded OEM control architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across high-voltage PTC and heat pump module production as 400V-800V platform validation requires specialized test equipment and cleanroom assembly environments. Long-term viability over the next decade favors integrated thermal management conglomerates with captive electronics manufacturing and unified battery-cabin climate module portfolios. Acquisition target archetype: mid-cap combustion specialists with heritage burner engineering seeking electric competency through distressed restructuring. The signal to watch is silicon carbide inverter adoption rates in Scandinavian fleet operator procurement specifications, indicating tipping point timing for pure-electric thermal system displacement.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 ASIL-D Certification Investment | Functional safety leadership secures embedded OEM supply agreements against emerging competitors. |
| Silicon Carbide Inverter Integration | Power electronics advancement reduces thermal response latency for battery electric vehicle range retention. |
| Backward Integration into Ceramics | Upstream control over PTC element supply mitigates single-source dependency from Japanese suppliers. |
| Unified Climate Module Development | Battery-cabin thermal management consolidation eliminates discrete component complexity for OEM platform engineers. |
| Aftermarket Retrofit Kit Expansion | Modular auxiliary heater packages capture fleet electrification conversion demand in California and Germany. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier 1 thermal management procurement leads, aftermarket distributor operations heads, and commercial fleet maintenance directors anchored the qualitative base for this study. Primary interview insights combined with secondary validation from EPA mobile source emission filings, EU F-Gas Regulation implementation databases, vehicle production statistics, and SEC disclosures from listed thermal management suppliers. Bottom-up unit economics triangulated against top-down market sizing across electric, combustion, and heat pump architectures.
Sensitivity analysis framed the quantitative modeling across product type, vehicle propulsion architecture, installation channel, and regional regulatory cluster dimensions. Volume and value outputs reflect interpolation between historical shipment data and projected platform electrification timelines throughout the forecast period. CAGRs derived from segment-specific adoption curves weighted by zero-emission vehicle mandate compliance deadlines and commercial fleet replacement cycles. Industry-specific forecast inputs incorporated silicon carbide inverter penetration rates and copper price volatility bands.
The analysis sits within stated boundaries; outcomes outside sustained battery electric vehicle adoption trajectories or abrupt regulatory relaxation would require recalibration. Forecasts reflect documented assumptions regarding OEM platform lifecycle commitments, aftermarket parts availability, and technician training network capacity. Revision becomes warranted when extreme cold range degradation thresholds cross fleet operator tolerance limits or when ceramic PTC supplier concentration exceeds critical dependency thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market