
 Automotive Active Grille Shutter (AGS) Market | 2026-2036
Automotive Active Grille Shutter (AGS) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Grille Shutter (AGS) Market Analysis
OEM-grade aerodynamic specifications is redrawing competitive requirements across the Automotive Active Grille Shutter landscape. Robert Bosch GmbH leverages its mechatronics heritage to supply integrated shutter-actuator modules to European and Asian vehicle programs. Magna International anchors North American supply through manufacturing scale and proximity to Detroit-based OEM assembly operations. Valeo differentiates via thermal management integration, combining AGS with battery cooling architectures for electrified platforms.
Automotive Active Grille Shutters are motor-driven louver assemblies, typically constructed from glass-reinforced polyamide or aluminum stampings, that modulate frontal airflow to balance engine cooling demands with drag coefficient reduction. The assembly incorporates position sensors, control modules, and temperature feedback loops to automate blade angle adjustment between zero and ninety degrees based on real-time thermal load and vehicle speed. Adaptive Shutter systems command premium positioning as they enable variable geometry response across highway and urban drive cycles, while Fixed Shutter variants retain cost-sensitive volume applications in economy vehicle segments. Composite Material formulations are gaining share as OEMs target mass reduction alongside corrosion resistance in electrified architectures where thermal envelope requirements differ from internal combustion platforms.
The EPA enforces fleet-wide fuel economy benchmarks that directly incentivize AGS deployment as a cost-effective drag reduction pathway, while the EU Green Deal and associated CO2 fleet mandates through EMA-coordinated frameworks compel European manufacturers to adopt active aerodynamic elements. China's MIIT administers parallel new energy vehicle efficiency standards that incorporate active thermal management as a scored criterion within dual carbon policy implementation. Stakeholders must monitor divergence between regional testing protocols, as the EPA's FTP-75 cycle, Europe's WLTP, and China's CLTC produce incompatible aerodynamic load profiles that complicate platform-standardized shutter calibration strategies.
Market Dynamics
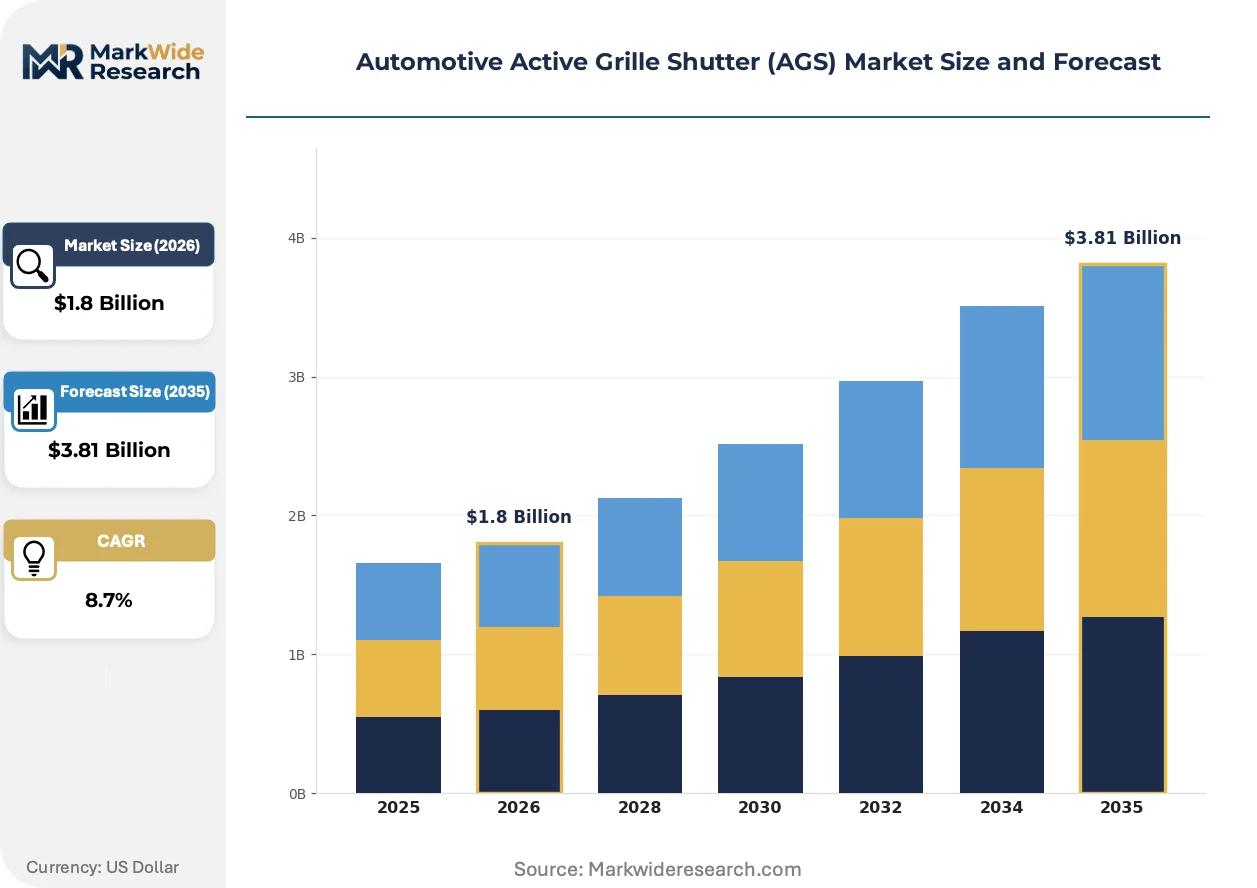
Fleet efficiency mandates across the United States, Germany, and China are forcing passenger vehicle OEMs to embed active aerodynamic systems as standard equipment rather than optional trim packages. The regulatory pressure is compressing supplier qualification timelines and reshaping procurement criteria toward thermal-electromechanical integration capability.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:United States OEMs deploy AGS to close gap between test-cycle performance and real-world drag reduction targets. The regulation treats active aerodynamics as a scored compliance pathway.
- Glass-reinforced polyamide formulations:Composite material advances enable 30-40% mass reduction versus aluminum stampings while maintaining blade rigidity across thermal cycling. Electrified platforms prioritize this weight saving.
- China MIIT dual carbon policy:New energy vehicle efficiency scoring incorporates active thermal management as a rated criterion. Domestic OEMs accelerate AGS integration to capture policy incentives.
Market Restraints
- Actuator motor supply concentration:Precision stepper motor production clusters in East Asian manufacturing corridors. Single-source exposure creates vulnerability to logistics disruption or tariff escalation.
- Polyamide resin price volatility:Glass-reinforced composite feedstock tracks petrochemical and energy input costs. Margin compression cycles through the supply chain during feedstock spikes.
- Legacy thermal calibration protocols:Internal combustion engine cooling maps do not translate directly to electrified thermal envelopes. Platform redesign delays AGS standardization.
Strategic Opportunities
- Commercial vehicle underpenetration:Heavy-duty truck fleets in the United States lack AGS adoption despite highway-dominated duty cycles. Aerodynamic retrofit programs represent untapped volume.
- Battery electric vehicle thermal convergence:AGS integration with heat pump architectures and battery conditioning loops creates system-level value propositions. Valeo and Bosch already pilot unified thermal-aerodynamic modules.
- EU Green Deal CO2 fleet mandates:The 2035 internal combustion phase-out deadline accelerates electrified platform development. Active grille shutters score within the EMA-coordinated compliance framework.
Industry Challenges
- Multi-protocol calibration complexity:EPA FTP-75, WLTP, and CLTC test cycles generate incompatible aerodynamic load profiles. Engineering teams must develop region-specific shutter maps rather than global platform standards.
- Electromechanical reliability certification:Automotive OEMs demand 15-year/240,000-kilometer actuator durability validation. Testing timelines extend supplier qualification windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Grille Shutter (AGS) Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Shutter, Adaptive Shutter, Fixed Shutter, Dynamic Shutter Functionality: Manual Control, Automatic Control, Temperature Regulation, Aerodynamic Efficiency Material: Plastic, Aluminum, Composite, Steel End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Robert Bosch GmbH, Faurecia, Magna International, MAHLE GmbH, Plastic Omnium, Valeo, DENSO Corporation, Röchling Automotive, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Grille Shutter (AGS) Market Emerging Trajectories
Active grille shutter technology is converging with thermal management architectures and sensor fusion systems. The market is shifting from standalone aerodynamic components toward integrated vehicle energy management nodes.
Smart blade actuation systems incorporating position feedback loops and predictive thermal algorithms are miniaturizing control module footprints. European premium OEMs specify these compact integrated units for electrified platforms where packaging space is constrained. The technology is miniaturizing hardware while expanding software-defined functionality, compressing the traditional separation between aerodynamic and thermal engineering disciplines.
China's MIIT administers parallel efficiency standards that incorporate active thermal management as a scored criterion within dual carbon policy implementation. Domestic OEMs respond by mandating AGS across mid-tier and above vehicle lines. The policy is accelerating supplier localization requirements and compressing the window for foreign component qualification.
Fleet procurement departments now specify total cost of ownership metrics rather than component purchase price alone. North American commercial vehicle operators calculate fuel savings over 10-year ownership horizons. The behavioral shift is elevating suppliers who can document validated drag reduction coefficients and durability guarantees.
Automotive Active Grille Shutter (AGS) Market Segmentation
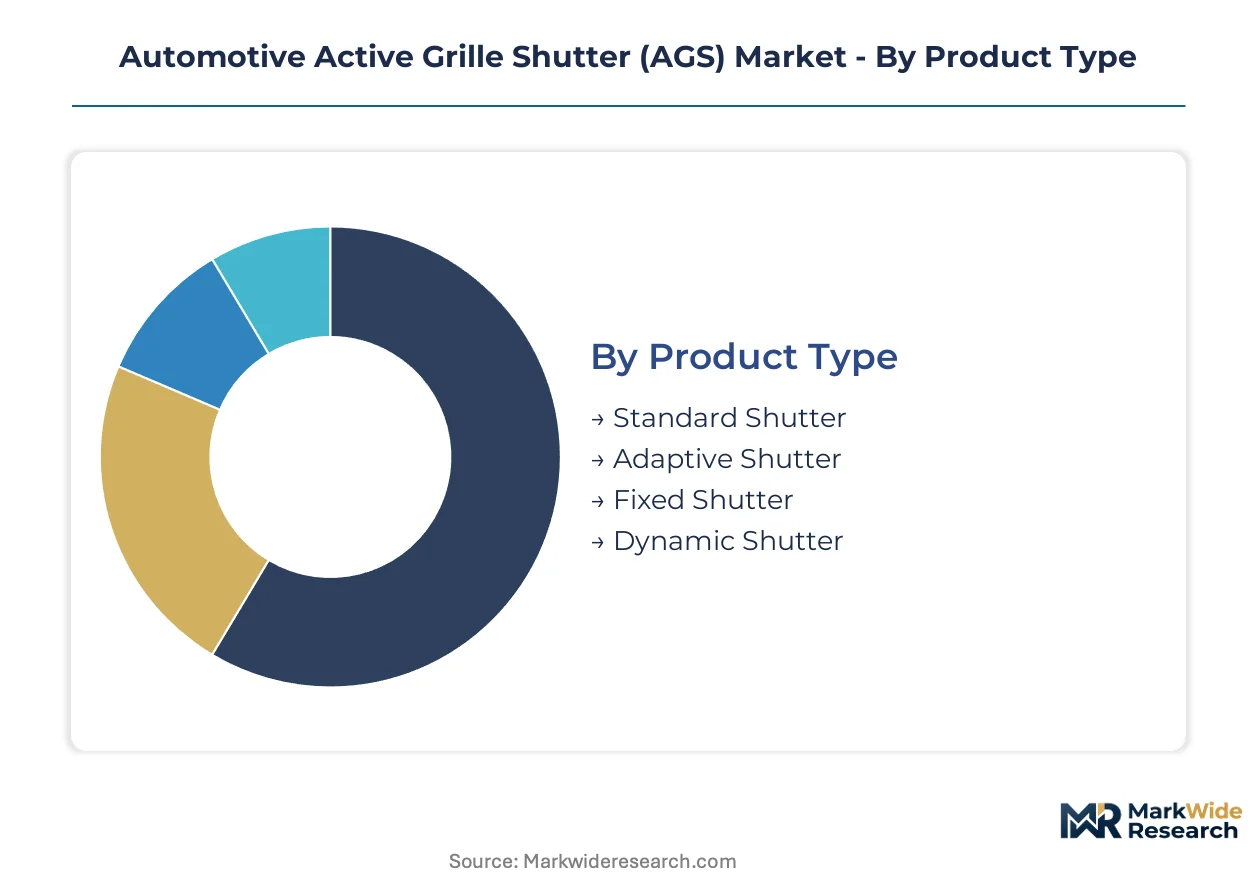
Active grille shutter procurement channels diverge sharply by product complexity and thermal integration requirements. OEMs route high-specification adaptive systems through Tier-1 suppliers with electromechanical integration capabilities, while aftermarket channels handle simpler fixed-shutter replacements.
Product Type:
Channel mix splits between integrated module supply to vehicle programs and component-level distribution for repair networks. Adaptive and dynamic variants flow through controlled OEM-Tier-1 relationships, while standard and fixed shutters support broader aftermarket access.
- Adaptive Shutter:Motor-driven louver assemblies with position feedback and real-time thermal algorithms modulate blade angles across highway and urban cycles. Demand concentrates in German premium OEM platforms where EPA and EU Green Deal fleet mandates drive aerodynamic scoring. These systems require 15-year actuator durability validation, compressing supplier qualification timelines.
- Dynamic Shutter:Predictive control modules integrate with vehicle CAN bus architectures to anticipate thermal loads before they materialize. Expansion concentrates in China's MIIT-scored new energy vehicle programs where active thermal management earns policy incentives. Domestic OEMs mandate these across mid-tier and above model lines.
- Standard Shutter:Basic electromechanical assemblies with limited position sensing serve cost-optimized vehicle segments.
- Fixed Shutter:Passive louver geometries without actuation retain economy vehicle applications where purchase price dominates procurement criteria.
Adaptive Shutter dominates installed base. Dynamic Shutter is where expansion concentrates.
Functionality:
Application requirements reshape how control architectures reach vehicle platforms. Temperature-critical functions integrate deeper into thermal management hierarchies, while aerodynamic efficiency modules operate as standalone drag reduction pathways.
- Temperature Regulation:Closed-loop sensor networks feed engine and battery cooling demands through shutter position commands. OEM specifications in Germany and China prioritize this integration for electrified platforms where thermal envelopes differ from internal combustion architectures. Glass-reinforced polyamide formulations enable mass reduction alongside corrosion resistance.
- Automatic Control:Speed-responsive algorithms adjust blade angles without driver intervention, balancing cooling airflow with coefficient of drag targets. Demand concentrates in United States passenger vehicle programs where EPA CAFE standards treat active aerodynamics as scored compliance pathways. Fleet efficiency mandates compress adoption timelines from optional trim to standard equipment.
- Manual Control:Driver-actuated override systems for specific thermal or aerodynamic preferences.
- Aerodynamic Efficiency:Drag-focused calibration prioritizes highway fuel economy over cooling capacity.
Temperature Regulation commands premium positioning in new platform development. Automatic Control is climbing the fastest in retrofit and mid-cycle enhancement programs.
Material:
Volume scale and thermal cycling requirements determine raw material procurement patterns. Electrified platforms shift specifications toward corrosion-resistant composites, while legacy programs retain metal stampings for established supply relationships.
- Composite:Glass-reinforced polyamide formulations deliver 30-40% mass reduction versus aluminum alternatives while maintaining blade rigidity across thermal cycles. OEMs in Germany and China specify these for battery electric architectures where weight saving compounds range extension. Polyamide resin price volatility creates margin compression risk during petrochemical spikes.
- Aluminum:Stamped and extruded profiles with proven corrosion resistance serve hybrid platforms bridging thermal management paradigms. Demand concentrates in North American OEM assembly operations where Magna International anchors supply through manufacturing scale and Detroit proximity.
- Plastic:Unreinforced polymer formulations for cost-sensitive fixed-shutter applications.
- Steel:Legacy metal stampings retaining commercial vehicle and heavy-duty segments.
Aluminum dominates current installed base. Composite is gaining share fastest as electrified platform volumes scale.
End User:
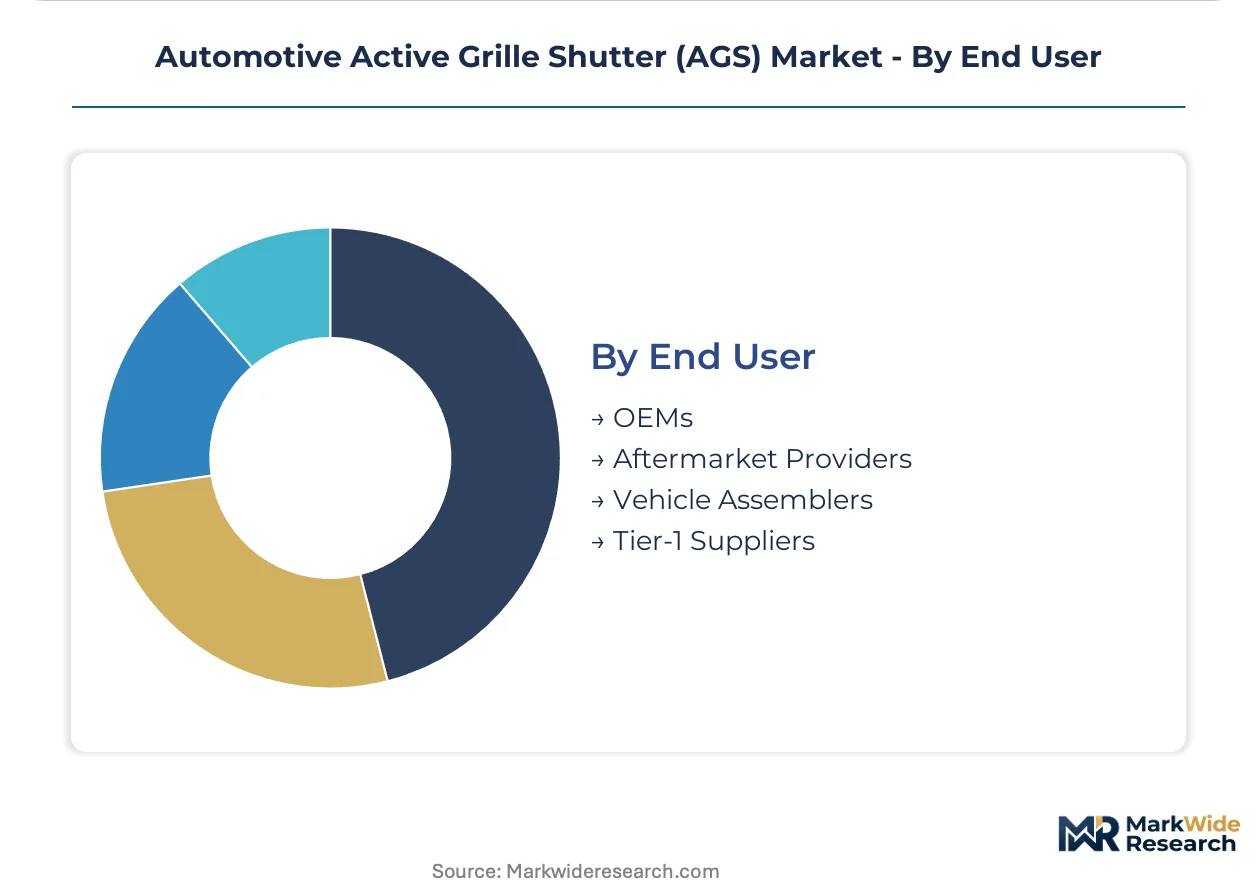
Customer type determines specification authority and technical integration depth. OEMs and Tier-1 suppliers co-develop module architectures, while aftermarket providers operate within constrained replacement protocols.
- OEMs:Vehicle manufacturers specify integrated thermal-aerodynamic modules with unified control logic and durability guarantees. Procurement in Germany, the United States, and China demands 15-year/240,000-kilometer validation documentation. Bosch and Valeo pilot converged heat pump-shutter architectures for these programs.
- Tier-1 Suppliers:System integrators manage electromechanical assembly, actuator sourcing, and OEM platform qualification. These intermediaries concentrate precision stepper motor procurement from East Asian manufacturing corridors, creating single-source exposure to logistics disruption.
- Vehicle Assemblers:Contract manufacturing operations executing OEM-specified assembly sequences.
- Aftermarket Providers:Distributors and service networks handling replacement shutter modules outside original platform development cycles.
OEMs dominate specification authority. Tier-1 Suppliers is where supply chain consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of integrated shutter-actuator modules concentrate in German and Japanese manufacturing corridors, while import dependency for precision stepper motors shapes procurement strategies in North American assembly operations. The United States, Germany, China, Japan, and South Korea collectively anchor production capacity and regulatory momentum for active aerodynamic systems.
United States
Detroit-based OEM assembly operations drive specification authority for integrated thermal-aerodynamic modules. EPA Corporate Average Fuel Economy standards treat active grille shutters as scored compliance pathways for fleet efficiency mandates. Magna International anchors North American supply through manufacturing scale and proximity to Michigan vehicle plants.
Germany
Premium automakers embed adaptive shutter systems across multiple model lines to meet EU Green Deal CO2 fleet mandates. EMA-coordinated frameworks compel manufacturers to adopt active aerodynamic elements through 2035 internal combustion phase-out deadlines. Stuttgart and Munich engineering clusters concentrate electromechanical integration development for electrified platforms.
China
Domestic OEMs mandate active grille shutters across mid-tier and above vehicle lines to capture MIIT dual carbon policy incentives. New energy vehicle efficiency scoring incorporates active thermal management as a rated criterion. Yangtze River Delta manufacturing corridors accelerate supplier localization requirements and compress foreign component qualification windows.
Japan
Precision stepper motor production clusters anchor East Asian supply chains for actuator-dependent adaptive systems. METI-administered efficiency standards parallel European and North American regulatory frameworks. Toyota City and Nagoya industrial zones concentrate electromechanical module assembly for hybrid and battery electric architectures.
South Korea
Hyundai-Kia vehicle programs integrate active aerodynamic systems to meet corporate efficiency targets across export markets. Domestic suppliers scale composite material formulations for mass reduction in electrified platforms. Seoul Capital Area engineering centers co-develop shutter-heat pump convergence architectures with European Tier-1 partners.
Automotive Active Grille Shutter (AGS) Market Vendor Landscape
Concentration sits with diversified automotive suppliers possessing electromechanical integration heritage and thermal management expertise. The vendor base stratifies across three tiers: global diversified suppliers with mechatronics capabilities, specialized aerodynamic component manufacturers, and regional actuator producers. Strategic moves center on portfolio diversification into unified thermal-aerodynamic modules and backward integration into precision motor production to reduce East Asian supply exposure.
Among European-based diversified suppliers, Robert Bosch GmbH, Valeo, and MAHLE GmbH exemplify the integration-focused archetype. Bosch represents the mechatronics heritage segment supplying shutter-actuator modules across multiple geographies. Valeo occupies a position within thermal convergence specialists combining active grille systems with battery cooling architectures. MAHLE GmbH anchors the traditional automotive supplier tier extending thermal management portfolios into aerodynamic optimization.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Faurecia |
| Magna International |
| MAHLE GmbH |
| Plastic Omnium |
| Valeo |
| DENSO Corporation |
| Röchling Automotive |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Eighteen-month actuator qualification timelines compress procurement windows and concentrate pricing power with Tier-1 integrators who control East Asian motor sourcing. This lead-time rigidity forces OEMs into long-term offtake agreements that lock in component costs before platform volume certainty emerges.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing that stratifies across premium adaptive systems, standard electromechanical assemblies, and economy fixed-shutter tiers. Price differentiation hinges on ISO 26262 functional safety certification grade and volume scale commitments above 50,000 units annually. Cost compression in economy tiers intensifies because polyamide resin feedstock tracks volatile petrochemical indices. Fleet procurement departments exhibit highest price sensitivity, while premium German OEMs prioritize thermal integration over unit cost.
Supply Chain Analysis
Port congestion on Shanghai-to-Long Beach lanes elevates inbound logistics costs for precision stepper motors sourced from Yangtze River Delta manufacturing corridors. Supply concentrates in China, Japan, and Germany for actuator modules, glass-reinforced polyamide formulations, and integrated control electronics respectively. Raw material dependencies rest on petrochemical-derived resin, rare-earth magnet alloys, and copper winding stock. Single-source vulnerability in East Asian motor production creates tariff exposure risk. Distribution runs through controlled OEM-Tier-1 direct channels with limited aftermarket penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as electrified platform thermal requirements diverge from legacy combustion architectures, creating specialist niches for heat pump-integrated shutter modules.
For Market Incumbents: Compound defensive positioning through backward integration into precision stepper motor production and captive polyamide compounding capacity to neutralize East Asian supply exposure. Secure 15-year durability validation documentation ahead of competitor qualification windows. Prioritize R&D investment in unified thermal-aerodynamic control algorithms that embed shutter logic within battery management systems. For New Entrants and Emerging Players: IATF 16949 certification fast-tracks enable qualification for Chinese domestic OEM mid-tier vehicle programs where MIIT policy incentives accelerate AGS mandates. Target commercial vehicle retrofit segments in the United States where highway duty cycles maximize aerodynamic return-on-investment yet supplier penetration remains minimal. Pursue direct fleet operator relationships bypassing traditional Tier-1 gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because fleet efficiency mandates hardwire active aerodynamics into vehicle platform economics regardless of propulsion technology shifts. Acquisition target archetype: specialized thermal-electromechanical integrators with validated electrified platform programs. Watch EPA CAFE standard stringency revisions as inflection signal for North American demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces per-vehicle engineering cost across EPA, WLTP, and CLTC calibration protocols. |
| Backward Integration into Actuator Production | Neutralizes single-source exposure in East Asian precision stepper motor corridors. |
| Battery Supply Agreement | Secures thermal management co-development rights with electrified platform OEMs. |
| Geographic Manufacturing Footprint | Positions assembly capacity near Detroit, Stuttgart, and Shanghai engineering clusters. |
| Software-Defined Vehicle Investment | Enables predictive thermal algorithms that anticipate load before sensor detection. |
Methodological Framework
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributor operations heads, and thermal management R&D leads provided ongoing calibration across the study period. Primary interview findings were cross-validated against vehicle production databases, IHS Markit registration data, EPA compliance filings, and MIIT efficiency scorecards. Bottom-up unit volume estimates triangulated with top-down OEM fleet mandate analysis.
Consistency checks validated volume and value outputs against external production forecasts and regulatory compliance pathway modeling across the projection horizon. Segmentation dimensions included propulsion architecture, vehicle class, shutter functionality tier, material composition, and regional production cluster. CAGRs were derived from fitted growth curves incorporating policy mandate timelines and platform refresh cycles. Industry-specific inputs encompassed thermal envelope specifications for battery electric architectures and durability testing protocols.
Underlying assumptions cover sustained EPA CAFE stringency, EU Green Deal implementation through EMA-coordinated frameworks, and MIIT dual carbon policy continuity, with deviation risk concentrated in trade policy escalation affecting East Asian actuator sourcing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market
Automotive Interior & Exterior
Automotive Sunroof Market