
 North America Automotive Seat Market | 2026-2036
North America Automotive Seat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Seat Market Analytics
A shortage of skilled polyurethane foam technicians and advanced stitching automation specialists is reorganizing supplier hiring patterns across the Great Lakes and Southeastern Mexico. Lear Corporation leverages its vertical integration into foam-in-place manufacturing to sustain cost advantages in high-volume programs. Adient plc anchors its position through R&D intensity focused on modular seat platforms that reduce assembly complexity for Detroit-area OEMs.
Automotive seats are structural-interior assemblies comprising steel or aluminum frames, polyurethane foam cushions, suspension systems, and trim materials engineered to meet occupant safety, ergonomic, and crash-performance specifications; their primary purpose is to position and protect vehicle occupants while supporting H-point and head-restraint geometric requirements during frontal and rear-impact events. The powered and heated technology segments command the strongest margin pools as OEMs bundle thermal comfort into premium trim configurations, while fabric and leather material types split volume leadership across mass-market and luxury nameplates respectively. Bucket seat types dominate light-truck and SUV applications where individual adjustability drives consumer preference.
NHTSA Federal Motor Vehicle Safety Standards govern seat strength, head-restraint geometry, and occupant retention, while EPA Corporate Average Fuel Economy rules push suppliers toward lighter frame designs and recycled-content trim materials; OSHA workplace standards additionally shape foam-chemical handling protocols at U.S. and Mexican assembly plants. Stakeholders must monitor how NHTSA's evolving side-impact test protocols and California's advancing low-carbon material mandates will reshape foam formulation and frame metallurgy decisions.
Market Dynamics
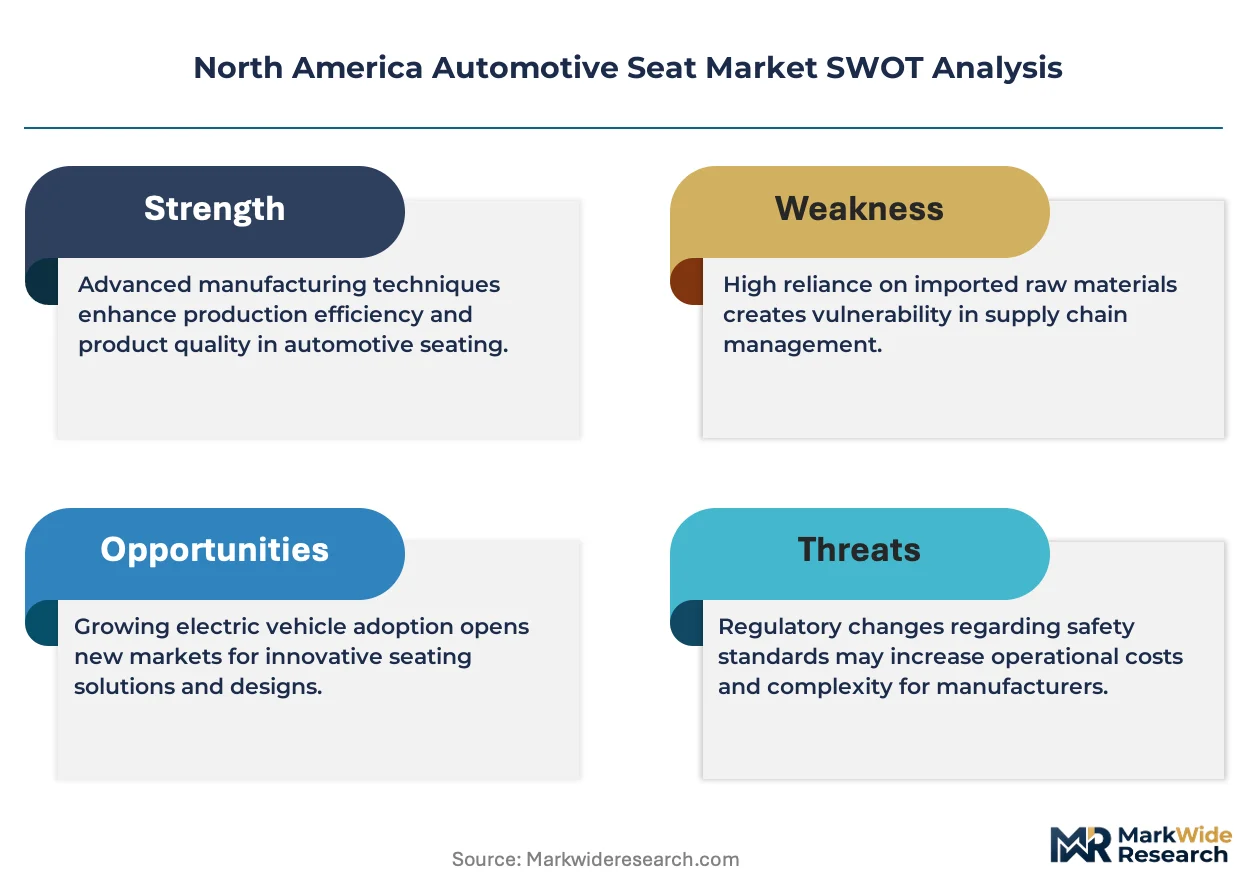
Electric vehicle platform architectures are compressing seat assembly lead times while NHTSA side-impact protocols and EPA fuel economy mandates force simultaneous lightweighting and structural reinforcement investments across U.S., Canadian, and Mexican supply chains.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 202a:Mandated head-restraint geometry improvements are accelerating frame redesign cycles across Detroit-area OEM programs, pulling advanced high-strength steel and aluminum extrusion demand.
- Polyurethane foam-in-place manufacturing:In-situ molding processes are reducing component count and assembly labor hours, enabling tier-one suppliers to capture value previously lost to downstream integrators.
- Mexico's Bajío automotive corridor:Concentrated OEM final assembly expansion around León and Silao is localizing seat module demand within four-hour logistics radii of frame and foam production.
Market Restraints
- Steel and aluminum price volatility:Frame material cost swings compress supplier margins on fixed-price annual contracts, particularly for high-volume light-truck programs with thin engineering-change buffers.
- Polyol and isocyanate supply concentration:Chemical feedstock production clusters along the U.S. Gulf Coast expose foam suppliers to hurricane-related disruption cascades with limited secondary sourcing.
- Technical limitation in multi-material bonding:Dissimilar material interfaces between aluminum frames and steel suspension components create galvanic corrosion risks that extend validation timelines.
Strategic Opportunities
- Canada's low-carbon aluminum mandate:Federal clean fuel regulations and provincial carbon pricing create preferential sourcing incentives for Quebec-smelted primary aluminum in seat frame applications.
- Autonomous vehicle interior reconfiguration:Swiveling and stowable seat architectures for robo-taxi applications demand new suspension kinematics and occupant restraint integration.
- Recycled synthetic fiber certification:California's advancing recycled-content mandates for automotive interiors are creating first-mover advantages for suppliers with verified post-consumer polyester supply chains.
Industry Challenges
- Polyurethane foam technician shortage:Specialized chemical handling and process control expertise is scarce across Great Lakes manufacturing zones, inflating wage premiums and training cycle investments.
- NHTSA side-impact protocol compliance timelines:Evolving FMVSS 214 test procedures demand rapid structural validation, compressing design-to-tooling windows and increasing prototype iteration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Seat Market |
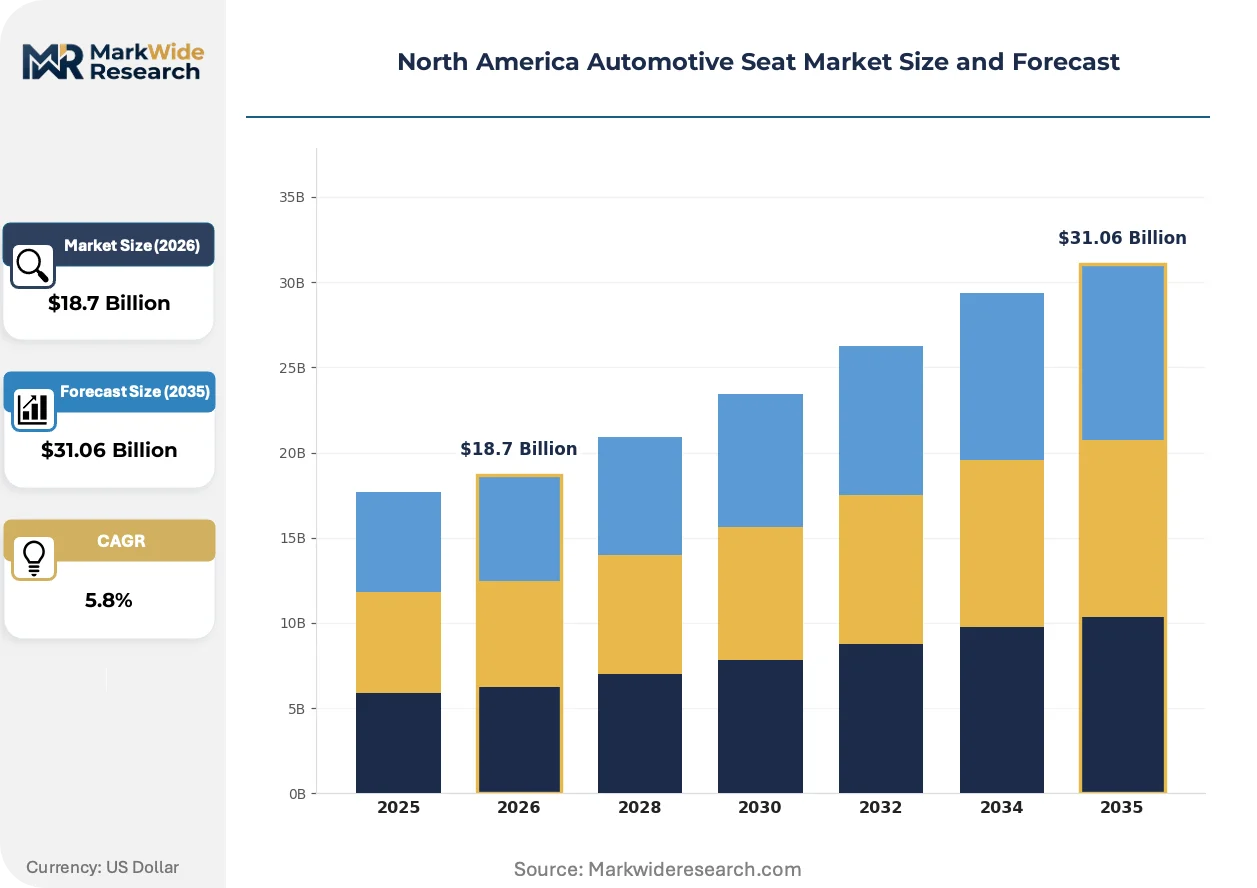
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Fabric, Leather, Vinyl, Alcantara Seat Type: Bucket, Bench, Recliner, Captain End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Manual, Powered, Heated, Cooling |
| Companies Covered | Lear Corporation, Adient plc, Toyota Boshoku Corporation, Faurecia SE (FORVIA), Magna International, Johnson Controls, Tachi-S Co., Ltd., NHK Spring Co., Ltd., RECARO Automotive Seating, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Seat Market Evolving Landscape
Seat architecture is converging toward modular platform designs that decouple structural frames from trim and comfort systems, enabling faster model-cycle refresh rates without full tooling reinvestment.
Bio-based polyurethane foam formulations derived from castor oil and soy polyols are supplanting petroleum-derived alternatives in headrest and cushion applications. Tier-one suppliers serving Ford and General Motors light-truck programs have accelerated qualification timelines from thirty-six to eighteen months. This substitution is compressing petrochemical feedstock exposure while creating new agricultural supply chain dependencies in the U.S. Midwest.
EPA Corporate Average Fuel Economy standards are mandating gram-level weight reductions that cascade into seat frame metallurgy decisions. High-strength steel grades above 980 MPa are displacing mild steel in side-impact-critical members. Canadian and Mexican assembly plants are synchronizing material specifications to maintain cross-border platform commonality.
Fleet procurement departments are unbundling seat module sourcing from complete vehicle contracts, creating direct supplier-OEM engineering relationships previously mediated by vehicle assemblers. This disintermediation concentrates specification authority with Detroit-area technical centers while exposing seat suppliers to volume volatility from individual nameplate cancellation decisions. The pattern is most pronounced in commercial van and last-mile delivery vehicle segments.
North America Automotive Seat Market Segmentation
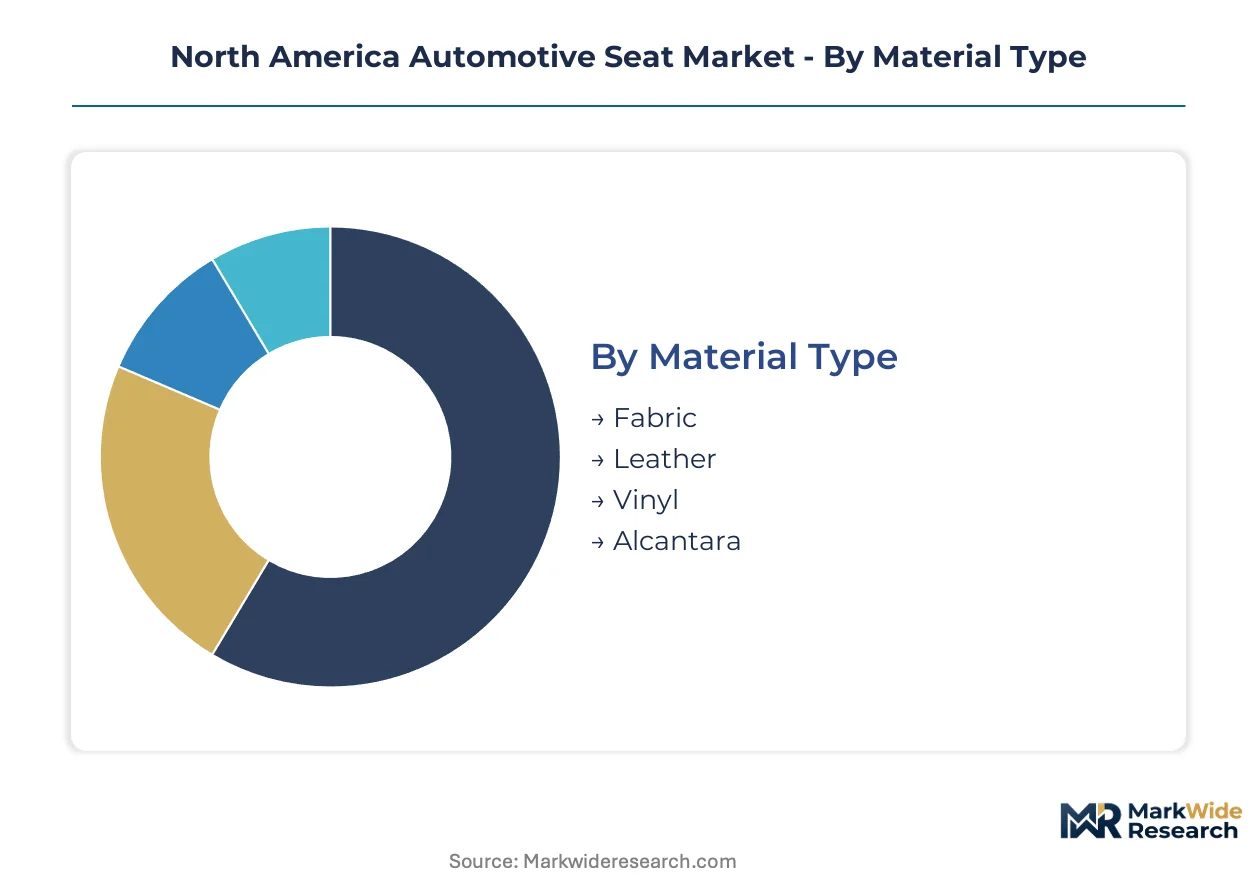
Seat architecture in North America fragments across material specifications, mechanical configurations, and thermal comfort technologies. Each segmentation axis carries distinct margin profiles and regulatory exposure that reshape supplier investment priorities across the Great Lakes and Mexican Bajío corridors.
Material Type:
Premium trim configurations concentrate margin pools in synthetic and natural leather applications, while mass-market programs anchor volume in woven textiles and vinyl formulations.
- Leather:Full-grain and corrected-grain hides dominate luxury nameplate interiors across Detroit Three premium truck and SUV lines. Demand clusters in Michigan and Ohio final assembly plants where OEMs bundle leather seating into high-margin trim packages. NHTSA flammability standards and California's advancing low-carbon material mandates are accelerating vegetable-tanning process investments.
- Fabric:Woven polyester and nylon blends anchor mass-market sedan and compact SUV programs through cost-optimized supply chains anchored in South Carolina textile corridors. The segment faces margin compression from recycled-content certification requirements spreading across California and Quebec regulatory jurisdictions.
- Vinyl:PVC-based synthetic leather substitutes serve fleet and commercial vehicle segments where durability and cleanability outweigh tactile premium requirements.
- Alcantara:Microfiber suede applications concentrate in performance nameplates and limited-edition trims where weight reduction and distinctive haptic properties justify material premiums.
The dominant share belongs to fabric, while leather is closing the gap fastest through premium truck and SUV configuration bundling.
Seat Type:
Structural architecture choices cascade into frame metallurgy decisions and suspension system complexity, with individual adjustability commanding engineering investment priority.
- Bucket:Individual seating positions with independent fore-aft, recline, and height adjustment dominate light-truck and SUV applications where consumer preference favors personalized ergonomics. Michigan and Ohio assembly plants specify bucket architectures for over eighty percent of crew-cab pickup production.
- Bench:Continuous seating surfaces persist in commercial van and entry-level sedan segments where cost minimization and passenger capacity outweigh individual adjustability requirements.
- Recliner:Articulating backrest mechanisms with extended travel ranges serve second-row comfort applications in full-size SUV and minivan platforms.
- Captain:Individual bucket seats separated by center consoles anchor premium three-row SUV configurations, requiring reinforced floor pan attachments and integrated armrest structures.
Bucket configurations hold the volume leadership position, though captain chairs are expanding most quickly through three-row SUV platform proliferation.
End User:
Supply chain position determines specification authority and volume volatility exposure, with direct OEM relationships displacing mediated tier-two arrangements.
- OEMs:Detroit Three technical centers in Warren, Dearborn, and Auburn Hills retain final specification authority over frame metallurgy, foam density, and trim material selection. Direct engineering relationships concentrate investment in modular platform architectures that cross multiple nameplates.
- Tier-1 Suppliers:Lear Corporation and Adient plc anchor seat module assembly through vertically integrated foam-in-place and frame manufacturing capabilities. These suppliers capture value previously lost to downstream integrators while absorbing volume volatility from individual nameplate cancellation decisions.
- Vehicle Assemblers:Final assembly plants in Michigan, Ohio, and Ontario coordinate just-in-time seat module sequencing with body shop throughput.
- Aftermarket Providers:Independent distributors serve collision repair and customization segments with lower regulatory scrutiny but thinner margin profiles than original equipment contracts.
OEMs control the specification hierarchy, yet tier-1 suppliers are gaining share fastest through integrated module assembly and direct engineering accountability.
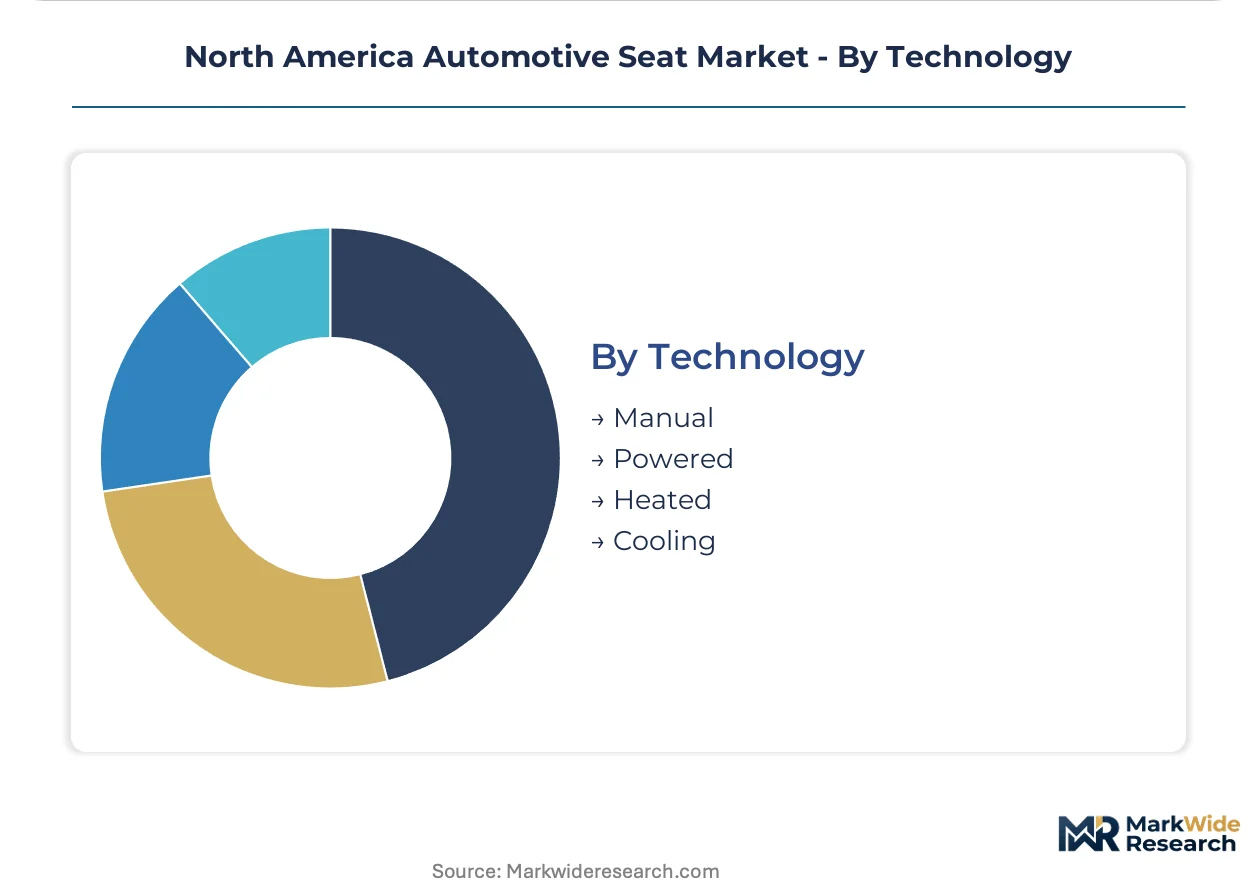
Technology:
Thermal comfort features and powered adjustment mechanisms concentrate margin pools in premium trim configurations, while manual systems anchor entry-level programs.
- Powered:Electric motors driving fore-aft, height, lumbar, and tilt functions command the strongest margin pools as OEMs bundle multi-way adjustability into mid-tier and premium configurations. Wiring harness integration and motor durability validation extend development timelines.
- Heated:Resistive heating elements woven into cushion and backrest foam layers spread from luxury nameplates into mass-market cold-weather packages. Demand concentrates in Great Lakes and Canadian markets where consumer willingness-to-pay for thermal comfort remains elevated.
- Cooling:Forced-air ventilation systems with permeable trim materials and blower motor integration serve premium truck and SUV segments where competitive differentiation justifies additional cost and complexity.
- Manual:Mechanical linkages and recliner mechanisms anchor entry-level compact and subcompact programs where cost discipline overrides comfort feature proliferation.
Powered systems occupy the revenue core, while heated configurations are climbing the fastest through cold-weather package standardization across Detroit Three lineups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA Federal Motor Vehicle Safety Standards anchor seat design requirements across the dominant United States market, while EPA Corporate Average Fuel Economy rules push lightweight frame adoption throughout the tri-national supply chain.
United States
Detroit Three OEM final assembly expansion drives seat module demand across Michigan, Ohio, and Indiana manufacturing corridors. NHTSA FMVSS 202a head-restraint geometry mandates accelerate frame redesign cycles for high-strength steel and aluminum extrusion sourcing. Warren, Dearborn, and Auburn Hills technical centers concentrate specification authority for modular platform architectures serving light-truck and SUV production.
Canada
Quebec-smelted primary aluminum gains preferential positioning under federal clean fuel regulations and provincial carbon pricing schemes. Health Canada and Transport Canada coordinate occupant protection standards with NHTSA protocols to maintain cross-border platform commonality. Ontario assembly plants in Windsor, Oakville, and Alliston synchronize just-in-time seat sequencing with U.S. Midwest body shop throughput.
Mexico
Bajío automotive corridor expansion around León and Silao localizes seat module demand within four-hour logistics radii of frame and foam production facilities. Mexican federal environmental regulations and labor standards shape chemical handling protocols at foam-in-place manufacturing plants. Nuevo León and Jalisco assembly operations anchor tier-one supplier investment in vertically integrated module assembly capacity.
Great Lakes Manufacturing Zone
Polyurethane foam technician scarcity inflates wage premiums across Michigan and Ohio supplier plants specializing in chemical process control. OSHA workplace standards govern isocyanate and polyol handling protocols at U.S. foam production facilities. Lansing, Flint, and Lordstown production clusters face compressed design-to-tooling windows from evolving NHTSA side-impact test procedures.
Southeastern Mexico Supply Base
Advanced stitching automation specialist shortages reorganize hiring patterns across tier-two trim suppliers serving Bajío OEM final assembly. Mexican federal labor law and occupational safety regulations shape workforce development investments for foam-chemical handling expertise. Puebla and Querétaro industrial corridors concentrate frame stamping and suspension component manufacturing for cross-border platform supply.
North America Automotive Seat Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated module assembly capabilities separating tier-one suppliers from component-focused fabricators. The market structure concentrates specification authority with Detroit-area technical centers while exposing seat suppliers to volume volatility from individual nameplate decisions. Three archetypes dominate: vertically integrated module assemblers, frame-and-foam specialists, and trim-focused component suppliers. Competitive moves center on backward integration into foam-in-place manufacturing and geographic co-location with OEM final assembly plants.
Among integrated module assemblers, Lear Corporation and Adient plc exemplify the tier-one archetype through captive supply of structural frames and polyurethane foam systems. Toyota Boshoku Corporation anchors the Japanese-origin specialist tier with manufacturing presence serving transplant OEM operations. Faurecia SE (FORVIA) occupies a position bridging European engineering heritage with North American platform scale requirements. These three entities represent distinct strategic postures: Lear Corporation and Adient plc through Detroit-proximate vertical integration, Toyota Boshoku Corporation through transplant supply chain alignment, and Faurecia SE through cross-regional technology transfer.
| Leading Market Players |
|---|
| Lear Corporation |
| Adient plc |
| Toyota Boshoku Corporation |
| Faurecia SE (FORVIA) |
| Magna International |
| Johnson Controls |
| Tachi-S Co., Ltd. |
| NHK Spring Co., Ltd. |
| RECARO Automotive Seating |
| Others |
Value Network & Pricing Analysis
Capacity utilization at foam-in-place manufacturing facilities across the Great Lakes and Mexican Bajío corridors shapes supplier pricing power and establishes floor pricing for seat module contracts. NHTSA compliance investments and EPA lightweighting mandates compress margin buffers, forcing tier-one suppliers to extract value through backward integration rather than price escalation.
Pricing Analysis
Michigan and Ohio assembly plants command pricing premiums over Mexican Bajío sourcing for identical seat specifications, reflecting logistics proximity to Detroit Three technical centers and just-in-time sequencing requirements. Three-tier pricing structure across premium leather, mid-grade fabric, and economy vinyl configurations anchors contract negotiations, with thermal comfort feature bundling driving differentiation. Cost compression in mass-market fabric tiers is intensifying because recycled-content certification requirements spread across California and Quebec regulatory jurisdictions. Fleet procurement departments exhibit highest price sensitivity, while luxury SUV trim buyers absorb premium leather and powered adjustment premiums with minimal negotiation.
Supply Chain Analysis
U.S. Gulf Coast polyol and isocyanate production clusters create chemical feedstock chokepoints that expose foam suppliers to hurricane-related disruption cascades with limited secondary sourcing. Seat frame manufacturing draws from high-strength steel mills in Indiana and Ohio, aluminum extrusion facilities in Quebec, and suspension component stamping operations in Puebla and Querétaro. Single-source vulnerability concentrates in specialized polyurethane foam technician labor pools across Michigan and Ohio. Distribution runs through tier-one module assemblers co-located within four-hour logistics radii of OEM final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle platform proliferation represents an early-cycle expansion story, with seat architecture redesigns for battery-electric vehicles creating replacement demand across existing nameplate portfolios.
For Market Incumbents: Compound defensive positioning through captive foam-in-place manufacturing investments and Quebec aluminum sourcing agreements that lock in low-carbon frame material advantages. Emerging bio-based polyurethane formulations from castor oil and soy polyols threaten petrochemical feedstock exposure for suppliers slow to qualify agricultural alternatives. NHTSA side-impact protocol compliance timelines compress design-to-tooling windows, favoring incumbents with established validation infrastructure.
For New Entrants and Emerging Players: Anchor in aftermarket thermal comfort retrofit segments where regulatory scrutiny remains minimal and consumer willingness-to-pay for heated seat upgrades runs high. The commercial van and last-mile delivery vehicle segments present the most penetrable white-space, with fleet procurement departments unbundling seat module sourcing from complete vehicle contracts. A direct supplier-fleet engineering relationship model bypasses tier-one assembler mediation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated module assemblers with captive foam and frame capabilities over trim-focused component suppliers exposed to stitching automation specialist shortages. Long-term viability hinges on qualification timelines for bio-based foam formulations and recycled synthetic fiber certification. The signal to monitor is California's advancing recycled-content mandate enforcement velocity as an inflection indicator for material substitution investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Foam-in-Place Manufacturing Scale-Up | Lear Corporation and Adient plc capture value previously lost to downstream integrators through in-situ molding process control. |
| Quebec Aluminum Sourcing Agreement | Federal clean fuel regulations and provincial carbon pricing create preferential positioning for low-carbon primary aluminum in seat frames. |
| Bio-Based Polyurethane Qualification | Castor oil and soy polyol formulations compress petrochemical feedstock exposure while creating Midwest agricultural supply chain dependencies. |
| Modular Platform Architecture Investment | Decoupled structural frames from trim systems enable faster model-cycle refresh rates without full tooling reinvestment for Detroit-area OEMs. |
| Recycled Synthetic Fiber Certification | Verified post-consumer polyester supply chains create first-mover advantages under California's advancing low-carbon material mandates. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-one supplier procurement leads, polyurethane foam technicians, and aftermarket distribution channel heads converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation against NHTSA FMVSS filings, EPA fuel economy rulemakings, vehicle production databases, and IHS Markit registration data established baseline demand estimates. Bottom-up seat content per vehicle calculations triangulated against top-down market value reconstructions.
Segmentation dimensions modeled span material type, seat architecture, thermal comfort technology, and propulsion platform across the projection horizon. CAGRs were derived from trend extrapolation of electric vehicle penetration rates and lightweighting investment cycles. Industry-specific forecast inputs include NHTSA side-impact protocol implementation timelines and Quebec carbon pricing trajectory assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued Detroit Three light-truck production concentration assumptions; material deviation in trade policy or battery-electric vehicle adoption velocity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Global Automotive Tinted Window Pane Market