
 Automotive Sealants Market | 2026-2036
Automotive Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sealants Market Intelligence
The European Union's Green Deal, with its focus on vehicle emissions reduction and circular economy principles, is restructuring demand for advanced automotive sealants. Henkel AG & Co. KGaA leverages its extensive portfolio to serve the specific needs of electric vehicle battery sealing. Sika AG competes through its high-strength structural bonding solutions for lightweight, multi-material vehicle bodies. Dow Inc. specializes in silicone technologies that provide critical protection for sensitive electronic components and battery systems.
Automotive sealants are advanced polymeric materials engineered to prevent the passage of fluids, air, and contaminants between vehicle components. These formulations are specified by their rheology, cure mechanism, and long-term resistance to vibration, UV exposure, and automotive chemicals. Polyurethane and MS Polymer sealants dominate body shop applications due to their high structural strength and durability. Within the technology segment, water-based formulations are gaining traction for interior assembly, driven by OEM requirements for low-VOC materials.
Regulations from the US EPA on volatile organic compounds and Europe's REACH framework directly influence sealant chemistry. These standards compel a shift towards low-VOC and solvent-free formulations like water-based and MS Polymer products. Navigating divergent regional standards for chemical safety and end-of-life vehicle material recovery will be a critical determinant of supplier success.
Market Dynamics
The transition toward electric vehicles and the parallel push for lightweight vehicle architectures represent the central structural force shaping the automotive sealants market. Demands for specialized battery pack sealing solutions and compliance with circular economy principles, such as the EU's End-of-Life Vehicles Directive, are fundamentally altering material science requirements and OEM specification criteria.
Growth Catalysts
- Electric Vehicle Production:The expansion of EV manufacturing creates substantial demand for sealants used in battery pack assembly, where they provide thermal management, fire retardancy, and protection from moisture and vibration.
- Lightweighting Mandates:Regulations targeting vehicle emissions and fuel efficiency encourage the use of multi-material bodies, increasing the reliance on structural sealants and adhesives to bond dissimilar substrates like aluminum, composites, and high-strength steel.
- Low-VOC Formulations:OEM and regulatory pressure to reduce volatile organic compounds inside vehicle cabins, guided by standards from the US EPA and China's MEE, drives the adoption of water-based and MS Polymer sealants for interior applications.
Market Restraints
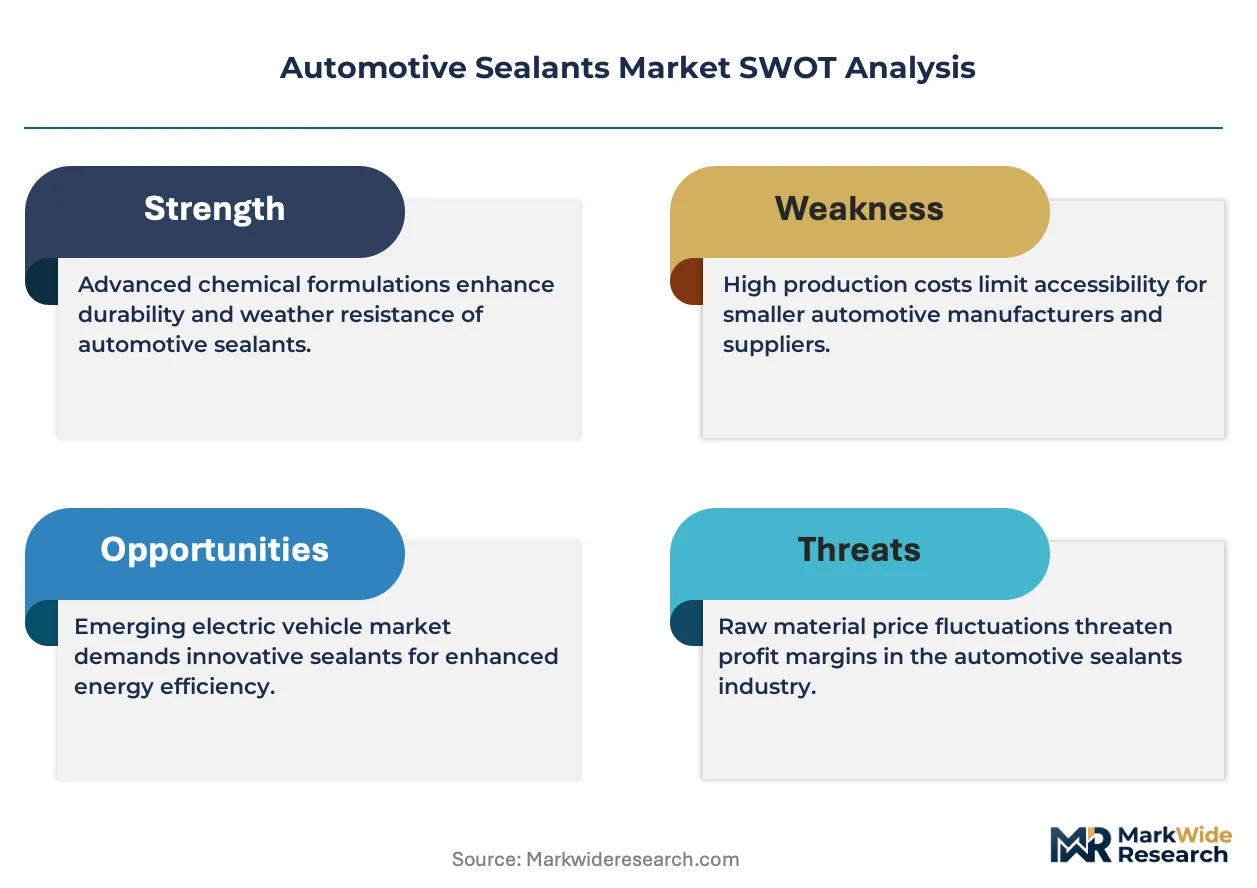
- Raw Material Price Volatility:The market is exposed to price fluctuations in key petrochemical feedstocks, including polyols, isocyanates, and silane precursors, which can compress supplier margins and affect end-product pricing.
- Multi-Material Adhesion Challenges:Ensuring durable, long-term adhesion between diverse substrates with different coefficients of thermal expansion, such as carbon fiber composites and aluminum, remains a significant technical barrier for structural applications.
- Divergent Regional Standards:Navigating conflicting chemical regulations like Europe's REACH and the US's Toxic Substances Control Act (TSCA) complicates global product development, formulation, and market entry for sealant manufacturers.
Strategic Opportunities
- Sealants for ADAS and Sensors:A developing opportunity exists in formulating specialized sealants for protecting sensitive ADAS cameras, LiDAR, and radar sensors from environmental factors without interfering with their operational frequencies.
- Conductive and Shielding Formulations:The integration of conductive fillers into sealants presents a white-space opportunity for creating materials that provide both environmental sealing and electromagnetic interference (EMI) shielding for vehicle electronics.
- Bio-Based and Recyclable Materials:Developing sealants from renewable feedstocks or designing them for easier disassembly and recycling aligns with OEM sustainability goals and regulations like the EU Green Deal, creating a new basis for competitive differentiation.
Industry Challenges
- OEM Qualification Timelines:The extensive and time-consuming testing and validation processes required to gain OEM approval for new sealant formulations can act as a significant barrier to innovation and slow market adoption.
- Application Process Automation:Adapting sealant rheology and cure profiles for high-speed robotic application on complex assembly lines presents an ongoing engineering challenge, requiring close collaboration between material suppliers and equipment manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sealants Market |
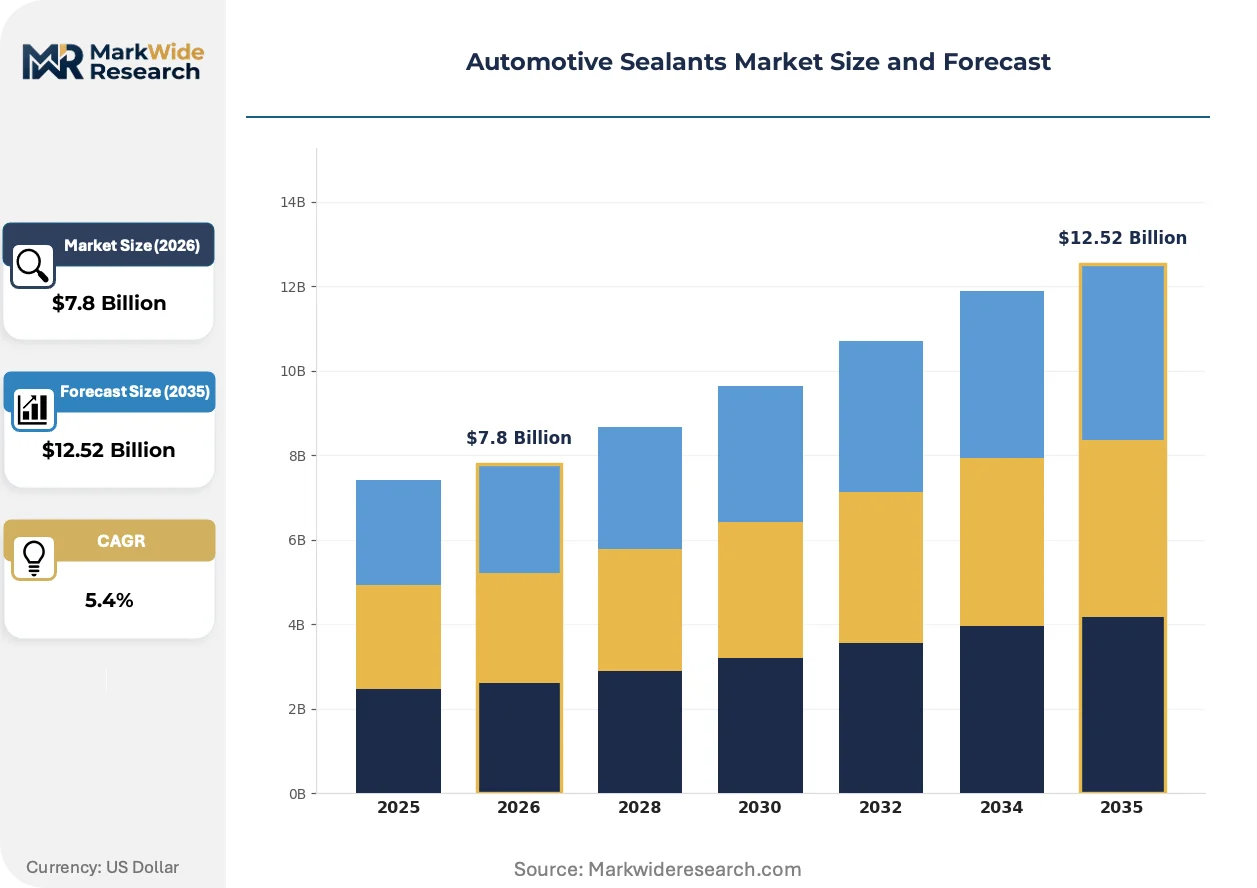
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Sealants, Polyurethane Sealants, MS Polymer Sealants, Acrylic Sealants End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Body Shop, Engine Compartment, Windshield, Interior Assembly Technology: Thermosetting, Thermoplastic, Solvent-Based, Water-Based |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, BASF SE, H.B. Fuller Company, Dow Inc., Arkema, Huntsman Corporation, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sealants Market Strategic Shifts & Innovations
The market's evolution is defined by the need to engineer materials that meet stringent sustainability targets without compromising on the advanced performance required by modern vehicle platforms. This dynamic forces innovation in polymer chemistry, particularly for applications in electric vehicles and lightweight body structures where durability and safety are critical.
Modified Silane (MS) Polymer technology combines the strength of polyurethanes with the flexibility and weathering resistance of silicones. Automotive OEMs and Tier 1 suppliers are adopting these isocyanate-free formulations for both structural bonding and elastic sealing. The technology's favorable environmental profile and versatile performance mean MS Polymers are overtaking traditional chemistries in specifications for new vehicle body shops.
Europe's REACH regulation continues to restrict the use of certain chemicals, directly influencing sealant formulation across the continent. This framework compels a move away from solvent-based products and specific plasticizers, accelerating research into safer, compliant alternatives like water-based acrylics and high-solids polyurethanes. The body-in-white and paint shop segments are most impacted, adapting processes to accommodate the different curing mechanisms of these newer materials.
Automaker material specification is evolving from a product-centric to a system-based approach, especially for critical assemblies. OEMs now often qualify an entire suite of compatible products—such as primers, adhesives, and sealants for a battery enclosure—from a single source to ensure system integrity. This shift in procurement is most visible in the advanced manufacturing hubs of Germany and South Korea, favoring suppliers with broad, integrated portfolios.
Automotive Sealants Market Segmentation
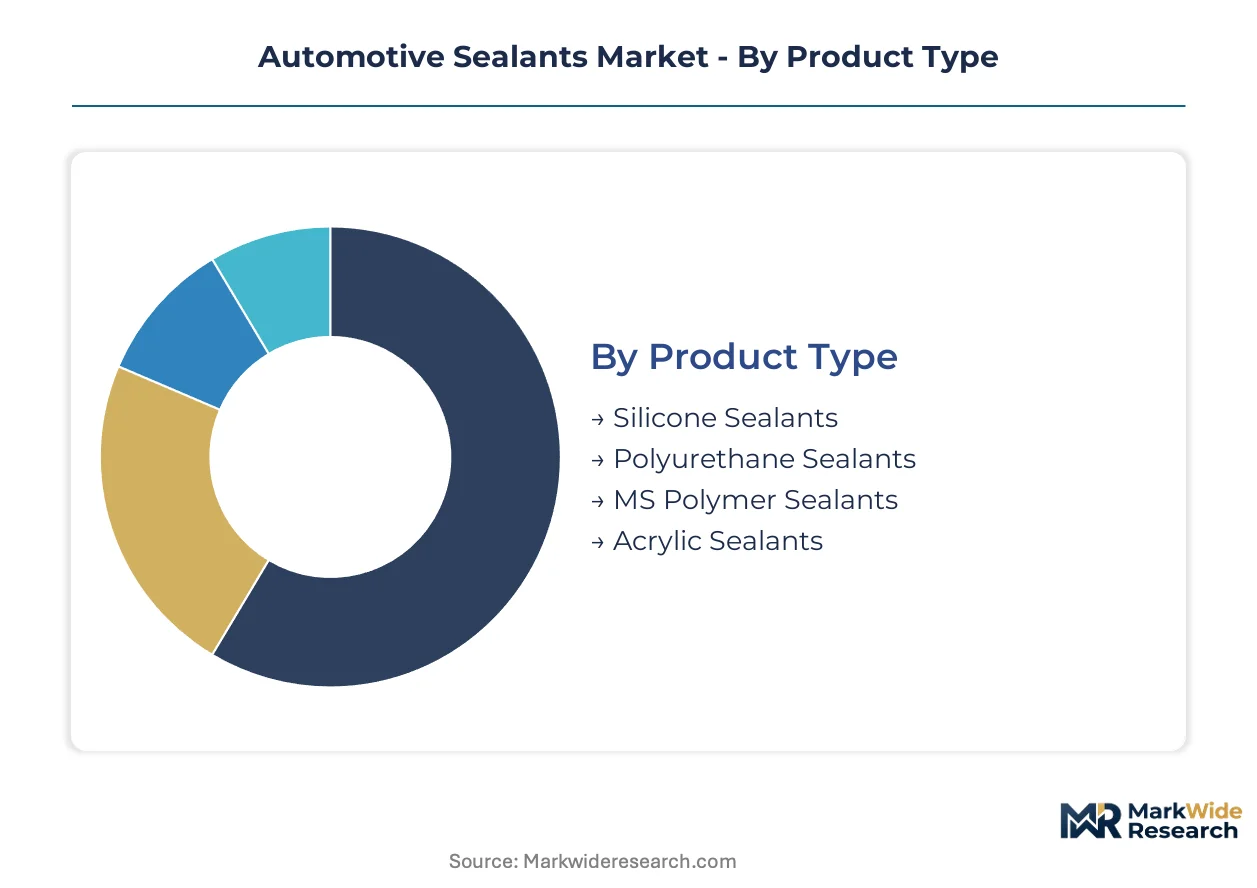
Understanding the varied requirements across automotive manufacturing and vehicle lifecycle stages is critical for sealant suppliers. This market segments across distinct product types, end-user applications, and underlying technologies. Each segment presents unique performance demands and regulatory compliance challenges for material science developers.
Product Type:
Buyer selection in this category is differentiated by the specific performance characteristics required for the application, balancing flexibility, adhesion strength, and environmental resistance.
- MS Polymer Sealants:These modified silane formulations offer a compelling combination of polyurethane's strength and silicone's flexibility, while being isocyanate-free. Demand is concentrating in body shop applications within Germany and South Korea, driven by OEM specifications for enhanced durability and environmental compliance.
- Polyurethane Sealants:Known for their high structural strength and excellent adhesion to various substrates, polyurethane sealants are widely used in body-in-white and direct glazing applications. Their application is particularly prevalent in high-volume automotive production hubs in China, where robust bonding solutions are essential for vehicle integrity.
- Silicone Sealants:Silicone sealants provide superior temperature resistance and protect sensitive electronic components, crucial for battery pack sealing and ADAS sensors.
- Acrylic Sealants:Acrylic sealants, often water-based, offer good UV resistance and are specified for interior trim and non-structural sealing where low-VOCs are prioritized.
Polyurethane Sealants lead volumes today; MS Polymer Sealants are gaining share fastest.
End User:
Application focus varies among different end users in this market, reflecting their distinct roles in the automotive value chain.
- OEMs:Original Equipment Manufacturers directly integrate sealants into new vehicle production, driving specifications for performance, automation compatibility, and regulatory compliance. Their demand is concentrated in advanced manufacturing facilities in Germany and Japan, where vehicle platforms are designed for longevity and safety.
- Tier-1 Suppliers:These suppliers manufacture major sub-assemblies like battery packs, seating systems, or body components, sourcing sealants that meet OEM specifications for their integrated products. They operate globally, with significant purchasing volumes in Mexico and Eastern Europe, supporting large assembly plants.
- Aftermarket Providers:Aftermarket providers, including repair shops and parts distributors, use sealants for vehicle maintenance and collision repair, emphasizing ease of application.
- Vehicle Assemblers:Vehicle assemblers focus on final component integration, using sealants for windshield installation and interior trim, often prioritizing fast-curing formulations.
OEMs establish the initial demand; aftermarket providers ensure long-term vehicle maintenance.
Application:
The specific performance requirements of each application area dictate the sealant chemistry chosen for automotive use.
- Body Shop:This segment encompasses structural bonding, seam sealing, and anti-flutter applications during the body-in-white stage, demanding high-strength, durable, and corrosion-resistant formulations. Demand is high in major automotive production centers like China and the United States, where vehicle bodies are assembled.
- Interior Assembly:Sealants here focus on noise, vibration, and harshness (NVH) reduction, trim attachment, and cabin air quality, requiring low-VOC, aesthetically pleasing, and flexible materials. This application is critical for passenger comfort and air quality regulations in Europe, influencing material choices.
- Engine Compartment:Engine compartment sealants must withstand extreme temperatures, oils, and fuels, providing durable sealing for components like valve covers and oil pans.
- Windshield:Windshield sealants provide structural integrity, crash resistance, and weather sealing, with fast cure times essential for efficient assembly line processes.
Body shop applications consume the largest volumes; interior assembly demands specialized low-VOC formulations.
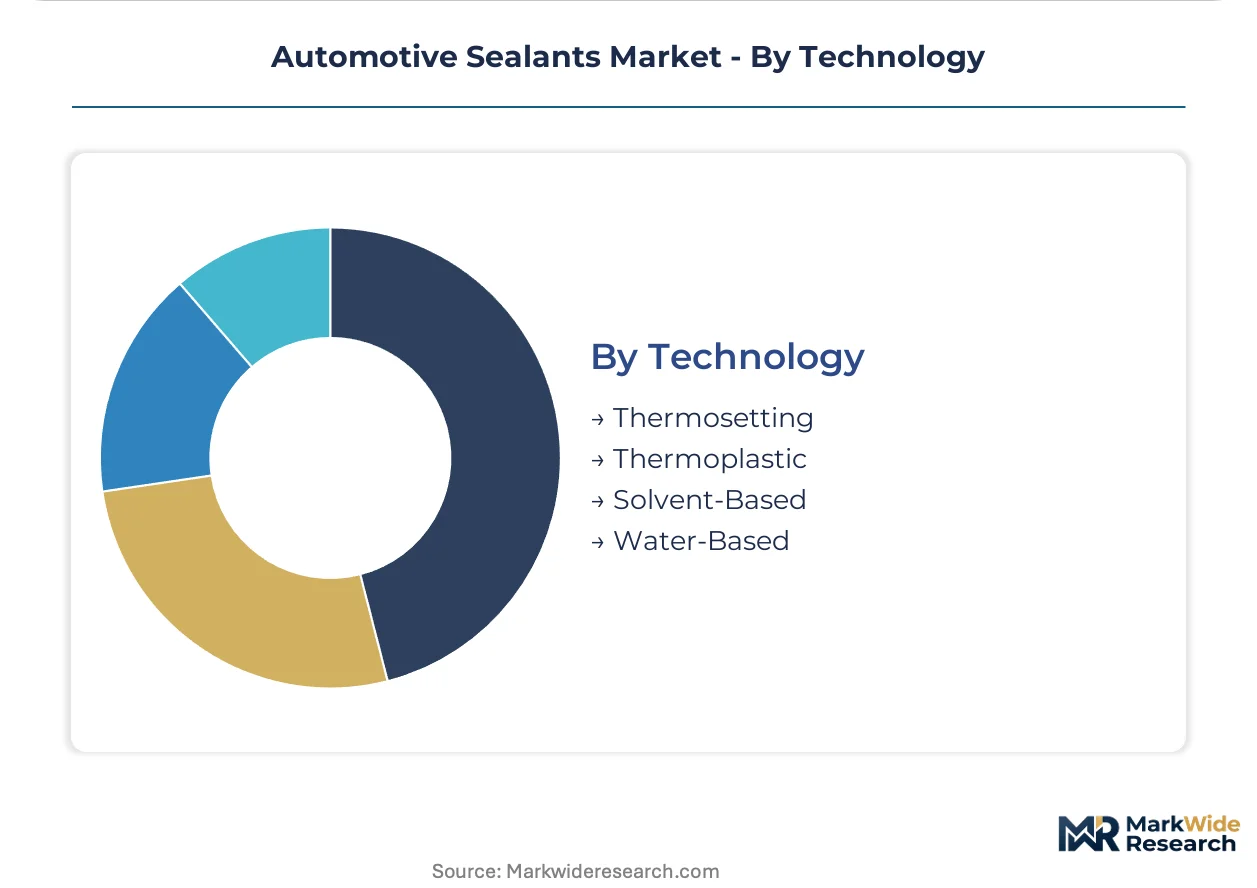
Technology:
Technological advancements are driving a shift towards more sustainable and high-performance sealant formulations in the automotive sector.
- Water-Based:These formulations reduce volatile organic compound (VOC) emissions, aligning with stringent environmental regulations and OEM sustainability goals for interior and non-structural applications. Their use is expanding quickly in European markets due to the EU Green Deal and REACH framework.
- Thermosetting:Characterized by irreversible chemical cross-linking upon curing, thermosetting sealants offer high mechanical strength, chemical resistance, and thermal stability, suitable for structural and high-performance applications. These are critical for heavy-duty vehicle manufacturing in the US, ensuring long-term durability.
- Solvent-Based:Historically dominant, solvent-based sealants are seeing reduced adoption due to environmental concerns, though they offer quick drying and good adhesion in specific legacy applications.
- Thermoplastic:Thermoplastic sealants can be repeatedly softened by heating and hardened by cooling, offering processing flexibility and recyclability for less demanding applications.
Water-based technologies are expanding quickly; thermosetting formulations provide high structural integrity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled engineering workforces and advanced manufacturing capabilities drive regional sealant demand across key automotive production centers. These regions exhibit distinct regulatory frameworks and OEM requirements shaping material specifications. Sealant suppliers must navigate varied technical demands and compliance landscapes.
China
China's robust electric vehicle manufacturing sector creates substantial demand for specialized battery pack sealants. The Ministry of Ecology and Environment (MEE) standards for volatile organic compounds influence sealant chemistry for interior applications. Automotive production clusters in the Yangtze River Delta actively integrate advanced sealant technologies into new vehicle platforms.
Germany
Germany's focus on lightweight vehicle architectures and circular economy principles drives demand for high-strength structural sealants. The EU Green Deal and REACH framework compel manufacturers to adopt low-VOC and solvent-free formulations. Bavaria and Baden-Württemberg, key automotive regions, prioritize system-based sealant qualification for advanced vehicle designs.
United States
United States automotive production benefits from significant investments in EV manufacturing and multi-material body structures. US EPA regulations on VOC emissions influence the adoption of water-based and MS Polymer sealants. Michigan's automotive hub remains a center for OEM and Tier-1 supplier collaboration on sealant development and application processes.
South Korea
South Korea's leadership in battery technology and advanced electronics manufacturing generates specific demand for silicone sealants in EV battery packs and ADAS sensors. The country's chemical safety regulations, influenced by global standards, guide formulation choices for new materials. The Seoul Capital Area drives innovation in material science for next-generation vehicle components.
Japan
Japanese automakers prioritize high-performance sealants for ADAS sensor protection and structural applications in hybrid and electric vehicles. JIS standards for industrial materials ensure product quality and reliability across the supply chain. The Chubu region, home to major automotive OEMs, focuses on integrating advanced sealing solutions for enhanced vehicle durability.
Automotive Sealants Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in automotive sealants. The market exhibits a tiered structure, with large diversified chemical companies alongside specialized material science firms. Strategic archetypes include integrated solution providers, niche technology specialists, and regional manufacturers. Dominant competitive moves involve portfolio diversification and strategic partnerships.
Large, diversified chemical conglomerates, such as Germany-based Henkel AG & Co. KGaA, exemplify integrated solution providers offering broad portfolios across various automotive applications. Switzerland-based Sika AG occupies a position as a leading specialist in high-strength structural bonding solutions. Dow Inc., a US-based chemical giant, anchors the market with its advanced silicone technologies for critical electronic and battery systems. These entities collectively shape product development and market access.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| BASF SE |
| H.B. Fuller Company |
| Dow Inc. |
| Arkema |
| Huntsman Corporation |
| PPG Industries |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and diversified chemical conglomerates shape supply behavior and pricing discipline across the automotive sealants market. Their investment in specialized production facilities and long-term OEM contracts influence material availability and cost structures.
Pricing Analysis
Bundled solutions, encompassing primers, sealants, and application support, command premium pricing within the automotive sealants market. Price differentiation stems from certification levels for specific OEM platforms and the volume scale of procurement contracts. Pricing pressure stems from raw material price volatility, particularly for petrochemical feedstocks like polyols and isocyanates. Aftermarket providers exhibit the highest price sensitivity, while OEMs prioritize performance and long-term reliability over marginal cost savings.
Supply Chain Analysis
Automotive sealant input dependency centers on specialty chemical production in Germany, China, and the United States. Raw material dependencies include polyols, isocyanates, and silane precursors, which are susceptible to global petrochemical market fluctuations. Raw material price volatility represents a significant structural risk for manufacturers. Distribution runs through direct sales channels to OEMs and Tier-1 suppliers, alongside regional distributors serving the aftermarket segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards high-performance, specialized sealants for electric vehicles and lightweight architectures.
For Market Incumbents:Anticipate increasing demand for system-based sealant solutions, particularly for EV battery packs and ADAS components. Diversify portfolios to include bio-based and recyclable formulations, addressing the EU Green Deal's circular economy principles. Invest in R&D for advanced MS Polymer and silicone technologies to mitigate the threat from generic alternatives. Strengthen strategic partnerships with major OEMs in Germany and Japan to secure long-term qualification for critical vehicle platforms.
For New Entrants and Emerging Players:Enter via niche applications requiring specialized performance, such as conductive sealants for EMI shielding in vehicle electronics. Target the burgeoning market for ADAS sensor protection, focusing on formulations that do not interfere with operational frequencies. The most penetrable segment lies in specific regional compliance needs, like low-VOC interior sealants for European markets. A strong go-to-market angle involves offering rapid OEM qualification support and tailored technical assistance.
For Investors and Strategic Acquirers:Diversified chemical conglomerates are the most active acquirers in this space, seeking to expand their high-performance materials divisions. The long-term viability of the automotive sealants market remains strong over the next 5-10 years, driven by electrification and lightweighting trends. Acquisition targets should include specialized material science firms with patented technologies in MS Polymers, advanced silicones, or sustainable formulations. A critical signal to watch is the acceleration of OEM mandates for bio-based or easily recyclable sealant materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in EV Hubs | Secures supply for battery pack manufacturing in China and Germany. |
| Green Manufacturing Transition | Aligns production with EU Green Deal and OEM sustainability goals. |
| Long-term Supply Agreements | Stabilizes raw material costs amidst petrochemical price volatility. |
| Joint Ventures for ADAS Sealants | Combines material expertise with sensor technology for advanced protection. |
| Portfolio Diversification into Bio-based Materials | Addresses demand for sustainable solutions and enhances competitive positioning. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a comprehensive market view. This involved engaging with OEM platform engineers, Tier 1 procurement specialists, R&D directors at sealant manufacturers, and aftermarket distributors. Secondary data sources included vehicle production databases, regulatory reports from the US EPA and EU REACH, and industry association publications. The analysis employed both bottom-up aggregation and top-down validation to ensure data integrity.
The analytical framework modeled market dynamics across the analysis window, segmenting demand by product type, end-user, application, technology, and regional production clusters. Compound annual growth rates were derived from historical data trends and projected future adoption rates, informed by ongoing shifts in vehicle propulsion types. Key forecast inputs included electric vehicle production forecasts and lightweighting material adoption rates across major automotive manufacturing regions.
Inputs from industry reports and regulatory bodies were available through the study window; gaps in emerging material qualification data introduce uncertainty bands. Forecasts reflect assumptions regarding technological advancements and regulatory stability in key markets. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market