
 Light Weight Automotive Body Panels Market | 2026-2036
Light Weight Automotive Body Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Light Weight Automotive Body Panels Market Analysis
OEM procurement concentration is decoupling from traditional steel-centric supplier relationships as electric vehicle programs fragment material sourcing across aluminum, carbon fiber, and magnesium specialists. ArcelorMittal leverages its integrated steel-aluminum portfolio to retain structural panel contracts while defending against substitution. Novelis competes through recycled-content aluminum sheet capacity positioned near North American and European assembly plants. Toray Industries anchors carbon fiber supply for premium electric vehicle roof and hood programs in Asia.
Light weight automotive body panels are structural and closure components engineered from aluminum alloys, carbon fiber reinforced polymers, glass fiber composites, or magnesium castings, typically achieving 30-50% mass reduction versus conventional steel through stamping, injection molding, composite layup, or extrusion processes. Their primary purpose is to reduce vehicle curb weight to improve fuel efficiency and electric range while maintaining crashworthiness and surface quality standards. Aluminum dominates passenger vehicle hood and door applications due to mature stamping infrastructure and cost-positioning relative to carbon fiber. Composite layup leads in sports car and premium electric vehicle segments where low-volume, high-performance panels justify longer cycle times and higher material costs.
The U.S. EPA and NHTSA Corporate Average Fuel Economy standards, European Union CO2 fleet emission regulations, and China's MIIT new energy vehicle credit mandates collectively mandate gram-per-kilometer and mile-per-gallon improvements that force OEMs to adopt lighter body-in-white and closure materials. REACH and RoHS frameworks in Europe restrict certain coatings and additives used in panel surface treatments, redirecting formulation R&D toward compliant pretreatment and adhesive systems. Stakeholders must monitor how battery-electric platform architectures alter load path requirements and whether magnesium extrusion investments can overcome historical corrosion and joining limitations to capture door inner and tailgate applications.
Market Dynamics
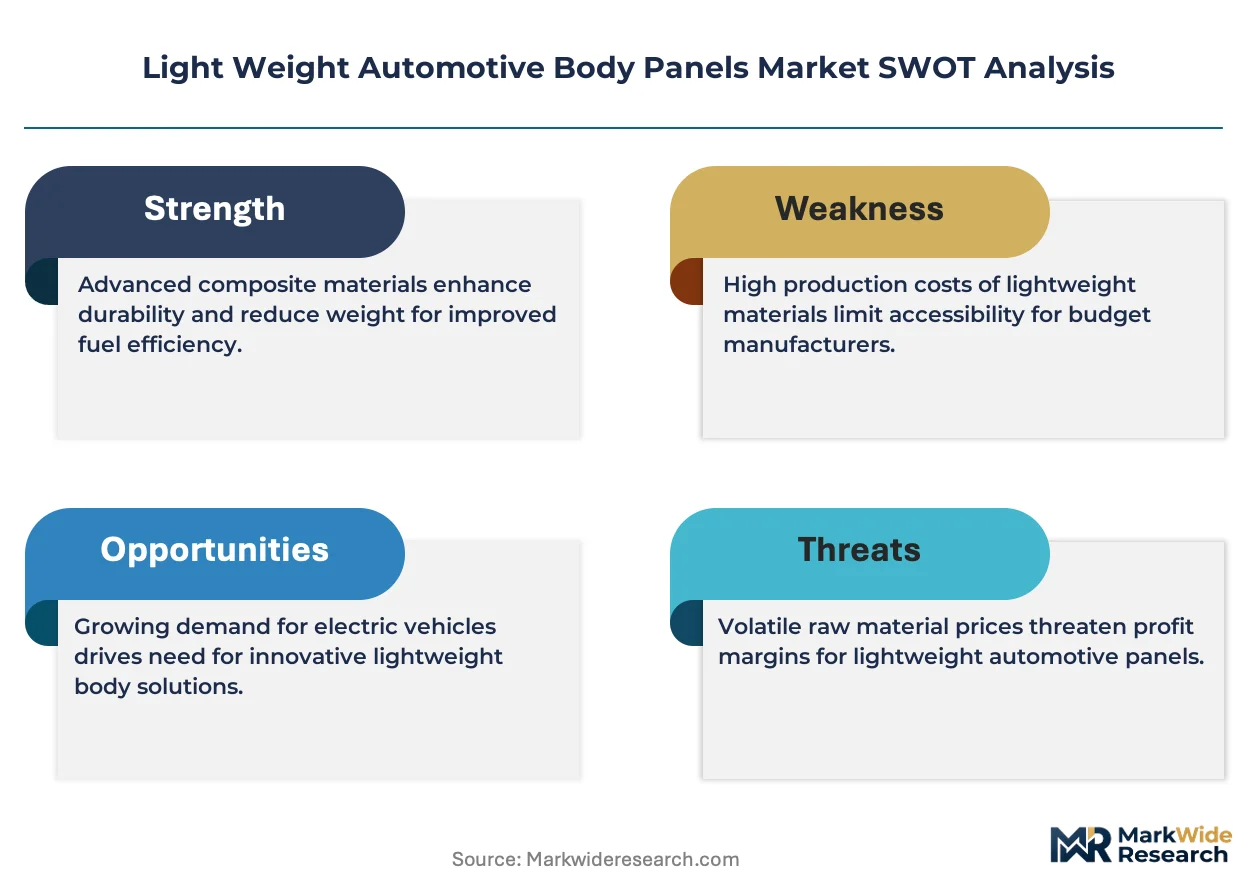
Electric vehicle platform architectures are forcing a recalibration of body panel load path engineering, as battery pack integration shifts structural demands from traditional front-engine crumple zones toward reinforced floor pans and roof structures that demand entirely different material stiffness profiles.
Growth Catalysts
- EU CO2 Fleet Targets:The European Union's binding emission reduction mandates compel OEMs to achieve gram-per-kilometer improvements through mass reduction, directly accelerating aluminum closure adoption in Germany and France.
- China MIIT Credit Mandates:China's Ministry of Industry and Information Technology new energy vehicle credit system rewards range extension, driving carbon fiber roof panel integration in premium domestic EV programs.
- Hot Stamping Infrastructure:Mature aluminum stamping lines in the US Midwest and Ontario enable cost-competitive hood and door production without greenfield capital deployment.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum price swings and energy cost spikes in European smelting regions compress panel supplier margins and destabilize long-term OEM contracts.
- Carbon Fiber Supply Concentration:PAN precursor and oxidation capacity clusters in Japan and select US sites create single-source vulnerability for premium EV roof programs.
- REACH Compliance Friction:ECHA restrictions on hexavalent chromium pretreatments force reformulation of aluminum surface coatings, extending qualification timelines by 12-18 months.
Strategic Opportunities
- Thailand EV Assembly Hub:Board of Investment incentives for EV manufacturing are attracting Chinese and Japanese OEMs, creating localized demand for aluminum closure stamping capacity.
- Magnesium Door Inners:Corrosion-resistant alloy formulations and improved friction stir welding are unlocking tailgate and door inner applications previously blocked by joining limitations.
- IRA Domestic Content Credits:US Inflation Reduction Act battery and assembly incentives are pulling North American aluminum sheet capacity expansion toward Ohio and Kentucky assembly corridors.
Industry Challenges
- Multi-Material Joining Expertise:OEM engineering teams face acute shortages of technicians trained in aluminum-to-steel self-piercing rivet and flow-drill screw processes.
- Crash Simulation Recalibration:Battery-electric platform load path divergence requires rebuilding finite element models from first principles, consuming 18-24 month development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Weight Automotive Body Panels Market |
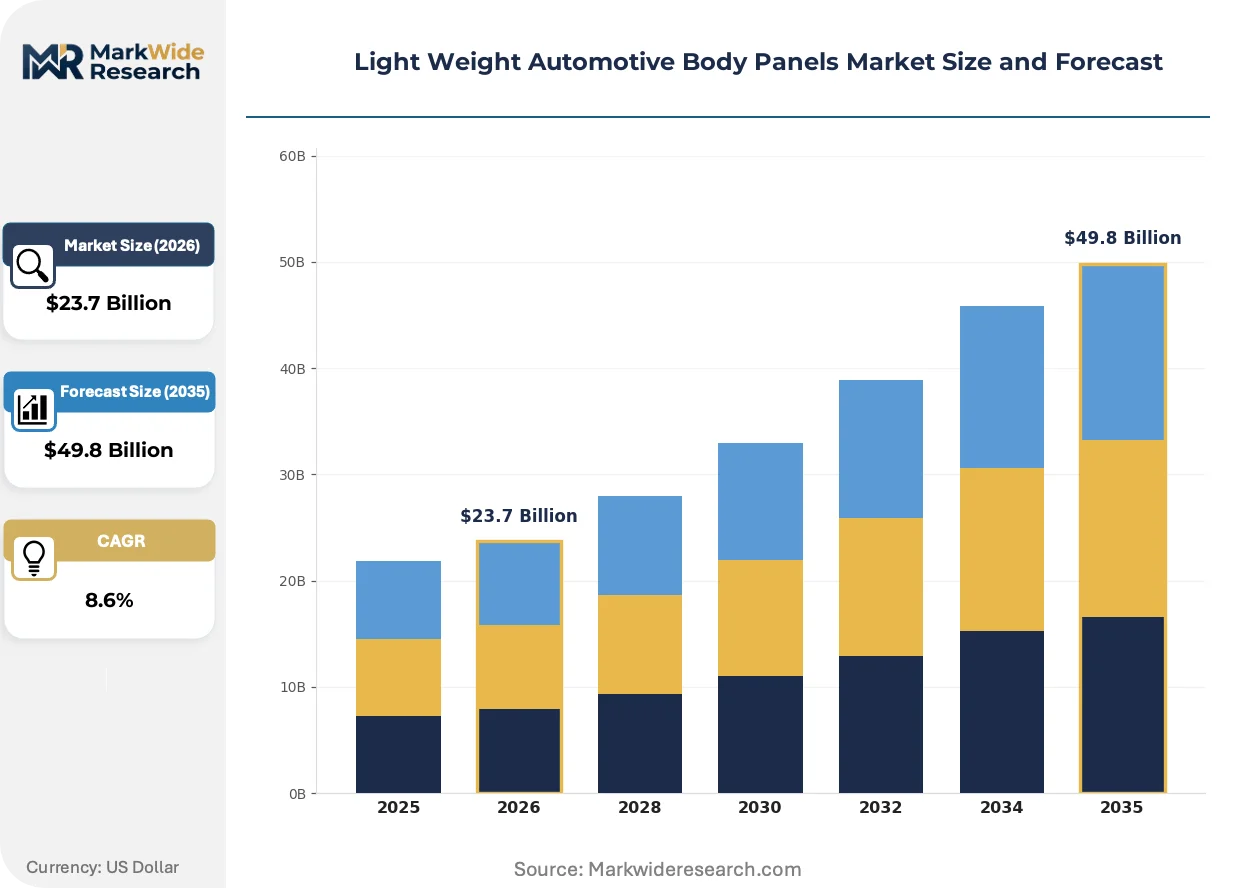
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Carbon Fiber, Glass Fiber, Magnesium End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Stamping, Injection Molding, Composite Layup, Extrusion Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Sports Cars |
| Companies Covered | ArcelorMittal, Magna International, Toray Industries, Alcoa Corporation, Novelis Inc., Constellium, Gestamp, Covestro AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Weight Automotive Body Panels Market Emerging Trajectories
Material-process combinations are proliferating beyond traditional aluminum stamping, as OEMs fragment sourcing across specialist suppliers capable of delivering certified panels for divergent platform architectures. This diversification is compressing incumbent supplier relationships while elevating technical qualification capabilities.
Carbon fiber sheet molding compound is expanding into mid-volume electric vehicle programs through automated preform and fast-cure resin transfer molding. European premium OEMs are adopting Toray and SGL Carbon formulations for hood and fender applications previously reserved for hand-layup sports cars. This expansion into higher-volume segments is compressing the cost gap with aluminum and enabling 40-50% mass reduction in closure systems without sacrificing surface quality.
REACH and RoHS frameworks in Europe are redirecting pretreatment chemistry away from hexavalent chromium toward zirconium and silane-based conversion coatings. ECHA substance restrictions are forcing aluminum suppliers to requalify entire coating stacks, including adhesive bonding primers. Tier-1 panel stampers in Germany and Italy are responding by consolidating formulation partnerships with Henkel and PPG to secure compliant supply chains.
Buyer concentration among battery-electric platform engineering teams is fragmenting traditional steel-centric procurement hierarchies. OEM material selection committees now span aluminum, composite, and magnesium specialists rather than defaulting to integrated steel suppliers. This behavioral shift is most visible in California and Shanghai, where EV-first manufacturers maintain direct supplier relationships with Novelis and Toray bypassing legacy tiered sourcing structures.
Light Weight Automotive Body Panels Market Segmentation
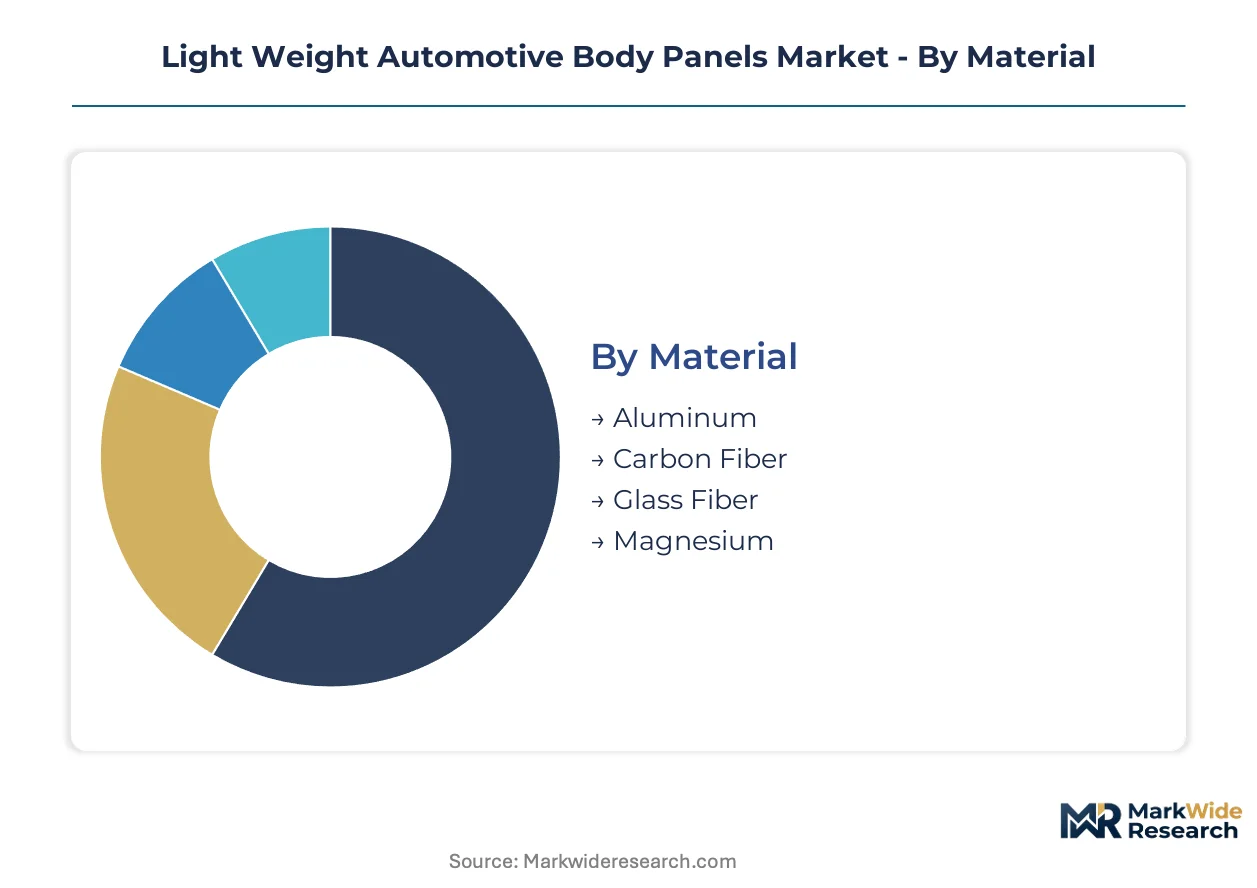
Light weight automotive body panels fragment across material, process, and end-use dimensions that determine qualification complexity and contract value. Each segment carries distinct tooling investments and regulatory compliance burdens that reshape supplier competitive position.
Material:
Upgrade cycles in body panel materials track platform electrification timelines, with incumbent aluminum facing displacement from carbon fiber in premium architectures.
- Aluminum:Stamped aluminum sheet dominates hood and door applications through mature North American and European supplier infrastructure. Demand concentrates in Germany and the United States where OEMs leverage existing press capacity for high-volume closure programs facing EPA and NHTSA fuel economy mandates.
- Carbon Fiber:Carbon fiber reinforced polymers deliver maximum mass reduction for electric vehicle roof and hood panels where range extension justifies material cost premiums. Japanese precursor supply chains anchor premium EV programs in Asia, with Toray Industries and SGL Carbon securing multi-year platform contracts.
- Glass Fiber:Glass fiber composites occupy mid-market applications where cost-positioning limits carbon fiber adoption, serving commercial vehicle panels and economy passenger vehicle closures.
- Magnesium:Magnesium castings and extrusions target door inners and tailgates as corrosion-resistant alloys and friction stir welding techniques overcome historical joining limitations.
Aluminum sits at the top of the volume ranking, with carbon fiber climbing the fastest.
End User:
Customer type determines contract structure, with direct OEM relationships commanding premium pricing against fragmented aftermarket channels.
- OEMs:Original equipment manufacturers specify material-grade requirements and surface finish standards for platform-integrated body panels, consolidating procurement through aluminum and composite specialists rather than legacy steel-centric hierarchies.
- Tier-1 Suppliers:Tier-1 stampers and composite processors execute panel production under OEM technical supervision, with German and Italian suppliers consolidating compliant coating partnerships with Henkel and PPG under REACH frameworks.
- Aftermarket Providers:Aftermarket channels serve collision repair and restoration segments with lower certification barriers, though crash safety documentation requirements limit unauthorized panel substitution.
- Vehicle Assemblers:Contract assemblers and EV startup manufacturers source panels through direct material supplier relationships, bypassing traditional tiered sourcing structures visible in California and Shanghai.
OEMs capture the dominant contract value share, with Tier-1 Suppliers expanding most quickly through insourced composite capabilities.
Manufacturing Stage:
Process selection locks in capital intensity and cycle time economics that determine viable production volumes per platform.
- Stamping:Aluminum stamping lines in the US Midwest and Ontario enable cost-competitive hood and door production without greenfield investment, serving high-volume internal combustion and battery-electric platforms.
- Injection Molding:Thermoplastic composite injection molding targets complex geometry panels with integrated mounting features, reducing secondary assembly operations for tailgate and liftgate modules.
- Composite Layup:Hand and automated fiber placement serves low-volume sports car and premium EV segments where longer cycle times justify superior stiffness-to-weight ratios.
- Extrusion:Aluminum and magnesium extrusion produces structural rails and reinforcements for battery-electric floor pan architectures, with profile complexity driving die engineering specialization.
Stamping maintains volume leadership, with Composite Layup gaining share fastest in electrified premium segments.
Application:
Vehicle category determines crash load path requirements and surface quality specifications that filter material and process eligibility.
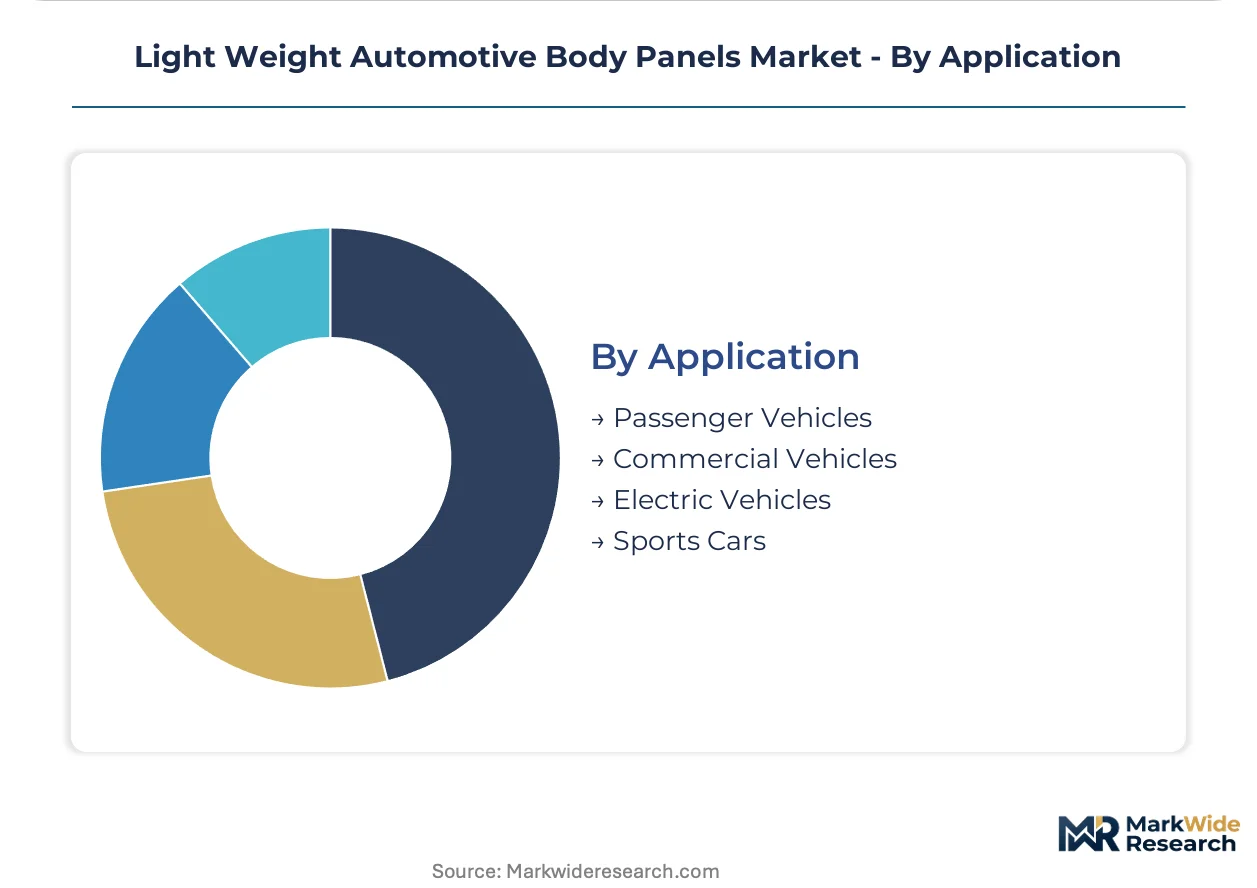
- Passenger Vehicles:High-volume sedan and SUV programs drive aluminum closure standardization, with hood and door panels representing the largest addressable volume for stamped sheet suppliers.
- Commercial Vehicles:Fleet operators prioritize total cost of ownership, favoring glass fiber reinforced panels for delivery van bodies where durability and repairability outweigh mass reduction premiums.
- Electric Vehicles:Battery-electric platforms recalibrate structural demands toward reinforced roof and floor structures, with MIIT credit mandates in China accelerating carbon fiber roof integration in premium domestic programs.
- Sports Cars:Low-volume performance vehicles justify hand-layup carbon fiber body shells, with Italian and British manufacturers maintaining specialized composite supply chains for monocoque construction.
Passenger Vehicles anchor volume demand, with Electric Vehicles expanding most quickly as platform architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tooling engineers and composite technicians concentrate in Germany, Michigan, and Shanghai, anchoring the technical workforce that executes panel qualification programs for electrified platforms.
Germany
Aluminum closure demand from BMW and Mercedes-Benz electrification programs drives supplier investment in stamping capacity. EU CO2 fleet targets under the European Green Deal mandate gram-per-kilometer reductions that accelerate hood and door panel substitution. The Stuttgart and Munich corridors host concentrated tooling expertise serving premium EV architectures.
China
MIIT new energy vehicle credit mandates reward range extension, pulling carbon fiber roof integration into premium domestic EV programs. Dual carbon goals tighten material specifications for body-in-white applications. The Yangtze River Delta clusters composite layup capacity around Shanghai assembly hubs serving NIO and BYD platforms.
United States
EPA and NHTSA Corporate Average Fuel Economy standards force gram-per-mile improvements through mass reduction in closure systems. IRA domestic content credits pull aluminum sheet capacity expansion toward Ohio and Kentucky assembly corridors. The Detroit-to-Toronto stamping belt retains cost-competitive hood and door production infrastructure.
Japan
Toray Industries anchors PAN precursor supply chains serving premium EV roof programs across Asia. METI industrial policy supports carbon fiber oxidation capacity expansion for automotive qualification. The Nagoya and Tokyo metropolitan areas concentrate composite engineering talent for low-volume, high-performance panel development.
Thailand
Board of Investment incentives for EV manufacturing attract Chinese and Japanese OEMs seeking ASEAN market access. Localized aluminum closure stamping demand emerges as assembly capacity scales. The Eastern Economic Corridor around Rayong hosts emerging supplier tooling investments serving regional export programs.
Light Weight Automotive Body Panels Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material-grade boundaries, creating a tiered structure where integrated metals groups defend structural panel contracts against composite and magnesium entrants. Three archetypes dominate: steel-aluminum portfolio diversifiers, recycled-content aluminum specialists, and carbon fiber precursor suppliers. M&A activity concentrates on coating technology assets under REACH pressure, while capacity expansion targets IRA-eligible corridors in North America.
Within the integrated metals tier, ArcelorMittal and Alcoa Corporation exemplify portfolio diversification strategies spanning steel and aluminum structural applications. Novelis Inc. and Constellium occupy positions as recycled-content aluminum specialists with capacity positioned near assembly plants. Toray Industries anchors the carbon fiber precursor tier supplying premium EV programs. These three archetypes represent the competitive vectors reshaping procurement relationships as OEM material selection committees fragment across material specialists.
| Leading Market Players |
|---|
| ArcelorMittal |
| Magna International |
| Toray Industries |
| Alcoa Corporation |
| Novelis Inc. |
| Constellium |
| Gestamp |
| Covestro AG |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up aluminum stamping specialists in Germany and the US Midwest exercise disciplined pricing power through captive press capacity, while sovereign-backed Chinese carbon fiber producers anchor premium segment pricing through controlled PAN precursor supply. This ownership fragmentation creates divergent pricing logics across material tiers, with recycled-content aluminum commanding contract premiums under IRA domestic content rules and Japanese precursor suppliers maintaining margin insulation through technical qualification barriers.
Pricing Analysis
Bundled coating-and-logistics contracts dominate aluminum closure supply to Tier-1 stampers, while unbundled carbon fiber preform sales to premium EV programs separate material cost from processing fees. Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-grade carbon fiber tiers reflects qualification investment recovery timelines, with automotive-certified grades facing cost compression from fast-cure resin transfer molding scale-up. OEM procurement teams in Shanghai and California demonstrate lowest price sensitivity for roof panel programs where range extension credits offset material premiums, while fleet operators in commercial vehicle segments negotiate aggressively on total cost of ownership metrics.
Supply Chain Analysis
Workforce availability for composite layup technicians concentrates in Japan's Nagoya corridor and Germany's Stuttgart region, constraining carbon fiber panel expansion regardless of precursor supply. Primary aluminum smelting draws from bauxite supply anchored in Guinea and Australia, with secondary recovery from post-consumer scrap feeding Novelis and Constellium capacity near Ohio and Kentucky assembly plants. Single-source vulnerability in PAN precursor oxidation capacity creates supply chain risk for premium EV programs, while distribution runs through Tier-1 stamping consortia in Ontario and Bavaria serving OEM final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory mandates for fleet CO2 reduction and electric range extension generate durable demand visibility across platform cycles. Material substitution dynamics and qualification barriers protect incumbent positions while creating selective entry points for specialists.
For Market Incumbents: Extend coating formulation partnerships with Henkel and PPG to lock in REACH-compliant supply chains before ECHA substance restrictions tighten further. Add friction stir welding capacity in Kentucky and Ohio corridors to capture magnesium door inner applications as corrosion-resistant alloys mature, defending against carbon fiber substitution in closure systems.
For New Entrants and Emerging Players: Enter via Thailand's Eastern Economic Corridor where Board of Investment incentives for EV assembly create localized aluminum stamping demand without incumbent capacity overhang. Target carbon fiber recycling and reclaimed precursor processing as the most penetrable white space, leveraging sustainability positioning to qualify for premium OEM programs seeking circular material content.
For Investors and Strategic Acquirers: Valuations sit cheapest among recycled-content aluminum specialists with IRA-eligible domestic capacity, where earnings visibility from long-term OEM contracts supports defensive multiple expansion. Monitor magnesium extrusion qualification timelines with BMW and Mercedes-Benz platforms as the inflection signal for material share shift beyond historical corrosion limitations.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Recycling Capacity Buildout | Reclaimed carbon fiber feedstock unlocks circular qualification pathways for premium EV roof programs. |
| Magnesium Extrusion Qualification | Friction stir welding advances enable door inner applications previously blocked by corrosion risk. |
| Fast-Cure Resin Transfer Molding Scale-Up | Automated preform processing compresses carbon fiber cycle times for mid-volume EV architectures. |
| REACH-Compliant Coating Consolidation | Zirconium-based conversion coating partnerships with Henkel secure aluminum surface treatment supply. |
| IRA Corridor Capacity Expansion | Ohio and Kentucky sheet capacity additions capture domestic content credits for battery-electric platforms. |
Methodological Framework
Bottom-up electric vehicle platform modeling reconciled against top-down aluminum and carbon fiber capacity tracking forms the analytical core. Primary interviews with OEM platform engineers, Tier-1 stamper procurement directors, composite process technicians, and coating formulation specialists combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings from listed suppliers, and ECHA substance restriction notifications. Top-down triangulation against MIIT credit mandate disclosures and EPA fuel economy compliance data anchored demand-side estimates.
Historical trendline analysis across material-grade substitution patterns and platform architecture shifts informed projection modeling without year-specific anchoring. Segmentation dimensions span propulsion architecture, vehicle class, content per vehicle, material grade tier, and regional production cluster. CAGRs derived from elasticity-adjusted demand curves incorporating battery pack integration effects on load path requirements and closure mass reduction targets. Industry-specific inputs include OEM electrification platform timelines and REACH compliance phase-in schedules.
Inputs from primary fieldwork and regulatory filing databases were available through the study window; gaps in real-time OEM contract disclosure introduce uncertainty bands around supplier market share estimates. Forecasts reflect assumptions regarding magnesium alloy qualification progress and carbon fiber precursor capacity expansion timelines. Practitioners should monitor ECHA substance restriction updates and MIIT credit policy adjustments for early signals of material specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive in-Cabin Air Quality Improvement Solutions Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Mexico Automotive Sunroof Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Car Canopies Market