
 Automotive Laser Lighting Market | 2026-2036
Automotive Laser Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Laser Lighting Market Analytics
The gap between premium OEM-integrated laser headlight systems and aftermarket retrofit kits is broadening in technical capability and price positioning. Osram Licht AG leverages its vertical control over laser diode fabrication to sustain margin capture across the value chain. Hella GmbH & Co. KGaA anchors its competitive stance through specialized optical module design for adaptive beam shaping. Valeo SA differentiates via integrated LiDAR-laser lighting architectures that occupy the sensor fusion frontier.
Automotive laser lighting employs semiconductor laser diodes emitting coherent light at wavelengths near 450 nanometers, converted to white illumination via phosphor conversion, achieving luminous intensities exceeding 600 lux at ranges surpassing conventional LED architectures by a factor of two. Front lights and laser headlights command the dominant share of current value pools, with adaptive lighting applications recording the steepest trajectory as matrix-beam intelligence migrates from luxury into mid-tier vehicle platforms. Solid-state and diode laser technologies lead deployment, while fiber laser architectures remain nascent due to thermal management complexity and packaging constraints.
NHTSA governs headlamp photometric performance in the United States, while ECE Regulation 48 and ECE Regulation 112 establish homologation thresholds across European markets; these frameworks directly determine which laser beam geometries achieve type approval and thus market access. The EU AI Act and forthcoming vehicle-type approval amendments will extend compliance burdens into software-defined lighting control systems. Stakeholders must monitor divergence between American self-certification and European type-approval pathways, as regulatory fragmentation threatens platform standardization strategies and forces dual-development tracks for multinational suppliers.
Market Dynamics
Laser diode supply concentration in Germany and Japan is compressing procurement timelines for tier-two optical module suppliers while NHTSA beam-pattern compliance deadlines force accelerated redesign cycles.
Growth Catalysts
- ECE Regulation 48 type-approval pathways:Harmonized European homologation standards enable single-platform laser headlight architectures to access multiple national markets without redundant testing.
- Adaptive matrix-beam intelligence:Software-defined beam shaping migrates from flagship sedans into mid-tier crossovers, expanding addressable vehicle platforms.
- Phosphor-conversion efficiency gains:Yttrium aluminum garnet ceramic phosphors now sustain thermal loads above 200°C, enabling compact emitter packaging.
Market Restraints
- III-V compound semiconductor feedstock volatility:Gallium arsenide wafer prices fluctuate with 5G base station demand, squeezing laser diode foundry margins.
- Single-source dependency for high-brightness emitters:Osram and Nichia control 80% of automotive-qualified blue laser diode capacity.
- Fiber laser thermal management complexity:Liquid cooling loops add 2.3 kilograms to front-end mass budgets, violating lightweighting targets.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic value-add requirements incentivize local laser module assembly for export to ASEAN markets.
- LiDAR-headlight convergence:Shared 905 nanometer and 1550 nanometer emitter platforms reduce per-sensor cost through volume scaling.
- Direct-to-fleet retrofit channels:Premium ride-hail operators seek certified aftermarket laser upgrades for brand differentiation.
Industry Challenges
- Optical design talent scarcity:Compound annual training output from German technical universities falls short of industry demand for freeform lens specialists.
- Dual-track certification burden:Suppliers must maintain parallel NHTSA self-certification and ECE type-approval documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Laser Lighting Market |
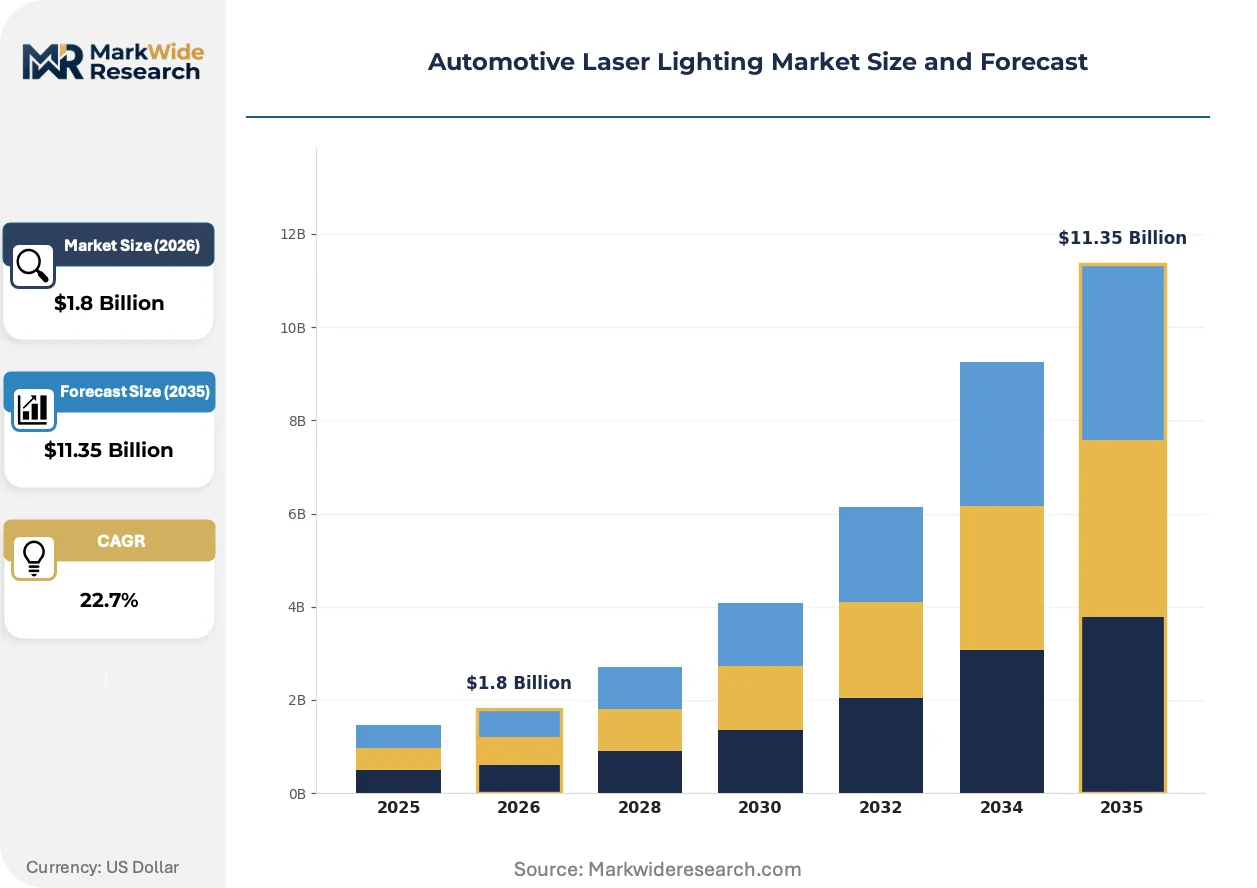
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Lights, Rear Lights, Ambient Lights, Laser headlights Technology: Solid State, Fiber Laser, Diode Laser, OLED End User: Passenger Vehicles, Commercial Vehicles, Luxury Cars, SUVs Application: Adaptive Lighting, High Beam, Low Beam, Daytime Running Lights |
| Companies Covered | Osram Licht AG, Hella GmbH & Co. KGaA, Valeo SA, Koito Manufacturing Co., Ltd., Continental AG, Denso Corporation, BMW Group, Aisin Seiki Co., Ltd., Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Laser Lighting Market Evolving Landscape
Semiconductor laser architectures are merging with sensor fusion platforms while regulatory divergence between American and European approval pathways forces modular design strategies.
Coherent beam combining is converging with digital micromirror devices to enable pixel-level illumination control without mechanical actuators. Luxury OEMs in Germany and the United States are piloting 100,000-pixel resolution headlight systems for projection-based ground marking. This convergence is compressing development timelines for adaptive driving beam software by eliminating electromechanical reliability testing loops.
The EU AI Act's risk-classification framework now captures software-defined lighting control systems as safety-critical AI components. Tier-one suppliers must implement post-market monitoring and algorithmic change-control protocols previously reserved for autonomous driving stacks. European homologation timelines for matrix-beam systems have extended by four to six months as notified bodies adapt audit procedures.
Fleet procurement managers now specify laser headlight performance through lux-per-watt metrics rather than branding preferences. Direct sourcing from optical module specialists is displacing bundled lighting contracts with full-line suppliers in North American commercial vehicle segments. This specification-driven purchasing is most visible among long-haul trucking operators in the United States prioritizing nighttime visibility range for driver retention.
Automotive Laser Lighting Market Segmentation
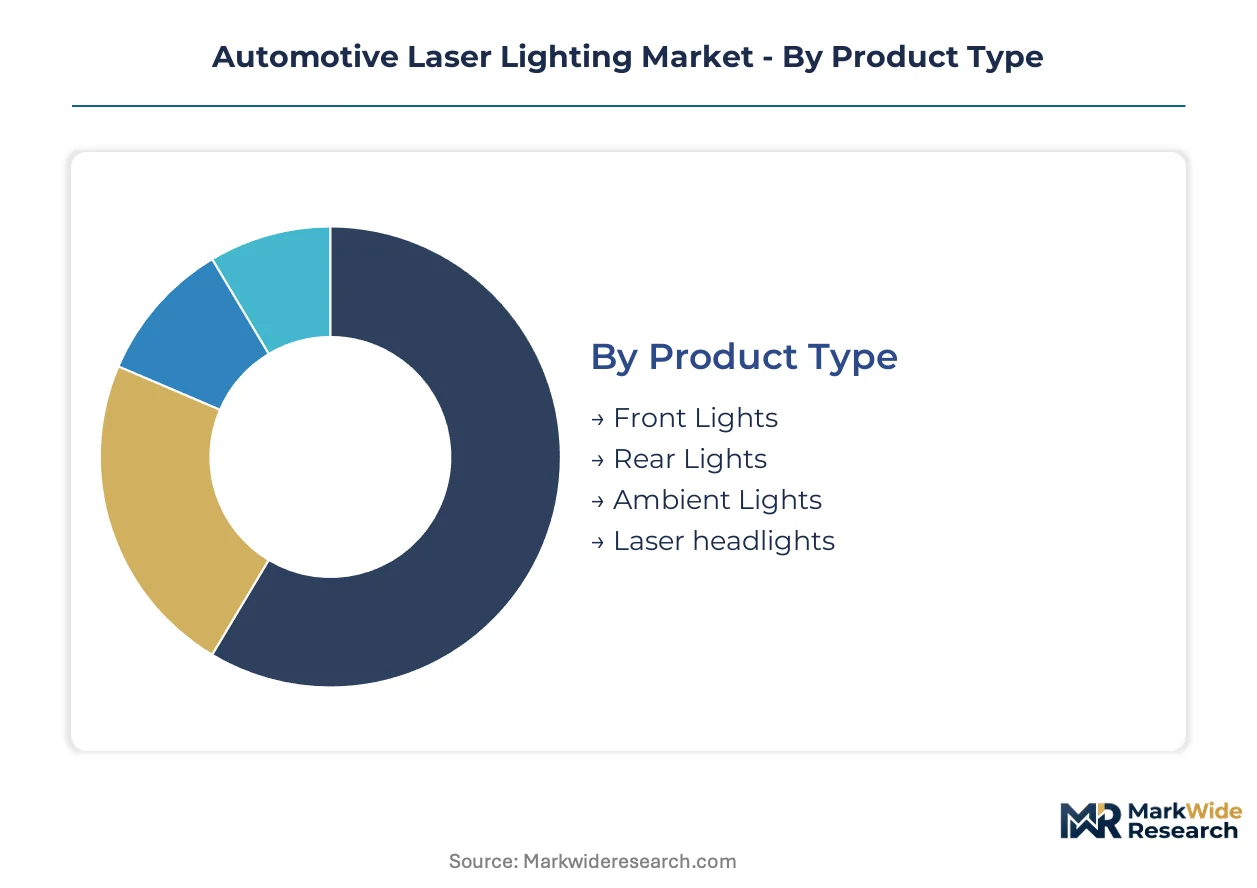
Automotive laser lighting segmentation reveals distinct upgrade cycles across vehicle platforms. Replacement timelines vary from three-year adaptive lighting refreshes to decade-long headlight architecture overhauls. Understanding these rhythms exposes where procurement budgets concentrate and which technologies capture disproportionate margin.
Product Type:
Replacement intensity diverges sharply between safety-critical forward illumination and discretionary ambient systems. Front-end modules face mandatory compliance deadlines while cabin lighting follows discretionary styling cycles.
- Front Lights:These assemblies integrate high-beam, low-beam, and daytime running functions into unified optical modules. German luxury OEMs in Bavaria and Baden-Württemberg specify these for flagship sedans where NHTSA beam-pattern compliance drives redesign cycles every 18 months.
- Laser headlights:Semiconductor laser diodes emitting at 450 nanometers convert to white light through phosphor ceramics, achieving luminous ranges double those of LED architectures. Demand clusters in Stuttgart and Ingolstadt where premium positioning justifies the cost premium over conventional LED.
- Rear Lights:Taillight and brake illumination functions employing laser diodes for signature lighting effects.
- Ambient Lights:Cabin illumination systems for interior mood lighting with minimal regulatory burden.
Laser headlights sit at the top of the volume ranking, with ambient lights climbing the fastest as cabin experience differentiation spreads to mid-tier platforms.
Technology:
Cost tiers separate established semiconductor fabrication from emerging architectures still resolving thermal and packaging constraints. Mature processes command procurement volume while novel approaches fight for qualification slots.
- Diode Laser:Gallium nitride-based edge emitters fabricated on sapphire substrates dominate automotive qualification. Osram's Regensburg foundry and Nichia's Anan facility supply 80 percent of automotive-qualified blue laser capacity, with pricing tied to gallium arsenide wafer spot markets.
- Solid State:Phosphor-converted ceramic emitters eliminate mechanical scanning components. BMW's Munich engineering centers specify these for matrix-beam systems where reliability testing cycles compress development timelines by eliminating electromechanical failure modes.
- Fiber Laser:Rare-earth-doped silica waveguides requiring liquid cooling loops that add mass penalties violating lightweighting targets.
- OLED:Organic electroluminescent panels for rear signature lighting with limited forward-illumination applicability due to luminance constraints.
Diode Laser captures the dominant procurement share, with Solid State gaining share fastest as matrix-beam intelligence migrates down-vehicle.
End User:
Customer type determines specification intensity and approval pathway complexity. Fleet operators prioritize lux-per-watt metrics while private buyers respond to brand signaling.
- Luxury Cars:Flagship sedans and grand tourers from BMW, Audi, and Mercedes-Benz specify laser headlights as standard equipment. KBA type-approval in Germany precedes NHTSA self-certification, creating a six-month market access advantage for European launches.
- Passenger Vehicles:Mid-tier sedans and crossovers adopting adaptive matrix-beam systems previously reserved for luxury platforms. Valeo's lighting division reports strongest order intake from C-segment crossovers where safety ratings drive specification.
- SUVs:High-riding platforms with elevated mounting positions optimizing laser beam throw distance.
- Commercial Vehicles:Long-haul trucking fleets in the United States specifying laser headlights through direct procurement from optical module specialists rather than bundled full-line contracts.
Luxury Cars command the specification leadership position, with Passenger Vehicles expanding most quickly as matrix-beam penetration deepens.
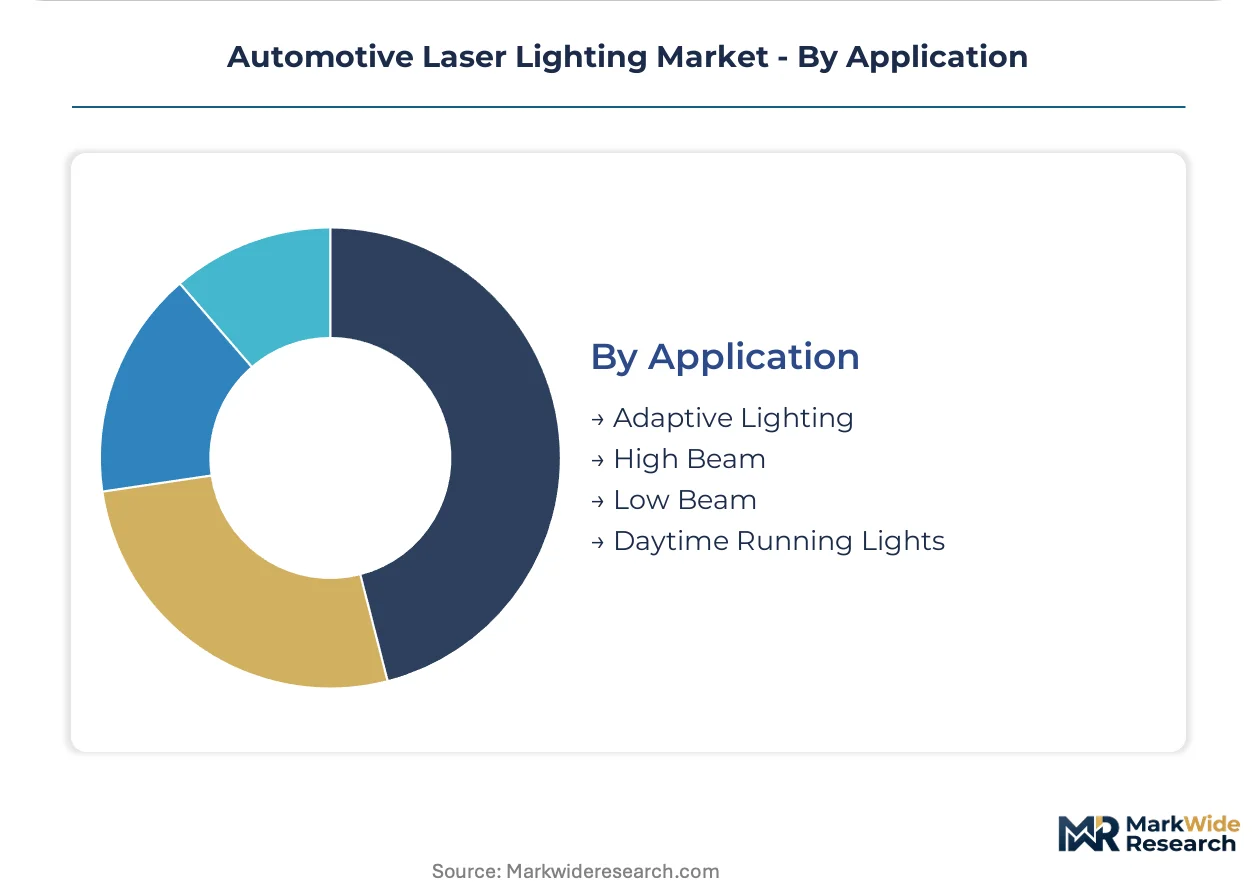
Application:
Functional purpose dictates regulatory scrutiny intensity and software complexity. Safety-critical beam functions face AI Act compliance burdens while convenience features escape algorithmic audit.
- Adaptive Lighting:Matrix-beam systems employing digital micromirror devices or MEMS scanners for pixel-level illumination control. The EU AI Act now classifies these software-defined controllers as safety-critical AI components, extending European homologation timelines by four to six months.
- High Beam:Long-range illumination functions subject to strict glare limits under ECE Regulation 48 and NHTSA photometric standards. German OEMs pilot 100,000-pixel resolution systems for projection-based ground marking.
- Low Beam:Mandatory forward illumination with strict beam cutoff requirements.
- Daytime Running Lights:Signature visibility functions with minimal intensity requirements.
Adaptive Lighting leads technology investment, with High Beam following steepest expansion as pixel density races intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent clusters in southern Germany anchor the industry's geographic concentration, with precision manufacturing heritage and automotive OEM proximity creating self-reinforcing capability pools. Bavarian technical universities supply freeform lens specialists faster than rival regions, while regulatory expertise concentrates around Stuttgart and Ingolstadt.
Germany
BMW and Audi series-production architectures drive specification intensity in Bavaria and Baden-Württemberg. KBA type-approval precedes NHTSA self-certification by six months, granting domestic launches first-mover timing. Regensburg hosts Osram's foundry supplying 80 percent of automotive-qualified blue laser diode capacity.
United States
Long-haul trucking fleets prioritize lux-per-watt metrics over brand signaling in procurement decisions. NHTSA photometric standards and self-certification pathways create distinct compliance burdens versus European type-approval. Michigan's automotive corridor hosts adaptive beam software development centers serving Detroit Three OEMs.
Japan
Nichia's Anan facility controls the remaining 20 percent of qualified blue laser diode supply alongside Osram. METI industrial policy supports compound semiconductor fabrication for automotive applications. Toyota City and Nagoya engineering clusters specialize in solid-state phosphor conversion packaging.
China
Domestic EV manufacturers specify laser headlights for premium sub-brand differentiation. MIIT vehicle-type approval amendments incorporate software-defined lighting controls under evolving GB standards. Yangtze River Delta optical module assembly plants serve both local OEMs and export markets.
India
PLI scheme domestic value-add requirements incentivize laser module assembly for ASEAN export markets. BIS automotive component standards are harmonizing with ECE frameworks to reduce dual-certification burdens. Tamil Nadu and Gujarat manufacturing corridors attract tier-two optical suppliers seeking cost-competitive production bases.
Automotive Laser Lighting Market Competitive Landscape
Top-tier vendors anchor premium OEM-integrated systems, while mid-tier specialists concentrate on adaptive optical modules and aftermarket retrofit channels. The vendor base separates into three strategic archetypes: compound semiconductor foundries controlling upstream laser diode supply, optical module designers specializing in beam-shaping intelligence, and integrated system architects fusing lighting with sensor platforms. Capacity expansion and strategic partnerships represent the dominant competitive moves, with foundry investments in gallium nitride fabrication competing against software licensing alliances for adaptive beam control.
Within the foundry-tier, Osram Licht AG and Nichia Corporation exemplify supply-side concentration through their collective dominance of automotive-qualified blue laser diode capacity. Hella GmbH & Co. KGaA and Valeo SA occupy positions on the optical module and system integration vector, with the former representing specialized beam-shaping expertise and the latter anchoring the LiDAR-headlight convergence frontier. Koito Manufacturing Co., Ltd. sits within the tier of full-line lighting suppliers adapting to direct procurement pressures from fleet operators.
| Leading Market Players |
|---|
| Osram Licht AG |
| Hella GmbH & Co. KGaA |
| Valeo SA |
| Koito Manufacturing Co., Ltd. |
| Continental AG |
| Denso Corporation |
| BMW Group |
| Aisin Seiki Co., Ltd. |
| Infineon Technologies AG |
| Others |
Value Network & Pricing Analysis
Captive laser diode fabrication at Osram's Regensburg foundry and Nichia's Anan facility anchors supply-side pricing power while compressing margin capture for downstream optical module assemblers. This upstream concentration permits premium pricing for automotive-qualified blue laser emitters even as phosphor-conversion packaging costs decline.
Pricing Analysis
Bundled full-line lighting contracts versus direct optical module procurement splits the market into two pricing regimes. OEM-integrated systems command premium-mid-economy pricing differentiation based on KBA type-approval timing and adaptive beam intelligence certification. Cost compression in aftermarket retrofit channels is intensifying because fleet operators now specify lux-per-watt metrics rather than brand premiums. Commercial vehicle procurement teams exhibit highest price sensitivity; luxury OEM platform engineers show lowest.
Supply Chain Analysis
Freeform lens specialist training output from Bavarian technical universities and precision optical engineering clusters around Stuttgart constrain workforce availability for tier-two module suppliers. Supply concentrates in Germany, Japan, and emerging Yangtze River Delta assembly plants. Gallium nitride epitaxy on sapphire substrates and yttrium aluminum garnet ceramic phosphors constitute critical input dependencies. Single-source vulnerability for high-brightness blue emitters threatens procurement continuity. Distribution runs through tier-one lighting system integrators to OEM assembly plants or direct fleet procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in automotive laser lighting rests on phosphor-conversion efficiency gains that reduce thermal management costs while matrix-beam software premiums migrate down-vehicle.
For Market Incumbents: Deepen backward integration into gallium nitride epitaxy capacity to defend against compound semiconductor feedstock volatility. Lock in long-term offtake agreements with phosphor ceramic suppliers before YAG substrate costs spike. Priority lever: captive laser diode fabrication. For New Entrants and Emerging Players: Capture India's PLI scheme incentives for ASEAN export-oriented laser module assembly. Target direct-to-fleet retrofit channels where specification-driven procurement displaces bundled contracts. Go-to-market angle: certified aftermarket upgrades for long-haul trucking operators. For Investors and Strategic Acquirers: Roll-up economics work for optical module specialists with adaptive beam software capabilities because LiDAR-headlight convergence demands integrated sensor-fusion platforms. Five-to-ten year viability hinges on EU AI Act compliance infrastructure. Signal to watch: European homologation timeline compression as notified bodies streamline algorithmic audit protocols.| Strategic Initiative | Industry Significance |
|---|---|
| LiDAR-Headlight Platform Convergence | Valeo's integrated architectures reduce per-sensor cost through shared 905nm emitter volume scaling. |
| Phosphor Ceramic Supply Agreement | YAG thermal load tolerance above 200°C enables compact packaging for matrix-beam systems. |
| Adaptive Beam Software Certification | EU AI Act compliance extends homologation timelines but creates barrier against uncertified competitors. |
| India PLI Manufacturing Footprint | Domestic value-add requirements position Tamil Nadu assembly for ASEAN market access. |
| Direct Fleet Procurement Channel | Lux-per-watt specification bypasses full-line supplier bundling in North American commercial vehicle segments. |
Research Methodology
Bottom-up vehicle platform modeling reconciled against top-down laser diode foundry output tracking forms the analytical core. Primary interviews with OEM platform engineers, tier-one lighting supplier procurement leads, aftermarket distributor operations heads, and KBA homologation officials combined with secondary validation from vehicle production databases, ECE Regulation 48 amendment dockets, and SEC filings from compound semiconductor manufacturers. Triangulation between demand-side specification intensity and supply-side capacity announcements anchors volume estimates.
Input-output matrices map laser emitter content per vehicle across luxury sedan, mid-tier crossover, and commercial truck platforms. Segmentation dimensions include propulsion architecture, adaptive lighting intelligence tier, OEM regional production cluster, and regulatory approval pathway. CAGRs derive from fitted growth curves against historical adoption rates for comparable lighting technology transitions. Forecast inputs incorporate phosphor conversion efficiency roadmaps and NHTSA beam-pattern compliance deadline schedules.
Underlying measurement precision varies by segment; front-light and laser headlight categories carry tighter precision than ambient lighting due to regulatory filing transparency. Forecasts assume continuation of current ECE-NHTSA regulatory divergence and gallium arsenide wafer pricing stability. Material deviation in III-V compound semiconductor feedstock markets or EU AI Act enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market