
 Automotive Decorative Interior Trim Market | 2026-2036
Automotive Decorative Interior Trim Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Decorative Interior Trim Market Outlook
Asset-light leasing models for injection-molding equipment are reshaping competitive entry in automotive decorative interior trim, allowing mid-scale suppliers to bid on OEM programs without capital-heavy tool ownership. Yanfeng Automotive Interiors leverages this flexibility to sustain capacity across multiple vehicle platforms. Toyota Boshoku Corporation anchors its position through captive supply relationships with Toyota Motor's global assembly network. Lear Corporation differentiates via vertical integration into leather finishing and cut-and-sew operations for premium seating surrounds.
Automotive decorative interior trim encompasses surface-finished components applied to instrument panels, door panels, center consoles, and pillar garnishes, typically manufactured through injection molding, vacuum forming, or CNC machining of substrates including ABS, polypropylene, wood veneer, and aluminum alloy, serving both aesthetic differentiation and tactile quality functions in vehicle cabins. Plastic trim dominates volume manufacturing due to cost-efficient injection molding scalability across mass-market vehicle programs. Leather segments command concentrated margin pools in luxury and performance design styles, where hand-stitched finishes justify substantial material premiums. Modern and sporty design styles are gaining fastest in electric vehicle architectures, where minimalist interiors and ambient lighting integration redefine trim surface requirements.
FDA guidelines on indirect food contact materials influence trim adhesives and coatings used in cabin environments, while EPA regulations on volatile organic compound emissions shape solvent-based finishing processes in US manufacturing facilities. ECHA's REACH restrictions on chromium VI in leather tanning directly impact European supplier compliance costs for luxury trim components. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions to anticipate reformulation investments and qualify alternative coating chemistries ahead of regulatory enforcement timelines.
Market Dynamics
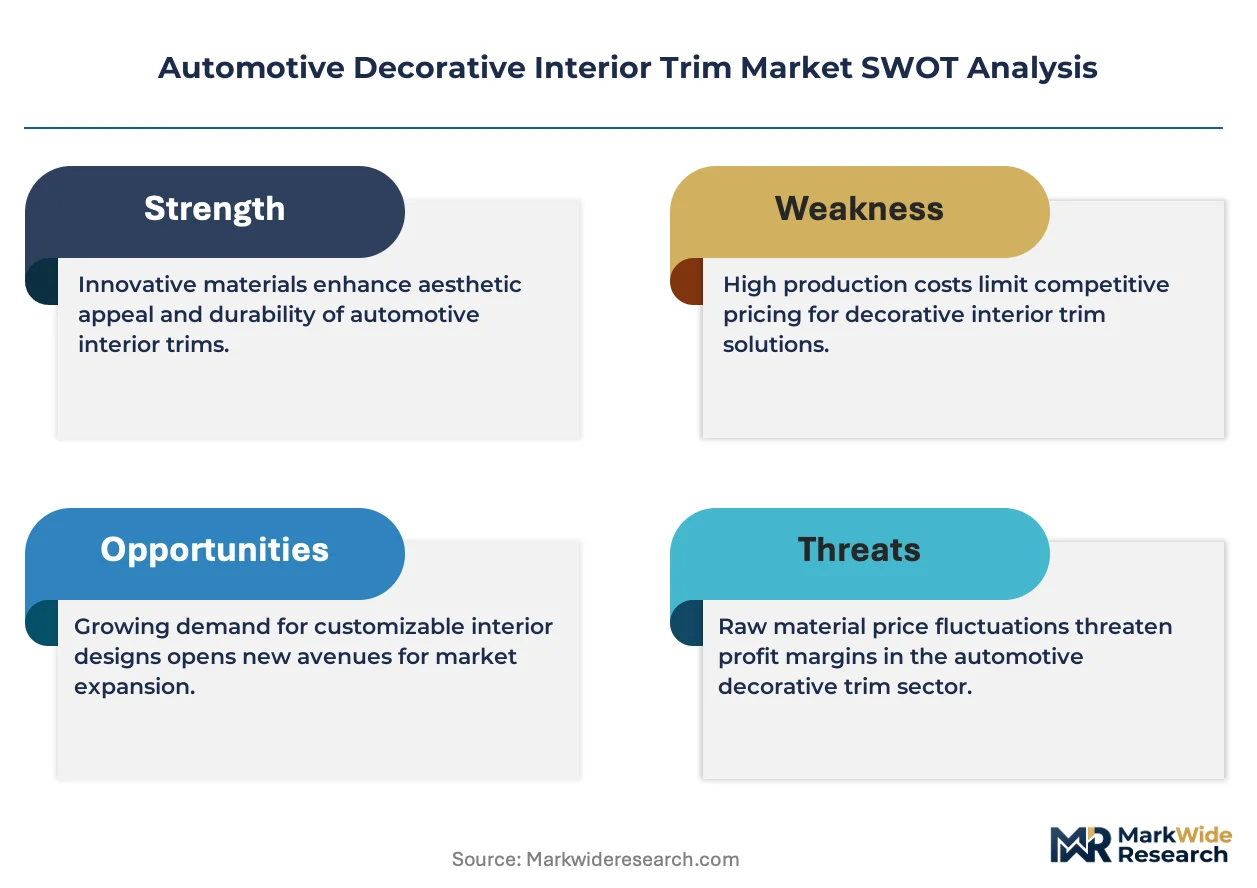
Luxury OEMs are weaponizing interior customization as a margin defense against electric vehicle price compression, forcing tier-one suppliers to retool for batch-size-one manufacturing flexibility without sacrificing throughput economics.
Growth Catalysts
- REACH chemical restrictions:Europe's phased chromium VI ban in leather tanning is accelerating supplier migration to vegetable-based alternatives, opening premium positioning for compliant finishers.
- Electric vehicle architectures:Flat-floor battery platforms enable expanded cabin surface areas requiring new trim geometries, multiplying component counts per vehicle.
- Stuttgart-Munich R&D corridor:Germany's concentrated supplier engineering clusters are shortening development cycles for bio-based coating formulations.
Market Restraints
- Petrochemical feedstock volatility:ABS and polypropylene resin prices swing with crude oil indices, compressing margins on fixed-price OEM contracts.
- Tooling capital intensity:Injection mold fabrication for complex grain-matched surfaces requires six-figure investments that freeze supplier liquidity.
- Aluminum alloy substitution:Cold-rolled steel trim substrates in commercial vehicle segments threaten plastic volume in price-sensitive applications.
Strategic Opportunities
- India's PLI scheme for auto components:Component-level incentives are attracting trim suppliers to establish finishing operations near Chennai and Pune assembly plants.
- Ambient lighting integration:Convergence of LED micro-arrays with translucent polycarbonate surfaces creates new premium tier definitions.
- Post-consumer recycled content mandates:OEM sustainability scorecards are generating qualified demand for recycled ABS with validated chain-of-custody documentation.
Industry Challenges
- Surface finishing technician scarcity:Vacuum metallization and physical vapor deposition operations require specialized operators with limited training pipeline availability.
- Dual-chemistry qualification timelines:Suppliers must validate both solvent-based and waterborne coating systems in parallel to hedge regulatory uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Decorative Interior Trim Market |
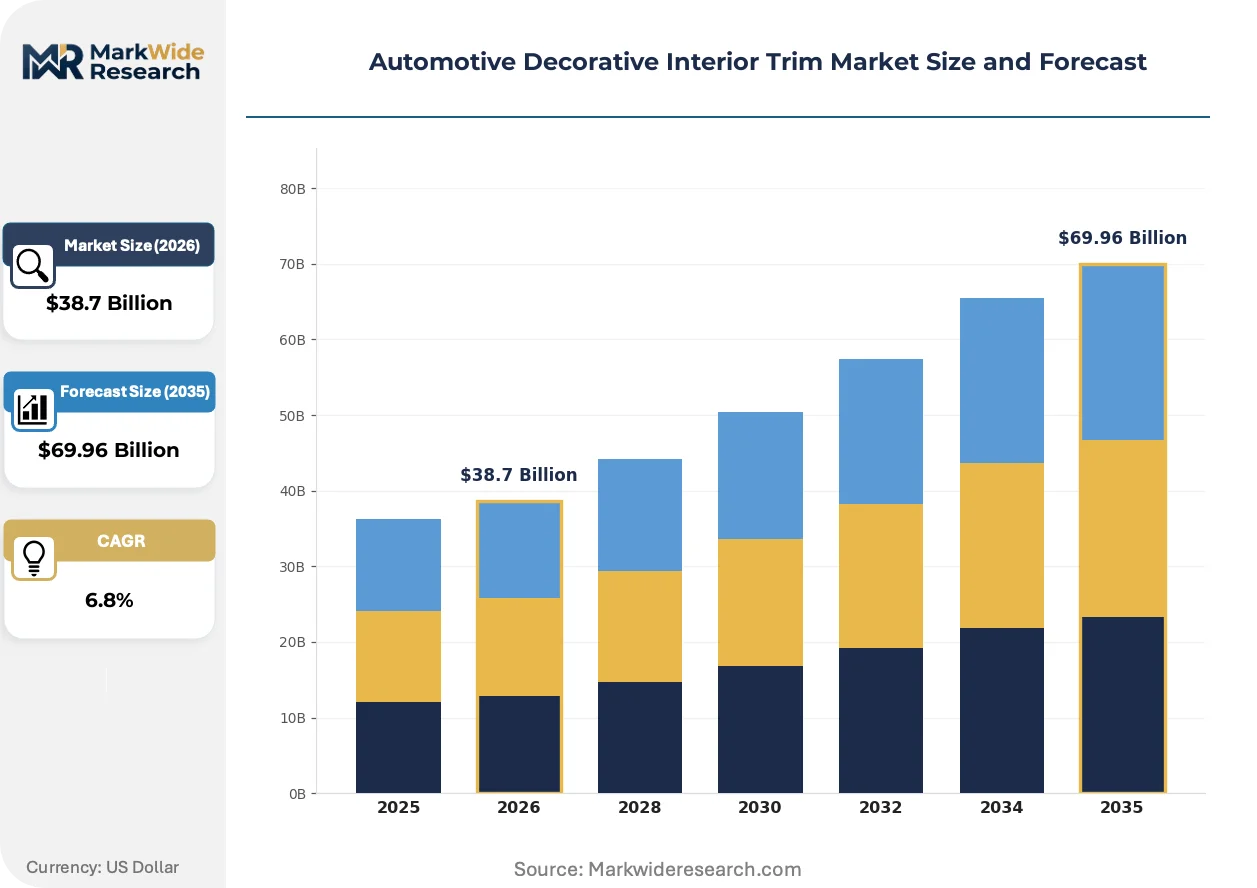
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Wood, Leather, Metal End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Process: Injection Molding, Vacuum Forming, CNC Machining, 3D Printing Design Style: Traditional, Modern, Sporty, Luxurious |
| Companies Covered | Magna International, Grupo Antolin, Yanfeng Automotive Interiors, Toyota Boshoku Corporation, International Automotive Components Group, Faurecia, Lear Corporation, Visteon Corporation, Adient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Decorative Interior Trim Market Strategic Shifts
Surface engineering is bifurcating between tactile authenticity and digital integration, with material scientists racing to reconcile haptic warmth with embedded sensor functionality.
Natural fiber-reinforced polypropylene is hybridizing conventional plastic trim with flax and hemp composites to reduce weight while preserving injection molding process compatibility. Premium German OEMs are adopting these substrates for visible door panel inserts. The technology is hybridizing supply chains by forcing compounders to source agricultural byproducts alongside petrochemical feedstocks.
EPA volatile organic compound emission limits for surface coating operations are compelling US manufacturing facilities to convert solvent-based spray lines to waterborne or powder systems. Compliance investments average three to four years for full line replacement. Tier-one suppliers serving Detroit Three OEMs are consolidating finishing operations into fewer, larger facilities to amortize abatement equipment costs.
Fleet procurement departments are consolidating interior trim specifications across multiple vehicle nameplates to leverage volume pricing and reduce supplier management overhead. Standardized grain patterns and color palettes are displacing model-specific designs in rental and commercial vehicle channels. This concentration is most pronounced in US full-size pickup segments where fleet sales exceed forty percent of volume.
Automotive Decorative Interior Trim Market Segmentation
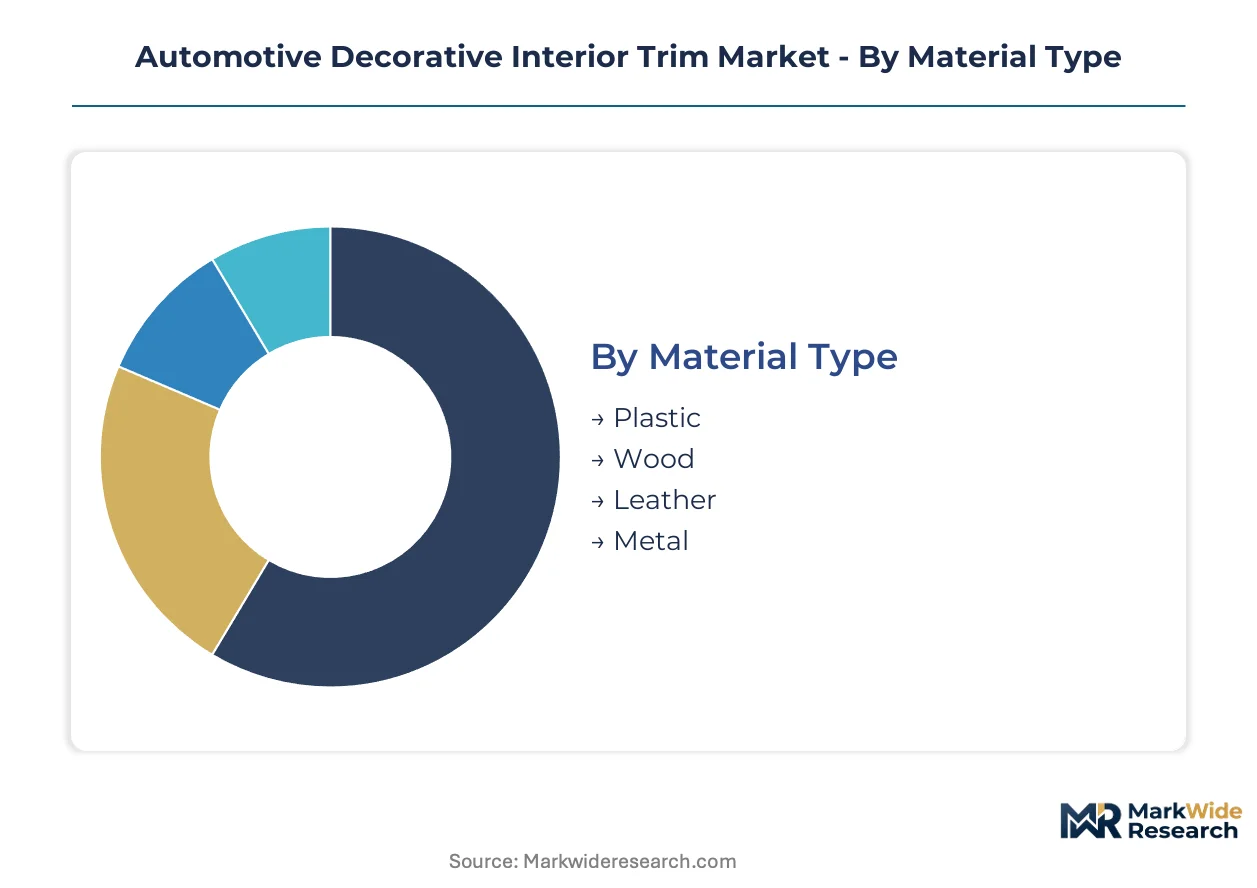
Trim material selection dictates aftermarket service intervals, warranty exposure, and refurbishment economics across vehicle lifecycles. Component durability directly influences dealer parts revenue and collision repair channel profitability. Understanding segment-level replacement patterns enables suppliers to calibrate inventory depth and pricing power.
Material Type:
After-sales service intensity varies sharply by substrate, with leather requiring specialized reconditioning protocols and plastic dominating high-frequency replacement cycles.
- Plastic:ABS and polypropylene formulations enable cost-efficient injection molding at mass-market scale. Demand concentrates in German compact and mid-size vehicle programs where Stuttgart-based compounders supply OEM-approved color-matched resins with validated low-VOC emissions under REACH protocols.
- Leather:Full-grain and corrected-grain hides undergo chromium-free tanning to meet ECHA restrictions, with hand-stitched finishes commanding substantial material premiums. Italian and German luxury OEMs anchor demand clusters, where vegetable-tanned alternatives justify compliance-driven price positioning.
- Wood:Veneer and open-pore finishes serve heritage luxury nameplates with limited production volumes.
- Metal:Brushed aluminum and cold-rolled steel substrates address commercial vehicle durability requirements with lower service intensity.
Plastic holds the largest share; momentum sits with leather as regulatory compliance reshapes premium sourcing.
End User:
Customer type determines contract structure, with captive supply relationships offering volume certainty and aftermarket channels delivering margin expansion.
- OEMs:Original equipment manufacturers specify trim grades during vehicle development, locking suppliers into multi-year program commitments with tool amortization schedules. German and Japanese OEMs maintain the most stringent surface quality specifications.
- Aftermarket Providers:Independent distributors and collision repair networks source replacement trim for vehicle refurbishment, with demand tracking regional fleet age profiles. North American channels show particular concentration in pickup truck interior refurbishment.
- Tier-1 Suppliers:Integrated seating and cockpit module manufacturers procure trim components for assembly into higher-level systems.
- Vehicle Assemblers:Contract manufacturers and regional assembly plants source trim for localized production programs.
OEMs dominate volume; aftermarket providers are expanding most quickly as average vehicle age extends replacement demand.
Manufacturing Process:
Process selection governs capital intensity, with injection molding requiring substantial upfront tooling investment and additive methods enabling design iteration.
- Injection Molding:High-pressure resin injection into precision-machined tools produces grain-matched surfaces with repeatable tolerances. Tooling investments freeze supplier liquidity for mass-market programs.
- Vacuum Forming:Heated sheet thermoforming suits lower-volume applications with reduced tooling costs.
- CNC Machining:Subtractive manufacturing of aluminum and wood substrates delivers precision for low-volume luxury applications.
- 3D Printing:Fused deposition modeling and selective laser sintering enable rapid prototyping and batch-size-one customization for premium personalization programs.
Injection molding commands volume leadership; 3D printing is gaining share fastest in electric vehicle personalization services.
Design Style:
Aesthetic positioning correlates with material specification intensity and surface finishing complexity.
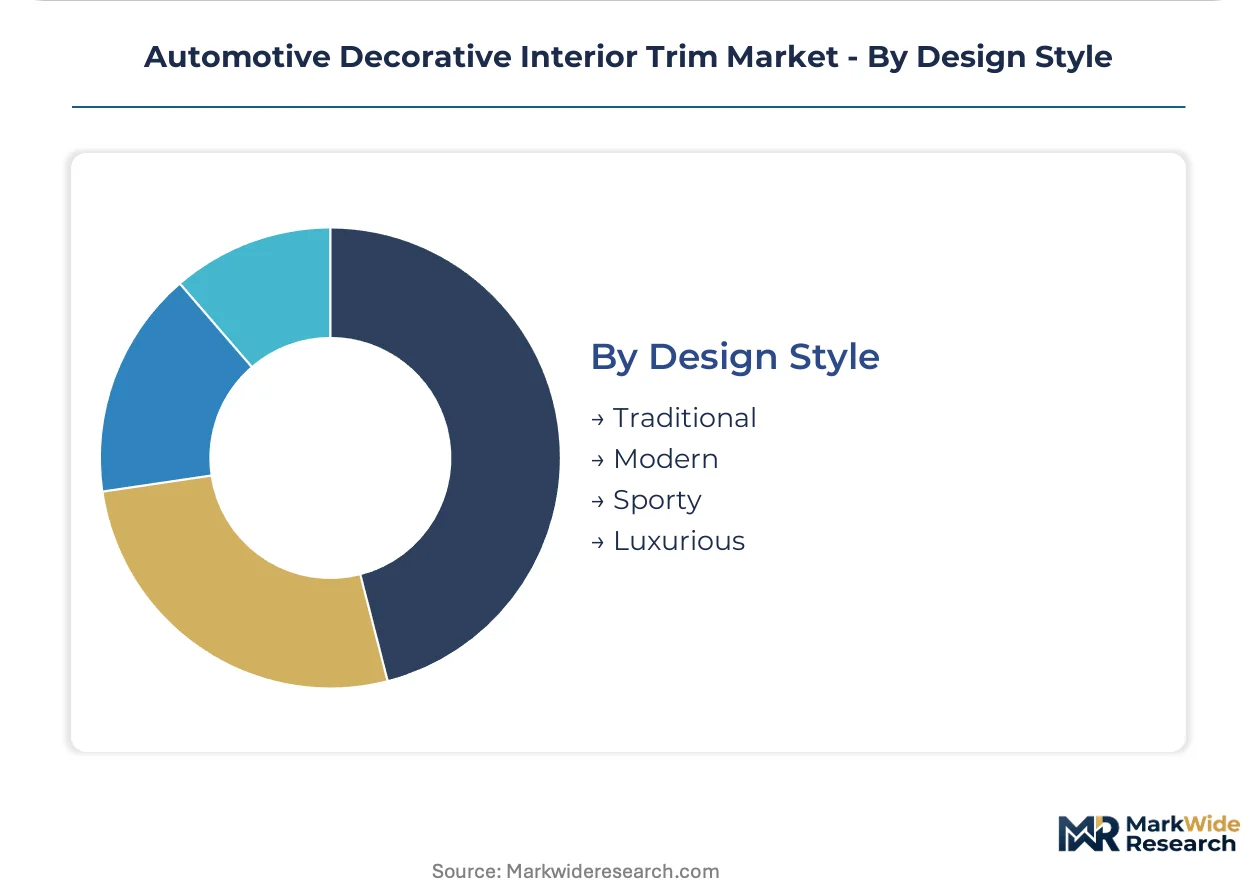
- Modern:Minimalist surfaces with integrated ambient lighting and concealed controls dominate electric vehicle architectures. Flat-floor battery platforms multiply component counts per cabin.
- Luxurious:Multi-material layering with hand-finished details and bespoke color-matching serves ultra-premium nameplates. Vegetable-tanned leather and open-pore wood define tactile authenticity.
- Traditional:Classic grain patterns and chrome accents persist in heritage nameplates with established customer expectations.
- Sporty:Carbon-fiber-look finishes, contrast stitching, and metallic accents target performance-oriented segments.
Luxurious maintains margin leadership; modern is climbing the fastest as electric vehicle production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automotive decorative interior trim tilt toward net manufacturing surplus in Germany and China, while the United States and Japan balance trade through technology licensing rather than physical component flows. Currency volatility and resin feedstock costs reshape regional competitiveness quarterly.
Germany
Stuttgart and Munich anchor Europe's densest supplier engineering clusters for sustainable interior finishes. ECHA's REACH restrictions on chromium VI in leather tanning accelerate migration to vegetable-based alternatives among Swabian tanneries. Bavarian compounders supply OEM-approved color-matched resins with validated low-VOC emissions to premium vehicle programs.
United States
Detroit Three OEM procurement consolidation drives standardized grain patterns across full-size pickup and fleet vehicle interiors. EPA volatile organic compound emission limits compel solvent-to-waterborne coating line conversions averaging three to four years. Southeast assembly corridors near Tennessee and Kentucky attract finishing operations seeking regulatory amortization scale.
China
Flat-floor battery electric vehicle architectures multiply cabin surface areas and component counts per vehicle. MIIT guidelines on new energy vehicle interior material safety influence supplier qualification protocols. Yangtze River Delta manufacturing zones concentrate injection-molding capacity for both domestic OEMs and export programs.
Japan
Captive supply relationships between interior specialists and Toyota Motor's global assembly network preserve program volume certainty. METI industrial standards on automotive interior air quality shape adhesive and coating specifications. Nagoya-area engineering centers prototype next-generation bio-based substrate formulations for premium nameplates.
India
Component-level PLI scheme incentives attract trim suppliers to establish finishing operations near Chennai and Pune assembly plants. BIS certification requirements for automotive interior materials extend qualification timelines for new market entrants. Tamil Nadu's automotive supplier parks concentrate vacuum-forming capacity for compact vehicle programs.
Automotive Decorative Interior Trim Market Competitive Environment
On the supply side, the industry is tiered between scale-driven injection-molding specialists and premium finishing houses serving luxury nameplates. Consolidation pressure concentrates among mid-scale suppliers lacking captive OEM relationships or backward integration into resin compounding. Three archetypes dominate: asset-light equipment leasers, vertically integrated seating module producers, and regional captive suppliers tethered to single OEM networks. Competitive moves center on M&A for coating technology access and geographic expansion into PLI-subsidized manufacturing zones.
Within the captive supply tier, Toyota Boshoku Corporation exemplifies the Japanese keiretsu model through exclusive program relationships. Yanfeng Automotive Interiors occupies a position as the dominant China-based specialist leveraging asset-light leasing flexibility across multiple platforms. Lear Corporation anchors the premium leather-finishing vector through in-house production of cut-and-sew seating surrounds.
| Leading Market Players |
|---|
| Magna International |
| Grupo Antolin |
| Yanfeng Automotive Interiors |
| Toyota Boshoku Corporation |
| International Automotive Components Group |
| Faurecia |
| Lear Corporation |
| Visteon Corporation |
| Adient |
| Others |
Value Chain & Pricing Dynamics
German compounder concentration around Stuttgart and Munich feeds directly into premium leather-finishing margin pools, where vegetable-tanned compliance premiums offset REACH-driven cost inflation downstream.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with multi-year tool amortization schedules. Pricing stratifies across premium hand-stitched leather, standard injection-molded ABS, and economy vacuum-formed polypropylene tiers. Cost compression in mass-market plastic trim is intensifying because petrochemical resin volatility outpaces contract renegotiation cycles. Fleet procurement departments exhibit highest price sensitivity; luxury OEM platform engineering teams show lowest.
Supply Chain Analysis
Export-control restrictions on physical vapor deposition equipment limit technology transfer to emerging finishing operations. Supply concentrates in Germany, China, and Japan for injection-molding tools and coating formulations. Raw material flows draw from ABS resin producers, chromium-free tanning chemical suppliers, and LED micro-array component manufacturers. Single-source vulnerability sits with precision mold-fabrication houses. Distribution runs through captive OEM supply relationships and Tier 1 module assembly networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment moat: REACH compliance investments and OEM qualification timelines create switching costs that freeze out unqualified competitors.
For Market Incumbents: Build certification moats through dual-chemistry coating qualifications that anticipate ECHA enforcement timelines. Deepen backward integration into resin compounding to hedge petrochemical feedstock volatility. Consolidate finishing operations into fewer facilities to amortize EPA abatement equipment costs against aluminum alloy substitution threats. For New Entrants and Emerging Players: Build out asset-light equipment leasing capabilities to bid on OEM programs without six-figure tooling capital. Target India's PLI-subsidized manufacturing zones near Chennai assembly corridors. Pursue aftermarket refurbishment channels where fleet age extension multiplies replacement trim demand. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across waterborne coating line conversions. Long-term viability favors suppliers with validated chain-of-custody documentation for post-consumer recycled content mandates. Acquisition focus: mid-scale finishers lacking captive OEM relationships. Signal to watch: MIIT guidelines tightening on new energy vehicle interior material safety.| Strategic Initiative | Industry Significance |
|---|---|
| Vegetable-Tanning Capacity Expansion | Swabian tanneries capture REACH-compliant premium positioning ahead of chromium VI phaseout. |
| Recycled ABS Supply Agreement | OEM sustainability scorecards generate qualified demand with validated chain-of-custody documentation. |
| Ambient Lighting Module Integration | LED micro-array convergence with polycarbonate surfaces creates new premium tier definitions. |
| PLI Zone Manufacturing Footprint | Chennai and Pune assembly proximity reduces logistics costs for Indian compact vehicle programs. |
| Bio-Based Coating Joint Venture | Bavarian R&D clusters shorten development cycles for next-generation sustainable interior finishes. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs. Stakeholder roles included OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution managers, surface finishing technicians, and leather tanning operations heads. Secondary validation drew from vehicle production databases, IHS Markit registration data, ECHA substance restriction notifications, and SEC filings of listed suppliers. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Calibration anchored volume and value outputs to observed program commitments and tool amortization schedules across the projection horizon. Segmentation dimensions modeled included material type, manufacturing process, design style, end-user category, and regional production cluster. CAGRs derived from trend extrapolation of injection-molding capacity expansion, electric vehicle architecture penetration, and regulatory compliance investment cycles. Industry-specific inputs incorporated REACH chemical restriction timelines and MIIT new energy vehicle guidelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light equipment leasers or PLI-subsidized entrants would shift outcomes. Material shifts in ECHA enforcement timelines or EPA emission limit stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Fog Free Mirrors Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Global Automotive Rear Window Blinds Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market