
 Electric Loader Rickshaw Market | 2026-2036
Electric Loader Rickshaw Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Loader Rickshaw Market Analysis
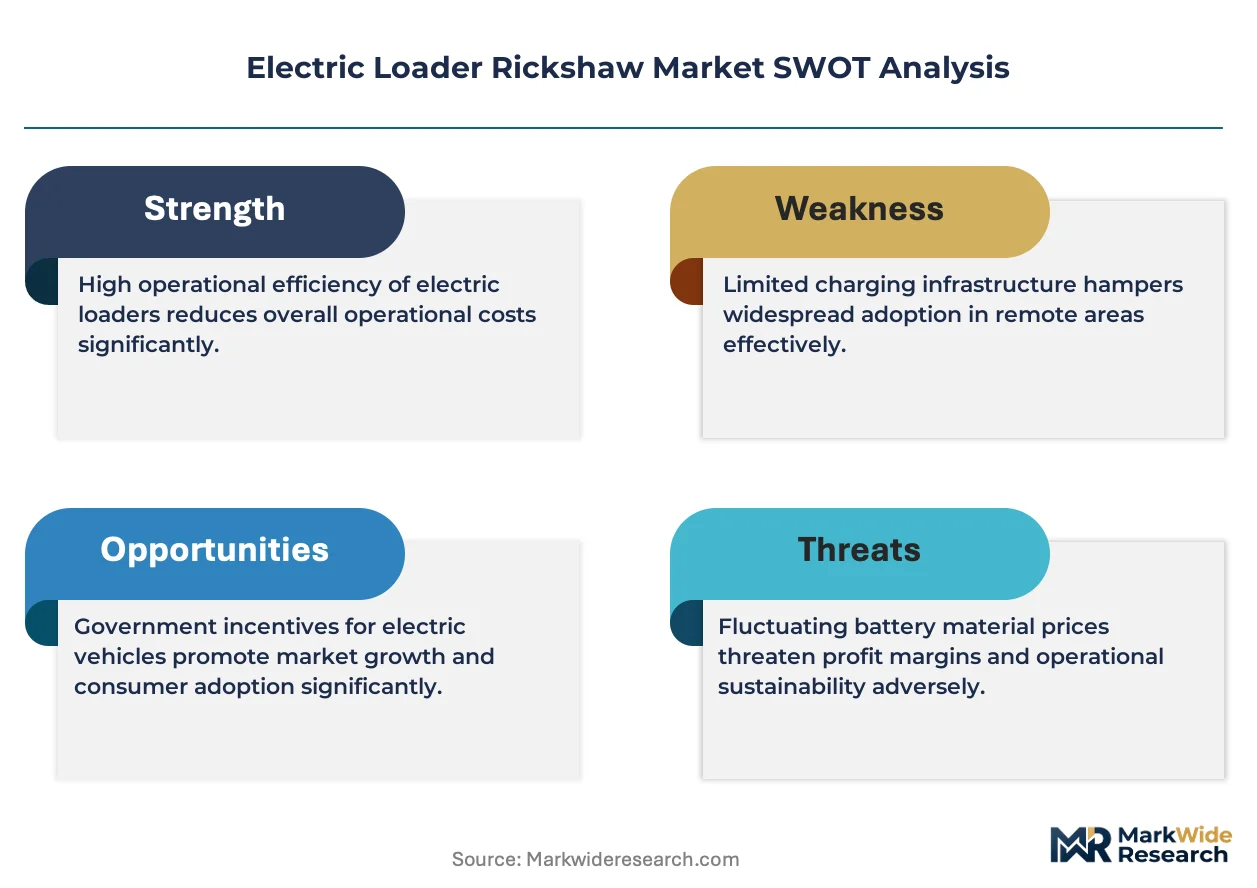
India's FAME-II subsidy extension and state-level electric vehicle policies is realigning fleet procurement toward zero-emission cargo transport. Mahindra Electric Mobility Limited leverages its established dealership network to sustain rural-urban distribution coverage. Bajaj Auto Limited anchors its position through dedicated electric three-wheeler manufacturing scale. Euler Motors differentiates via proprietary battery thermal management systems for commercial duty cycles.
An electric loader rickshaw is a battery-powered three-wheeled commercial vehicle designed for intra-city freight transport, typically featuring a payload capacity of 500–1,500 kilograms and a lithium-ion or lead-acid battery pack mounted beneath the cargo deck. Its primary purpose is to replace diesel and CNG cargo three-wheelers in congested urban environments where maneuverability and operating cost reduction matter. The three-wheeler product type dominates unit shipments due to regulatory homologation familiarity and driver licensing accessibility across Indian states. Among end users, logistics companies command the largest addressable pool as e-commerce fulfillment networks expand same-day delivery requirements. Lithium-ion battery technology leads value capture despite higher upfront cost, since fleet operators prioritize total cost of ownership over acquisition price.
The Ministry of Road Transport and Highways enforces AIS-038 standards for electric vehicle construction, while the Bureau of Indian Standards certifies battery pack safety through IS 16046 protocols. State transport departments in Delhi, Maharashtra, and Gujarat administer purchase subsidies and road tax waivers that directly reduce procurement friction for commercial buyers. The Central Electricity Regulatory Commission oversees charging tariff frameworks affecting fleet depot economics. Stakeholders must monitor state-level subsidy renewal timelines and battery recycling mandate developments to calibrate capacity planning and residual value assumptions.
Market Dynamics
State-level FAME-II subsidy extensions and tightening urban freight emissions mandates are compressing diesel cargo three-wheeler replacement cycles across Indian logistics corridors. Fleet operators now face procurement deadlines tied to regulatory phase-out timelines rather than traditional asset depreciation schedules.
Growth Catalysts
- Lithium-ion cost compression:Battery pack prices per kilowatt-hour have fallen below lead-acid parity thresholds for commercial duty cycles, removing the primary TCO barrier for fleet electrification.
- Delhi EV freight mandate:The Delhi government's mandatory electrification of last-mile delivery fleets in designated congestion zones creates immediate replacement demand.
- E-commerce fulfillment density:Same-day delivery network expansion in Tier-2 cities is multiplying depot-based charging infrastructure deployment.
Market Restraints
- Lithium supply concentration:Raw material processing bottlenecks in select overseas jurisdictions create cell procurement uncertainty for domestic pack assemblers.
- AIS-038 homologation timelines:Central Motor Vehicle Rules certification delays extend product launch windows by six to twelve months.
- Residual value opacity:Absence of standardized battery health assessment protocols depresses secondary market liquidity for used electric cargo units.
Strategic Opportunities
- Bihar freight electrification gap:Low penetration of organized logistics networks in eastern Gangetic plains states offers first-mover depot infrastructure positioning.
- Battery-as-a-service models:Swappable pack subscription structures separate asset ownership from energy costs, reducing fleet operator capex barriers.
- Solar-integrated charging:Photovoltaic canopy installations at urban distribution hubs align with CEA renewable purchase obligation frameworks.
Industry Challenges
- High-voltage technician scarcity:Commercial vehicle service networks lack certified personnel for lithium pack diagnostics and thermal management system repair.
- Multi-state subsidy navigation:Fleet operators operating across Maharashtra, Gujarat, and Karnataka must maintain separate compliance documentation for each jurisdiction's incentive claim process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Loader Rickshaw Market |
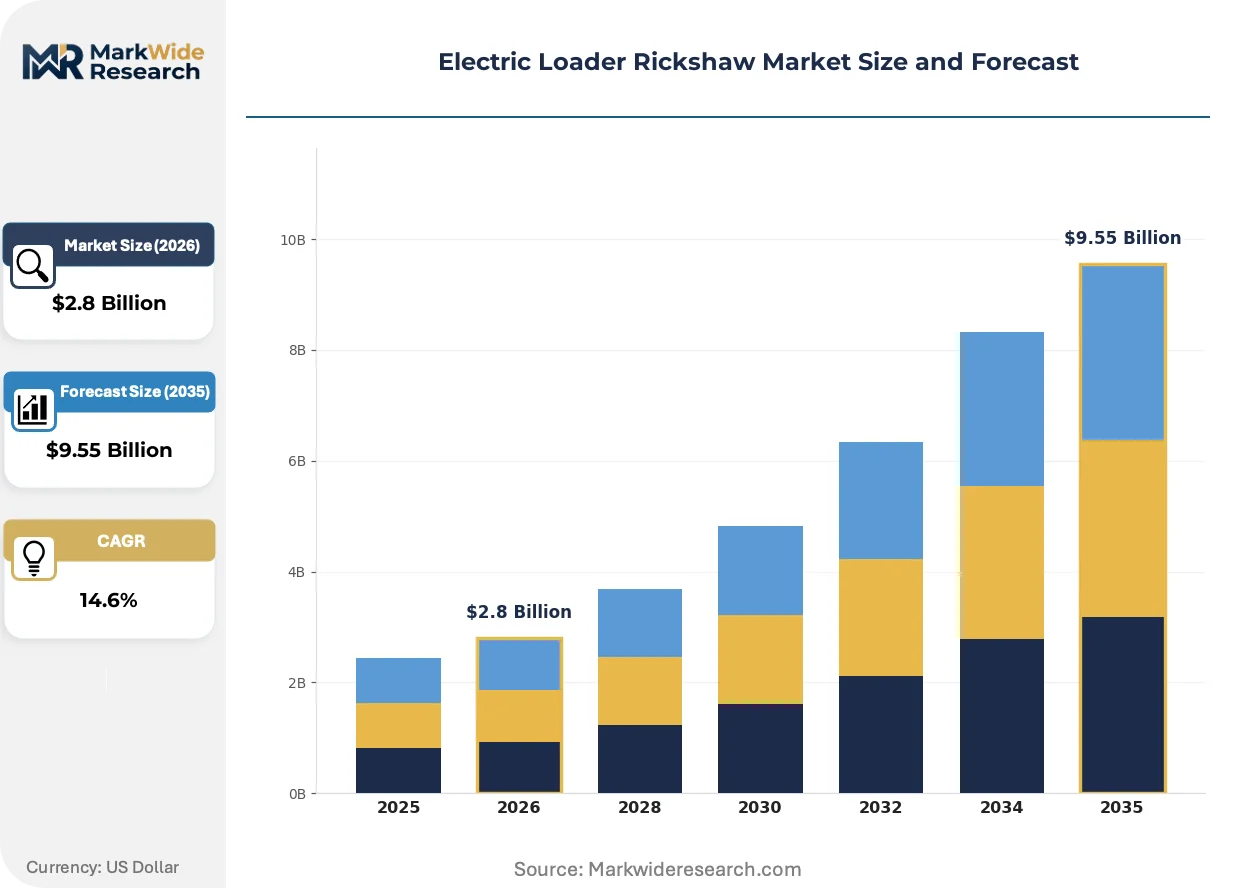
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Wheeler, Three-Wheeler, Four-Wheeler, E-Rickshaw End User: Logistics Companies, Retailers, Delivery Services, Commercial Entities Technology: Electric Drive, Regenerative Braking, Lithium-Ion Battery, Solar-Assisted Installation: On-Road, Off-Road, Urban Areas, Rural Areas |
| Companies Covered | Mahindra Electric Mobility Limited, Bajaj Auto Limited, Piaggio Vehicles Pvt. Ltd., Atul Auto Limited, AG International Pvt. Ltd., Arna Electric Auto Private Limited, YC Electric Vehicle, Euler Motors, Kinetic Green Vehicles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Loader Rickshaw Market Emerging Trajectories
Battery architecture standardization and charging infrastructure interoperability are compressing fleet deployment timelines. Technology providers and logistics operators are co-developing purpose-built electric cargo platforms rather than retrofitting existing three-wheeler chassis.
Pack thermal management hardware is modularizing around standardized cell formats, enabling fleet operators to swap cooling subsystems without replacing entire battery assemblies. Third-party logistics providers in Uttar Pradesh are piloting this architecture to minimize depot downtime. The approach is compressing service interval costs and extending pack warranty compliance windows.
Maharashtra's state electric vehicle policy mandates commercial freight electrification percentages for urban agglomerations, binding fleet operators to procurement quotas regardless of total cost of ownership calculations. The regulation is forcing rapid vendor qualification cycles and compressing incumbent diesel three-wheeler residual values. Logistics companies are responding by consolidating procurement decisions at the state level rather than depot level.
Fleet leasing structures are displacing outright purchase as the dominant acquisition mode among mid-scale e-commerce delivery contractors. Asset-light operators in Tier-1 cities prefer per-kilometer contracts that bundle vehicle, energy, and maintenance costs. This shift is most visible in Bengaluru and Hyderabad where venture-backed logistics platforms dominate last-mile fulfillment networks.
Electric Loader Rickshaw Market Segmentation
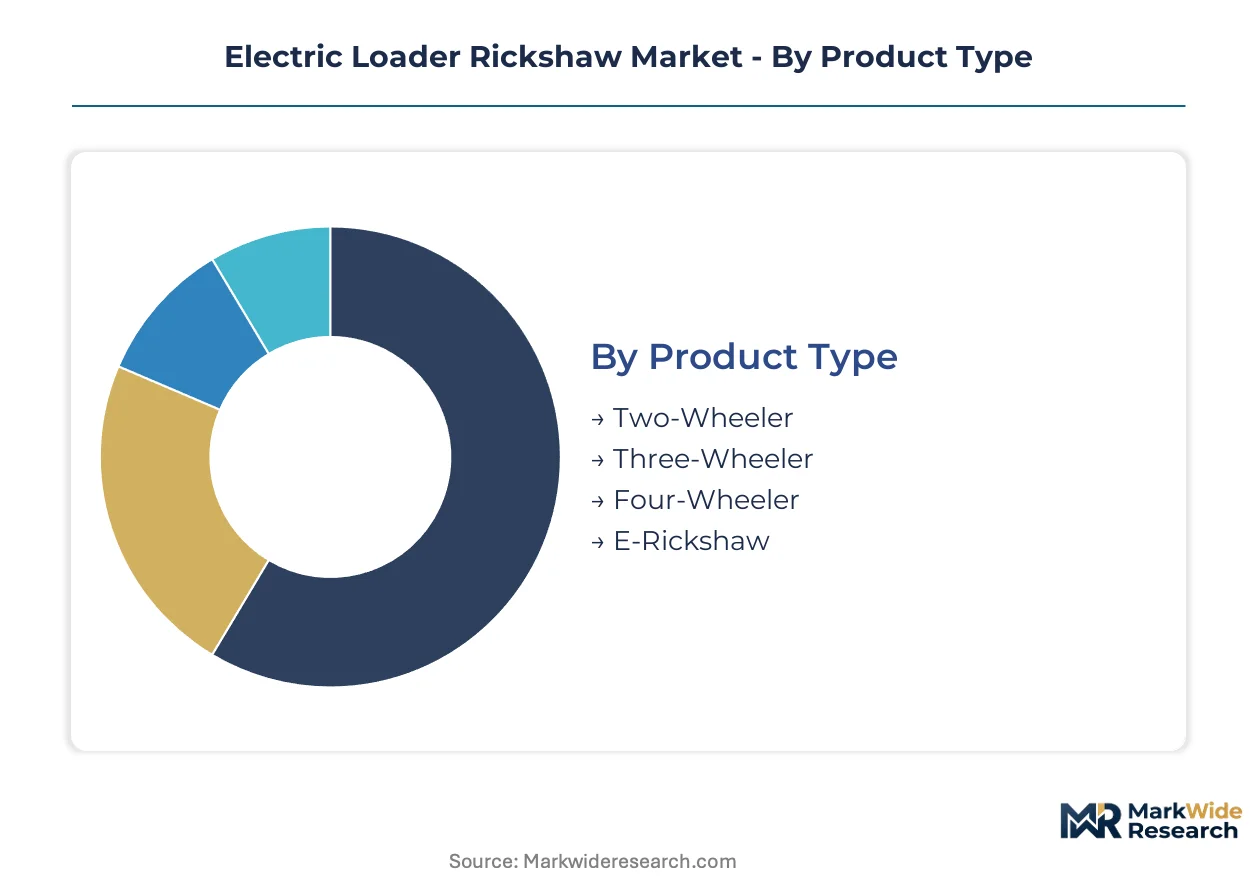
Segmentation in the electric loader rickshaw market reveals how technical specifications, operational environments, and customer procurement patterns create distinct commercial pockets. Fleet operators select configurations based on payload requirements, duty cycle intensity, and state-level subsidy eligibility rather than uniform specifications.
Product Type:
Chassis architecture determines regulatory homologation pathways, driver licensing requirements, and load-bearing economics across Indian logistics corridors.
- Three-Wheeler:Dominant platform featuring open-cargo deck configuration with 500–1,500 kilogram payload ratings. Uttar Pradesh and Maharashtra procurement concentrates here due to established AIS-038 certification familiarity and accessible commercial driving permits.
- E-Rickshaw:Purpose-built electric platform with integrated battery subfloor and reinforced suspension for repetitive stop-start urban duty cycles. Delhi's mandatory freight electrification zones are accelerating replacement of diesel equivalents in last-mile delivery networks.
- Two-Wheeler:Compact electric cargo scooter format serving sub-100 kilogram express parcel segments.
- Four-Wheeler:Enclosed-cabin configuration for weather-sensitive freight categories.
Three-wheeler configurations lead on scale; e-rickshaw platforms lead on momentum.
End User:
Customer procurement sophistication varies sharply between organized fleet operators and fragmented commercial buyers.
- Logistics Companies:Organized fleet operators deploying 50+ unit depots with centralized charging infrastructure and battery management systems. Same-day delivery network expansion in Tier-2 cities is multiplying procurement volumes as e-commerce fulfillment density increases.
- Delivery Services:Venture-backed last-mile platforms operating on per-kilometer leasing contracts rather than asset ownership. Bengaluru and Hyderabad contractors favor this model for balance-sheet flexibility.
- Retailers:Mid-scale commercial buyers with irregular freight patterns.
- Commercial Entities:Institutional procurement for captive logistics needs.
Logistics companies anchor current volume; delivery services are climbing the fastest.
Technology:
Powertrain and energy storage specifications directly determine total cost of ownership calculations and residual value assumptions.
- Lithium-Ion Battery:Nickel-manganese-cobalt and lithium-iron-phosphate cell configurations delivering 80–120 kilometer range with 3,000+ cycle durability. Fleet operators in Gujarat and Karnataka prioritize this technology despite higher upfront acquisition cost due to superior energy density and warranty terms.
- Regenerative Braking:Kinetic recovery systems capturing deceleration energy in high-stop-frequency urban corridors. Deployment concentrates in Mumbai and Delhi where traffic congestion maximizes energy recuperation potential.
- Electric Drive:Hub motor and mid-drive configurations with direct torque delivery.
- Solar-Assisted:Photovoltaic canopy integration for depot-based trickle charging.
Lithium-ion battery technology commands revenue concentration; regenerative braking systems show steepest expansion trajectory.
Installation:
Operating environment dictates suspension specifications, ground clearance requirements, and charging infrastructure topology.
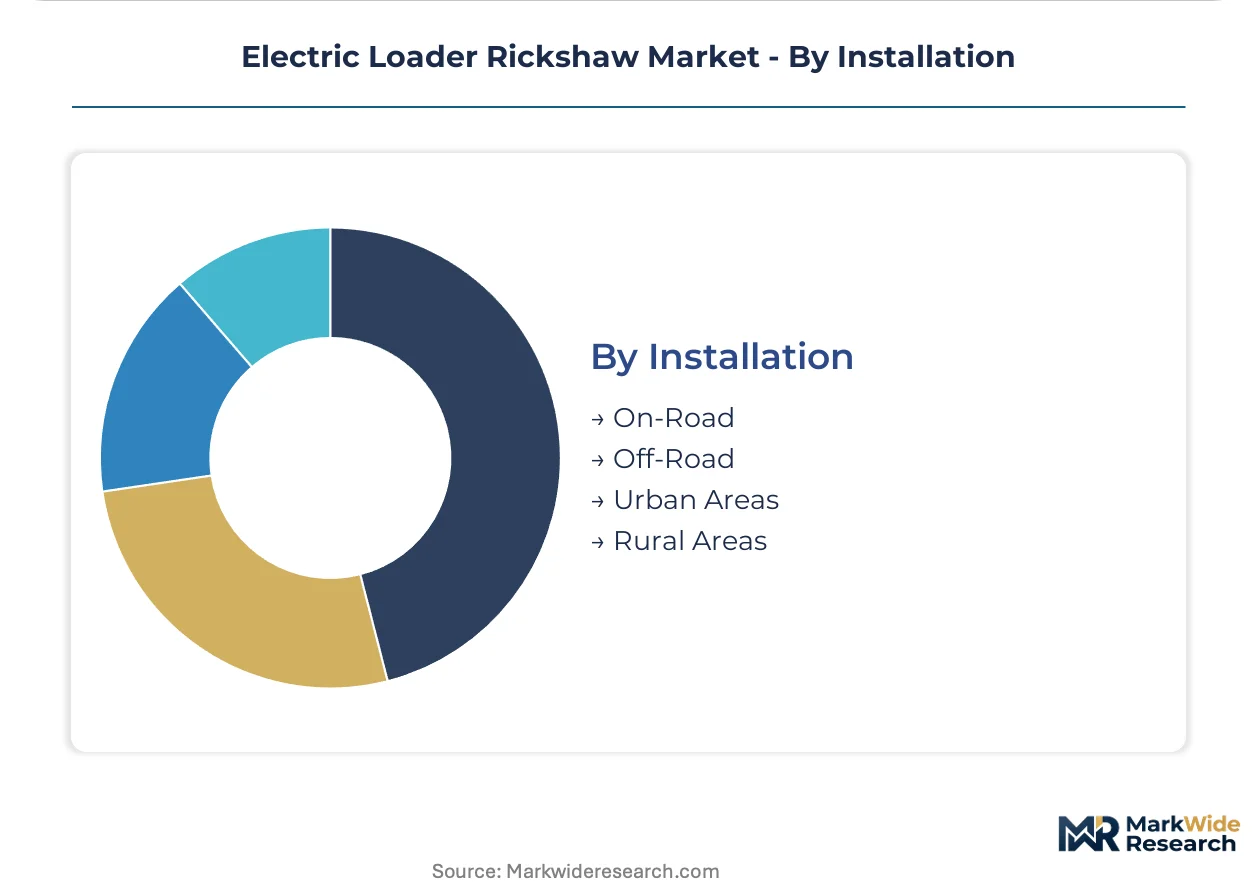
- Urban Areas:Paved-road deployment with standardized charging depot networks and congestion-zone emissions mandates. Delhi, Mumbai, and Bengaluru procurement clusters dominate due to municipal electrification deadlines and e-commerce fulfillment density.
- On-Road:Public thoroughfare operation subject to Motor Vehicles Act compliance and state transport department registration.
- Off-Road:Industrial campus and warehouse yard operation with reduced regulatory oversight.
- Rural Areas:Unpaved surface deployment requiring reinforced suspension and dust-sealed electrical enclosures.
Urban installations lead on scale; rural configurations gain share fastest as organized logistics networks penetrate eastern Gangetic states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric loader rickshaw industry traces its commercial origins to India's informal urban freight networks, where three-wheeled cargo vehicles first displaced hand-pulled carts and animal-drawn transport in the 1990s. Battery-electric variants emerged from this foundation as lithium-ion economics improved and municipal emissions mandates tightened across South Asian logistics corridors.
India
Uttar Pradesh and Maharashtra account for the densest procurement clusters as state-level FAME-II subsidies compress diesel replacement cycles. The Ministry of Road Transport and Highways enforces AIS-038 homologation standards that streamline certification for domestic manufacturers. Delhi's mandatory freight electrification zones in congestion corridors are accelerating fleet turnover among last-mile delivery contractors.
China
Jiangsu and Zhejiang provinces host the dominant battery cell and electric motor manufacturing bases supplying South Asian assemblers. MIIT certification protocols under GB/T standards govern export-oriented production lines. The Yangtze River Delta cluster ships lithium-iron-phosphate packs to Indian pack integrators under long-term supply agreements.
Bangladesh
Dhaka's garment export logistics networks are piloting electric cargo three-wheelers to navigate fuel import volatility and urban congestion penalties. The Bangladesh Road Transport Authority issues commercial permits under evolving EV registration frameworks. Chittagong port-adjacent warehousing zones concentrate early fleet deployment for container drayage substitution.
Vietnam
Ho Chi Minh City's e-commerce fulfillment density is driving depot-based charging infrastructure trials among express parcel operators. The Ministry of Transport administers electric vehicle incentive schemes targeting urban freight electrification. The Mekong Delta agricultural supply chain corridor represents an emerging addressable market for sub-ton cargo electrification.
Indonesia
Jakarta's odd-even license plate restrictions and fuel subsidy rationalization are shifting commercial fleet economics toward battery-electric alternatives. The Ministry of Industry coordinates domestic content requirements under the EV roadmap. Surabaya's port logistics zone is emerging as a testbed for three-wheeler cargo electrification in archipelago freight networks.
Electric Loader Rickshaw Market Vendor Landscape
Premium-margin players sit above commodity-margin players across battery thermal management capability and dealership network density. The vendor base stratifies between integrated automotive conglomerates with homologation expertise and specialist electric vehicle startups with purpose-built commercial platforms. Two strategic archetypes dominate: established two-wheeler and three-wheeler manufacturers leveraging existing distribution infrastructure, and venture-backed pure-plays optimizing for fleet-as-a-service economics. Capacity expansion and battery-as-a-service licensing represent the primary competitive vectors as procurement shifts from asset ownership to operational expenditure models.
Within the integrated automotive tier, Mahindra Electric Mobility Limited and Bajaj Auto Limited occupy positions anchored by rural-urban distribution coverage and manufacturing scale respectively. Euler Motors exemplifies the specialist archetype through proprietary battery system development for commercial duty cycles. These three entities represent the structural fault line between incumbent volume manufacturing and technology-differentiated fleet service provision.
| Leading Market Players |
|---|
| Mahindra Electric Mobility Limited |
| Bajaj Auto Limited |
| Piaggio Vehicles Pvt. Ltd. |
| Atul Auto Limited |
| AG International Pvt. Ltd. |
| Arna Electric Auto Private Limited |
| YC Electric Vehicle |
| Euler Motors |
| Kinetic Green Vehicles |
| Others |
Supply Flow & Price Mechanics
Performance-grade divergence between lithium-ion thermal management systems and lead-acid commodity platforms splits procurement economics across Indian logistics corridors. Fleet operators with centralized charging infrastructure command premium pricing power through battery-as-a-service bundling, while fragmented buyers face spot-market exposure to cell cost volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs fleet procurement decisions in Maharashtra and Gujarat. Price differentiation rests on battery chemistry certification under BIS IS 16046 protocols and depot-scale charging infrastructure bundling. Cost compression in standard-tier lithium packs is intensifying because Jiangsu cell manufacturers are expanding NCM output capacity. Logistics companies with 50-plus unit deployments show lowest price sensitivity; individual commercial buyers in Bihar exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Mumbai, Delhi, and Bengaluru anchor hub-and-spoke patterns for battery pack assembly and vehicle kit consolidation. Manufacturing gravity draws from China for lithium-iron-phosphate cells, South Korea for nickel-manganese-cobalt chemistry, and domestic Maharashtra facilities for chassis fabrication. Raw material dependencies span lithium carbonate from Chile, cobalt from the DRC, and copper busbars from domestic smelters. Single-source vulnerability concentrates in high-nickel cathode precursor supply. Distribution runs through state-level dealership networks with FAME-II subsidy claim integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's electric loader rickshaw sector functions as a regulatory compounder where Delhi's mandatory freight electrification zones and Maharashtra's commercial procurement quotas mechanically expand addressable demand regardless of underlying TCO calculations.
For Market Incumbents: Anchor dealership network density in Uttar Pradesh and Bihar to defend against venture-backed fleet-as-a-service entrants. Prioritize backward integration into battery pack assembly through Maharashtra manufacturing scale to capture FAME-II localization incentives. Certification investment in AIS-038 variant approvals protects against homologation timeline compression by agile competitors. For New Entrants and Emerging Players: Tier-2 city logistics contractors with irregular freight patterns represent the most penetrable buyer archetype underserved by incumbent per-kilometer leasing structures. Target eastern Gangetic states where organized depot infrastructure remains sparse. Deploy solar-integrated charging partnerships as differentiated go-to-market positioning against grid-dependent incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where battery thermal management IP scarcity intersects with homologation expertise deficits among pure-play specialists. Long-term viability favors vertically integrated platforms with captive cell sourcing and state-level subsidy navigation capabilities. Watch Bihar and Jharkhand procurement acceleration as inflection indicator for eastern market maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-as-a-Service Licensing | Separates energy asset ownership from vehicle procurement, reducing fleet operator capex barriers under FAME-II. |
| Thermal Management IP Development | Proprietary cooling subsystem designs extend warranty compliance windows for commercial duty cycles. |
| State-Level Subsidy Navigation Systems | Automated compliance documentation accelerates incentive claim processing across Maharashtra, Gujarat, and Karnataka. |
| Solar-Integrated Depot Infrastructure | Photovoltaic canopy installations align with CEA renewable purchase obligation frameworks for logistics hubs. |
| Secondary Market Battery Health Certification | Standardized assessment protocols unlock residual value liquidity for used electric cargo units. |
Methodological Framework
Bottom-up logistics fleet deployment modeling reconciled against top-down battery cell shipment tracking forms the analytical core of this study. Primary interviews with fleet operations managers, state transport department officials, battery pack assemblers, and charging infrastructure developers combined with secondary validation from Ministry of Road Transport and Highways AIS-038 certification records, Central Electricity Authority tariff filings, and FAME-II subsidy disbursement databases. Triangulation across these sources ensures demand-side and supply-side estimates converge within acceptable variance bands.
Input-output matrices map lithium-ion cell capacity, chassis production volumes, and state-level procurement incentives across product type, end user category, battery technology tier, and installation environment dimensions. CAGRs derive from segmented unit economics modeling incorporating battery cost decline curves, subsidy renewal probability, and diesel price parity thresholds. Forecast inputs include e-commerce fulfillment density trajectories in Tier-2 cities and AIS-038 homologation pipeline visibility.
Underlying measurement precision varies by segment; urban logistics company procurement data carry tighter precision than fragmented rural commercial buyer estimates. Forecasts reflect documented assumptions regarding FAME-II extension timelines, lithium supply contract renewals, and state electric vehicle policy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Oman EV Market
Electric Vehicles
Electric Vehicle Insulation Market
Electric Vehicles
Solar Powered Electric Vehicle Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Electric Utility Vehicle Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Foldable Electric Vehicle Market
Electric Vehicles
48V Mild Hybrid Battery Pack Systems Market
Electric Vehicles
Commercial Vehicle Electric Propulsion System Market
Electric Vehicles
AC BEV On-Board Charger Market
Electric Vehicles
China Solar E-Bike Market
Electric Vehicles
Global Electric Scooter Lift and Carrier Market
Electric Vehicles
Global Electric Vehicles Engineering Plastics Market
Electric Vehicles
High Performance Battery Electric Vehicle Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Train Battery Market