
 Automotive Trim Market | 2026-2036
Automotive Trim Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Trim Market Analysis
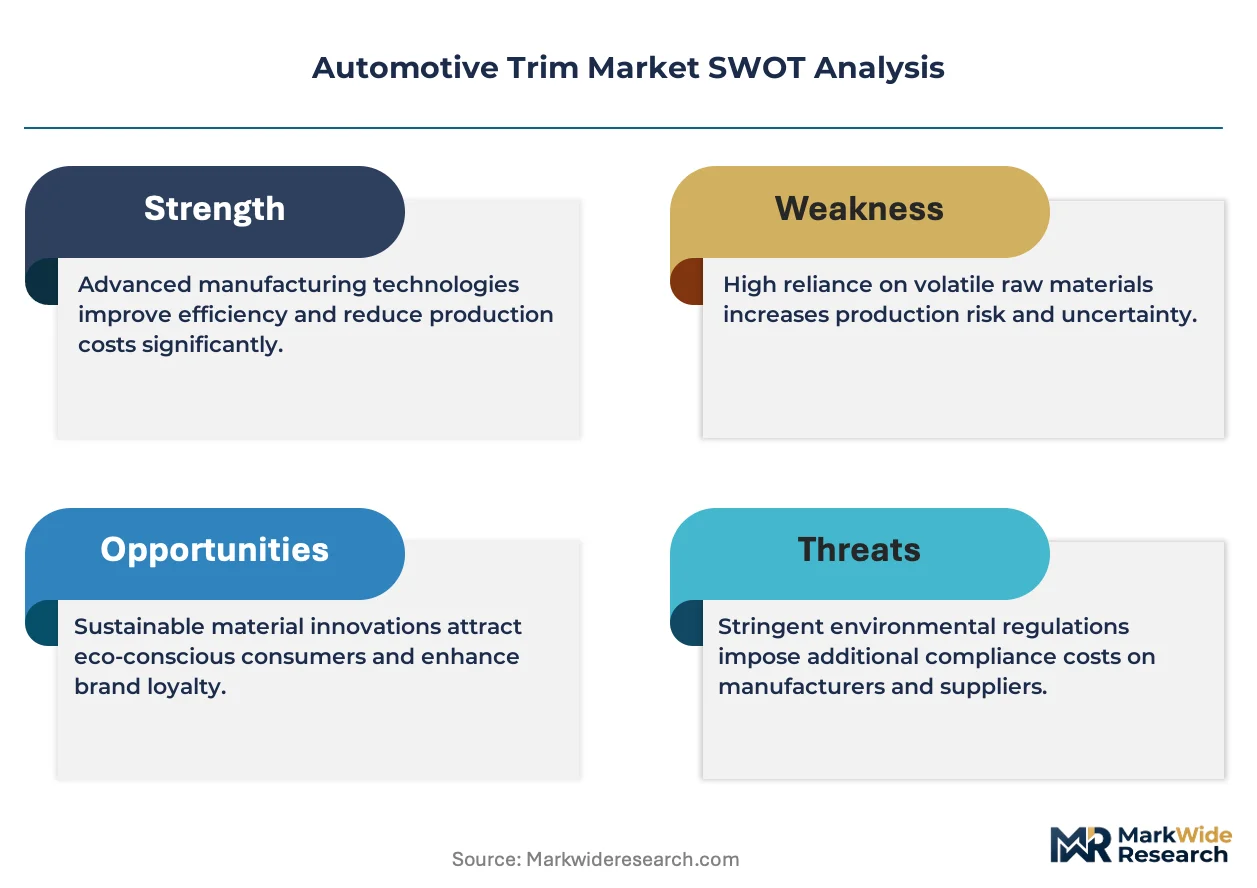
Asset-light leasing structures for injection-molding and thermoforming equipment are reshaping how tier-two suppliers enter automotive trim manufacturing without capital-intensive tool ownership. Magna International leverages its vertically integrated stamping and assembly footprint to control cost positions across interior and exterior trim modules. Lear Corporation anchors its competitive stance through specialized seating and door-trim integration that reduces OEM assembly complexity. Toyota Boshoku sustains technology leadership in textile-wrapped and acoustic-optimized trim surfaces for premium cabin segments.
Automotive trim encompasses the decorative and functional components that finish vehicle interior and exterior surfaces, typically manufactured through injection molding, thermoforming, or compression molding of polymers, metals, and textile composites to tolerances of 0.1-0.5 millimeters for gap-and-flush requirements. These components serve both aesthetic differentiation and structural protection, managing occupant touchpoints while sealing body openings and managing aerodynamic interfaces. Interior trim commands the largest value pool due to higher material diversity and customization depth, while exterior trim in lightweight polymers represents the fastest-expanding material category as OEMs pursue mass reduction targets. Plastic formulations dominate volume consumption, though fabric-wrapped applications in premium cabins sustain higher per-unit margins through specialized lamination and stitching processes.
EPA vehicle interior air-quality guidelines, EU REACH substance restrictions on phthalates and flame retardants, and China's GB standards for volatile organic compound emissions collectively constrain material formulation choices and supplier qualification pathways across major production regions. NHTSA surface-flammability requirements for occupant compartments add a separate compliance layer that shapes textile and polymer selection for North American-bound vehicles. Stakeholders must monitor accelerating regulatory divergence between jurisdictions as a determinant of regional sourcing strategies and product-line rationalization decisions.
Market Dynamics
Electric vehicle architecture is fundamentally reconfiguring trim specifications as cabin experience replaces engine performance as the primary purchase differentiator, forcing suppliers to expand material portfolios and accelerate development cycles.
Growth Catalysts
- EU REACH substance restrictions:Phased limitations on phthalates and flame retardants are redirecting formulation R&D toward bio-based polyurethanes and low-VOC substrates, opening qualification pathways for sustainable material specialists.
- China's domestic EV brands:NIO, BYD, and XPeng specify substantially higher trim content per vehicle than legacy combustion portfolios, concentrating demand growth in premium textile-wrapped and acoustic-optimized surfaces.
- Injection-molding equipment leasing:Asset-light manufacturing structures enable tier-two suppliers to enter trim production without capital-intensive tool ownership, expanding the viable supplier base.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and ABS resin prices fluctuate with crude oil indices, compressing margin predictability for high-volume exterior trim producers.
- Tooling cost concentration:Large-format thermoforming dies for door panels and instrument clusters require concentrated capital deployment, favoring incumbent suppliers with captive mold-making capabilities.
- Surface-flammability compliance:NHTSA FMVSS 302 requirements for occupant compartments add qualification layers that extend development timelines for North American-bound programs.
Strategic Opportunities
- India's expanding automotive manufacturing:Domestic OEMs and joint ventures are localizing trim supply chains under BIS quality mandates, creating first-mover positions for material compounders establishing regional compounding facilities.
- Recyclability mandates:EU Green Deal circular-economy requirements for end-of-life vehicle recovery are accelerating demand for mono-material trim assemblies that simplify disassembly and reprocessing.
- Digital twin integration:Convergence of injection-molding simulation with real-time quality sensing is compressing design-to-production cycles for complex gap-and-flush specifications.
Industry Challenges
- Color-matching expertise scarcity:Specialized knowledge in pigment dispersion across textured polymers and fabric lamination is concentrating among aging technician cohorts, constraining capacity expansion.
- Multi-jurisdiction certification timelines:Simultaneous qualification for EPA interior air-quality guidelines, REACH substance restrictions, and China's GB VOC standards extends program validation by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Trim Market |
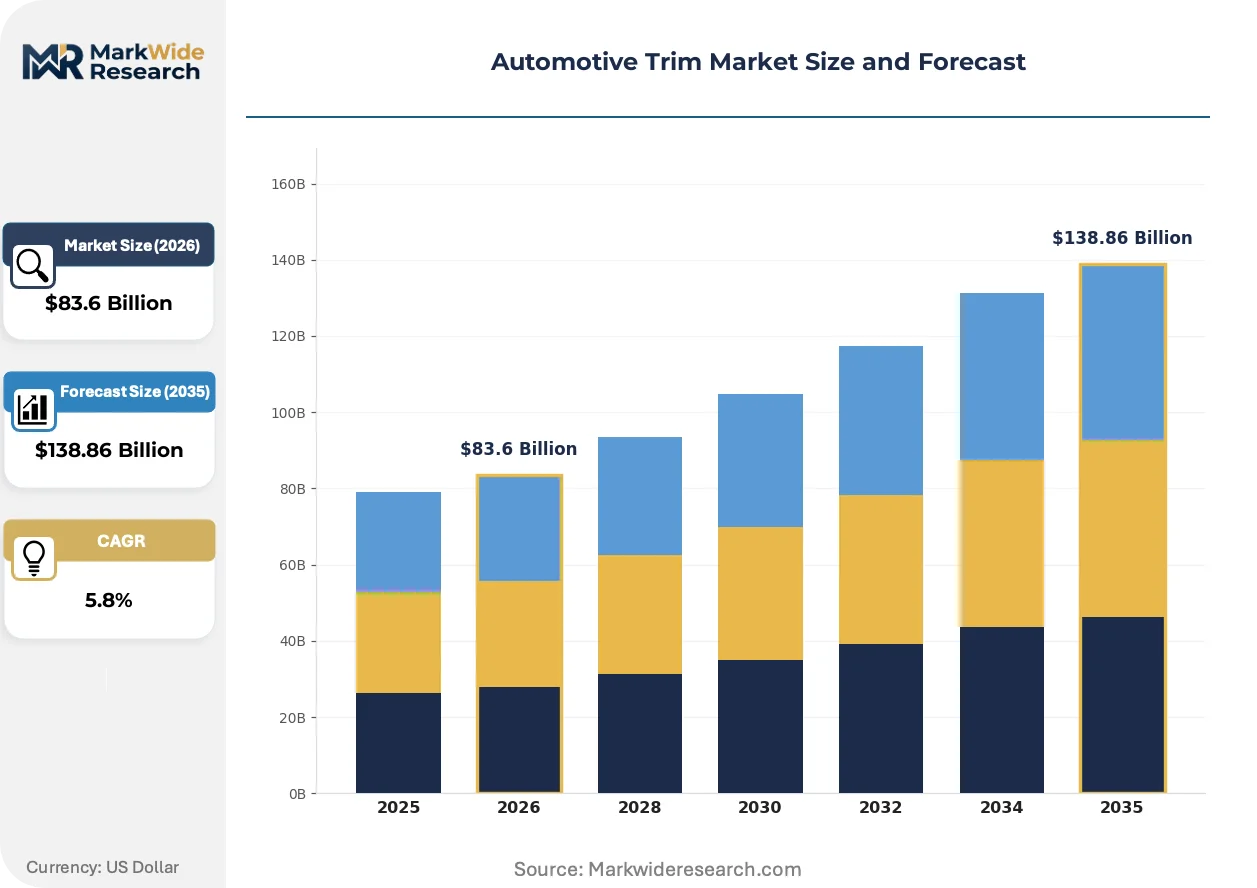
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $138.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Trim, Exterior Trim, Bumpers, Grilles Material: Plastic, Metal, Vinyl, Fabric End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Feature: Customizable Designs, Lightweight Materials, Durability, Aesthetic Appeal |
| Companies Covered | Magna International, Lear Corporation, Toyota Boshoku, Seoyon E-Hwa, Grupo Antolin, Toyoda Gosei, Faurecia, Kasai Kogyo, Yanfeng Automotive Interiors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Trim Market Emerging Trajectories
Material science and manufacturing process evolution are compressing development cycles while expanding the design vocabulary available to cabin architects, particularly in acoustic performance and haptic surface engineering.
Natural fiber-reinforced polypropylene is migrating from concept demonstrators to production door panels and package trays. BMW and Volvo have adopted flax and hemp composites for interior substrates, drawn by density advantages and lifecycle carbon positioning. The technology is migrating from premium niche applications toward volume programs as fiber processing consistency improves and OEM sustainability scorecards harden.
REACH authorization procedures for SVHC substances are tightening disclosure requirements across the supply chain. Compounders must now document full material composition down to 0.1% concentration thresholds, forcing reformulation of legacy flame-retardant packages. Tier-one suppliers serving German OEMs are most exposed, responding by qualifying halogen-free alternatives from specialized additive houses.
Fleet procurement of trim modules is consolidating specification authority at the platform-architecture level rather than individual model programs. Tier-one integrators now contract directly for cross-vehicle-line interior systems, displacing historical OEM direct sourcing of discrete components. This concentration is most visible in China, where domestic EV platforms share standardized cockpit modules across multiple brand derivatives.
Automotive Trim Market Segmentation
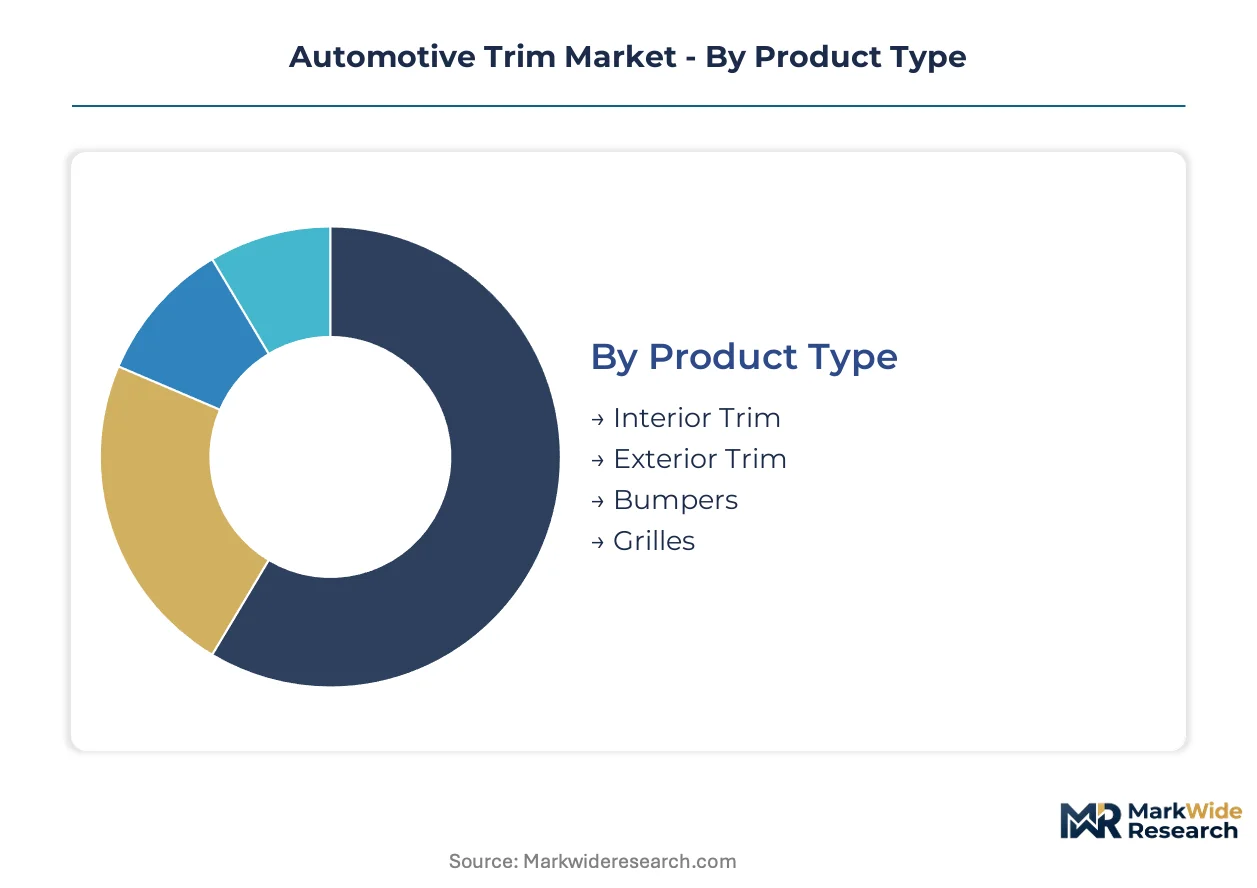
Segmentation in automotive trim reveals how specification authority, material science, and regulatory pressure fragment value capture across the supply chain. Understanding these divides exposes where margin concentrates and where commoditization threatens.
Product Type:
Interior and exterior applications diverge sharply in specification complexity, assembly integration depth, and OEM involvement in design sign-off.
- Interior Trim:Encompasses instrument panels, door panels, pillars, and headliners requiring multi-material lamination and acoustic engineering. Demand concentrates in Chinese EV platforms where NIO and XPeng specify textile-wrapped surfaces and ambient lighting integration as primary purchase differentiators.
- Exterior Trim:Covers beltline moldings, wheel arches, and rocker panels molded in lightweight polymers for aerodynamic management. European OEMs pursuing fleet CO2 targets drive specification toward recycled-content ABS and polypropylene compounds that satisfy ECHA REACH substance restrictions.
- Bumpers:Structural fascias and energy-absorbing systems integrating pedestrian protection and sensor accommodation.
- Grilles:Aperture closures evolving from cooling function to brand identity surfaces, particularly critical for EV differentiation where traditional airflow requirements diminish.
Established volume favors Interior Trim; emerging adoption favors Exterior Trim as mass reduction targets harden.
Material:
Raw material selection determines compliance pathways, tooling amortization rates, and end-of-life recovery economics under tightening circular-economy mandates.
- Plastic:Polypropylene and ABS formulations dominate through injection molding and thermoforming, offering design flexibility at scale. EU Green Deal recyclability requirements are accelerating mono-material assembly strategies that simplify disassembly and reprocessing.
- Metal:Aluminum and steel stampings persist in structural trim applications and premium surface finishes. Cost volatility in aluminum ingot markets and stamping die capital requirements constrain tier-two supplier entry.
- Vinyl:PVC-based surfaces facing phased substance restrictions under REACH SVHC authorization procedures.
- Fabric:Textile-wrapped applications commanding premium positioning through specialized lamination, stitching, and haptic engineering for luxury cabin segments.
Plastic commands current volume leadership; fabric surfaces claim the steepest expansion trajectory as cabin experience displaces powertrain performance in purchase decisions.
End User:
Procurement authority is consolidating at the platform-architecture level, displacing historical direct OEM sourcing of discrete components.
- OEMs:Retain specification authority for flagship programs and brand-defining surfaces, particularly in premium segments where interior differentiation anchors pricing power.
- Aftermarket Providers:Serve collision repair and customization demand with reverse-engineered or licensed replacement trim modules.
- Vehicle Assemblers:Contract for complete cockpit and door-trim systems under module-level procurement consolidating multiple component categories.
- Tier-1 Suppliers:Magna International and Lear Corporation increasingly contract directly for cross-vehicle-line interior systems, integrating seating, door-trim, and instrument panel modules.
Tier-1 integrators are capturing specification authority from OEMs; aftermarket providers face margin compression from certified pre-owned vehicle programs.
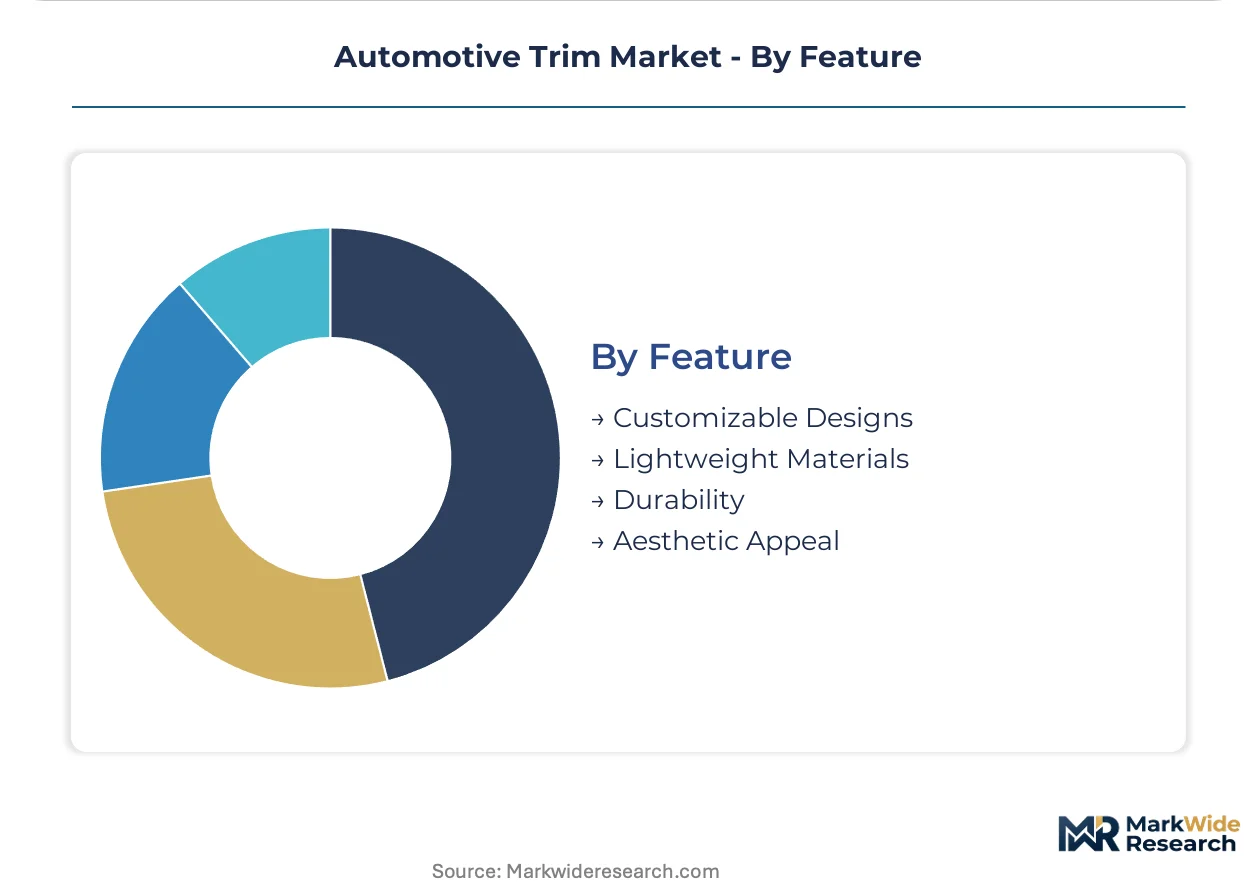
Feature:
Functional priorities in trim specification are reordering as electrification elevates cabin experience and sustainability scorecards harden supplier qualification.
- Customizable Designs:Configurable color, texture, and ambient lighting programming enabling post-purchase personalization. Chinese EV platforms lead specification depth here, offering over-the-air updateable cabin themes.
- Lightweight Materials:Density reduction for range extension in battery-electric vehicles, driving natural fiber-reinforced polypropylene adoption by BMW and Volvo for interior substrates.
- Durability:Scratch resistance, UV stability, and cycle-life performance for high-touch surfaces and exterior exposure.
- Aesthetic Appeal:Gap-and-flush precision to 0.1-millimeter tolerances, surface gloss consistency, and haptic quality for premium positioning.
Lightweight Materials dominate engineering resource allocation; Customizable Designs are climbing fastest as software-defined vehicle architectures enable post-sale revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy regimes and emissions standards are redirecting capital toward EV-centric trim production across major manufacturing zones, compressing development timelines for sustainable material qualification.
China
Domestic EV brands NIO, BYD, and XPeng specify substantially higher trim content per vehicle than legacy combustion portfolios, concentrating demand growth in premium textile-wrapped surfaces. MIIT dual carbon goals and GB standards for volatile organic compound emissions constrain material formulation choices for cabin components. The Yangtze River Delta hosts the densest cluster of tier-one integrators localizing supply chains for export-bound and domestic EV platforms.
Germany
BMW and Volkswagen Group procurement of natural fiber-reinforced polypropylene for interior substrates is accelerating as lifecycle carbon positioning hardens in sustainability scorecards. ECHA REACH substance restrictions on phthalates and flame retardants force reformulation of legacy polymer packages across the supplier base. Bavaria and Baden-Württemberg concentrate specialized additive houses and mold-making capabilities serving premium OEM interior programs.
United States
Detroit Three platform architectures are consolidating specification authority at the module level, displacing historical direct sourcing of discrete trim components. NHTSA FMVSS 302 surface-flammability requirements add qualification layers that extend development timelines for occupant compartment materials. The Southeast manufacturing corridor spanning Tennessee, South Carolina, and Alabama attracts injection-molding capacity to serve transplant OEM assembly operations.
Japan
Toyota and Honda cabin differentiation strategies emphasize acoustic-optimized trim surfaces and haptic quality for hybrid and battery-electric lineups. METI carbon neutrality roadmaps pressure suppliers to document full material composition down to 0.1% concentration thresholds for circular-economy compliance. The Nagoya-Toyota industrial zone sustains captive mold-making and textile lamination expertise for premium interior module production.
India
Maruti Suzuki and Hyundai Motor India are localizing trim supply chains under BIS quality mandates, creating first-mover positions for material compounders establishing regional compounding facilities. Automotive PLI scheme incentives favor domestic value addition in polymer processing and assembly integration. Tamil Nadu and Gujarat host the fastest-expanding clusters of thermoforming and injection-molding capacity serving both domestic consumption and export markets.
Automotive Trim Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where module-level procurement authority concentrates among integrators with captive design capabilities. The vendor base spans global tier-one integrators, regional specialists in textile lamination or acoustic engineering, and asset-light tier-two suppliers accessing equipment leasing structures. Three archetypes dominate: vertically integrated module assemblers, material science specialists in sustainable polymers, and precision mold-makers with simulation-integrated production. Competitive moves center on M&A to secure mold-making capabilities and strategic partnerships to qualify bio-based material formulations.
Within the tier-one integrator tier, Magna International, Lear Corporation, and Toyota Boshoku occupy positions defined by their geographic origins and corporate structures. Magna International exemplifies the vertically integrated archetype with stamping and assembly footprints spanning multiple continents. Lear Corporation represents the seating and door-trim integration specialist model that reduces OEM assembly complexity. Toyota Boshoku anchors the textile-wrapped and acoustic-optimized surface segment rooted in Japanese manufacturing heritage. These three entities illustrate how specification authority concentrates among players with cross-vehicle-line contracting relationships.
| Leading Market Players |
|---|
| Magna International |
| Lear Corporation |
| Toyota Boshoku |
| Seoyon E-Hwa |
| Grupo Antolin |
| Toyoda Gosei |
| Faurecia |
| Kasai Kogyo |
| Yanfeng Automotive Interiors |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion and container rate volatility feed directly into trim module landed costs, compressing margin buffers for European OEMs sourcing from Chinese tier-one integrators while amplifying price spreads between premium textile-wrapped and commodity polypropylene alternatives.
Pricing Analysis
Certification level under REACH SVHC and GB VOC standards creates the primary spread between qualified and unqualified material tiers. Three-tier pricing structure across premium textile-laminated, standard injection-molded, and economy unpainted polypropylene levels anchors transactional contracts. Cost compression in exterior trim grades is intensifying because of polypropylene resin price volatility tied to crude indices. Fleet procurement managers at domestic Chinese EV brands show least price sensitivity for acoustic-optimized cabin surfaces, while aftermarket collision repair channels face acute margin pressure from certified pre-owned vehicle program competition.
Supply Chain Analysis
Export-control restrictions on advanced injection-molding simulation software limit technology transfer to certain regional compounders, constraining mold-flow optimization capabilities outside Germany, Japan, and the Yangtze River Delta cluster. Raw material supply draws from Saudi petrochemical feedstocks for polypropylene resin, German additive houses for halogen-free flame retardants, and Italian textile laminators for premium fabric substrates. Single-source vulnerability concentrates in large-format thermoforming die production captive to Bavarian and Baden-Württemberg mold-makers. Distribution runs through module-level procurement contracts where tier-one integrators like Magna and Lear contract directly for cross-vehicle-line interior systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive trim is reconfiguring as a service-attach opportunity where over-the-air updateable cabin themes and subscription-based personalization layers expand recurring revenue faster than hardware shipment value.
For Market Incumbents: Build captive mold-making capabilities to defend against asset-light tier-two entrants leveraging equipment leasing structures. Secure qualification pathways for bio-based polyurethane formulations ahead of REACH SVHC authorization deadlines. Deepen backward integration into textile lamination to control haptic surface margins as Chinese EV platforms specify premium wrapped finishes. For New Entrants and Emerging Players: Build out regional compounding facilities in Tamil Nadu and Gujarat to capture first-mover positions under India's BIS quality mandates and Automotive PLI scheme incentives. Target natural fiber-reinforced polypropylene substrates for BMW and Volvo sustainability scorecards as the most penetrable material segment. Pursue direct qualification with domestic Chinese EV brands bypassing legacy tier-one gatekeepers through specialized acoustic engineering partnerships. For Investors and Strategic Acquirers: Specialized additive houses with halogen-free flame-retardant portfolios represent the most defensible acquisition archetype as REACH reformulation deadlines concentrate demand. Monitor ECHA authorization timeline acceleration as the signal indicating qualification backlog inflection. Long-term viability hinges on circular-economy compliance capabilities across mono-material assembly design and end-of-life vehicle recovery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates specification authority at tier-one integrators like Magna for cross-vehicle-line cockpit modules. |
| Bio-Based Material Qualification | Opens supplier pathways under EU REACH and China GB VOC mandates for sustainable polyurethanes. |
| Geographic Manufacturing Footprint | Localizes injection-molding capacity in India's Tamil Nadu corridor to satisfy BIS mandates and PLI incentives. |
| Software-Defined Vehicle Investment | Enables over-the-air updateable cabin themes generating recurring revenue beyond hardware sales. |
| Backward Integration into Mold-Making | Captures tooling economics and compresses design-to-production cycles for complex gap-and-flush specifications. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and tier-one supplier procurement patterns anchors the qualitative findings in this study. Primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution heads, and dealership operations managers combined with secondary analysis of vehicle production databases, IHS Markit registration data, ECHA REACH authorization filings, and SEC 10-K disclosures from listed automotive suppliers. Bottom-up content-per-vehicle modeling and top-down market sizing triangulate volume estimates across the projection horizon.
Calibration against historical penetration curves for natural fiber-reinforced composites and textile-wrapped surface adoption refines the analytical framework. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from fitted growth curves adjusted for regulatory mandate timelines and EV platform launch schedules. Industry-specific forecast inputs include MIIT dual carbon goal implementation pace and EU Green Deal circular-economy compliance thresholds.
Stress conditions across polypropylene resin price volatility, REACH authorization timeline acceleration, and Chinese domestic EV brand market share trajectories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and platform architecture standardization trends. Material shifts in EU recyclability mandate enforcement stringency or NHTSA surface-flammability rulemaking would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Cowl Panel Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Automotive Rocker Panel Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Automotive Seat Recliners Market