
 Automotive Performance Parts Market | 2026-2036
Automotive Performance Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Performance Parts Market Analysis
Specialty store networks is reshaping how performance parts reach end buyers, with dedicated showrooms and installer partnerships replacing traditional wholesale distribution. Brembo leverages its Italian manufacturing heritage to dominate the high-performance brake segment across European and North American racing circuits. COBB Tuning specializes in engine management software and staged upgrade kits, sustaining deep loyalty among Subaru and Ford enthusiast communities. HRE Wheels controls the premium forged-wheel category, commanding positions in motorsport and luxury vehicle customization through California-based production.
Automotive performance parts comprise engineered components designed to enhance vehicle dynamics, power output, or aesthetic character beyond original equipment specifications, typically manufactured from aerospace-grade aluminum alloys, titanium alloys, or carbon fiber composites using CNC machining, forging, or autoclave curing processes. These components serve commercial purposes spanning amateur motorsport preparation, street-legal vehicle personalization, and professional racing team procurement where regulatory compliance and measurable performance gains determine purchasing decisions. Exhaust systems and turbochargers anchor the product type segment, with turbochargers capturing expanding share as factory-boosted platforms proliferate and owners seek incremental power through bolt-on upgrades. The distribution channel dimension reveals online retail as the fastest-growing pathway, though specialty stores retain margin concentration through bundled installation services and technical consultation.
EPA tailpipe emissions enforcement and NHTSA Federal Motor Vehicle Safety Standards govern street-legal performance part certification in the United States, while the EU Green Deal and F-Gas Regulation constrain refrigerant and thermal management modifications in Europe. TÜV, EPA, and NHTSA collectively determine market access by distinguishing track-only components from road-certified upgrades, with non-compliant parts restricted to closed-course applications. Stakeholders must monitor evolving emissions enforcement intensity and the divergence between regional certification frameworks when allocating product development budgets and inventory across markets.
Market Dynamics
Factory-boosted engine architectures are proliferating across OEM lineups, redirecting aftermarket R&D budgets toward bolt-on turbocharger upgrades and complementary engine management systems rather than naturally aspirated power adders.
Growth Catalysts
- TÜV Certification Premium:Germany's type-approval system creates a definable price tier for street-legal components, rewarding manufacturers who invest in homologation testing with access to insured, road-registered vehicle modifications.
- Carbon Fiber Manufacturing Scale:Autoclave curing capacity expansion in aerospace supply chains is spilling into automotive, reducing per-unit costs for performance body panels and structural reinforcements.
- Track Day Participation:Amateur motorsport preparation has institutionalized in the United States through SCCA and NASA event structures, sustaining predictable demand for safety-compliant roll cages and fire suppression systems.
Market Restraints
- Titanium Alloy Supply Concentration:Russian and Chinese sponge producers control upstream feedstock for exhaust valves and connecting rods, exposing fabricators to export restriction volatility.
- EPA Enforcement Intensification:Defeat device prosecutions against tuners and resellers have chilled the engine control module flashing segment, compressing margins for software-based power upgrades.
- Forge Press Capacity Scarcity:Aerospace and defense procurement is absorbing available large-die forging capacity, extending lead times for monoblock wheel blanks and suspension uprights.
Strategic Opportunities
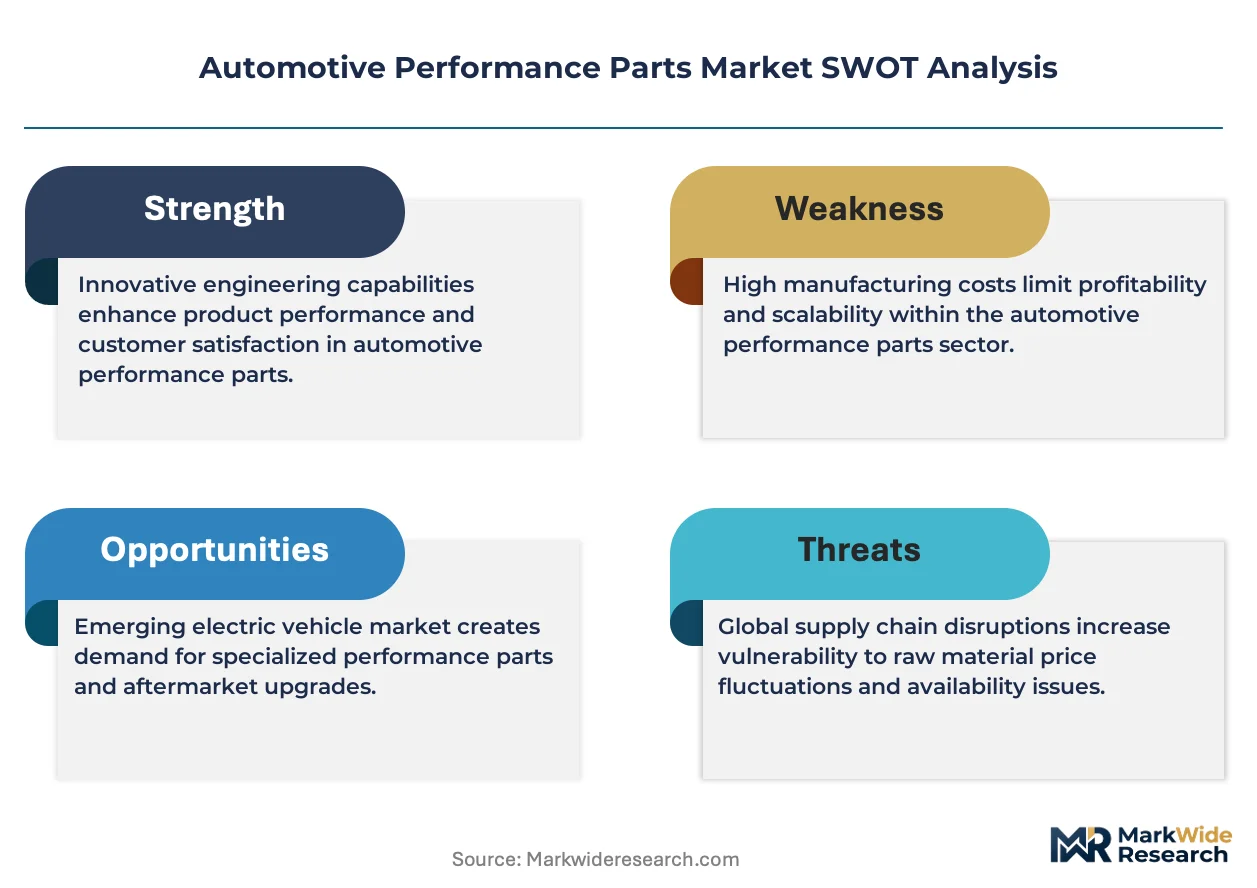
- Electric Vehicle Thermal Management:Battery cooling system upgrades represent an emerging category as track-oriented EV owners seek sustained power output through enhanced heat exchanger capacity.
- India Import Liberalization:DGFT duty restructuring on CKD kits is enabling organized retailers to establish branded performance part assembly operations serving domestic enthusiast clusters.
- Subscription-Based Tuning:Over-the-air calibration services are displacing permanent hardware flashes, creating recurring revenue streams through cloud-delivered power maps matched to fuel quality sensors.
Industry Challenges
- Homologation Engineer Scarcity:TÜV and EPA certification expertise concentrates among retiring specialists, inflating salaries for regulatory compliance talent capable of navigating multi-jurisdiction type approval.
- Legacy CAN Bus Integration:Modern engine management overlays must interface with encrypted OEM control architectures, requiring reverse-engineering investments that strain mid-tier tuner development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Performance Parts Market |
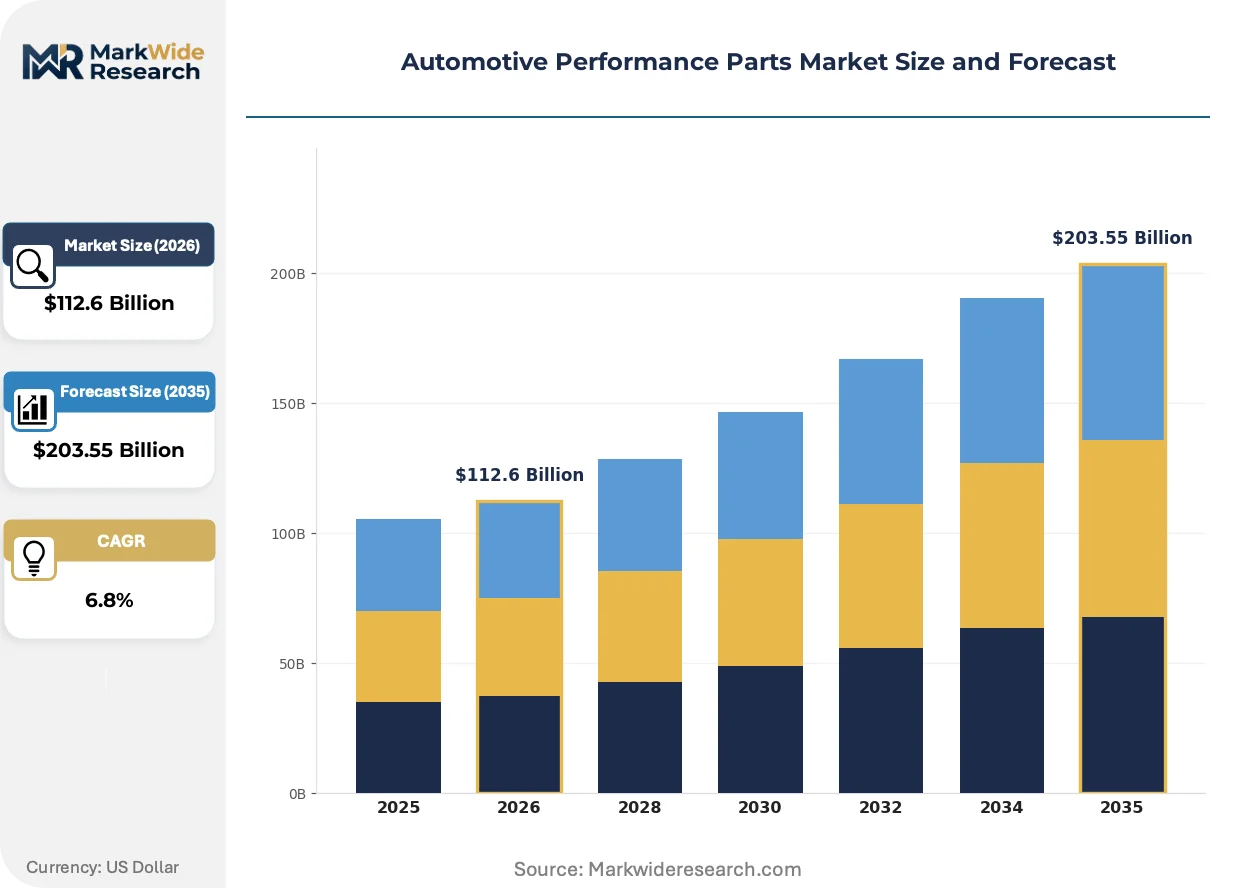
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Systems, Suspension Kits, Cold Air Intakes, Turbochargers End User: Performance Enthusiasts, Race Teams, Vehicle Manufacturers, Aftermarket Retailers Feature: Weight Reduction, Increased Horsepower, Improved Handling, Enhanced Aesthetics Distribution Channel: Online Retail, Specialty Stores, Automotive Shows, Direct Sales |
| Companies Covered | BBS, Bilstein, Brembo, COBB Tuning, Eibach, Akrapovič, KW Suspensions, K&N, HRE Wheels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Performance Parts Market Emerging Trajectories
Performance component development is bifurcating between track-only hardware exempt from emissions constraints and certified street-legal systems engineered for regulatory durability, with material science investments determining which manufacturers can bridge both categories profitably.
Additive manufacturing is hybridizing titanium exhaust manifold production, enabling wall thickness optimization impossible with casting or welding. Race team procurement offices are adopting topology-optimized headers for prototype validation, compressing design-to-track timelines from months to weeks. This capability is compressing the traditional foundry supply chain for low-volume, high-complexity components.
The EU Green Deal's embedded carbon reporting requirements are reshaping supplier qualification protocols for components entering European distribution. Manufacturers must now document Scope 3 emissions from aluminum smelting and carbon fiber precursor production, favoring vertically integrated producers with captive energy contracts. Brake and suspension suppliers with European forging operations are accelerating renewable electricity sourcing to maintain retailer access.
Enthusiast buyer research behavior has migrated to video-native platforms, displacing forum-based technical discussion as the primary pre-purchase validation channel. Specialty retailers are responding with installer-produced content demonstrating fitment and dyno-verified gains, particularly for Subaru and Ford EcoBoost platforms where owner communities concentrate. This shift is most pronounced in the United States, where YouTube and TikTok search volumes for specific part numbers now precede direct retailer site visits.
Automotive Performance Parts Market Segmentation
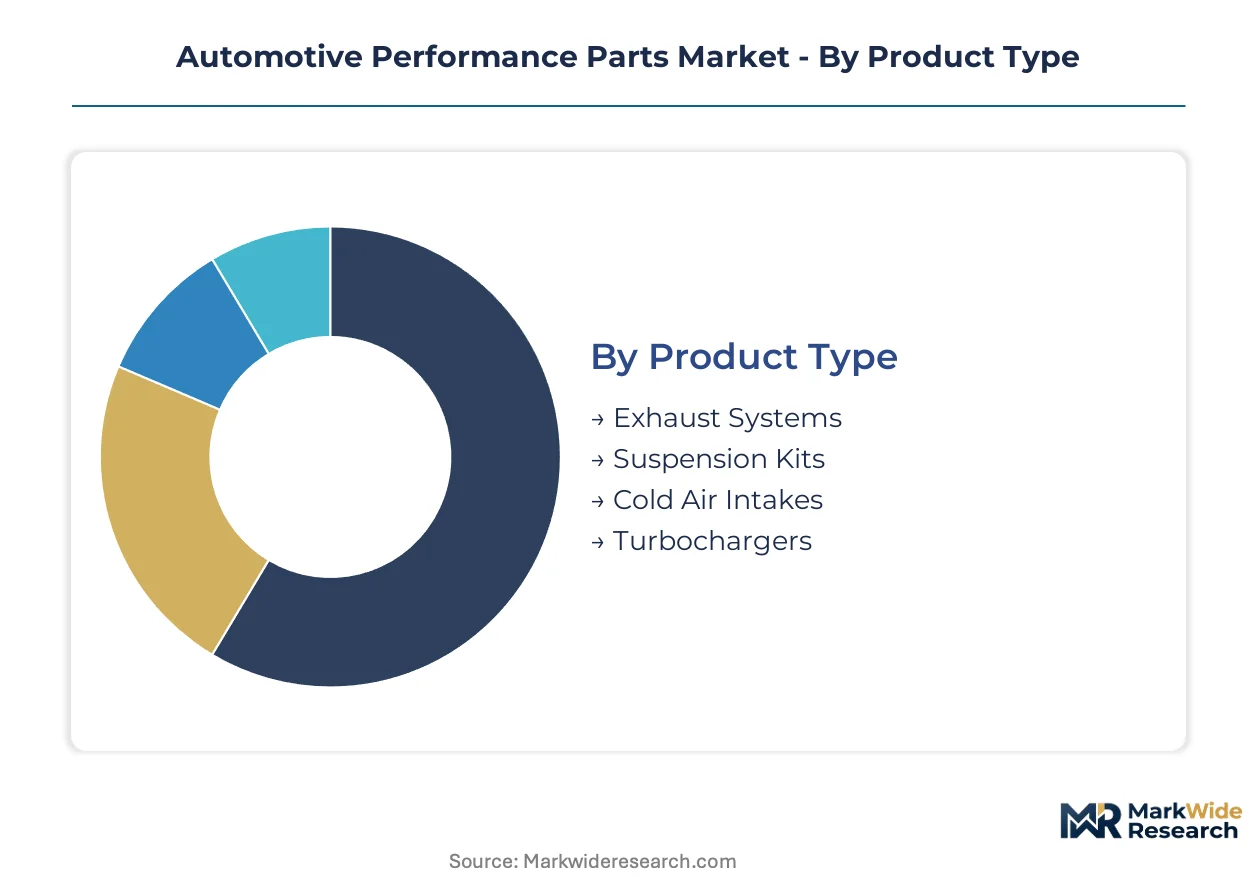
Performance parts segmentation reveals how engineering priorities diverge across buyer types, from amateur enthusiasts seeking bolt-on power to professional race teams demanding homologated durability. Understanding these splits enables manufacturers to align R&D budgets with the certification requirements and volume economics of each channel.
Product Type:
Component selection spans the use-case spectrum from daily-driven street vehicles requiring emissions compliance to dedicated track machines prioritizing weight and thermal efficiency.
- Turbochargers:Forced induction hardware dominates R&D investment as factory-boosted platforms proliferate. Demand concentrates in Germany, where TÜV-certified bolt-on upgrades command insured installation premiums and access to road-registered vehicle modifications.
- Exhaust Systems:Aftermarket headers and cat-back configurations balance acoustic character with backpressure reduction. Procurement is shifting toward titanium alloy construction among U.S. amateur motorsport participants seeking SCCA and NASA event compliance.
- Suspension Kits:Coilover assemblies and adjustable dampers serve stance customization and circuit preparation.
- Cold Air Intakes:Induction plumbing represents the entry-tier modification category with lowest homologation burden.
Established volume favors exhaust systems; emerging adoption favors turbochargers.
End User:
Customer archetypes stratify by technical sophistication, procurement scale, and regulatory tolerance.
- Performance Enthusiasts:Individual owners pursuing incremental power through staged upgrade paths. U.S. buyers concentrate on Subaru and Ford EcoBoost platforms where owner communities validate modifications through video-native research channels.
- Race Teams:Professional procurement offices demand topology-optimized components with rapid design-to-track validation. Carbon fiber manufacturing scale from aerospace supply chains is reducing per-unit costs for safety-compliant roll cages and fire suppression systems.
- Vehicle Manufacturers:OEM accessory programs seeking co-branded performance variants.
- Aftermarket Retailers:Specialty store networks bundling installation services with technical consultation.
Margin concentration sits with race teams; volume expansion sits with performance enthusiasts.
Feature:
Engineering value propositions map to distinct buyer willingness-to-pay curves and material science investments.
- Increased Horsepower:Power adders and engine management calibration anchor the premium pricing tier. EPA enforcement intensification against defeat devices has chilled the engine control module flashing segment, compressing margins for software-based upgrades.
- Weight Reduction:Carbon fiber body panels and forged wheel blanks leverage aerospace-grade material sourcing. Autoclave curing capacity expansion is spilling into automotive, reducing costs for structural reinforcements.
- Improved Handling:Chassis dynamics upgrades through suspension geometry and tire contact patch optimization.
- Enhanced Aesthetics:Visual differentiation through wheel design and aerodynamic appendages.
Technical buyers prioritize increased horsepower; lifestyle buyers prioritize enhanced aesthetics.
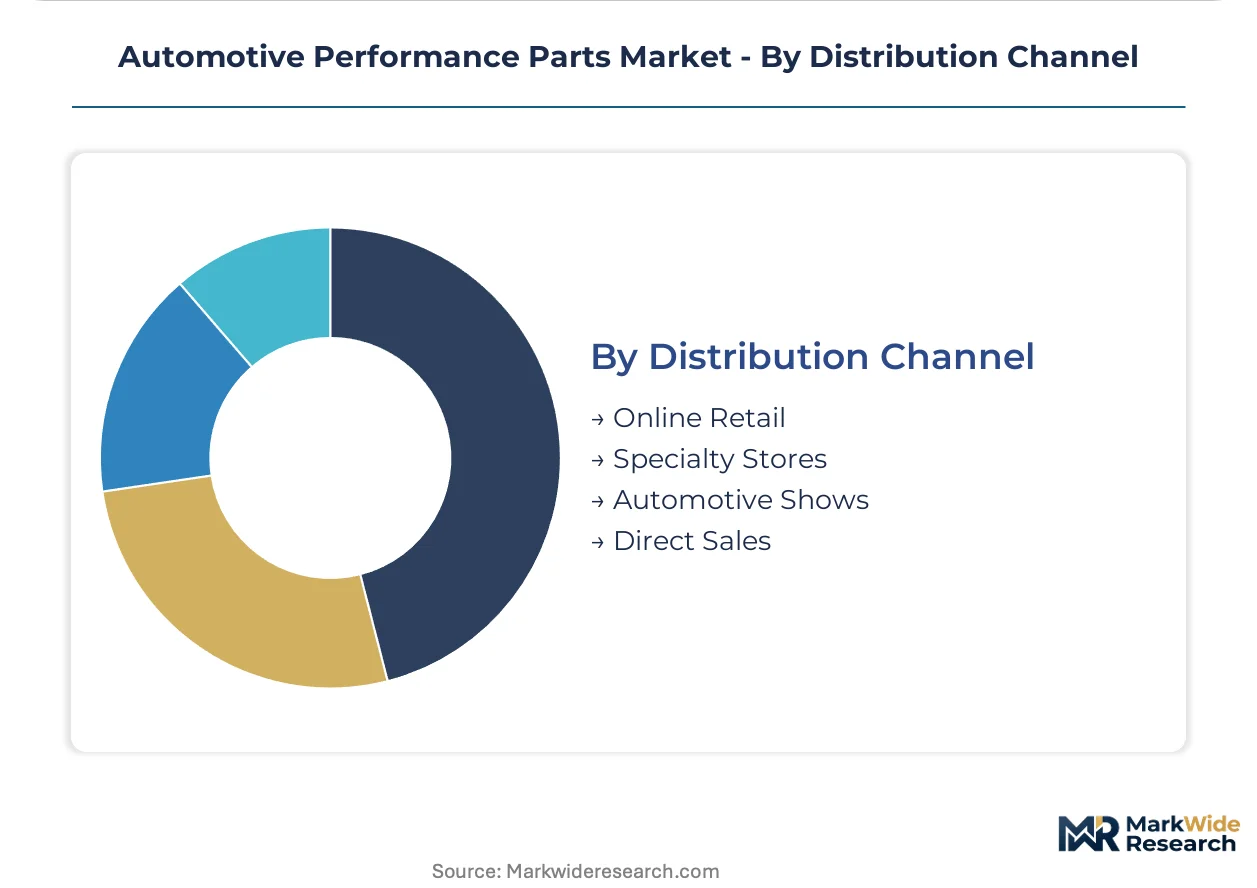
Distribution Channel:
Pathway economics determine margin capture and customer acquisition cost structures.
- Specialty Stores:Dedicated showrooms and installer partnerships sustain margin concentration through bundled installation services. EU Green Deal embedded carbon reporting requirements are reshaping supplier qualification protocols for components entering European distribution.
- Online Retail:Direct-to-consumer platforms are displacing traditional wholesale distribution. YouTube and TikTok search volumes for specific part numbers now precede direct retailer site visits in the United States.
- Automotive Shows:Event-based commerce enabling tactile evaluation and immediate purchase.
- Direct Sales:Manufacturer-owned channels for proprietary calibration and warranty integration.
Margin protection favors specialty stores; customer acquisition scaling favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's TÜV-certified tier, where homologated components command insured installation premiums; the United States sustains higher volume at lower certification thresholds. Regulatory divergence between these markets shapes manufacturer portfolio allocation and margin capture strategies.
Germany
Street-legal performance modifications drive insured installation premiums through TÜV-certified workshops. The KBA enforces type-approval standards that distinguish road-registered from track-only components. Stuttgart's motorsport engineering cluster hosts brake and suspension fabricators supplying certified upgrades to domestic and export markets.
United States
Amateur motorsport preparation through SCCA and NASA event structures sustains demand for safety-compliant roll cages and fire suppression systems. EPA enforcement against defeat devices has compressed margins for engine control module flashing. Southern California's aftermarket ecosystem anchors carbon fiber body panel production and forged wheel manufacturing.
Japan
Kei car tuning culture and heritage platform restoration sustain demand for lightweight forged components. METI oversees industrial standards coordination between automotive and aerospace supply chains. Osaka's forging district supplies titanium alloy exhaust valves to domestic and export performance markets.
United Kingdom
Track day participation and classic motorsport preparation drive procurement of homologated safety equipment. DVSA administers Individual Vehicle Approval for modified vehicles seeking road registration. Motorsport Valley clusters around Oxfordshire and Northamptonshire host race team procurement offices and prototype validation facilities.
China
Domestic enthusiast communities are emerging around domestic performance platforms and parallel import vehicles. MIIT governs vehicle type approval and modification compliance for road-legal operation. Guangdong Province's manufacturing corridor supplies aluminum forging and CNC machining capacity to regional aftermarket brands.
Automotive Performance Parts Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying calibrated sub-assemblies to branded kit manufacturers. Market structure concentrates margin capture among certification-holding incumbents with established TÜV, EPA, and NHTSA testing relationships. Three archetypes dominate: heritage European brake and suspension houses, California-based forged wheel and software tuners, and Asian forging specialists serving volume exhaust and intake categories. Competitive moves center on homologation capacity expansion and installer network partnerships.
Among heritage European component houses, Brembo and Bilstein exemplify the certification-anchored archetype, leveraging decades of motorsport validation to sustain OEM and aftermarket positioning. COBB Tuning represents the software-integrated specialist model, occupying a position within engine management calibration and staged upgrade ecosystems. These three companies illustrate how geographic origin and technical heritage map to distinct competitive vectors in a market where regulatory durability determines market access.
| Leading Market Players |
|---|
| BBS |
| Bilstein |
| Brembo |
| COBB Tuning |
| Eibach |
| Akrapovič |
| KW Suspensions |
| K&N |
| HRE Wheels |
| Others |
Supply Flow & Price Mechanics
Stuttgart's motorsport engineering cluster anchors European brake and suspension fabrication, where autoclave curing capacity from aerospace supply chains spills into automotive carbon fiber production, compressing per-unit costs for body panels and redirecting margin capture toward certified component tiers.
Pricing Analysis
Configured-to-order pricing for TÜV-certified turbocharger kits commands a 40-60% premium over standard catalog exhaust systems, with price differentiation driven by homologation testing depth and brand heritage from motorsport validation. Cost compression in the software-tuning segment is intensifying because EPA defeat-device prosecutions have chilled permanent ECU flashes, squeezing margins for COBB Tuning-style calibration providers. Amateur enthusiasts exhibit highest price sensitivity, while race team procurement offices prioritize thermal efficiency and design-to-track velocity over unit economics.
Supply Chain Analysis
Titanium alloy sponge feedstock draws from Russian and Chinese upstream producers, exposing exhaust valve and connecting rod fabricators to export restriction volatility. Aerospace-grade aluminum smelting concentrates in Germany, Japan, and the United States, with carbon fiber precursor production anchored in Japanese and American petrochemical corridors. Single-source vulnerability in titanium sponge creates procurement risk for monoblock wheel blank manufacturers. Distribution runs through specialty store networks bundling installation services, though online retail is displacing traditional wholesale pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around platform-integrated specialists capable of delivering calibrated sub-assemblies, fragmenting procurement authority away from standalone component distributors toward end-to-end system providers.
For Market Incumbents: Build certification moats through TÜV and EPA testing relationship expansion, defending against mid-tier tuners with encrypted OEM CAN bus reverse-engineering investments. Capacity addition in California-based carbon fiber curing preserves access to Southern California's aftermarket ecosystem. Channel control through installer network partnerships sustains margin capture against direct-to-consumer erosion. For New Entrants and Emerging Players: India's DGFT duty restructuring on CKD kits represents underpenetrated white space for branded performance part assembly operations serving domestic enthusiast clusters. Battery cooling system upgrades for track-oriented EV owners offer the most penetrable emerging category. A go-to-market angle anchored in over-the-air subscription tuning bypasses hardware flash regulatory exposure while capturing recurring revenue. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-integrated specialists with cloud-delivered calibration capabilities, positioning them for superior long-term viability across a 5-10 year electrification transition. Acquisition targets should profile as vertically integrated producers with captive renewable energy contracts for EU Green Deal compliance. The signal to watch is EPA enforcement intensity against defeat devices as an inflection indicator for software-tuning segment margins.| Strategic Initiative | Industry Significance |
|---|---|
| TÜV Homologation Expansion | Certified testing capacity unlocks insured installation premiums in Germany's road-registered modification tier. |
| Carbon Fiber Autoclave Investment | Aerospace supply chain spillover reduces per-unit costs for performance body panels and structural reinforcements. |
| Subscription Tuning Platform Launch | Over-the-air calibration services displace permanent hardware flashes, creating recurring revenue through fuel-quality-matched power maps. |
| EV Thermal Management Development | Battery cooling upgrades address track-oriented EV owner demand for sustained power output through enhanced heat exchanger capacity. |
| India CKD Assembly Operations | DGFT duty restructuring enables organized retailers to establish branded performance part assembly serving domestic enthusiast clusters. |
Methodological Framework
A standing panel of aftermarket distributor procurement heads, OEM platform engineers, Tier 1 supplier manufacturing leads, and specialty store installer technicians provided ongoing calibration against secondary validation from EPA enforcement action records, NHTSA FMVSS certification databases, TÜV type-approval registries, and IHS Markit vehicle production data. Bottom-up demand modeling from enthusiast community sizing and top-down supply verification from forging capacity surveys were triangulated to constrain forecast variance.
Scenario-bracketing around regulatory enforcement intensity and aerospace supply chain spillover rates framed projections across the analysis window, with segmentation modeling across product type, end user archetype, feature priority, and distribution channel. CAGRs were derived from installed base growth of factory-boosted platforms and track day participation trends, incorporating carbon fiber manufacturing scale and titanium alloy feedstock availability as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese aluminum forging specialists or encrypted OEM CAN bus architecture providers would shift outcomes beyond modeled bounds. Cross-checking against SCCA and NASA event participation statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Sintered Silencer Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Die Cast Parts for Electric Vehicle Market
Automotive Parts
Automotive Air Lift Jack Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Italy Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Proportioning Valves Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Light Vehicle Exhaust and Emissions Systems Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
United States Passenger Vehicles Lubricants Market
Automotive Parts
Saudi Arabia Vehicle Exhaust Hose Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Automotive Pneumatic Actuators Market