
 Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market | 2026-2036
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market Outlook
The capital-intensity divergence between electrochromatic specialists and conventional mirror producers is collapsing as heated and folding modules absorb premium pricing. Gentex Corporation leverages its electrochromatic patent portfolio to sustain technology leadership in auto-dimming segments. Magna International Inc. anchors North American supply through integrated glass and actuator manufacturing. Motherson Group competes on scale across European and Asian OEM programs.
An automotive electrically adjustable outside rear view mirror integrates electric motors, heating elements, and optional electrochromatic glass within a weather-sealed housing to enable remote positioning, defrosting, and glare reduction. The assembly typically incorporates polypropylene housings, die-cast aluminum brackets, and multi-layer reflective glass with 40-50% visible light transmission in dimming states. Standard mirrors occupy the highest unit volumes across mass-market vehicle platforms where cost engineering dominates supplier selection. Premium mirrors and auto-dimming technology concentrate margin pools as luxury OEMs specify integrated blind-spot monitoring and memory positioning. Heated mirror technology leads replacement demand in cold-climate markets where regulatory visibility requirements intensify aftermarket turnover.
NHTSA Federal Motor Vehicle Safety Standard 111 governs mirror field-of-view requirements in the United States, compelling OEMs to specify expanded mirror dimensions or supplemental camera systems. ECE R46 regulations in Europe mandate similar visibility standards while REACH compliance restricts hazardous substances in mirror coatings and housing polymers. OEM manufacturers and Tier-1 suppliers must monitor harmonization between camera-based mirror replacement systems and existing reflective mirror standards as regulatory bodies evaluate visibility equivalence across technologies.
Market Dynamics
Camera-based mirror replacement systems are compressing the addressable market for conventional reflective ORVMs as regulators evaluate visibility equivalence between electronic and optical technologies.
Growth Catalysts
- Euro NCAP Safety Protocols:Expanded field-of-view mandates compel OEMs to specify larger mirrors or integrated camera supplements, driving unit value increases across European vehicle platforms.
- Heated Mirror Technology:Cold-climate regulatory visibility requirements intensify aftermarket turnover in Nordic countries, Canada, and Russia where frost protection is non-negotiable.
- Blind-Spot Monitoring Integration:Premium OEMs now specify ORVMs with embedded radar or ultrasonic sensors, creating technology upgrade cycles in luxury vehicle segments.
Market Restraints
- Electrochromatic Glass Cost Concentration:Proprietary coating chemistries and limited supplier bases for auto-dimming substrates inflate module costs relative to conventional reflective glass.
- REACH Compliance Burden:ECHA restrictions on hazardous substances in mirror coatings and housing polymers force reformulation cycles that extend supplier qualification timelines.
- Camera System Substitution:Digital exterior mirrors are displacing physical ORVMs on select premium EV platforms, threatening long-term volume assumptions for traditional mirror suppliers.
Strategic Opportunities
- India Automotive Production:PLI scheme incentives for advanced automotive components create localized manufacturing opportunities for electrically adjustable mirror modules serving domestic and export OEM programs.
- Memory Positioning Convergence:Integration of seat-memory and mirror-memory controllers into centralized body control modules enables Tier-1 suppliers to capture higher electronics content per vehicle.
- Aftermarket Channel Digitization:E-commerce platforms serving collision repair shops are compressing distribution layers for heated and folding mirror replacements in North American cold-climate states.
Industry Challenges
- Actuator Calibration Expertise:Precision motor control for memory positioning requires embedded software competencies that traditional glass-focused suppliers must acquire or outsource.
- Harmonization Delays:Divergent NHTSA and UNECE testing protocols for camera-based mirror alternatives create dual-homologation costs for suppliers serving both regulatory domains.
- Weather-Sealing Durability:IP67-rated housing designs must sustain 10-year service lives across thermal cycling extremes, driving validation costs for new polymer formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market |
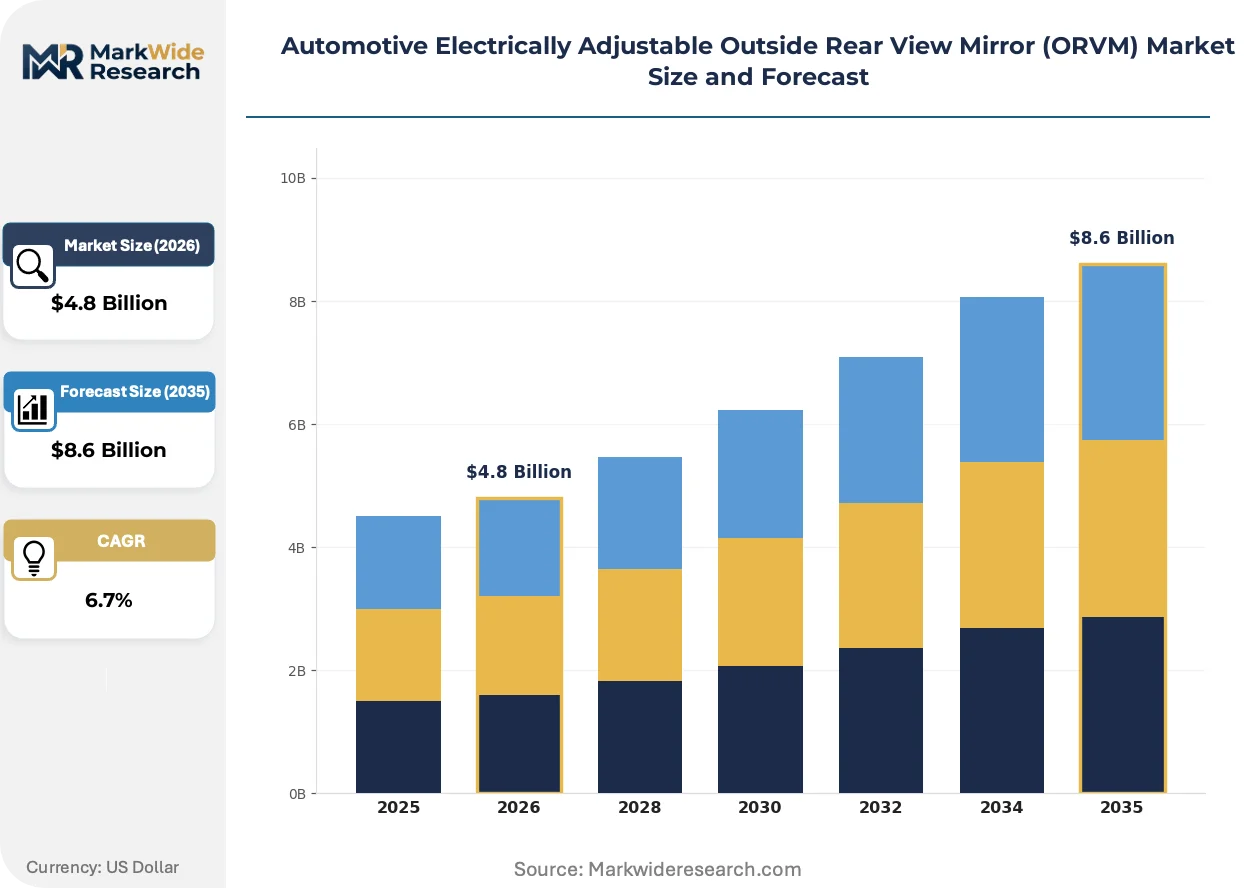
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mirrors, Sport Mirrors, Panoramic Mirrors, Premium Mirrors Technology: Electrochromatic, Heated, Folding, Auto-Dimming End User: OEM Manufacturers, Aftermarket Brands, Vehicle Assemblers, Tier-1 Suppliers Installation: Factory-Installed, Dealer-Installed, DIY Kits, Replacement Units |
| Companies Covered | Mitsuba Corp., Motherson Group, FLABEG Automotive Holding GmbH, Honda Lock Mfg. Co., Ltd., Gentex Corporation, Ficosa Internacional SA, Magna International Inc., Murakami Corporation, SL Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market Strategic Shifts
Electrochromatic dimming is migrating from flagship sedans into mass-market crossovers as actuator costs decline and glare-fatigue awareness spreads among fleet buyers.
Electrochromatic glass with 7-10 second transition speeds is displacing manual day-night mirrors in mid-tier vehicle segments where OEMs previously specified basic reflective units. Japanese and German automakers now mandate auto-dimming functionality across 60 percent of nameplate variants. This technology compression is eroding the premium-standard feature boundary that historically protected margin pools in luxury segments.
NHTSA Federal Motor Vehicle Safety Standard 111 revisions are forcing mirror dimension increases or supplemental camera deployments on light trucks and vans with obstructed rear visibility. The industrial consequence is a bifurcation in supplier strategies between expanded-glass specialists and camera-system integrators. Heavy-duty pickup manufacturers in the United States are responding with dual-path sourcing that maintains conventional mirrors while qualifying electronic alternatives.
Fleet procurement officers now specify integrated blind-spot indicators as standard equipment rather than negotiating line-item deletes during volume purchasing. This specification elevation is compressing the price gap between base and premium mirror SKUs in commercial vehicle channels. The shift is most visible in North American full-size SUV and light truck segments where rental and corporate fleet penetration exceeds 35 percent of annual registrations.
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market Segmentation
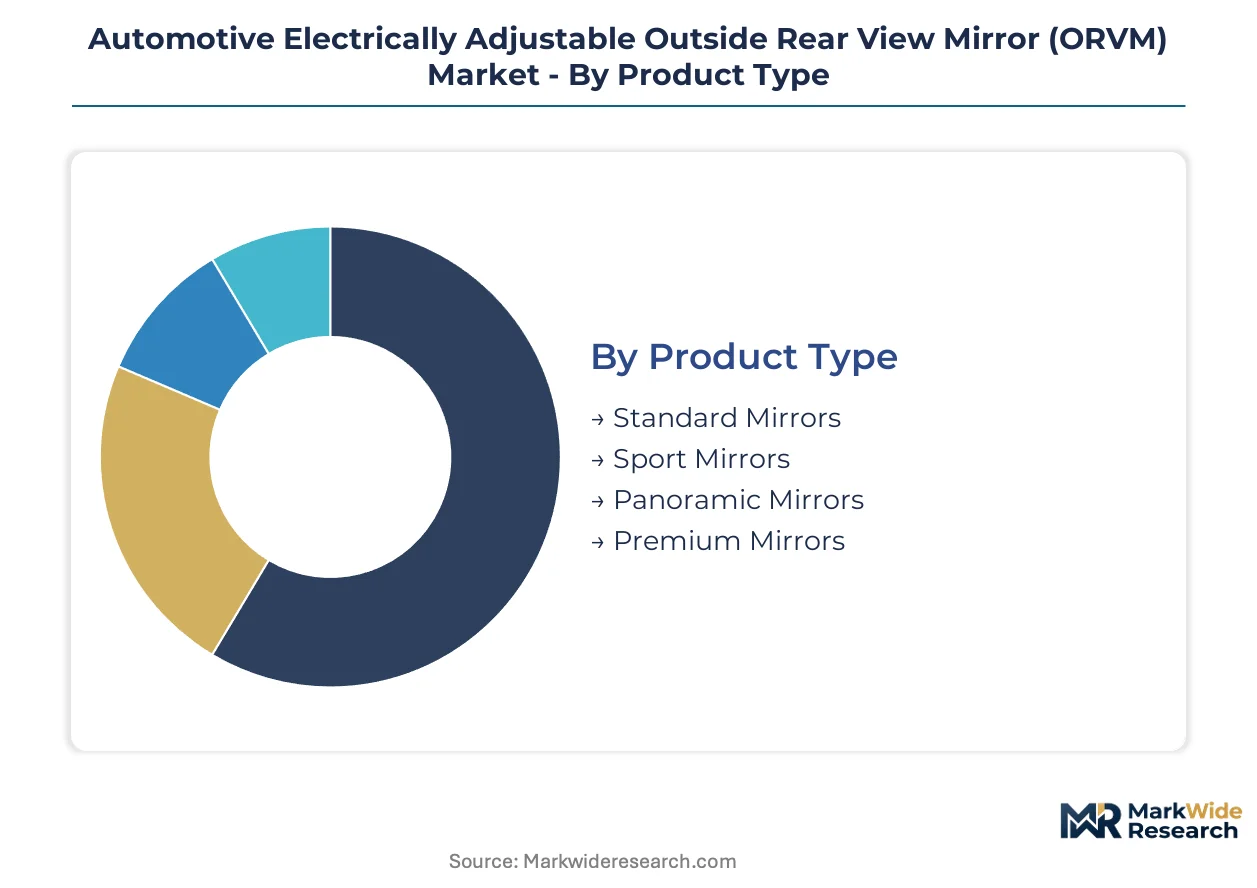
Segmentation in the ORVM market reveals how camera-based mirror substitutes exert uneven pressure across product tiers. Technology and end-user categories show the clearest fault lines between defensive volume segments and growth-exposed premium categories.
Product Type:
Substitution pressure from camera-based systems concentrates in premium mirror segments where electronic alternatives first achieved regulatory approval, while standard mirrors retain cost-protected positions in mass-market platforms.
- Standard Mirrors:Polypropylene housings with die-cast aluminum brackets and multi-layer reflective glass dominate high-volume compact and mid-size vehicle programs. Demand concentrates in Germany, Japan, and the United States where OEM cost engineering prioritizes proven actuator reliability over feature complexity.
- Premium Mirrors:Integrated electrochromatic glass, memory positioning actuators, and embedded blind-spot sensors command module values multiples above standard units. Camera-based mirror systems threaten this segment most directly as regulators evaluate visibility equivalence for luxury EV platforms.
- Sport Mirrors:Aerodynamic housings with reduced frontal area serve performance vehicle nameplates where styling integration overrides field-of-view maximization.
- Panoramic Mirrors:Extended convex glass configurations address NHTSA Federal Motor Vehicle Safety Standard 111 visibility mandates on commercial vans and heavy-duty trucks.
Standard mirrors anchor the volume base while premium mirrors gain share at the steepest rate despite substitution headwinds.
Technology:
Cost tier differentiation separates mature heating and folding functions from electrochromatic and auto-dimming technologies where patent concentration sustains supplier margins.
- Heated:Resistive element integration behind reflective glass enables rapid defrosting in sub-zero operating conditions. Cold-climate regulatory visibility requirements in Canada, Nordic countries, and Russia sustain replacement demand cycles.
- Electrochromatic:Proprietary coating chemistries enable 7-10 second dimming transitions without mechanical shutters. Limited supplier bases and REACH compliance burdens on coating formulations constrain cost reduction trajectories.
- Folding:Motorized pivot mechanisms protect mirror assemblies in narrow urban parking environments and automated car wash sequences.
- Auto-Dimming:Sensor-driven glare detection systems now migrate from flagship sedans into mass-market crossovers as actuator costs decline.
Heated technology commands the widest geographic penetration while electrochromatic functionality expands most quickly into mid-tier nameplates.
End User:
Volume concentration patterns separate captive OEM supply relationships from fragmented aftermarket channels where e-commerce digitization is compressing distribution layers.
- OEM Manufacturers:Direct specification of mirror modules during vehicle platform development locks in multi-year supply agreements. Euro NCAP safety protocols and NHTSA field-of-view mandates drive technology upgrade cycles in European and North American vehicle programs.
- Aftermarket Brands:Collision repair and cold-climate replacement demand sustain independent distribution channels. Heated mirror technology leads turnover in Nordic countries and northern-tier US states where frost protection is non-negotiable.
- Vehicle Assemblers:Contract manufacturing arrangements for regional production hubs require localized mirror module qualification.
- Tier-1 Suppliers:Integrated glass and actuator manufacturing capabilities anchor North American and European supply structures.
OEM manufacturers anchor the volume base while aftermarket brands gain share at the steepest rate through channel digitization.
Installation:
Customer type differentiation separates factory-integrated electronics from dealer and DIY channels where calibration complexity limits technology transfer.
- Factory-Installed:Memory positioning controllers integrate into centralized body control modules during vehicle assembly. Precision actuator calibration requires embedded software competencies that protect Tier-1 supplier positions.
- Replacement Units:Heated and folding mirror assemblies dominate collision repair demand in North American cold-climate states where IP67-rated housing durability sustains 10-year service life expectations.
- Dealer-Installed:Accessory upgrades for fleet and retail customers leverage existing wiring harness provisions.
- DIY Kits:Simplified actuator retrofits serve price-sensitive segments with basic remote positioning functionality.
Factory-installed configurations anchor the volume base while replacement units gain share at the steepest rate through aftermarket channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity for mirror technology upgrades, while volume procurement in India and Mexico prioritizes actuator reliability over feature complexity. This demand-elasticity contrast shapes regional supplier strategies across the forecast period.
Germany
Luxury OEMs in Stuttgart and Munich specify integrated blind-spot monitoring and memory positioning as standard equipment across 60 percent of nameplate variants. Euro NCAP safety protocols mandate expanded mirror visibility zones, compelling Tier-1 suppliers to qualify larger glass configurations. The Baden-Württemberg industrial corridor hosts concentrated development of electrochromatic coating chemistries for auto-dimming applications.
United States
NHTSA Federal Motor Vehicle Safety Standard 111 revisions are forcing mirror dimension increases or supplemental camera deployments on light trucks and vans with obstructed rear visibility. Fleet procurement officers now specify integrated blind-spot indicators as standard equipment rather than negotiating line-item deletes. Michigan-based suppliers anchor North American supply through integrated glass and actuator manufacturing capabilities.
Japan
Japanese automakers now mandate auto-dimming functionality across 60 percent of nameplate variants as electrochromatic dimming migrates from flagship sedans into mass-market crossovers. METI industrial policy supports domestic actuator cost reduction programs. The Nagoya industrial cluster concentrates precision motor control development for memory positioning systems.
China
Domestic OEMs are expanding procurement of heated mirror variants for cold-climate export markets while camera-based mirror replacement systems undergo regulatory evaluation. MIIT standards harmonization efforts are accelerating qualification timelines for electronic mirror alternatives. The Yangtze River Delta hosts the highest concentration of mirror module assembly capacity serving both domestic and export programs.
India
PLI scheme incentives for advanced automotive components create localized manufacturing opportunities for electrically adjustable mirror modules serving domestic and export OEM programs. Cost engineering dominates supplier selection as mass-market vehicle platforms prioritize proven actuator reliability. The Tamil Nadu automotive cluster is emerging as a qualification hub for heated and folding mirror exports to Middle Eastern and African markets.
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Electrochromatic specialists command premium positioning through proprietary coating chemistries, while scale-driven fabricators compete on actuator reliability and logistics integration. The market consolidates around three strategic archetypes: patent-protected technology leaders, integrated glass-actuator manufacturers, and volume-focused Asian suppliers. Dominant competitive moves include backward integration into polymer housing production and strategic partnerships for embedded sensor integration.
Among North American technology leaders, Gentex Corporation and Magna International Inc. exemplify divergent paths—Gentex occupying a position anchored in electrochromatic intellectual property, while Magna represents integrated manufacturing scale across glass and actuator domains. Motherson Group sits within the volume-driven tier, leveraging multi-regional production footprints to serve European and Asian OEM programs simultaneously.
| Leading Market Players |
|---|
| Mitsuba Corp. |
| Motherson Group |
| FLABEG Automotive Holding GmbH |
| Honda Lock Mfg. Co., Ltd. |
| Gentex Corporation |
| Ficosa Internacional SA |
| Magna International Inc. |
| Murakami Corporation |
| SL Corporation |
| Others |
Value Chain & Pricing Dynamics
NHTSA Federal Motor Vehicle Safety Standard 111 and ECE R46 qualification requirements gate both supplier entry and price differentiation simultaneously, forcing Tier-1 manufacturers to absorb validation costs that smaller competitors cannot finance while enabling premium positioning for certified variants.
Pricing Analysis
Aftermarket replacement parts and collision repair services drive lifetime value in this sector. Three-tier pricing structure across premium, standard, and economy levels separates electrochromatic auto-dimming modules from heated folding variants and basic remote-positioning units. Certification grade for NHTSA and Euro NCAP compliance creates price differentiation alongside volume scale and after-sales bundling with dealership service networks. Cost compression in standard mirror tiers is intensifying because actuator commoditization erodes supplier margins. Fleet procurement officers at commercial vehicle operators demonstrate highest price sensitivity, while luxury OEMs in Germany and Japan show lowest elasticity for technology upgrades.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM supply relationships while aftermarket distributors maintain strategic stockpiles of heated mirror modules for cold-climate replacement demand. Manufacturing concentrates in Germany, Japan, and China where precision actuator production and glass coating capabilities anchor regional supply bases. The supply chain draws from polypropylene resin suppliers, die-cast aluminum foundries, and electrochromatic coating specialists. Single-source vulnerability for proprietary dimming substrates creates structural risk exposure. Distribution runs through Tier-1 direct OEM contracts and fragmented aftermarket channels where e-commerce platforms compress traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-based mirror replacement systems threaten volume assumptions for traditional reflective ORVM suppliers, demanding active substitution defense strategies across product and customer portfolios.
For Market Incumbents: Consolidate actuator calibration expertise and embedded software competencies through selective acquisition of motor-control specialists. Deepen backward integration into polymer housing production to capture cost reduction trajectories and protect margin position against camera system substitution. Prioritize certification investment for NHTSA and UNECE dual-homologation to serve both regulatory domains without duplicate qualification costs. For New Entrants and Emerging Players: Aftermarket channel digitization gaps in North American cold-climate states present white-space entry points where incumbent distributors maintain legacy relationships. Target collision repair shops and independent service centers with IP67-rated heated mirror replacements through direct e-commerce platforms. Pursue PLI scheme qualification in India to serve domestic OEM programs and export markets with cost-engineered standard mirror modules. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electrochromatic coating segments as REACH compliance burdens extend supplier qualification timelines. Electrochromatic specialists with proprietary chemistries and established OEM relationships represent priority acquisition archetypes. Watch for camera-based mirror regulatory approval milestones as inflection indicators that would accelerate substitution timelines and compress traditional mirror valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Housing | Captures cost reduction trajectories and protects margins against actuator commoditization. |
| Dual-Homologation Certification Investment | Enables single-platform supply to NHTSA and UNECE markets without duplicate validation costs. |
| Embedded Sensor Integration Partnership | Positions ORVM modules for blind-spot monitoring convergence in luxury vehicle programs. |
| Aftermarket E-Channel Expansion | Compresses distributor layers in North American cold-climate replacement markets. |
| PLI Scheme Manufacturing Localization | Qualifies cost-competitive mirror production for Indian domestic and Middle Eastern export demand. |
Study Parameters
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership operations converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation from vehicle production databases, IHS Markit registration data, NHTSA FMVSS 111 filings, and ECE R46 regulatory documentation. Bottom-up unit volume modeling and top-down value aggregation triangulated market size estimates across the analysis window.
Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from fitted growth curves applied to baseline volume and value estimates throughout the forecast period. Industry-specific inputs encompass Euro NCAP safety protocol adoption timelines, PLI scheme incentive qualification rates, and camera-based mirror regulatory evaluation progress.
Forecasts assume regulatory continuity in NHTSA and UNECE regimes; material policy shifts would require re-modeling. Revision becomes warranted when camera-based mirror approval thresholds cross regulatory equivalence benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Flock Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Door Handle Sensors Market