
 Car Organizer Market | 2026-2036
Car Organizer Market Size, Share, and Industry Trends Forecast 2026-2036
Car Organizer Market Insights
Ride-sharing drivers are unwinding the traditional family-centric demand model that long dominated car organizer purchasing. WeatherTech leverages its domestic manufacturing footprint to sustain premium positioning in all-weather trunk systems. Covercraft anchors its competitive stance through specialized seat-back configurations designed for professional transport use.
A car organizer is a vehicle-interior storage apparatus, typically fabricated from woven synthetic textiles or coated fabrics with reinforced stitching and modular compartment geometries, engineered to secure cargo, electronics, and personal items against motion during transit. Trunk organizers lead volume owing to their universal fit across SUV and crossover platforms, while backseat configurations command margin premiums through multi-compartment designs tailored to child safety seat integration. Polyester dominates material selection for its abrasion resistance and dye stability, though leather variants occupy the aftermarket luxury tier where professionals seek cabin aesthetics matching executive vehicle standards.
The US Consumer Product Safety Commission monitors flammability standards for automotive textiles, while the EPA regulates volatile organic compound emissions from adhesive bonding processes in organizer assembly. California's Proposition 65 mandates explicit labeling for phthalate-containing vinyl components, forcing reformulation across nylon-laminated product lines. Stakeholders must monitor evolving state-level chemical restriction cascades that could fragment compliance requirements beyond federal baselines.
Market Dynamics
Gig-economy fleet standardization is compressing design cycles for car organizer manufacturers, forcing rapid SKU proliferation to match ride-sharing platform specifications while polyester resin volatility squeezes margin buffers across the supply base.
Growth Catalysts
- REACH textile amendments:EU ECHA enforcement of perfluorinated compound restrictions is accelerating substitution toward bio-based coatings, opening premium positioning for compliant suppliers.
- Ride-sharing fleet protocols:Uber and Lyft driver incentive programs mandate cabin organization standards, creating institutional procurement channels that bypass traditional retail.
- Modular thermoforming:Vacuum-formed polypropylene inserts are displacing stitched fabric compartments in commercial vehicle segments due to sanitization durability requirements.
Market Restraints
- Prop 65 compliance costs:California's mandatory phthalate labeling forces reformulation of vinyl-laminated nylon products, adding 12-18% to raw material expenses for West Coast suppliers.
- Petrochemical input volatility:PTA and MEG feedstock price swings destabilize polyester fabric costing models, compressing contract manufacturing margins in Zhejiang province.
- Universal fit limitations:Cross-platform compatibility requirements prevent optimized designs for emerging electric vehicle architectures with non-standard trunk geometries.
Strategic Opportunities
- India two-wheeler expansion:Scooter delivery fleets in Bangalore and Mumbai represent untapped demand for under-seat storage systems with weatherproofing specifications.
- IRA domestic content credits:US assembly incentives favor reshoring of injection-molded organizer bases to qualify for electric vehicle accessory tax treatment.
- Smart cargo integration:RFID-tagged compartments converging with fleet telematics enable real-time inventory tracking for logistics contractors.
Industry Challenges
- Flammability certification timelines:FMVSS 302 testing backlogs at third-party laboratories delay product launches by 4-6 months for backseat configurations.
- Pattern digitization skills gap:Parametric design software expertise remains scarce among traditional sewing-floor supervisors transitioning to automated cutting systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Organizer Market |
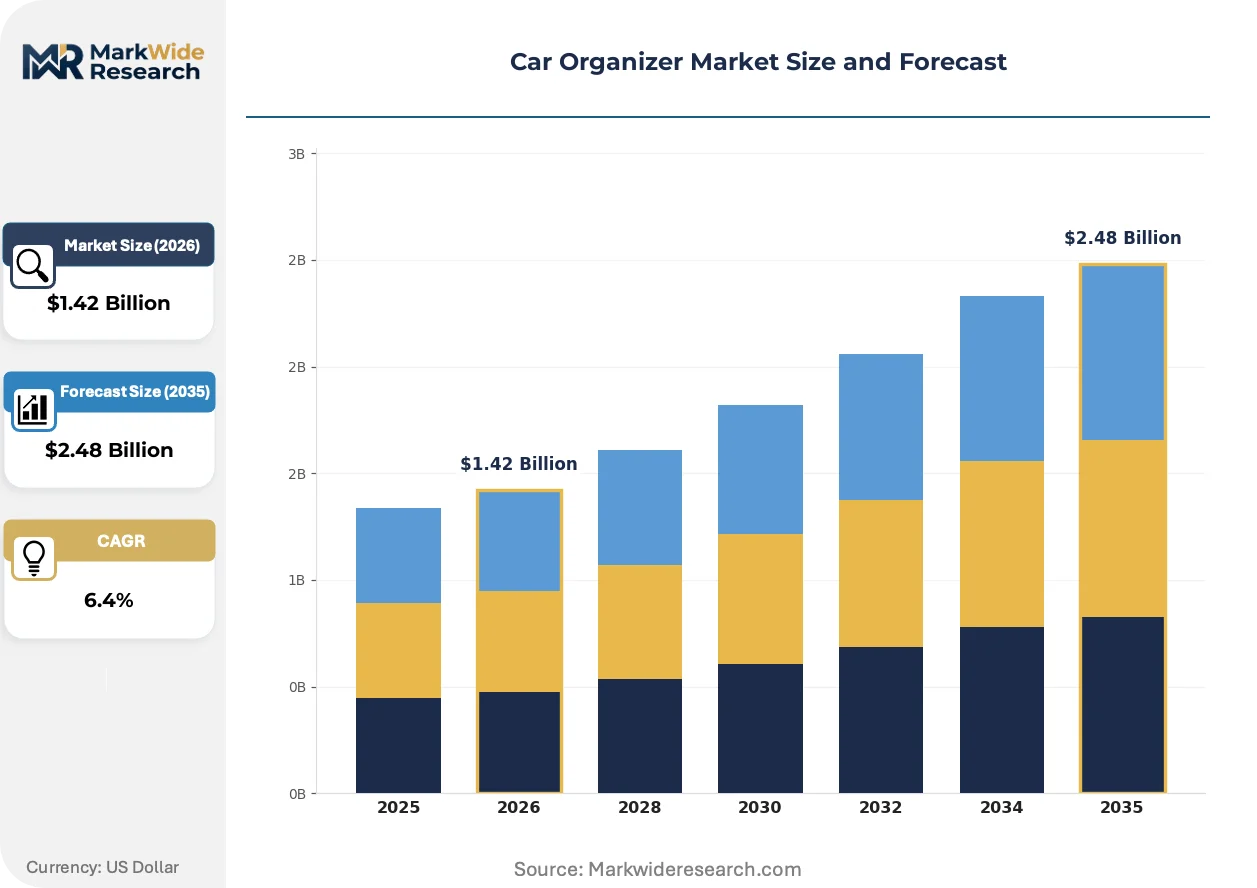
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trunk Organizer, Seat Organizer, Backseat Organizer, Dashboard Organizer Material: Canvas, Nylon, Polyester, Leather Feature: Water-Resistant, Foldable, Adjustable, Multi-Compartment End User: Families, Travelers, Professionals, Ride-Sharing Drivers |
| Companies Covered | Lund, Covercraft, WeatherTech, Du-Ha, Dee Zee, Rugged Ridge, Smittybilt, Go Rhino, Bestop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Organizer Market Trends and Innovations
Active materials research and regulatory chemistry shifts are redefining performance benchmarks for vehicle interior storage, while procurement centralization among fleet operators is collapsing traditional wholesale channels.
Recycled ocean-bound polyester is decomposing virgin polymer cost structures in premium organizer lines. Ride-sharing fleet managers in California and Texas are specifying 50%+ recycled content thresholds in RFPs. This material transition is decomposing established supplier hierarchies as Vietnamese and Indonesian mills capture share from legacy Chinese producers.
EU REACH Annex XVII restrictions on azo dyes are forcing textile finishers to migrate toward enzymatic treatment processes. German KBA type-approval documentation now requires full chemical disclosure for aftermarket cabin accessories. Seat-back organizer categories face the steepest compliance burden, with Dutch and Belgian distributors demanding batch-level traceability certificates.
Platform-controlled procurement is consolidating purchase authority among ride-sharing fleet administrators. Individual driver discretionary spending on cabin accessories is collapsing as Uber and Lyft issue standardized equipment kits. This channel shift concentrates demand in Illinois, Georgia, and Arizona where major fleet service hubs operate direct vendor relationships.
Car Organizer Market Segmentation
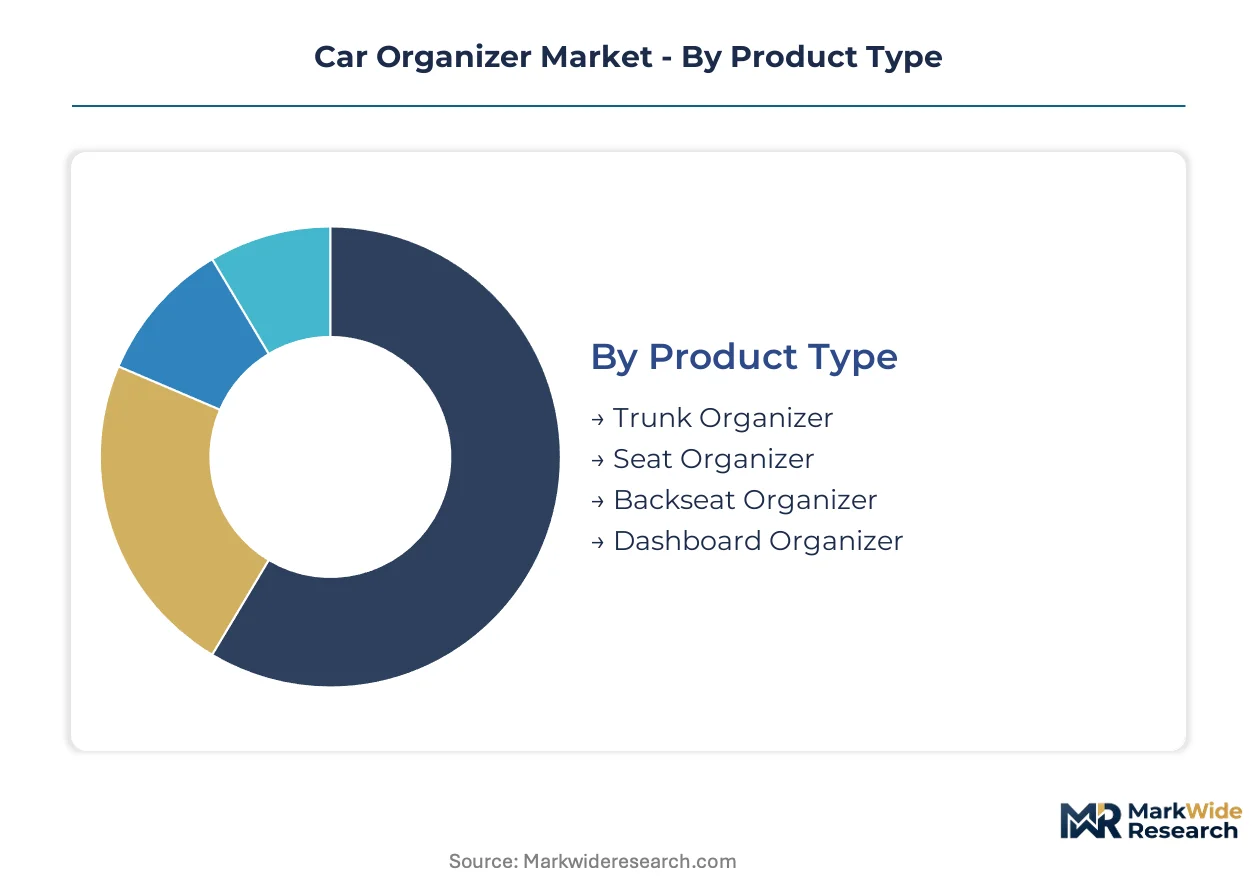
Car organizer manufacturers face divergent technical requirements across vehicle architectures and user workflows. Segmentation reveals where polyester resin volatility intersects with gig-economy procurement standardization.
Product Type:
Domestic consumption in the United States concentrates in trunk and backseat configurations, while export demand from European fleet operators favors seat organizers with sanitization-grade surfaces.
- Trunk Organizer:Vacuum-formed polypropylene bases with collapsible fabric walls dominate SUV and crossover fitments. Demand clusters in Texas and Arizona suburban corridors where long-commute cultures sustain bulk cargo management needs.
- Seat Organizer:Backrest-mounted configurations with tablet sleeves and insulated bottle pockets capture margin premiums. German KBA type-approval documentation requirements favor suppliers with batch-level chemical traceability.
- Backseat Organizer:Child safety seat integration drives multi-compartment geometries with reinforced anchor points. California Proposition 65 compliance costs elevate pricing for vinyl-laminated variants.
- Dashboard Organizer:Silicone-lined trays with anti-slip mats serve document and electronics storage. Compact dimensions limit material cost exposure to petrochemical volatility.
Trunk organizers command the established base. The steepest expansion runs through backseat configurations.
Material:
Cost tier stratification separates commodity synthetics from leather aftermarket premiums, with recycled content thresholds emerging as a procurement differentiator.
- Polyester:Abrasion-resistant woven construction with dye-stable coloration anchors volume production. Zhejiang province contract manufacturers face margin compression from PTA and MEG feedstock price swings.
- Nylon:Laminated vinyl treatments face California Proposition 65 reformulation mandates. EU REACH Annex XVII azo dye restrictions accelerate migration toward enzymatic finishing processes.
- Canvas:Heavy-duty cotton-poly blends with reinforced stitching serve commercial vehicle segments. Weatherproofing specifications from Bangalore scooter delivery fleets drive coating innovation.
- Leather:Full-grain and bonded variants occupy executive vehicle aftermarket tiers. Executive cabin aesthetic matching sustains pricing power despite synthetic alternatives.
Polyester maintains volume leadership. Recycled ocean-bound polyester variants are gaining share fastest among California and Texas ride-sharing fleet specifications.
Feature:
Application-specific functionality determines procurement channel access, with fleet standardization favoring sanitization-compatible specifications over consumer convenience features.
- Multi-Compartment:Modular divider systems with RFID-tagged pockets enable logistics contractor inventory tracking. Uber and Lyft standardized equipment kits specify compartment count minimums.
- Water-Resistant:PU-coated fabrics and welded seam construction serve outdoor recreation and food delivery segments. Dutch distributors demand full chemical disclosure for coating compounds.
- Foldable:Collapsible frames with quick-release mechanisms address space-constrained urban parking. Indian two-wheeler under-seat adaptations require compact stowage profiles.
- Adjustable:Velcro and buckle-based fitment systems accommodate non-standard trunk geometries. Electric vehicle architecture fragmentation complicates universal sizing.
Multi-compartment designs anchor commercial procurement. Water-resistant specifications are climbing the fastest as delivery fleet sanitization protocols harden.
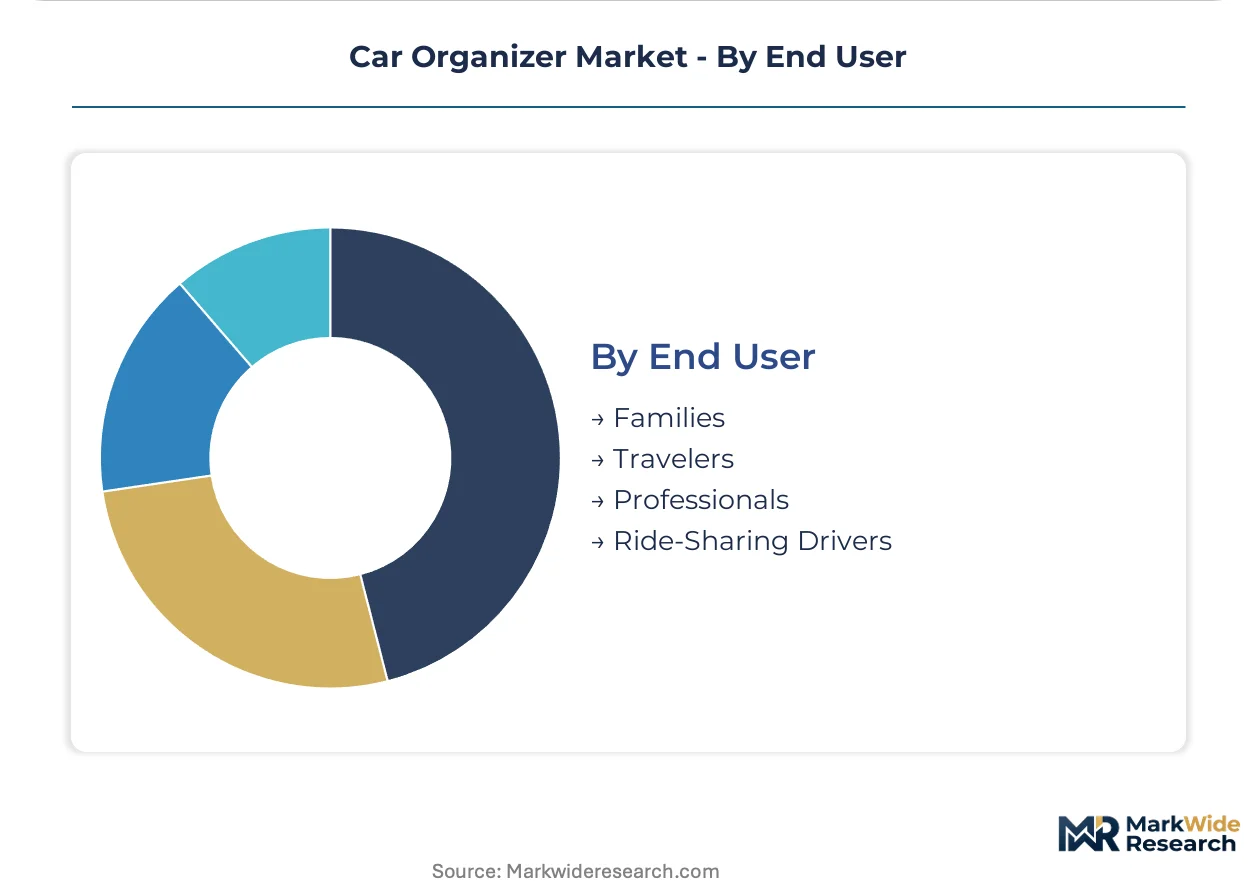
End User:
Customer type bifurcation separates discretionary retail purchases from institutional fleet procurement, with platform-controlled buying collapsing traditional wholesale channels.
- Ride-Sharing Drivers:Gig-economy fleet operators in Illinois, Georgia, and Arizona service hubs issue standardized equipment kits. Individual driver discretionary spending on cabin accessories is collapsing.
- Families:Suburban vehicle ownership in United States metropolitan corridors sustains trunk and backseat organizer demand. Child safety seat integration requirements drive premium configuration purchases.
- Professionals:Executive transport standards favor leather variants with cabin aesthetic matching. FMVSS 302 flammability certification timelines delay product launches.
- Travelers:Road-trip culture and rental vehicle use patterns favor compact foldable designs. Seasonal demand concentration complicates inventory planning.
Families retain the installed base. Ride-sharing drivers are expanding most quickly as platform procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract manufacturers cluster in Zhejiang province, Vietnam, and Indonesia, with polyester resin supply chains threading through petrochemical hubs in China and Southeast Asia. Demand-side procurement centralizes among ride-sharing fleet operators in Illinois, Georgia, and Arizona, while suburban family purchases sustain trunk organizer volumes across Texas and Arizona corridors.
United States
Suburban vehicle ownership and long-commute cultures sustain trunk and backseat organizer purchases across Texas and Arizona metropolitan corridors. The EPA regulates volatile organic compound emissions from adhesive bonding processes in organizer assembly. California's Proposition 65 mandates explicit labeling for phthalate-containing vinyl components, forcing reformulation across nylon-laminated product lines manufactured in Los Angeles-area facilities.
Germany
German KBA type-approval documentation now requires full chemical disclosure for aftermarket cabin accessories, elevating compliance burdens for seat-back organizer categories. EU REACH Annex XVII restrictions on azo dyes are forcing textile finishers to migrate toward enzymatic treatment processes. Dutch and Belgian distributors demanding batch-level traceability certificates source through Rhine-Ruhr industrial clusters.
China
Zhejiang province contract manufacturers face margin compression from PTA and MEG feedstock price swings destabilizing polyester fabric costing models. The country's national chemical regulator enforces GB standards for textile flammability in automotive applications. Ningbo and Wenzhou industrial zones host sewing-floor operations transitioning to automated cutting systems amid pattern digitization skills gaps.
Vietnam
Recycled ocean-bound polyester variants are gaining share fastest among California and Texas ride-sharing fleet specifications, decomposing established supplier hierarchies. Vietnamese mills capture share from legacy Chinese producers as recycled content thresholds harden in procurement RFPs. Ho Chi Minh City and Hanoi manufacturing corridors specialize in woven synthetic textile production for export-oriented organizer lines.
India
Scooter delivery fleets in Bangalore and Mumbai represent untapped demand for under-seat storage systems with weatherproofing specifications. The Bureau of Indian Standards monitors textile quality parameters for automotive accessory imports. Tamil Nadu and Gujarat industrial belts develop coating innovations for canvas-poly blends serving commercial vehicle segments.
Car Organizer Market Competitive Landscape
Concentration sits with domestic manufacturing specialists and vertically integrated textile converters. The vendor base spans three distinct tiers: premium all-weather system fabricators, mid-market nylon-laminated producers, and commodity polyester assemblers. Strategic differentiation runs through domestic manufacturing footprints, recycled content certification, and fleet procurement channel access. Competitive moves center on M&A to secure vertical control over resin supply and strategic partnerships with ride-sharing platform administrators.
Within the domestic manufacturing tier, WeatherTech and Covercraft exemplify divergent positioning strategies. WeatherTech leverages its domestic manufacturing footprint to sustain premium positioning in all-weather trunk systems. Covercraft anchors its competitive stance through specialized seat-back configurations. Among diversified automotive accessory specialists, Lund and Du-Ha occupy positions reflecting scale-driven production capabilities across multiple vehicle fitment categories.
| Leading Market Players |
|---|
| Lund |
| Covercraft |
| WeatherTech |
| Du-Ha |
| Dee Zee |
| Rugged Ridge |
| Smittybilt |
| Go Rhino |
| Bestop |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates above 85% at Zhejiang province contract manufacturers compress margin buffers for polyester fabric producers while simultaneously elevating price floors for West Coast distributors facing California Proposition 65 compliance costs. This scale-driven supply concentration grants volume leaders procurement leverage over PTA and MEG feedstock suppliers, yet fragments pricing power across tiered buyer segments with divergent specification tolerances.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from retail channel transactions, with three-tier pricing stratification across premium all-weather systems, standard nylon-laminated configurations, and economy polyester assemblers. Price differentiation hinges on recycled content certification thresholds and FMVSS 302 flammability compliance status, with California and Texas ride-sharing fleet administrators commanding steepest discounts through centralized RFP processes. Cost compression in the standard tier intensifies as Vietnamese mills displace legacy Chinese suppliers on recycled ocean-bound polyester specifications. Families purchasing through suburban retail channels exhibit highest price sensitivity, while executive transport professionals demonstrate lowest elasticity for leather aftermarket variants.
Supply Chain Analysis
China, Vietnam, and Indonesia anchor woven synthetic textile production for car organizer assembly, with Zhejiang province and Ho Chi Minh City manufacturing corridors specializing in polyester fabric conversion and automated cutting operations. Raw material flows draw from PTA and MEG petrochemical hubs in East Asia, with coated fabric finishing dependent on PU and vinyl laminate suppliers subject to REACH Annex XVII and Proposition 65 chemical restrictions. Single-source vulnerability concentrates in enzymatic treatment process chemicals as EU azo dye prohibitions force supplier transitions. Distribution runs through direct vendor relationships with Illinois, Georgia, and Arizona fleet service hubs, bypassing traditional wholesale channels for platform-controlled procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among ride-sharing fleet administrators as Uber and Lyft procurement centralization collapses individual driver discretionary spending, fragmenting incumbent pricing power across institutional and retail channels.
For Market Incumbents: Compound defensive positioning through backward integration into recycled polyester resin supply and captive certification laboratory capacity to neutralize Vietnamese mill cost advantages on ocean-bound content specifications. Prioritize FMVSS 302 testing queue placement to compress 4-6 month launch delays threatening backseat configuration market share against emerging polypropylene thermoforming substitutes. For New Entrants and Emerging Players: Fleet telematics integration services represent the most penetrable white-space layer as incumbent manufacturers lack software competency for RFID-tagged compartment development. Target Bangalore and Mumbai scooter delivery fleets with weatherproofed under-seat storage systems, leveraging canvas-poly blend coating innovations from Tamil Nadu industrial partnerships to establish beachhead before organized competitors reconfigure for two-wheeler geometries. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet procurement platform administrators with multi-year equipment kit contracts, positioning contract manufacturers with direct Uber and Lyft vendor relationships as superior cash-flow quality targets versus retail-dependent brand owners. Monitor California Proposition 65 chemical restriction cascades as inflection signal: state-level labeling mandates beyond federal baselines would force asset revaluation across West Coast supplier networks and create distressed acquisition opportunities among non-compliant nylon-laminated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification Investment | California and Texas fleet RFPs now mandate 50%+ ocean-bound polyester thresholds, disqualifying virgin polymer suppliers. |
| Automated Cutting System Deployment | Ningbo and Wenzhou sewing-floor operations reduce pattern digitization skills gaps compressing design cycle timelines. |
| Fleet Platform Direct Vendor Relationship | Illinois, Georgia, and Arizona service hub procurement centralization bypasses traditional wholesale margin extraction. |
| Enzymatic Treatment Process Migration | EU REACH Annex XVII azo dye restrictions force textile finishers toward German KBA-compliant chemical disclosure systems. |
| Polypropylene Thermoforming Capacity Addition | Vacuum-formed inserts displace stitched fabric in commercial segments requiring sanitization durability against COVID-era fleet protocols. |
Research Methodology
Desk research of customs trade records, EPA enforcement actions, and EU ECHA regulatory filings preceded structured interviews with Tier 1 automotive accessory procurement managers, Zhejiang province contract manufacturing executives, California ride-sharing fleet administrators, and Dutch distributor compliance officers. Primary fieldwork with platform-controlled buying organizations validated secondary estimates of SKU proliferation rates and design cycle compression. Bottom-up triangulation across polyester resin input costs and top-down validation against vehicle production databases anchored volume forecasts.
Variance-decomposition framing isolated segment-specific growth trajectories across product type, material composition, and end-user archetype dimensions throughout the forecast period. CAGRs were derived from modeled unit economics intersecting with fleet standardization protocols and family vehicle ownership patterns. Industry-specific inputs included FMVSS 302 certification timeline distributions and recycled content procurement threshold evolution from California and Texas fleet RFP documentation.
Forecasts assume regulatory continuity in EPA VOC emission standards and EU REACH Annex XVII chemical restrictions; material policy shifts such as expanded state-level Proposition 65 cascades or GB standard textile flammability amendments would require re-modeling. Recalibration cycles align with material shifts in petrochemical feedstock pricing, fleet procurement centralization milestones, and electric vehicle architecture standardization outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Cup Holder Market
Automotive Interior & Exterior
Automotive Door Frame Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Automotive Automatic Liftgate Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Lighting Molds Market