
 Automotive Decorative Exterior Trim Market | 2026-2036
Automotive Decorative Exterior Trim Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Decorative Exterior Trim Market Analysis
ISO/TS 16949 qualification is collapsing the supplier base for decorative exterior trim programs, forcing Tier-2 stampers and injection molders to consolidate or exit. Magna International leverages captive thermoplastic composite capacity to secure bumper and grille contracts with Detroit automakers. SRG Global sustains chrome plating leadership through vertical control of its Bowling Green, Kentucky finishing lines. Motherson Group anchors rear spoiler supply for European SUVs through dedicated plants in Germany and Spain.
Automotive decorative exterior trim comprises body-color and bright-finish components—bumpers, grilles, spoilers, and window trim—typically manufactured through injection molding, thermoforming, or metal stamping with subsequent painting, plating, or physical vapor deposition to achieve Class A surface specifications. These components serve both aerodynamic and brand-identity functions, with grilles functioning as primary visual signatures for OEM brand differentiation. Plastic dominates material selection for weight reduction, though metal retains share in premium grilles and window trim where cold-touch perception commands price premiums. OEM installation channels capture the majority of value, while aftermarket demand for collision repair and personalization sustains secondary volume.
FDA indirect food-contact regulations influence interior-adjacent trim chemistry, though exterior trim faces stricter EPA VOC emission limits on coating processes and NHTSA pedestrian-impact standards that reshape bumper energy-absorption geometry. ECHA REACH restrictions on hexavalent chromium plating accelerate supplier migration to trivalent chrome and PVD alternatives. Stakeholders must monitor how EPA coating rules and ECHA substance restrictions will reshape material qualification timelines and capital deployment decisions.
Market Dynamics
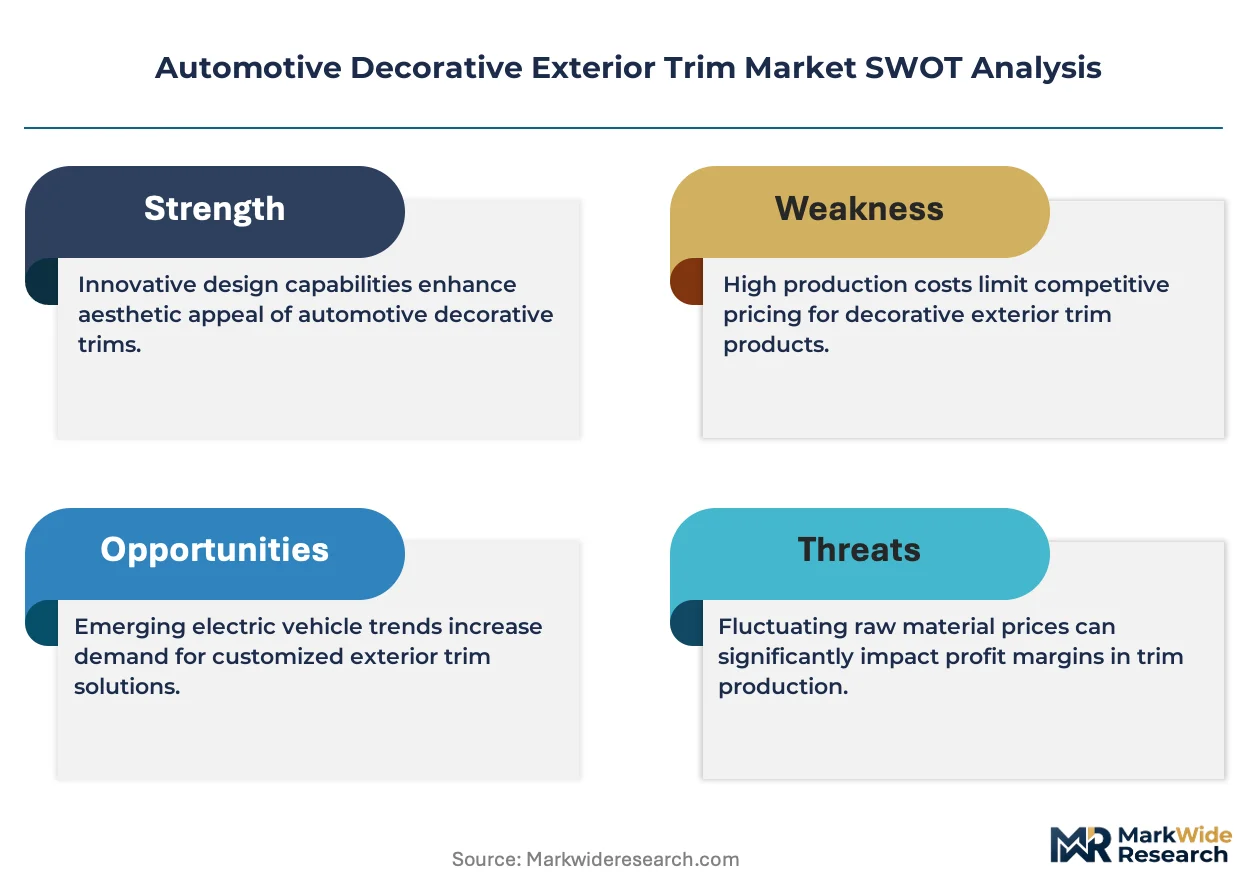
Surface-finishing chemistry regulations are compressing supplier margins while simultaneously creating qualification barriers that favor capital-intensive producers with captive plating and coating infrastructure.
Growth Catalysts
- ECHA REACH substance restrictions:Phased hexavalent chromium bans across EU member states are accelerating supplier transitions to trivalent chrome and PVD alternatives, creating replacement demand for compliant finishing lines.
- Luxury SUV production clustering:Premium German and US automakers are expanding dedicated SUV platforms with distinctive grille and bumper programs that require Class A decorative trim at higher unit values.
- Physical vapor deposition:PVD coating technology is penetrating mid-market vehicle segments as OEMs seek chrome alternatives that satisfy both environmental compliance and visual differentiation requirements.
Market Restraints
- Specialized resin supply concentration:Engineering-grade polymers for exterior trim face input cost volatility due to concentrated production of weatherable ABS and PC/ABS blends among Asian petrochemical suppliers.
- Plating wastewater treatment capex:EPA VOC emission limits and state-level discharge permits impose capital intensity on chrome finishing operations, structurally disadvantaging smaller independent job shops.
- Aluminum substitution in window trim:Cold-form aluminum extrusions are displacing plated plastic in premium sedan segments where tactile metal perception commands price premiums.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive parts are attracting decorative trim investment toward Gujarat and Tamil Nadu manufacturing corridors.
- Collision repair channel digitization:Insurance-tied body shop networks are consolidating parts procurement, creating direct-supply opportunities for certified aftermarket trim producers.
- China dual carbon goals:Provincial MEE enforcement of carbon intensity benchmarks is accelerating demand for lightweight plastic trim that supports OEM fleet efficiency compliance.
Industry Challenges
- ISO/TS 16949 migration timeline:Tier-2 stampers and injection molders face compressed recertification windows as IATF 16949 supersedes legacy quality standards, forcing documentation system overhauls.
- Paint-shop color-matching precision:Body-color bumper programs require spectrophotometric consistency across multiple production sites, straining supply chain quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Decorative Exterior Trim Market |
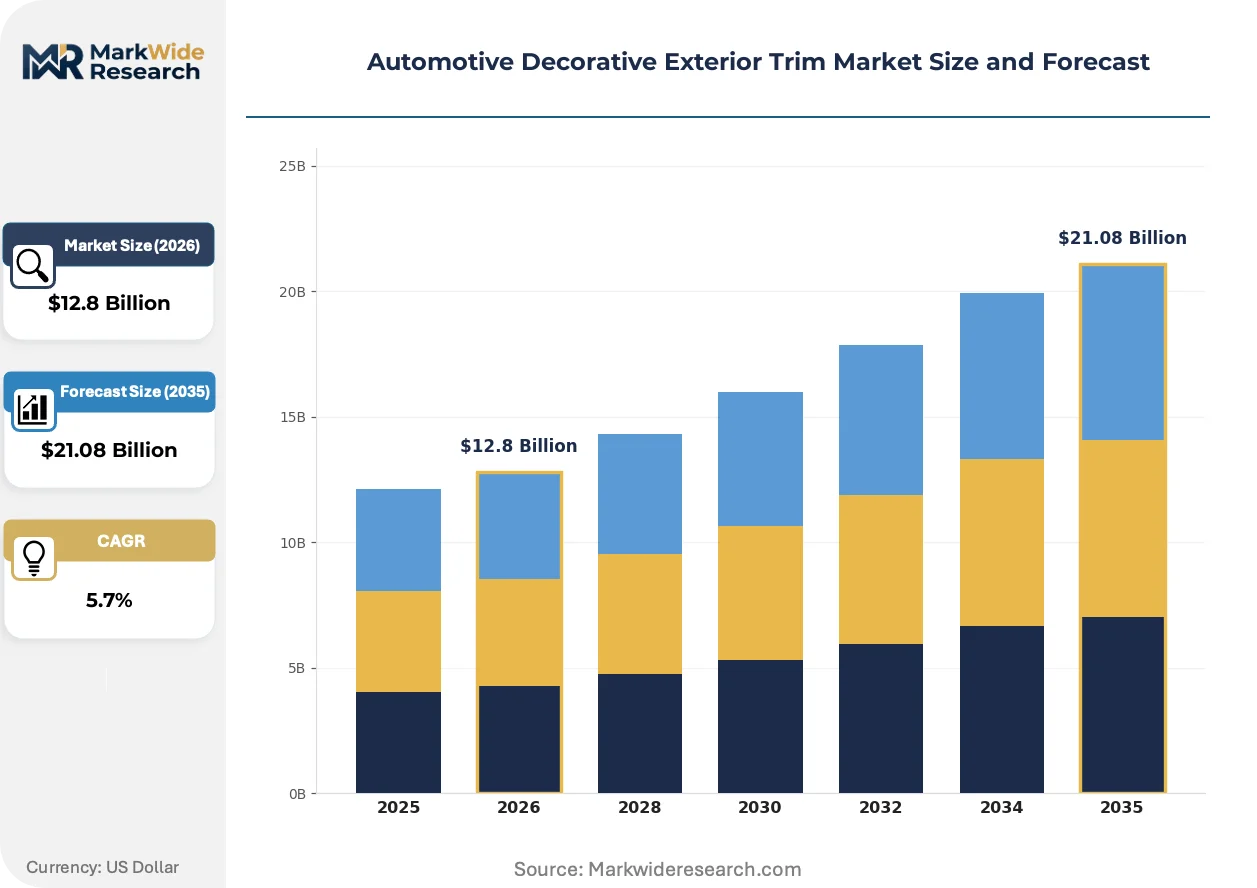
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bumpers, Grilles, Spoilers, Window Trim Material: Plastic, Metal, Composite, Rubber Installation Type: OEM, Aftermarket, Temporary, Permanent Vehicle Type: SUVs, Sedans, Trucks, Coupes |
| Companies Covered | Magna International, Flex-N-Gate, SRG Global, CIE Automotive, Motherson Group, Adler Pelzer, Plasman, Rehau Automotive, Toyoda Gosei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Decorative Exterior Trim Market Emerging Trajectories
Active grille shutter integration and illuminated signature elements are redefining component boundaries, merging aerodynamic function with brand-expression lighting in ways that reshape supplier technical requirements.
Thermoplastic composites with Class A surface capability are fragmenting traditional metal-stamping and injection-molding supplier roles. Magna International and similar integrators are adopting long-fiber thermoplastic formulations for bumper beams and grille carriers. This material convergence is compressing the addressable market for standalone metal formers while expanding contract scope for composite-capable Tier-1s.
EPA coating rules on hazardous air pollutants are tightening permissible VOC thresholds for automotive painting operations. Facilities in Michigan and Ohio are retrofitting thermal oxidizers and switching to waterborne basecoats. The regulatory pressure falls heaviest on independent finishing job shops serving aftermarket channels, which lack capital for abatement equipment.
Fleet procurement centralization among US and German leasing companies is consolidating aftermarket trim demand through certified collision networks. Traditional jobber distribution is losing share to direct OEM parts programs and insurance-preferred supplier agreements. This channel compression is most visible in Florida and California, where total-loss thresholds and repair-cost caps accelerate parts standardization.
Automotive Decorative Exterior Trim Market Segmentation
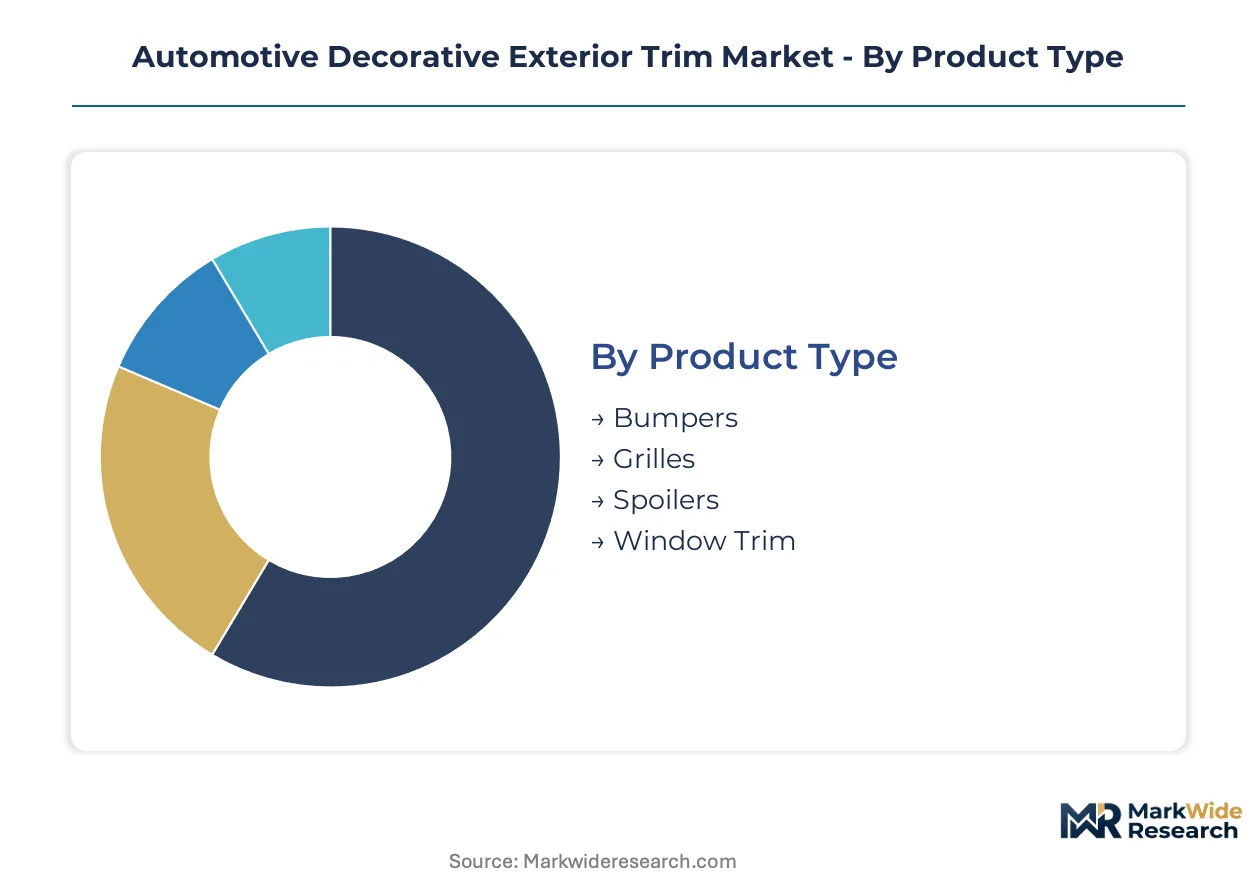
Automotive decorative exterior trim segments diverge sharply in margin structure, with surface-finish complexity and OEM certification requirements determining profitability pools. Material chemistry and installation channel access create distinct competitive territories that reshape supplier positioning across vehicle platforms.
Product Type:
Grille and bumper programs concentrate the highest unit values due to Class A surface specifications and brand-identity functionality.
- Grilles:Primary visual signatures for OEM brand differentiation, requiring precision injection molding or metal stamping followed by chrome plating or PVD finishing. German luxury automakers and Detroit SUV platforms drive specification intensity for active grille shutter integration.
- Bumpers:Large-format components merging energy-absorption engineering with decorative surface requirements. ECHA REACH hexavalent chromium restrictions and NHTSA pedestrian-impact standards are accelerating material transitions to compliant thermoplastic composites.
- Spoilers:Aerodynamic add-ons with secondary styling function, typically manufactured through thermoforming or reaction injection molding.
- Window Trim:Cold-touch perception commands price premiums in premium sedan segments, though aluminum extrusions are displacing plated plastic in upper tiers.
Grille programs hold installed capacity. Spoilers are rotating up the share rankings as SUV roofline personalization expands.
Material:
Cost tier stratification separates commodity resins from engineered composites with weatherable surface specifications.
- Plastic:ABS and PC/ABS blends dominate weight-reduction mandates, with weatherable grades from Asian petrochemical suppliers facing input cost volatility. China's GB standards for automotive plastics and EPA VOC emission limits on coating processes tighten qualification timelines.
- Metal:Cold-touch perception retains share in premium grilles and window trim. Trivalent chrome and PVD alternatives are gaining traction as ECHA REACH restrictions on hexavalent chromium plating accelerate supplier migration.
- Composite:Long-fiber thermoplastic formulations fragment traditional metal-stamping roles, with Magna International and similar integrators securing bumper beam contracts through captive composite capacity.
- Rubber:Limited to impact-resistant lower fascia elements and protective trim strips with lower surface-finish requirements.
Plastic commands volume leadership. Composite is climbing the fastest as material convergence reshapes supplier roles.
Installation Type:
Customer type determines channel economics, with OEM direct supply capturing certification premiums and aftermarket serving collision repair and personalization demand.
- OEM:Direct installation at vehicle assembly plants requires IATF 16949 qualification and spectrophotometric color-matching precision across multiple production sites. Detroit automakers and premium German manufacturers anchor contract values.
- Aftermarket:Insurance-tied body shop networks are consolidating procurement, creating direct-supply opportunities for certified producers in Florida and California collision corridors.
- Temporary:Clip-on accessories and protective films serving lease-return preparation and short-term personalization.
- Permanent:Adhesive-bonded or mechanically fixed upgrades requiring professional installation and paint-shop integration.
OEM channels hold certification barriers. Aftermarket is gaining share fastest as fleet procurement centralization reshapes distribution.
Vehicle Type:
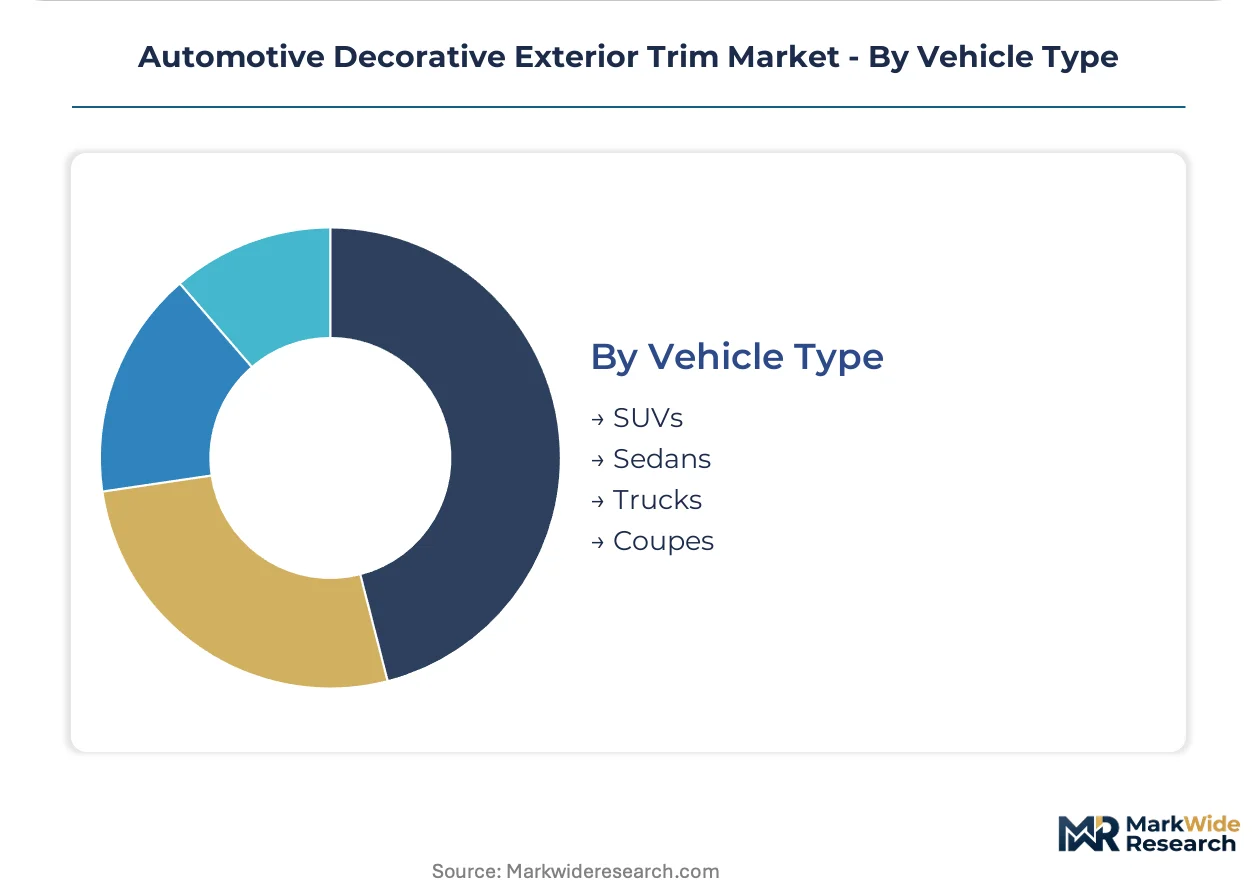
Application intensity varies by platform architecture, with SUV expansion programs driving the steepest trim specification increases.
- SUVs:Higher beltlines and distinctive front-end proportions multiply grille and bumper surface area per vehicle. Dedicated platform expansion by German and US premium automakers concentrates demand in Michigan, Alabama, and South Carolina assembly corridors.
- Sedans:Traditional three-box proportions emphasize window trim and lower-body brightwork, with aluminum substitution accelerating in premium segments.
- Trucks:Commercial and lifestyle pickup variants require durable finishes resistant to gravel impact and UV degradation.
- Coupes:Low-volume specialty platforms with highest surface-finish specifications and personalization rates.
SUV applications anchor platform investment. Sedan trim is rotating down the share rankings as body-style mix shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and tightening environmental regulations are redirecting capital toward manufacturing corridors with compliant infrastructure and OEM assembly proximity.
United States
Detroit automakers and premium SUV platforms in Michigan, Alabama, and South Carolina drive grille and bumper specification intensity. EPA VOC emission limits on coating operations force thermal oxidizer retrofits at independent finishing shops. Bowling Green, Kentucky hosts concentrated chrome plating capacity serving domestic OEM programs.
Germany
Luxury sedan and SUV production clusters in Bavaria and Baden-Württemberg sustain premium window trim and active grille shutter demand. ECHA REACH hexavalent chromium restrictions accelerate supplier migration to trivalent chrome and PVD alternatives. Dedicated plants in Germany and Spain anchor rear spoiler supply for European SUV platforms.
China
Provincial MEE enforcement of carbon intensity benchmarks accelerates lightweight plastic trim adoption for OEM fleet efficiency compliance. GB standards for automotive plastics tighten material qualification timelines. Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate engineering-grade polymer processing for domestic and export programs.
India
The PLI scheme for auto components attracts decorative trim investment toward Gujarat and Tamil Nadu manufacturing corridors. BIS certification requirements for automotive plastics reshape supplier qualification protocols. Domestic SUV production expansion drives localized bumper and grille program development.
Japan
Precision injection molding expertise in the Nagoya-Chubu corridor supports high-specification grille programs for domestic and export luxury vehicles. METI industrial standards guide surface-finish chemistry transitions. Long-fiber thermoplastic composite development centers serve next-generation bumper beam architectures.
Automotive Decorative Exterior Trim Market Vendor Landscape
Listed leaders compete with private specialists across capital-intensive finishing infrastructure and IATF 16949 certification barriers. The supplier base compresses as ISO/TS 16949 migration timelines force Tier-2 stampers and injection molders to consolidate or exit. Three archetypes dominate: integrated Tier-1s with captive composite capacity, specialized finishers with vertical plating control, and regional molders serving aftermarket collision networks. Competitive moves center on backward integration into resin compounding and strategic partnerships for PVD technology licensing.
Within the integrated Tier-1 tier, Magna International and Motherson Group exemplify capital-intensive producers leveraging captive thermoplastic composite and dedicated regional plant networks. SRG Global occupies a position among specialized finishers with concentrated plating infrastructure. These three anchors represent distinct strategic positions—material convergence capability, geographic proximity to OEM assembly, and surface-finish chemistry compliance—rather than competing directly across identical value chain segments.
| Leading Market Players |
|---|
| Magna International |
| Flex-N-Gate |
| SRG Global |
| CIE Automotive |
| Motherson Group |
| Adler Pelzer |
| Plasman |
| Rehau Automotive |
| Toyoda Gosei |
| Others |
Supply Flow & Price Mechanics
Ninety-day resin inventory cycles at Asian petrochemical suppliers concentrate pricing power among engineering-grade ABS and PC/ABS blend producers, compressing margins for Tier-2 injection molders while amplifying leverage for captive compounders with backward integration into resin sourcing. This lead-time asymmetry between raw material availability and finished component delivery shapes how OEMs structure long-term supply agreements across bumper and grille programs.
Pricing Analysis
Certification level (IATF 16949-qualified versus uncertified) creates the primary spread between premium OEM contract rates and aftermarket spot pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by surface-finish complexity, with Class A chrome plating and PVD finishing commanding substantial premiums over painted alternatives. Cost compression in standard-grade thermoplastic components is intensifying because of concentrated Asian resin supply and EPA VOC compliance capex requirements. Aftermarket collision repair channels exhibit highest price sensitivity due to insurance cost caps, while luxury OEM direct supply shows lowest sensitivity given brand-identity premium allocation.
Supply Chain Analysis
Suez Canal transit disruptions and Red Sea routing alternatives expose European-bound container flows from Yangtze River Delta plating facilities to extended lead-time volatility. Geographic supply concentrates in China, Germany, and the United States, with engineering-grade polymer compounding anchored in Asian petrochemical corridors and Class A finishing capacity clustering in Kentucky and Bavaria. Raw material dependencies span weatherable ABS resins, chromium-based plating chemistry, and long-fiber thermoplastic pellets. Single-source vulnerability runs through hexavalent chromium alternative qualification timelines under ECHA REACH phased bans. Distribution runs through OEM direct supply agreements for new vehicle programs, with aftermarket channels consolidating through insurance-preferred collision networks in Florida and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive decorative exterior trim market sits in early-cycle recovery as SUV platform expansion programs by German and US premium automakers restock supplier order books following inventory destocking through prior periods.
For Market Incumbents: Fortify captive finishing infrastructure against plating chemistry transition risks by accelerating trivalent chrome and PVD capacity deployment before ECHA REACH enforcement windows tighten. Secure backward integration into weatherable resin compounding to offset Asian petrochemical supply concentration and input cost volatility. Prioritize IATF 16949 recertification completion ahead of compressed migration timelines to preserve OEM contract eligibility. For New Entrants and Emerging Players: Differentiate on PVD technology licensing partnerships that bypass capital-intensive plating infrastructure requirements while satisfying environmental compliance mandates. Target India's PLI scheme corridors in Gujarat and Tamil Nadu as the most penetrable geography, where domestic SUV production expansion outruns localized supplier capacity. Pursue direct-supply relationships with consolidating insurance-tied collision networks as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parents seeking to divest non-core automotive exposure, particularly European metal-forming operations with latent thermoplastic composite conversion capability. Long-term viability hinges on material convergence positioning and regulatory compliance infrastructure rather than commodity molding scale. Monitor ECHA REACH enforcement acceleration and EPA VOC threshold tightening as the critical inflection signal for valuation multiple expansion in compliant finishing assets.| Strategic Initiative | Industry Significance |
|---|---|
| PVD Technology Licensing Partnership | Enables mid-market suppliers to bypass hexavalent chromium capital constraints while meeting ECHA REACH compliance deadlines. |
| Backward Integration into Resin Compounding | Captive weatherable ABS supply insulates margin structures from Asian petrochemical price volatility. |
| IATF 16949 Recertification Acceleration | Preserves OEM contract eligibility as quality standard migration compresses the qualified supplier base. |
| India PLI Scheme Manufacturing Footprint | Positions suppliers for domestic SUV platform growth in Gujarat and Tamil Nadu assembly corridors. |
| Collision Network Direct Supply Agreements | Captures aftermarket consolidation as insurance-preferred procurement displaces traditional jobber distribution. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement directors, aftermarket collision network managers, and plating facility operations heads anchored the qualitative base for this analysis. Primary interview findings triangulated against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed automotive suppliers, and ECHA REACH substance restriction documentation. Bottom-up segment sizing across grille, bumper, spoiler, and window trim categories converged with top-down market value reconstruction from OEM program announcements and supplier contract disclosures.
Sensitivity analysis around resin price volatility scenarios and regulatory enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, surface-finish specification tier, installation channel, and regional production cluster. CAGRs derived from production volume trajectories, content-per-vehicle trends, and platform mix shifts rather than extrapolated historical rates. Forecast inputs incorporated active grille shutter penetration curves and PVD technology cost-reduction pathways.
Material uncertainties — ECHA REACH enforcement acceleration, EPA VOC threshold revisions, and Asian petrochemical supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about SUV platform expansion continuity and collision repair channel consolidation velocity. Practitioners should keep alternative scenarios live as regulatory chemistry restrictions and lightweighting mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Zero Gravity Seat Market