
 Asia-Pacific Car Cleaning Products Market | 2026-2036
Asia-Pacific Car Cleaning Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Car Cleaning Products Market Analytics
Waterless and rinseless wash technologies are reshaping product formulation priorities across the Asia-Pacific car cleaning sector. Soft99 Corp leverages its Japanese R&D base to sustain premium wax and coating lines that anchor high-margin segments in East Asian markets. Pidilite Industries Ltd competes through extensive distribution networks that dominate India's aftermarket channel, while 3M Co differentiates via proprietary polymer science that extends protection durability in tropical climates.
Asia-Pacific car cleaning products comprise formulated chemical solutions designed to remove contaminants, restore surface finish, and protect automotive substrates including clear coat, glass, leather, and plastic trim, typically operating within pH ranges of 6.5 to 9.5 to prevent substrate damage while incorporating surfactant packages, solvents, and functional polymers for specific substrate compatibility. Their primary commercial purpose centers on preserving vehicle residual value and satisfying owner aesthetic expectations in high-humidity, high-UV, and monsoon-exposure environments characteristic of the region. Shampoos and glass cleaners carry the highest volume throughput in car wash service channels, while upholstery cleaners capture expanding margin pools as interior detailing gains frequency among private owners in urban India and Vietnam. Waxes remain the most mature category with slower growth but stable replacement cycles, whereas exterior polishing applications show the fastest acceleration tied to ceramic coating prep workflows.
Japan's Ministry of Economy, Trade and Industry (METI) chemical substance frameworks and Australia's Department of Climate Change, Energy, the Environment and Water biosecurity protocols both restrict volatile organic compound thresholds and phosphate content in automotive cleaning formulations, compelling reformulation investments from suppliers seeking market access. India's Bureau of Indian Standards (BIS) labeling mandates for household and institutional chemicals add compliance layers for imported concentrates, while REACH-aligned substance restrictions in EU-exporting supply chains indirectly shape raw material availability for Asia-Pacific blenders. Stakeholders must monitor divergence between national chemical registers as regulatory fragmentation risks fragmenting formulation platforms across the region's largest consumer markets.
Market Dynamics
Waterless cleaning formulations are compressing traditional car wash infrastructure requirements across Southeast Asia, forcing chemical suppliers to reformulate surfactant packages for high-heat, low-water application environments while professional service chains retool labor deployment around spray-and-wipe protocols.
Growth Catalysts
- Australia's biosecurity protocols:Phosphate restrictions in automotive cleaning formulations are accelerating biodegradable surfactant R&D, opening premium positioning for compliant suppliers.
- Interior detailing frequency:Rising vehicle ownership among India's middle-income households is generating recurring demand for upholstery and leather conditioning solutions in tier-one cities.
- Ceramic coating prep workflows:Exterior polishing applications are displacing wax-only maintenance routines among professional detailers in Vietnam and Thailand.
Market Restraints
- Petrochemical feedstock volatility:Solvent and polymer input costs fluctuate with regional naphtha cracking capacity concentrated in South Korea and Singapore.
- Import concentrate dependency:India's BIS labeling mandates create compliance friction for EU-exporting supply chains seeking market access.
- Performance ceiling in tropical UV:Clear coat protection durability remains technically constrained versus temperate-climate benchmarks, limiting warranty extensions.
Strategic Opportunities
- Vietnam's urban detailing segment:Ho Chi Minh City and Hanoi show underpenetrated professional service density relative to vehicle stock growth.
- Japan's METI green procurement incentives:Government fleet maintenance contracts now preference low-VOC formulations, creating certified-supplier preference.
- Subscription replenishment models:Direct-to-consumer channels are capturing recurring interior cleaner purchases from private owners in Australia's capital cities.
Industry Challenges
- Formulation chemist scarcity:Asia-Pacific blenders compete for talent capable of navigating divergent national chemical registers across Japan, Australia, and India.
- REACH-aligned substance tracking:Raw material qualification timelines extend as EU-exporting suppliers impose documentation requirements cascading into regional supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Car Cleaning Products Market |
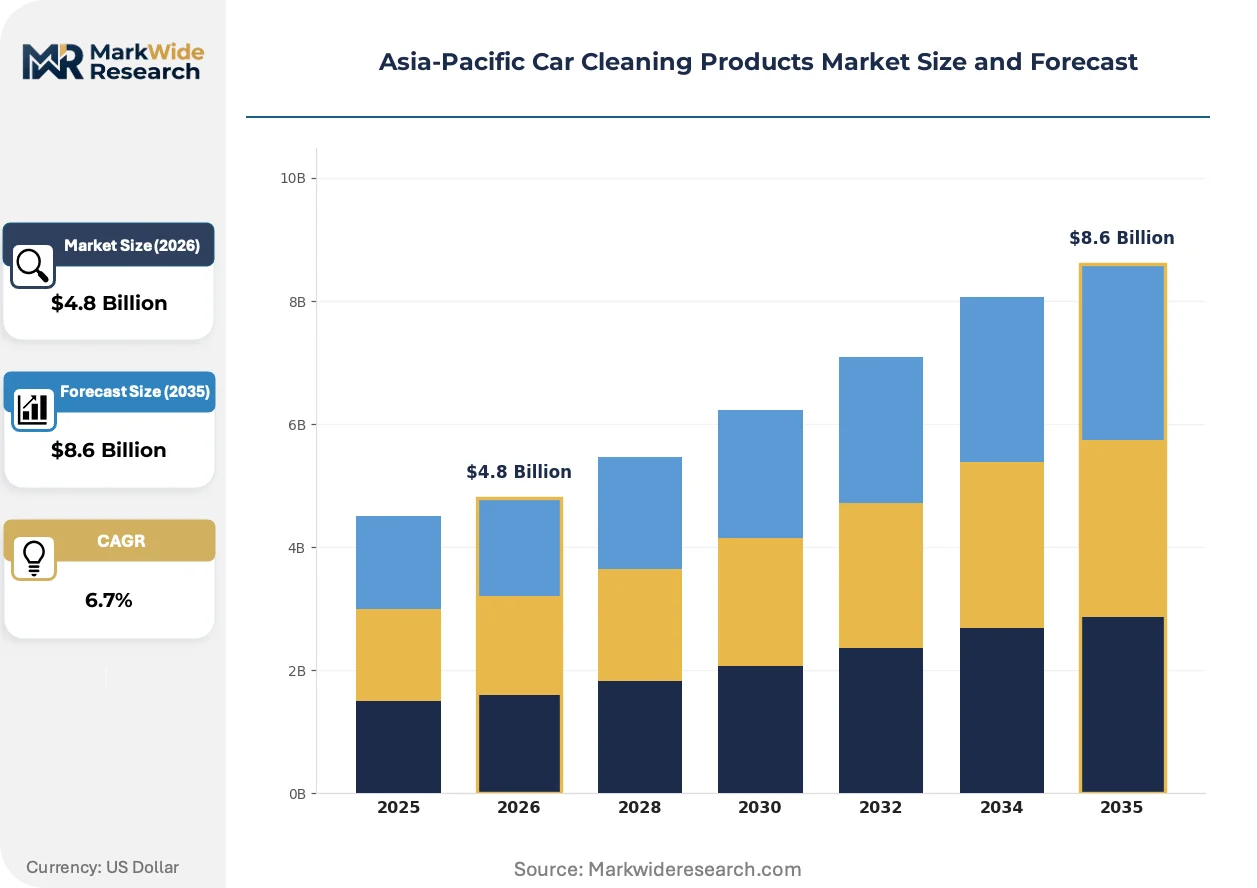
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Waxes, Glass Cleaners, Upholstery Cleaners Application: Automobile Maintenance, Vehicle Aesthetics, Interior Cleaning, Exterior Polishing End User: Private Owners, Car Wash Services, Dealerships, Fleet Operators Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | 3M Co, SONAX GmbH, Turtle Wax, Inc, Wurth Group, Tetrosyl Ltd, Soft99 Corp, Pidilite Industries Ltd, Cartec BV, Liqui Moly, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Car Cleaning Products Market Evolving Landscape
Formulation science and service delivery models are converging around water scarcity pressures and professional labor efficiency, compressing traditional wash-and-dry cycles into single-step chemical applications.
Ceramic-infused spray sealants are hybridizing conventional wax maintenance with long-term protection durability. Professional detailers in Thailand and Malaysia are adopting these products for express service menus that complete exterior treatment in under fifteen minutes. This hybridizing technology is collapsing the distinction between maintenance washes and protective coating applications, enabling service chains to capture higher ticket averages without bay capacity expansion.
Japan's METI chemical substance frameworks are tightening volatile organic compound thresholds for automotive cleaning products sold through commercial channels. Formulators must now recalculate solvent packages to maintain grease-cutting efficacy at reduced VOC loadings. Professional car wash operators in Osaka and Nagoya are responding by segregating compliant product lines for fleet contracts subject to green procurement audits.
Private vehicle owners in India's tier-one cities are compressing purchase cycles for interior cleaning solutions as ride-hailing drivers maintain stricter cabin hygiene standards. Traditional auto accessory retailers are ceding volume to quick-commerce platforms promising two-hour delivery of upholstery and glass cleaning kits. This behavioral shift is most visible in Mumbai and Bangalore where apartment parking constraints limit home washing infrastructure.
Asia-Pacific Car Cleaning Products Market Segmentation
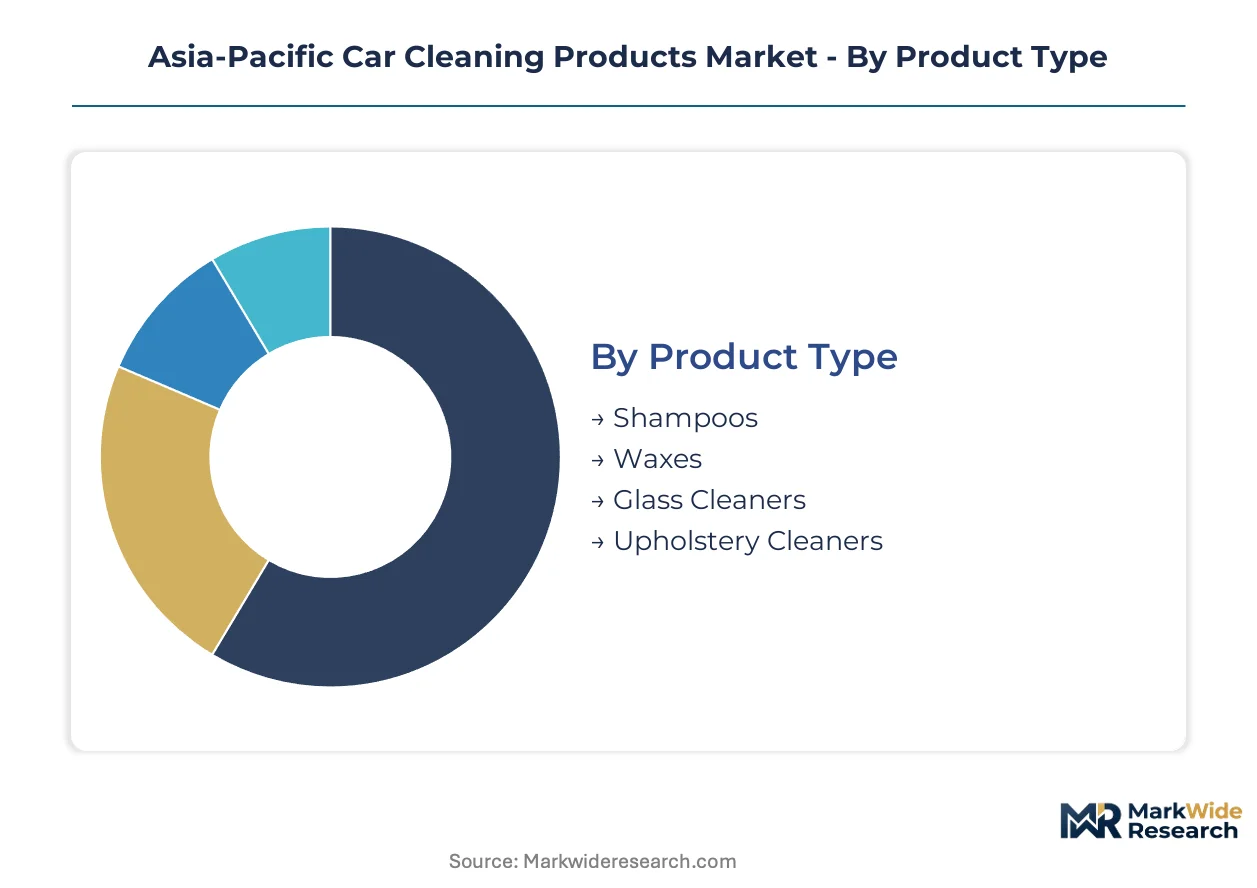
After-sales service intensity varies sharply across Asia-Pacific car cleaning segments. Professional service chains demand concentrated bulk formulations with technical support, while private owners prioritize convenience packaging and rapid replenishment. This divergence shapes formulation, pricing, and channel strategy for every supplier operating across the region.
Product Type:
After-sales service intensity peaks with products requiring technical application training and recurring replenishment schedules.
- Shampoos:Surfactant-based formulations operating at pH 6.5-8.5 to prevent clear coat etching. Car wash services in Vietnam and Thailand concentrate procurement here as bay throughput depends on foam density and rinse efficiency. Bulk concentrate formats dominate professional channels.
- Waxes:Carnauba and synthetic polymer blends delivering 30-90 day protection cycles. Demand concentrates among private owners in Australia's capital cities seeking DIY maintenance between professional detailing visits. Replacement cycles are predictable but elongating as ceramic alternatives gain traction.
- Glass Cleaners:Ammonia-free formulations for tinted window compatibility. Volume flows through car wash service channels across Southeast Asia where streak-free drying is a customer-visible quality signal.
- Upholstery Cleaners:Enzyme and solvent packages targeting leather, fabric, and synthetic substrates. Tier-one cities in India drive expansion as ride-hailing drivers maintain stricter cabin hygiene standards and quick-commerce platforms accelerate replenishment frequency.
Shampoos hold the largest share; momentum sits with upholstery cleaners.
Application:
Cost tier stratification separates premium protective treatments from commodity cleaning cycles.
- Automobile Maintenance:Routine washing and protection protocols preserving residual value. Fleet operators in Japan prioritize METI-compliant low-VOC formulations to secure green procurement contracts.
- Vehicle Aesthetics:Surface enhancement and gloss restoration treatments. Professional detailers in Ho Chi Minh City and Bangkok are expanding express service menus around ceramic-infused spray sealants that collapse wash and protection into single-step applications.
- Interior Cleaning:Cabin hygiene solutions for upholstery, plastics, and ventilation systems. Middle-income households in Mumbai and Bangalore are compressing purchase cycles as apartment parking constraints limit home washing infrastructure.
- Exterior Polishing:Paint correction and ceramic coating preparation workflows. This application is expanding most quickly among professional channels in Malaysia and Thailand where detailers capture higher ticket averages without bay capacity expansion.
Automobile maintenance captures the volume base; exterior polishing shows the steepest expansion trajectory.
End User:
Customer type determines formulation concentration, packaging format, and technical support requirements.
- Private Owners:Individual vehicle households purchasing retail-packaged solutions. Australia's capital cities show rising subscription replenishment for interior cleaners as direct-to-consumer channels capture recurring purchases.
- Car Wash Services:Professional bay operators procuring bulk concentrates with dilution systems. Southeast Asian chains are retooling labor deployment around waterless spray-and-wipe protocols under environmental compliance pressure.
- Dealerships:New and used vehicle preparation services requiring consistent finish quality. Volume concentrates in India's tier-one cities where pre-delivery detailing is standard for mid-segment vehicle sales.
- Fleet Operators:Commercial vehicle pools with scheduled maintenance programs. Japan's government fleet contracts now preference certified low-VOC suppliers under METI green procurement frameworks.
Car wash services command the largest procurement volumes; fleet operators are tightening compliance requirements fastest.
Distribution Channel:
Volume concentration versus margin capture splits channel strategy across the region.
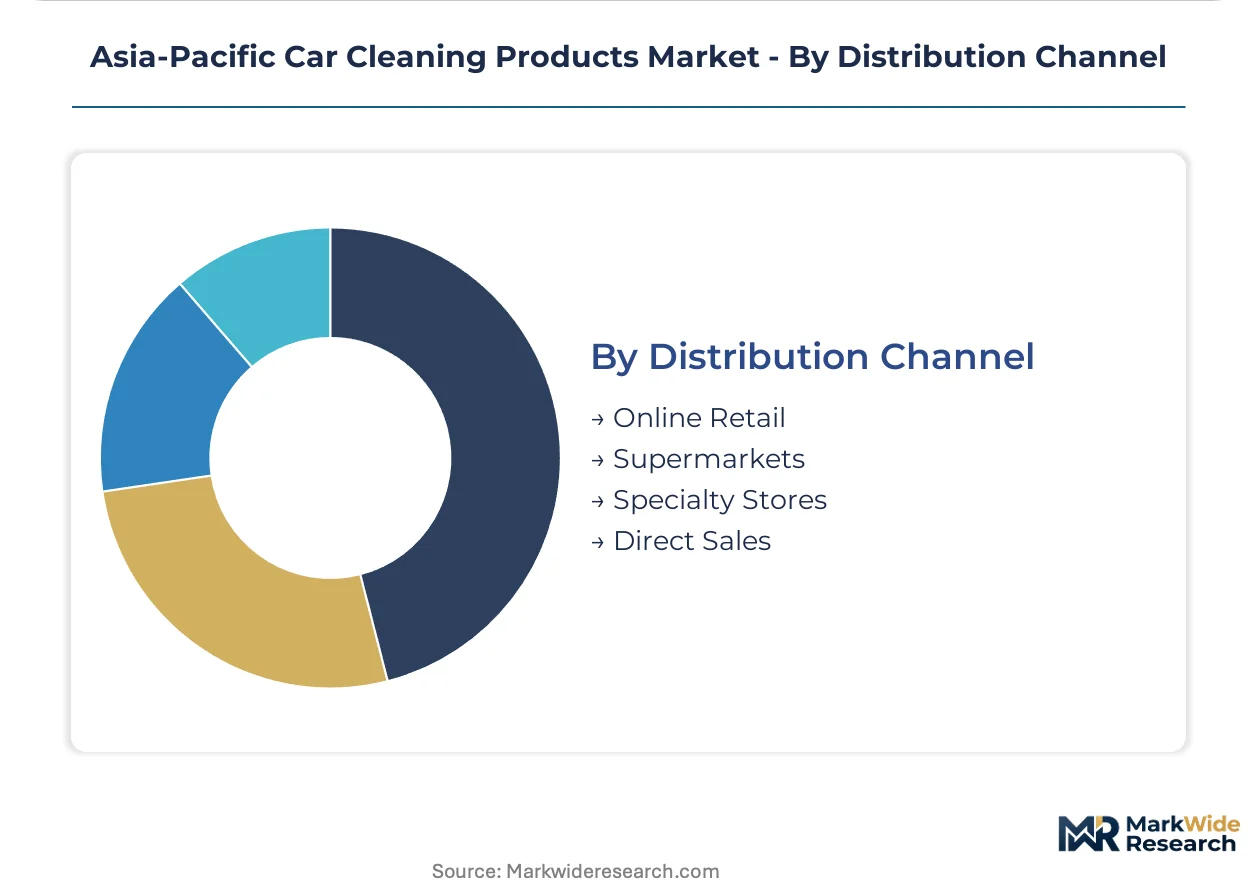
- Online Retail:Direct-to-consumer platforms with rapid fulfillment promises. Quick-commerce growth in Mumbai and Bangalore is displacing traditional auto accessory retailers for interior cleaning kits.
- Supermarkets:Mass-market shelf placement for commodity formulations. Australia's major chains carry biodegradable surfactant lines compliant with phosphate restrictions under biosecurity protocols.
- Specialty Stores:Technical product assortment with staff expertise. Professional detailers in Osaka and Nagoya source compliant product lines here for fleet contracts subject to green procurement audits.
- Direct Sales:Bulk concentrate and equipment packages for service chains. Concentration is highest in Vietnam where urban detailing penetration lags vehicle stock growth.
Supermarkets move the highest unit volumes; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional car wash services and private vehicle owners across Asia-Pacific drive divergent procurement patterns, with fleet operators in Japan and ride-hailing drivers in India compressing purchase cycles for distinct formulation categories.
Japan
Fleet maintenance contracts from government and corporate pools sustain premium demand for low-VOC formulations. METI chemical substance frameworks tighten volatile organic compound thresholds, compelling reformulation investments from suppliers seeking commercial channel access. Osaka and Nagoya host professional car wash operators segregating compliant product lines for green procurement audits.
India
Middle-income households in Mumbai and Bangalore generate recurring upholstery cleaner purchases as apartment parking constraints limit home washing infrastructure. BIS labeling mandates for household and institutional chemicals create compliance friction for imported concentrates. Tier-one cities concentrate pre-delivery detailing volume for mid-segment vehicle sales through dealership channels.
Australia
Capital cities show rising subscription replenishment for interior cleaners as direct-to-consumer channels capture recurring private owner purchases. The Department of Climate Change, Energy, the Environment and Water biosecurity protocols restrict phosphate content, accelerating biodegradable surfactant research and development. Supermarket chains carry compliant lines meeting environmental protocol requirements.
Vietnam
Ho Chi Minh City and Hanoi display underpenetrated professional service density relative to vehicle stock growth, creating whitespace for urban detailing expansion. Waterless cleaning formulations gain traction under environmental compliance pressure, forcing spray-and-wipe protocol adoption. Direct sales of bulk concentrate packages concentrate highest where service chain penetration lags.
Thailand
Professional detailers in Bangkok expand express service menus around ceramic-infused spray sealants that collapse wash and protection into single-step applications. Car wash service chains retool labor deployment around waterless protocols. Exterior polishing applications displace wax-only maintenance routines as detailers capture higher ticket averages.
Asia-Pacific Car Cleaning Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers, producing a bifurcated structure where distribution scale and technical differentiation operate as distinct competitive vectors. The vendor base spans multinational chemical conglomerates with polymer science capabilities alongside regional blenders with localized regulatory navigation expertise. Three archetypes dominate: premium coating specialists, mass-market surfactant suppliers, and professional-channel concentrate providers. M&A activity concentrates on acquiring formulation chemist talent, while portfolio diversification targets ceramic-infused hybrid categories.
Within the premium coating specialist tier, Soft99 Corp and 3M Co occupy positions anchored by Japanese and American polymer science heritage respectively. Pidilite Industries Ltd represents the mass-market surfactant archetype with extensive distribution networks dominating aftermarket channels. These three entities exemplify how geographic origin and company structure shape competitive positioning without converging on identical capability sets.
| Leading Market Players |
|---|
| 3M Co |
| SONAX GmbH |
| Turtle Wax, Inc |
| Wurth Group |
| Tetrosyl Ltd |
| Soft99 Corp |
| Pidilite Industries Ltd |
| Cartec BV |
| Liqui Moly |
| Others |
Value Network & Pricing Analysis
South Korean and Singaporean naphtha cracking capacity anchors solvent and polymer input costs for Asia-Pacific blenders, concentrating margin capture with formulators who maintain long-term offtake contracts against spot market volatility. This upstream concentration funnels pricing power toward integrated suppliers while fragmenting margin pools among toll-blenders dependent on import arbitrage.
Pricing Analysis
Cost-plus contracts with naphtha indexation dominate bulk concentrate procurement between Southeast Asian car wash chains and surfactant suppliers. Three-tier pricing structure across premium ceramic-infused, standard synthetic, and economy petroleum-distillate tiers separates professional detailers from fleet operators and private owners. Pricing pressure stems from biodegradable surfactant R&D compliance costs in Australia and Japan. Fleet operators show highest price sensitivity due to green procurement audit requirements, while ceramic coating prep specialists absorb premium markups for extended protection durability.
Supply Chain Analysis
Petrochemical feedstock supply concentrates in South Korea, Singapore, and Japan for solvent and polymer inputs that feed regional blending operations. Surfactant packages draw from palm-derived feedstocks in Malaysia and Indonesia alongside synthetic alcohols from Northeast Asian crackers. Single-source vulnerability runs through naphtha cracking capacity concentrated at Jurong Island and Yeosu complexes. Distribution runs through direct sales for professional service chains, quick-commerce platforms for private owners in Indian tier-one cities, and specialty retailers for compliant product lines in Japanese metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific car cleaning products market sits in a cyclical recovery phase as vehicle ownership rebounds across India's middle-income households and professional detailing penetration expands in Vietnam's urban centers.
For Market Incumbents: Pre-empt formulation chemist scarcity by acquiring regional blending facilities with established regulatory navigation expertise across Japan's METI frameworks and India's BIS labeling mandates. Consolidate backward integration into biodegradable surfactant production to defend margin position against Australia's phosphate restrictions and secure green procurement contract eligibility. For New Entrants and Emerging Players: Pursue Ho Chi Minh City and Hanoi urban detailing whitespace where professional service density lags vehicle stock growth. Target direct-to-consumer subscription replenishment models in Australian capital cities where interior cleaner purchase cycles compress. Anchor go-to-market strategy through quick-commerce platform partnerships that displace traditional auto accessory retailers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional blenders lacking ceramic-infused formulation capabilities but holding established distribution networks across Southeast Asian car wash chains. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity surfactant scale. Watch ceramic coating prep workflow adoption rates among Thai and Malaysian detailers as inflection indicator for premium formulation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant R&D Investment | Australia's biosecurity protocols restrict phosphate content, compelling compliant formulation development. |
| Ceramic-Infused Product Line Extension | Thai detailers adopt spray sealants that collapse wash and protection into single-step applications. |
| Quick-Commerce Channel Partnership | Mumbai and Bangalore platforms displace traditional retailers for interior cleaning kit replenishment. |
| Green Procurement Certification | Japan's METI frameworks preference low-VOC suppliers for government fleet maintenance contracts. |
| Formulation Chemist Talent Acquisition | Divergent chemical registers across Japan, Australia, and India create scarce technical capability pools. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with formulation chemists at regional blenders, procurement leads at Southeast Asian car wash chains, regulatory affairs specialists navigating METI and BIS frameworks, and category buyers at Australian supermarket retailers. Secondary validation drew from customs and trade data, chemical industry association reports, SEC filings of multinational suppliers, and national chemical register documentation. Bottom-up volume estimates from product-type and application segmentation were triangulated against top-down market sizing derived from vehicle stock and service intensity assumptions.
Calibration against historical growth patterns and documented regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user archetype, distribution channel format, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and substitution dynamics between waterless formulations and traditional wash protocols. Industry-specific inputs incorporated surfactant feedstock cost trajectories and ceramic coating adoption curves among professional detailers.
Macroeconomic conditions sit as an overlay; deviation in naphtha pricing, regional vehicle sales, or environmental enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation pace and technology substitution rates. Cross-checking against vehicle registration databases and chemical import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Maintenance & Aftermarket
Asia-Pacific Car Wash Market
Vehicle Maintenance & Aftermarket
E-Commerce Automotive Aftermarket Market
Vehicle Maintenance & Aftermarket
Car Glass Cleaner Market
Vehicle Maintenance & Aftermarket
Nitrogen Tire Inflators Market
Vehicle Maintenance & Aftermarket
Road Maintenance Service Market
Vehicle Maintenance & Aftermarket
Middle East and Africa Automotive Aftermarket Glass Market
Vehicle Maintenance & Aftermarket
Non OEM EV MRO Market
Vehicle Maintenance & Aftermarket
Car Wash Ancillary Products Market
Vehicle Maintenance & Aftermarket
Mobile Car Wash and Detailing Market
Vehicle Maintenance & Aftermarket
OBD-Linked Predictive Maintenance Diagnostic Platforms Market
Vehicle Maintenance & Aftermarket
Electric Vehicle Aftermarket Market
Vehicle Maintenance & Aftermarket
US Car Care Products Market
Vehicle Maintenance & Aftermarket
Highway Maintenance Market
Vehicle Maintenance & Aftermarket
Automotive Repair and Maintenance Services Market
Vehicle Maintenance & Aftermarket
Automotive Exhaust Aftertreatment Systems Market
Vehicle Maintenance & Aftermarket
US Maintenance Repair and Operations (MRO) Market