
 Global Automated Breast Ultrasound System (ABUS) Market | 2026-2036
Global Automated Breast Ultrasound System (ABUS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Breast Ultrasound System (ABUS) Market Intelligence
The bundling of ABUS hardware with long-term software and service contracts is consolidating buyer preference toward integrated, single-vendor solutions. This shift favors large, diversified medical technology firms that can offer comprehensive support. GE Healthcare leverages its extensive hospital network and established brand to promote its ABUS platforms. Siemens Healthineers competes on the strength of its imaging software and analytics integration, while Koninklijke Philips N.V. differentiates through a focus on workflow efficiency for high-volume radiology clinics.
An Automated Breast Ultrasound System is a medical imaging device that uses a wide-field-of-view transducer, often around 15 cm, to automatically capture volumetric images of the entire breast. Its primary purpose is to serve as an adjunctive screening tool to mammography, improving cancer detection in women with dense breast tissue. Among product types, 3D ABUS systems command the largest market share due to their superior diagnostic capabilities over 2D alternatives. Demand from diagnostic imaging centers for the specific application of dense tissue imaging represents the fastest-growing market segment.
Regulatory approvals from bodies like the US FDA, adherence to Europe's stringent Medical Device Regulation (MDR) for CE marking, and clearance from China's NMPA are critical for market access. These agencies' requirements for extensive clinical data on device efficacy and safety directly shape product development timelines. The future competitive positioning depends on how vendors navigate evolving reimbursement policies for supplemental screening and integrate AI-driven diagnostic aids into their platforms.
Market Dynamics
The market's central structural force is the shift toward integrated, single-vendor ecosystems. This trend bundles ABUS hardware with long-term software analytics and service contracts, concentrating market power with large, diversified medical technology firms that can offer end-to-end support.
Growth Catalysts
- State-Level Mandates:Dense breast notification laws in numerous US states compel providers to inform patients about their tissue density and the potential benefits of supplemental screening. This regulatory action directly stimulates patient inquiries and clinical demand for ABUS examinations.
- AI-Powered Algorithms:Advancements in artificial intelligence for image analysis significantly improve diagnostic accuracy and reduce radiologist reading times. This technological enhancement makes ABUS a more efficient and reliable adjunct to mammography, encouraging adoption in high-volume settings.
- Diagnostic Center Demand:Specialized diagnostic imaging centers, focused on providing outpatient services, represent the fastest-growing end-use segment. These facilities invest in ABUS to differentiate their services and cater to the specific clinical need for dense tissue imaging.
Market Restraints
- High Capital Investment:The substantial upfront cost of acquiring an Automated Breast Ultrasound System, coupled with associated software and training expenses, presents a significant financial barrier for smaller clinics and hospitals with constrained capital budgets.
- Reimbursement Variability:Inconsistent and often inadequate reimbursement policies for supplemental breast screening across different regions and payers create financial uncertainty for healthcare providers. This limits the economic viability of offering ABUS services on a widespread basis.
- Technical Interpretation Skills:Interpreting volumetric 3D ABUS datasets requires specialized training and represents a learning curve for radiologists accustomed to conventional handheld 2D ultrasound. A shortage of proficient users can slow the technology's effective clinical integration.
Strategic Opportunities
- Expansion in Asia-Pacific:Markets such as South Korea and Japan, with high breast density prevalence and sophisticated healthcare systems, offer significant growth potential. Tailoring market entry strategies to local screening programs and regulatory pathways is a key opportunity.
- Therapeutic Monitoring Applications:There is an opportunity to expand the use of ABUS beyond screening to include monitoring tumor response to neoadjuvant chemotherapy. This would establish the technology as a valuable tool throughout the cancer care continuum.
- Portable System Development:Developing smaller, more portable ABUS systems could open new markets in mobile screening units and clinics in underserved or rural areas. This would address accessibility gaps and expand the technology's reach beyond large medical centers.
Industry Challenges
- Data Integration Complexity:Integrating new ABUS platforms with existing hospital IT infrastructure, including Picture Archiving and Communication Systems (PACS) and Electronic Health Records (EHR), is a major operational challenge. Ensuring seamless data flow is critical for clinical workflow efficiency.
- Stringent Regulatory Hurdles:Securing and maintaining regulatory approvals from agencies like the US FDA, and conforming to Europe's MDR, requires extensive and costly clinical trials. These long validation cycles can delay the introduction of new innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Breast Ultrasound System (ABUS) Market |
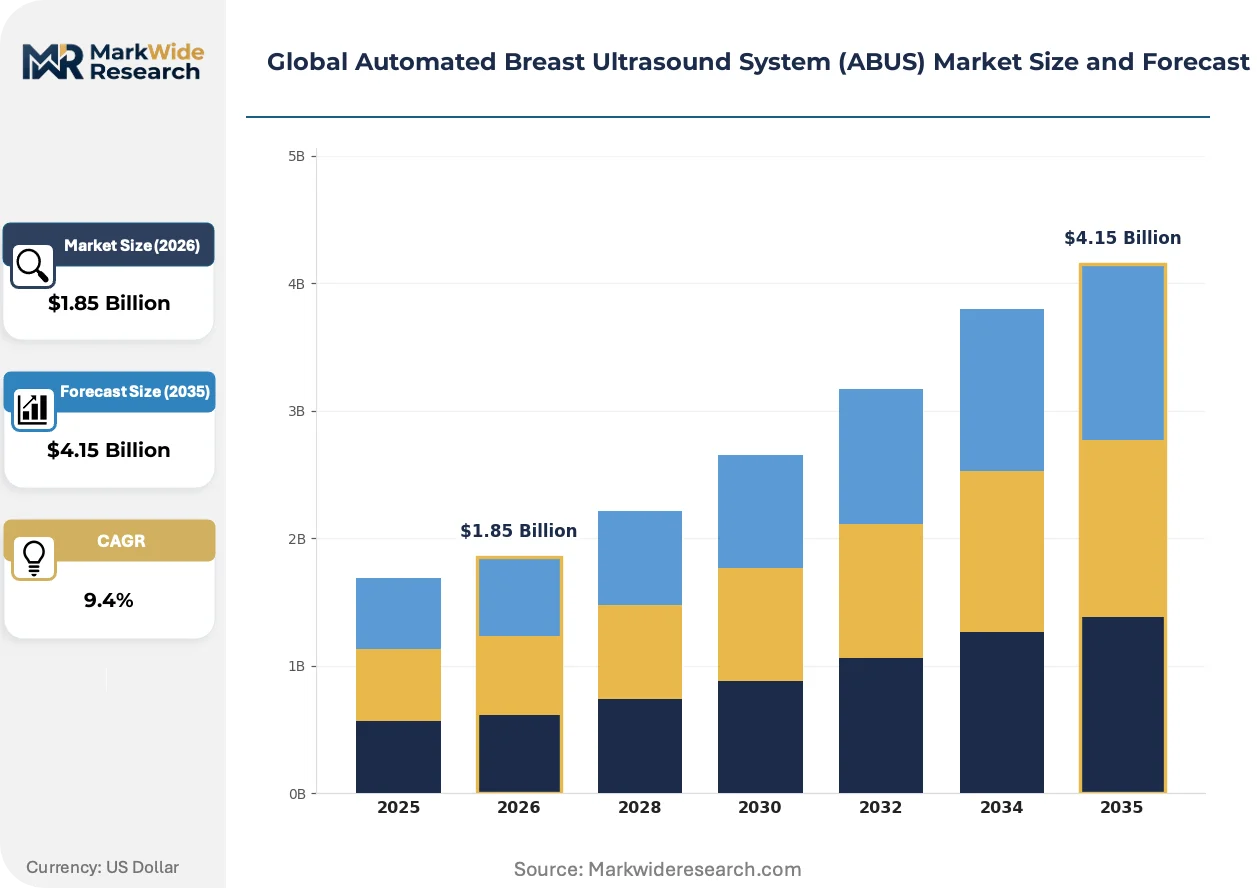
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D ABUS, 3D ABUS, Handheld ABUS, Full-Breast ABUS Technology: Sound Wave Imaging, Tomosynthesis, Elastography, Doppler Ultrasound Application: Breast Cancer Screening, Dense Tissue Imaging, Lesion Detection, Early Diagnosis End User: Radiology Clinics, Diagnostic Imaging Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Hologic, Inc., Hitachi, Ltd., GE Healthcare, Delphinus Medical Technologies, Inc., Samsung Medison Co., Ltd., Siemens Healthineers AG, Canon Medical Systems Corporation, SonoCiné SAS, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Breast Ultrasound System (ABUS) Market Strategic Shifts & Innovations
The convergence of AI-driven analytics and stricter regulatory standards for clinical evidence is reshaping the ABUS market. This dynamic pushes vendors toward developing smarter, more robustly validated systems that can be seamlessly integrated into complex clinical workflows.
AI-powered image analysis software is a defining technological evolution. This software uses deep learning algorithms to automatically identify and segment suspicious lesions within the volumetric data captured by the ABUS transducer. Diagnostic imaging centers and large hospital networks are the primary adopters. This technology is rewriting the diagnostic workflow by improving consistency and reducing radiologist interpretation time, making large-scale supplemental screening programs more practical.
Europe's Medical Device Regulation (MDR) has introduced a significant policy shift. The regulation mandates more rigorous clinical evidence and continuous post-market surveillance for all medical devices, including ABUS systems, to obtain or maintain CE marking. This increases the compliance burden and development costs for manufacturers. The ABUS product segment is directly affected, as vendors must now invest more heavily in clinical validation to prove safety and efficacy for European market access.
A preference for single-vendor, long-term partnerships is altering purchasing behavior. This model moves away from one-time hardware sales toward bundled contracts that include the ABUS system, analysis software, ongoing updates, and service agreements. This shift favors large, established med-tech companies over smaller, specialized hardware manufacturers. The trend is most visible in integrated health networks in the United States and parts of Europe, where total cost of ownership and system interoperability are key decision criteria.
Global Automated Breast Ultrasound System (ABUS) Market Segmentation
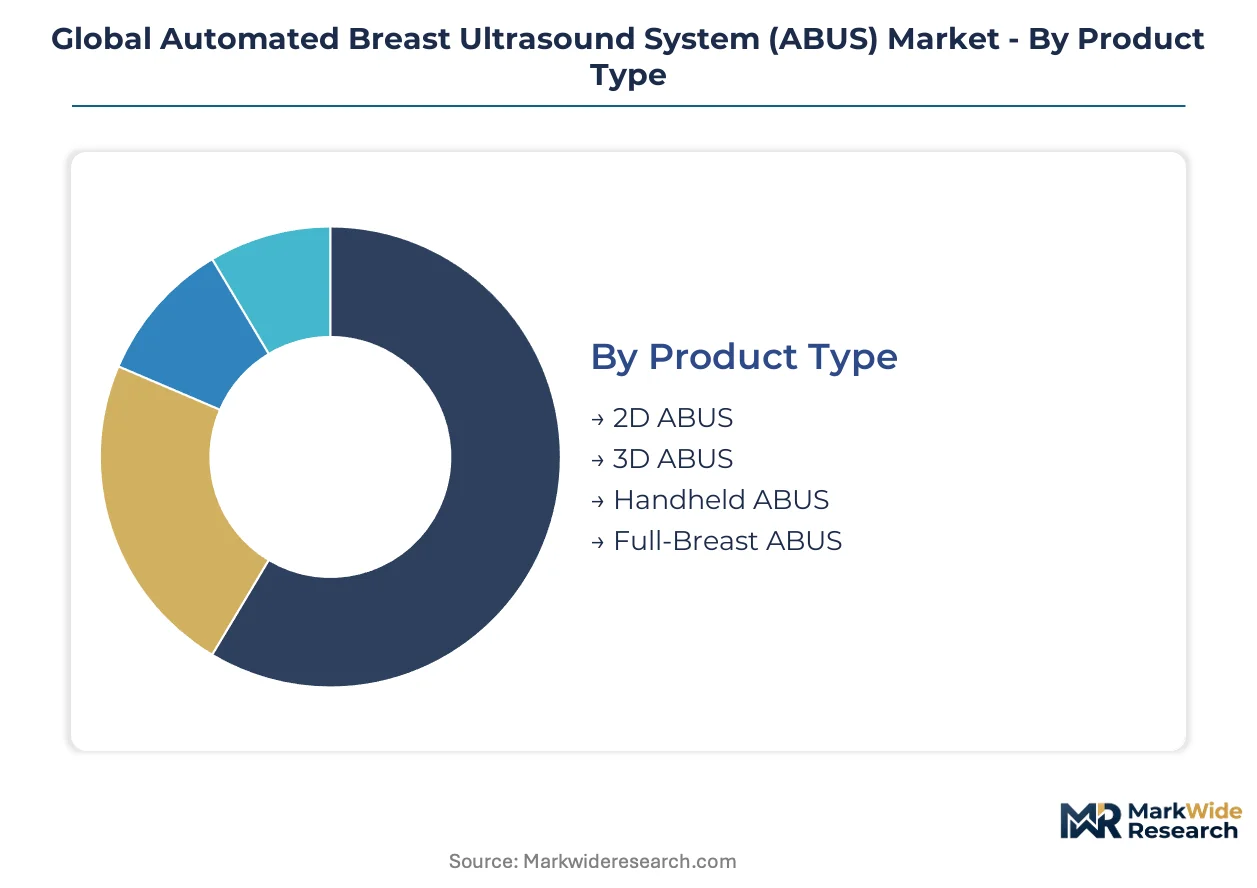
The Automated Breast Ultrasound System (ABUS) market is analyzed across key dimensions to understand adoption patterns and growth drivers. This segmentation highlights how different product types, underlying technologies, clinical applications, and end-user environments influence market dynamics. Understanding these distinctions is crucial for manufacturers to tailor product development and market entry strategies.
Product Type:
The technical specifications of ABUS systems define their primary utility and market penetration.
- 3D ABUS:These systems capture volumetric data of the breast, offering superior diagnostic capabilities for radiologists to visualize lesions from multiple planes. Demand concentrates in large hospital networks in the United States, driven by the need for enhanced diagnostic accuracy in complex cases.
- Full-Breast ABUS:Designed to capture comprehensive volumetric images of the entire breast in a single acquisition, these systems streamline the screening workflow. Diagnostic imaging centers in Europe actively adopt these systems to improve efficiency for high-volume patient throughput.
- 2D ABUS:These systems provide two-dimensional images of breast tissue, serving as an entry-level option for supplemental screening.
- Handheld ABUS:While less automated, these portable systems offer flexibility for targeted imaging in various clinical settings.
3D ABUS leads on scale; Full-Breast ABUS leads on momentum.
Technology:
The market's technological landscape differentiates ABUS systems based on their underlying imaging principles and diagnostic enhancements.
- Sound Wave Imaging:This core technology uses high-frequency sound waves to create detailed images of breast tissue, forming the fundamental basis for all ABUS platforms. Diagnostic imaging centers rely on this technology for its non-invasive nature and established safety profile.
- Elastography:This advanced technique measures tissue stiffness, providing additional information to differentiate benign from malignant lesions. Hospitals in Germany are increasingly integrating elastography-enabled ABUS systems to improve diagnostic confidence.
- Tomosynthesis:While primarily associated with mammography, some ABUS systems integrate principles to enhance image reconstruction and reduce artifact interference.
- Doppler Ultrasound:This technology assesses blood flow within breast lesions, offering insights into vascularity that can aid in characterization.
Sound Wave Imaging forms the foundational technology, while Elastography is gaining share fastest due to its diagnostic specificity.
Application:
The clinical utility of ABUS systems dictates their adoption across various medical scenarios.
- Dense Tissue Imaging:This application specifically targets women with dense breast tissue, for whom mammography alone may be less effective in detecting cancer. Demand from diagnostic imaging centers in the United States represents the fastest-growing market segment, stimulated by state-level notification laws.
- Breast Cancer Screening:ABUS serves as an adjunctive tool to mammography, improving overall cancer detection rates, especially in populations with higher breast density. Hospitals in Japan prioritize ABUS for its ability to enhance early detection programs.
- Lesion Detection:ABUS systems are used to identify suspicious areas within the breast, often guiding further diagnostic procedures.
- Early Diagnosis:The technology contributes to the timely identification of breast malignancies, facilitating prompt treatment initiation.
Dense Tissue Imaging represents the primary growth driver, with Breast Cancer Screening maintaining consistent demand.
End User:
The type of healthcare facility deploying ABUS systems influences purchasing decisions and market distribution.
- Diagnostic Imaging Centers:These specialized outpatient facilities focus on providing a broad range of imaging services, including advanced breast diagnostics. These centers invest in ABUS to differentiate their offerings and meet the specific needs of patients requiring supplemental screening.
- Radiology Clinics:Offering comprehensive radiological services, these clinics integrate ABUS to enhance their breast imaging capabilities and improve diagnostic accuracy for their patient base. Radiology clinics in South Korea are significant adopters, driven by high breast density prevalence.
- Specialty Clinics:Breast health centers and oncology clinics use ABUS for targeted patient management and follow-up.
- Research Institutes:Academic and research institutions employ ABUS for clinical trials, technology development, and advanced studies in breast cancer detection.
Diagnostic Imaging Centers are driving the most significant expansion, while Radiology Clinics maintain a substantial installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Automated Breast Ultrasound System (ABUS) market scaled significantly in developed economies. Early adoption and technological advancements primarily occurred in North America and Western Europe. These regions established foundational clinical practices for breast imaging, driving initial market growth.
United States
State-level dense breast notification laws directly stimulate patient inquiries and clinical demand for ABUS examinations in the United States. US FDA approvals are critical for market entry and widespread commercialization of new ABUS devices. California's medical technology hubs drive innovation in AI-powered ABUS systems, integrating advanced diagnostic algorithms.
Germany
Hospitals in Germany are increasingly integrating elastography-enabled ABUS systems to improve diagnostic confidence. Europe's stringent Medical Device Regulation (MDR) for CE marking dictates product development and market access for ABUS manufacturers. Munich's medical device ecosystem supports the development of advanced imaging software, enhancing ABUS capabilities.
Japan
Hospitals in Japan prioritize ABUS for its ability to enhance early detection programs, especially given the prevalence of dense breast tissue. PMDA clearance is a mandatory regulatory requirement for all medical devices entering the Japanese market. Tokyo's research institutions collaborate on integrating ABUS with AI diagnostic aids, improving diagnostic workflow.
South Korea
Radiology clinics in South Korea are significant adopters of ABUS, driven by the high breast density prevalence among the female population. MFDS approval is essential for medical imaging devices to gain market access and ensure patient safety in the country. Seoul's advanced healthcare infrastructure actively deploys full-breast ABUS systems for efficiency in high-volume settings.
China
Expanding healthcare infrastructure and a focus on early cancer detection drive demand for ABUS systems across China. China's NMPA clearance is a critical regulatory hurdle for market access, requiring extensive clinical data. Shanghai's medical equipment manufacturing centers are developing localized ABUS solutions, catering to regional market needs.
Global Automated Breast Ultrasound System (ABUS) Market Key Industry Players
The competitive structure tilts toward large, diversified medical technology firms. These firms offer integrated, single-vendor solutions for ABUS platforms, consolidating buyer preference. Strategic archetypes include comprehensive imaging solution providers and specialized breast imaging innovators. Dominant competitive moves involve portfolio diversification and strategic partnerships for AI integration, enhancing diagnostic capabilities.
Among global medical technology firms, GE Healthcare exemplifies leveraging an extensive hospital network and established brand to promote its ABUS platforms. This company capitalizes on its broad reach to offer integrated solutions to healthcare providers. Siemens Healthineers AG occupies a strong position by competing on the strength of its imaging software and analytics integration, catering to advanced diagnostic needs. Koninklijke Philips N.V. further differentiates itself through a focus on workflow efficiency for high-volume radiology clinics, representing the trend towards comprehensive support and streamlined operations for radiologists.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Hitachi, Ltd. |
| GE Healthcare |
| Delphinus Medical Technologies, Inc. |
| Samsung Medison Co., Ltd. |
| Siemens Healthineers AG |
| Canon Medical Systems Corporation |
| SonoCiné SAS |
| Koninklijke Philips N.V. |
Cost & Logistics Intelligence
Dense breast notification laws in the United States compel providers to invest in ABUS systems. This demand concentration influences pricing for integrated hardware and software solutions offered by large medical technology firms.
Pricing Analysis
Bundled long-term contracts define the dominant pricing model for Automated Breast Ultrasound Systems. Price differentiation stems from advanced software analytics capabilities and extensive service agreements. Pricing softness reflects intense competition among diversified med-tech firms and varying reimbursement policies. Smaller clinics and hospitals are highly price-sensitive due to high capital investment, while large integrated health networks prioritize comprehensive support over initial cost.
Supply Chain Analysis
Refurbishment and maintenance flows for ABUS systems are managed by major manufacturers, ensuring device longevity and performance. Component manufacturing for ABUS systems primarily occurs in Germany, Japan, and the United States. Key inputs include specialized transducers and advanced computing processors. Regulatory restrictions on medical device components pose a structural risk. Distribution runs through direct sales forces and established medical device distributors to hospitals and diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automated Breast Ultrasound System market functions as a stable compounder, driven by continuous technological advancements in AI-powered image analysis. This innovation consistently improves diagnostic accuracy and workflow efficiency for healthcare providers.
For Market Incumbents: Anchor existing market share by deepening integration of AI-driven diagnostic aids within ABUS platforms. This move counters emerging AI-only software providers and strengthens comprehensive offerings. Invest in clinical validation to meet stringent regulatory hurdles like Europe's MDR, securing long-term market access. Expand service and software contracts to retain large hospital networks.
For New Entrants and Emerging Players: Specialized diagnostic imaging centers represent a penetrable segment for innovative ABUS solutions. Partner with independent radiology groups to introduce cost-effective or portable ABUS systems. Focus on niche applications, such as therapeutic monitoring, where established players have less presence. Develop systems tailored for underserved rural areas to address accessibility gaps.
For Investors and Strategic Acquirers: Asymmetric upside sits with firms specializing in AI-powered image analysis algorithms and workflow integration for ABUS. Long-term viability rests on companies capable of navigating evolving reimbursement policies and regulatory landscapes. Target smaller innovators with strong intellectual property in advanced imaging software. Monitor clinical trial outcomes for new diagnostic capabilities as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Development | Enhances diagnostic accuracy and reduces radiologist interpretation time, making ABUS more efficient. |
| Regulatory Pathway Acceleration | Secures market access in regions like Europe and the US, validating device safety and efficacy. |
| Hospital Network Partnership | Leverages established patient bases and infrastructure for broader ABUS platform adoption. |
| Portable System Launch | Expands ABUS accessibility to underserved and rural areas, addressing patient screening gaps. |
| Reimbursement Strategy Development | Ensures economic viability for providers, stimulating broader clinical demand for ABUS examinations. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This analysis combines insights from clinicians, hospital purchasing committees, biomedical engineers, and regulatory affairs specialists. Secondary validation draws from US FDA filings, Europe's MDR guidelines, PMDA reports, and national healthcare statistics. Bottom-up and top-down triangulation ensured data integrity.
Volume and value were modeled at the product type, technology, application, and end-user levels across the analysis window. The framework also incorporated regional regulatory impacts and reimbursement trends. Compound annual growth rates were derived from historical data, market drivers, and projected technological adoption curves. Key forecast inputs included dense breast prevalence rates and healthcare infrastructure investment.
Revisions become necessary when significant shifts in regulatory policies or major technological breakthroughs materialize. Forecasts reflect assumptions regarding healthcare spending and patient screening adherence. Practitioners should monitor evolving reimbursement policies and AI integration advancements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
India Mammography Market
Medical Imaging
South America CT Market
Medical Imaging
India Diagnostic Imaging Equipment Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Wireless Ultrasound Scanner Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
United States Digital X-Ray Devices Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Asia-Pacific Digital Radiology Market
Medical Imaging
Structural Heart Imaging Market