
 Ultrasound Market | 2026-2036
Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Market Intelligence
Shortages of certified sonographers and clinical engineers is redrawing how hospitals deploy ultrasound capacity across developed markets. GE HealthCare leverages its installed base of cart-based systems to sustain recurring transducer revenue streams. Philips Healthcare anchors its competitive stance through AI-integrated diagnostic imaging platforms that reduce operator dependency. Siemens Healthineers differentiates via advanced Doppler imaging capabilities that target cardiology workflows in tertiary centers.
Ultrasound employs high-frequency sound waves, typically 2-18 MHz, to generate real-time anatomical images through piezoelectric crystal transducers that convert electrical pulses into acoustic energy and back. The technology serves diagnostic visualization, interventional guidance, and physiological monitoring across clinical settings without ionizing radiation exposure. Portable ultrasound devices now represent the fastest-expanding product category as battery density improvements and semiconductor miniaturization enable handheld systems that match legacy cart-based image quality. Cart-based systems still command the dominant share of absolute revenue within diagnostic imaging, though margin compression intensifies as point-of-care alternatives penetrate emergency departments and ambulatory clinics.
The FDA oversees 510(k) premarket notification requirements for ultrasound devices in the United States, while the EU Medical Device Regulation mandates clinical evidence thresholds that delay market entry for novel contrast-enhanced ultrasound agents. China's NMPA accelerates review timelines for domestically manufactured 2D and 3D ultrasound systems under innovation channel designations. Stakeholders must weigh regulatory capital requirements against the pace of AI algorithm validation to determine optimal portfolio sequencing between established modalities and emerging autonomous diagnostic platforms.
Market Dynamics
AI-integrated diagnostic platforms are compressing operator dependency requirements and redrawing competitive boundaries between established cart-based manufacturers and emerging handheld specialists.
Growth Catalysts
- Emergency Department Point-of-Care Adoption:Hospital systems in the United States accelerate equipment turnover cycles as bedside ultrasound displaces radiology department referrals for triage protocols.
- FDA 510(k) Modernization:Streamlined premarket notification pathways for AI-embedded devices reduce validation timelines and unlock capital deployment for autonomous diagnostic platforms.
- China's NMPA Innovation Channel:Domestic manufacturers of 2D and 3D systems receive expedited review designations, accelerating commercialization of cost-optimized hardware for outpatient networks.
Market Restraints
- Piezoelectric Crystal Supply Concentration:Advanced ceramic transducer materials depend on rare earth processing capabilities concentrated in East Asian supply chains.
- EU MDR Clinical Evidence Thresholds:Novel contrast-enhanced ultrasound agents face extended validation timelines that delay reimbursement eligibility across European hospital procurement frameworks.
- MRI and CT Substitution Pressure:Tertiary centers with fixed imaging infrastructure budgets prioritize multi-modal platforms over dedicated ultrasound capacity expansion.
Strategic Opportunities
- Ambulatory Clinic Penetration in Germany:Outpatient diagnostic networks seek portable systems to expand service capacity without radiologist co-location requirements.
- AI-Doppler Convergence:Machine learning algorithms integrated with spectral Doppler hardware enable autonomous cardiac output estimation in resource-limited settings.
- Direct-to-Consumer Channel Development:Subscription-based handheld device programs target primary care physicians bypassing traditional capital equipment sales cycles.
Industry Challenges
- Sonographer Certification Bottlenecks:Accredited training program capacity in the United States and Germany fails to match deployment velocity of point-of-care systems.
- Legacy PACS Integration Complexity:Hospital IT departments face interoperability friction when embedding AI-integrated ultrasound workstations into existing DICOM infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Market |
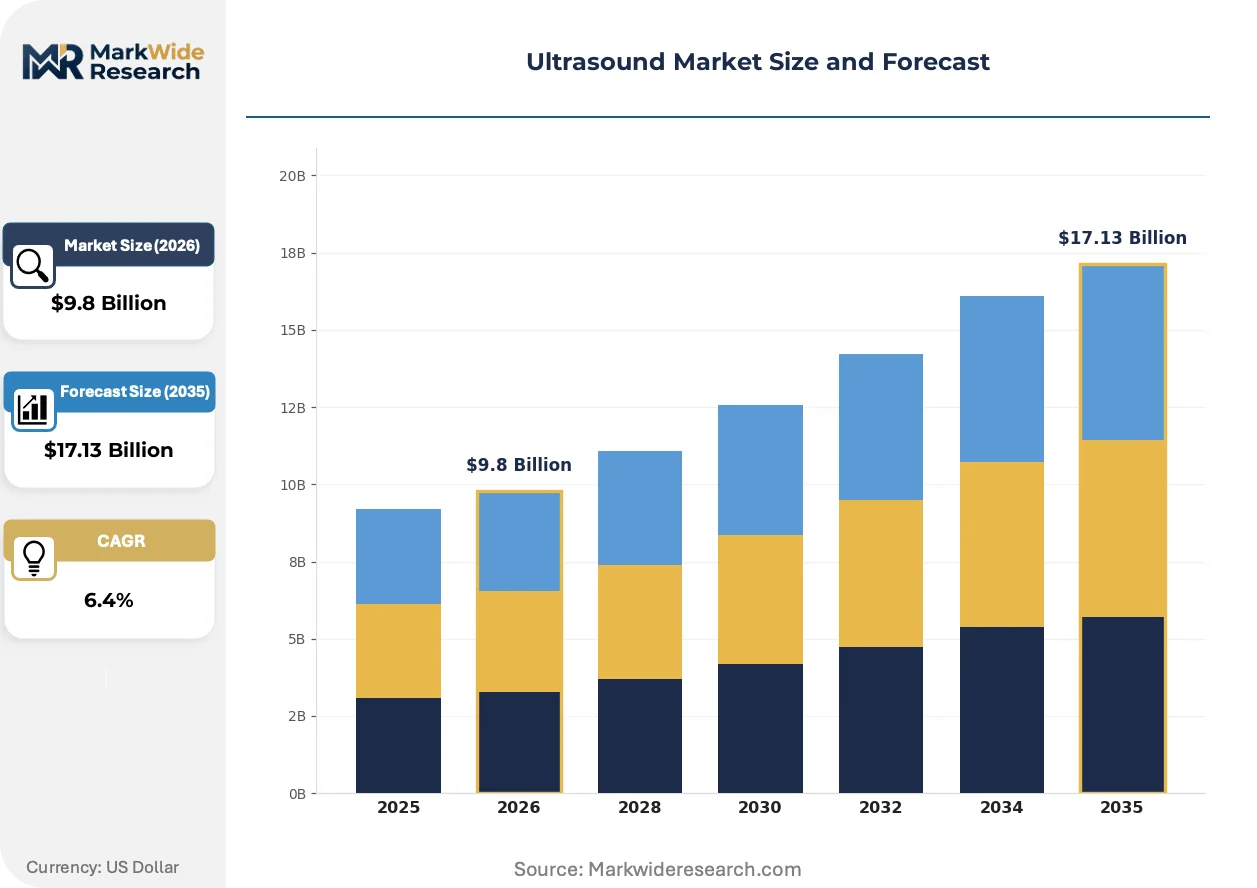
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ultrasound, Transducer, Cart-based System, Diagnostic Imaging End User: Hospitals, Clinics, Diagnostic Centers, Emergency Departments Application: Obstetrics, Cardiology, Urology, Musculoskeletal Technology: 2D Ultrasound, 3D Ultrasound, Doppler Imaging, Contrast-Enhanced Ultrasound |
| Companies Covered | GE HealthCare, Philips Healthcare, FUJIFILM Corporation, Canon Medical Systems, Mindray, Siemens Healthineers, Samsung Medison, Esaote, Konica Minolta Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Market Strategic Shifts & Innovations
Semiconductor miniaturization and battery chemistry advances are collapsing the performance gap between handheld and cart-based systems, forcing incumbents to defend installed base revenue through software differentiation.
Capacitive micromachined ultrasound transducers (CMUTs) replace conventional piezoelectric arrays in next-generation handheld devices. Emergency medicine departments and anesthesia teams adopt these systems for vascular access and regional nerve blocks. The technology is decomposing the traditional hardware-software bundle by enabling disposable transducer economics at price points below service contract minimums.
The EU Medical Device Regulation mandates post-market surveillance databases and unique device identifiers for all diagnostic imaging equipment sold in member states. Manufacturers must restructure quality management systems to capture real-world performance data across distributed installed bases. Cardiology-focused cart-based systems face the steepest compliance cost escalation due to higher-risk classification thresholds for hemodynamic monitoring applications.
Hospital procurement committees now unbundle transducer replacement schedules from initial system purchases, negotiating multi-vendor service agreements based on utilization metrics rather than manufacturer captivity. Integrated delivery networks in the United States lead this transition, leveraging volume concentration to extract performance-based pricing from GE HealthCare and Philips Healthcare service divisions. The shift compresses recurring revenue predictability for equipment vendors while improving total cost of ownership transparency for buyers.
Ultrasound Market Segmentation
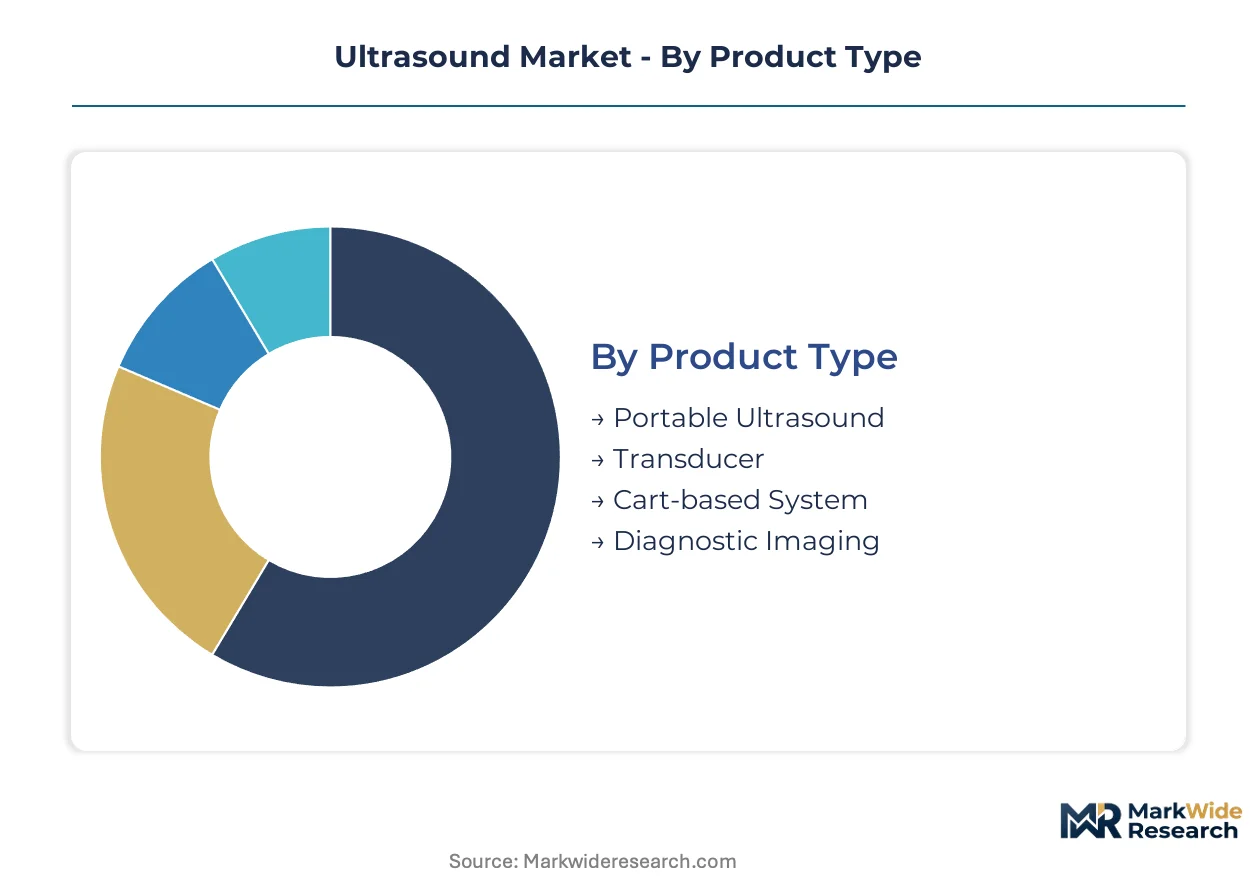
Segmentation in ultrasound equipment reveals how margin pools shift between hardware commoditization and software differentiation. Vendors now compete across four intersecting dimensions where technology maturity and clinical application urgency determine pricing power.
Product Type:
Margin concentration sits with systems that lock in recurring transducer revenue rather than one-time hardware sales.
- Portable Ultrasound:Handheld devices leverage CMUT semiconductor architecture and lithium-polymer battery packs to deliver diagnostic-grade imaging below 3 kg. Emergency departments in the United States and Germany accelerate procurement as bedside triage protocols displace radiology referrals. This segment gains share fastest as ambulatory networks prioritize mobility over channel density.
- Cart-based System:Tethered platforms integrate AI-embedded workstations with spectral Doppler hardware for cardiology and interventional suites. Tertiary centers in China sustain demand for premium configurations despite procurement committee pressure to unbundle service contracts. The dominant share belongs to this segment, while portable alternatives are closing the gap fastest.
- Transducer:Piezoelectric crystal arrays and CMUT membranes constitute the consumable revenue engine, with replacement cycles averaging 3-5 years under heavy utilization.
- Diagnostic Imaging:Software-integrated visualization platforms bundle reconstruction algorithms with PACS connectivity, capturing value through subscription licensing rather than perpetual sales.
Hardware commoditization pushes vendors toward software and consumable revenue models.
End User:
Procurement authority determines whether sales cycles run through capital committees or departmental operating budgets.
- Emergency Departments:Point-of-care protocols in United States health systems drive equipment turnover as bedside ultrasound replaces formal radiology orders for trauma and triage. CMUT-based handheld units penetrate fastest where sonographer shortages constrain department capacity.
- Hospitals:Integrated delivery networks negotiate multi-vendor service agreements based on utilization metrics, compressing manufacturer captivity in transducer replacement schedules.
- Clinics:Outpatient diagnostic networks in Germany seek portable systems to expand service capacity without radiologist co-location requirements.
- Diagnostic Centers:High-volume imaging facilities prioritize throughput-optimized cart-based platforms with automated measurement protocols.
Emergency departments command the steepest growth trajectory, though hospitals retain the largest installed base.
Application:
Clinical workflow complexity dictates whether AI integration reduces operator dependency or merely accelerates measurement tasks.
- Cardiology:Spectral Doppler and strain imaging require hemodynamic expertise that AI algorithms increasingly approximate, enabling autonomous cardiac output estimation in resource-limited settings. Tertiary centers sustain premium pricing for advanced quantification features.
- Obstetrics:3D/4D reconstruction for fetal anomaly screening drives recurring software license demand, with NMPA innovation channels accelerating domestic Chinese manufacturer entry.
- Musculoskeletal:Sports medicine and rheumatology applications favor portable systems for injection guidance and tendon assessment.
- Urology:Prostate and renal imaging concentrates in specialized diagnostic centers with contrast-enhanced protocol capabilities.
Cardiology applications generate the highest average selling prices, while obstetrics delivers the most predictable replacement demand.
Technology:
Regulatory validation burden separates established modalities from emerging platforms requiring clinical evidence investment.
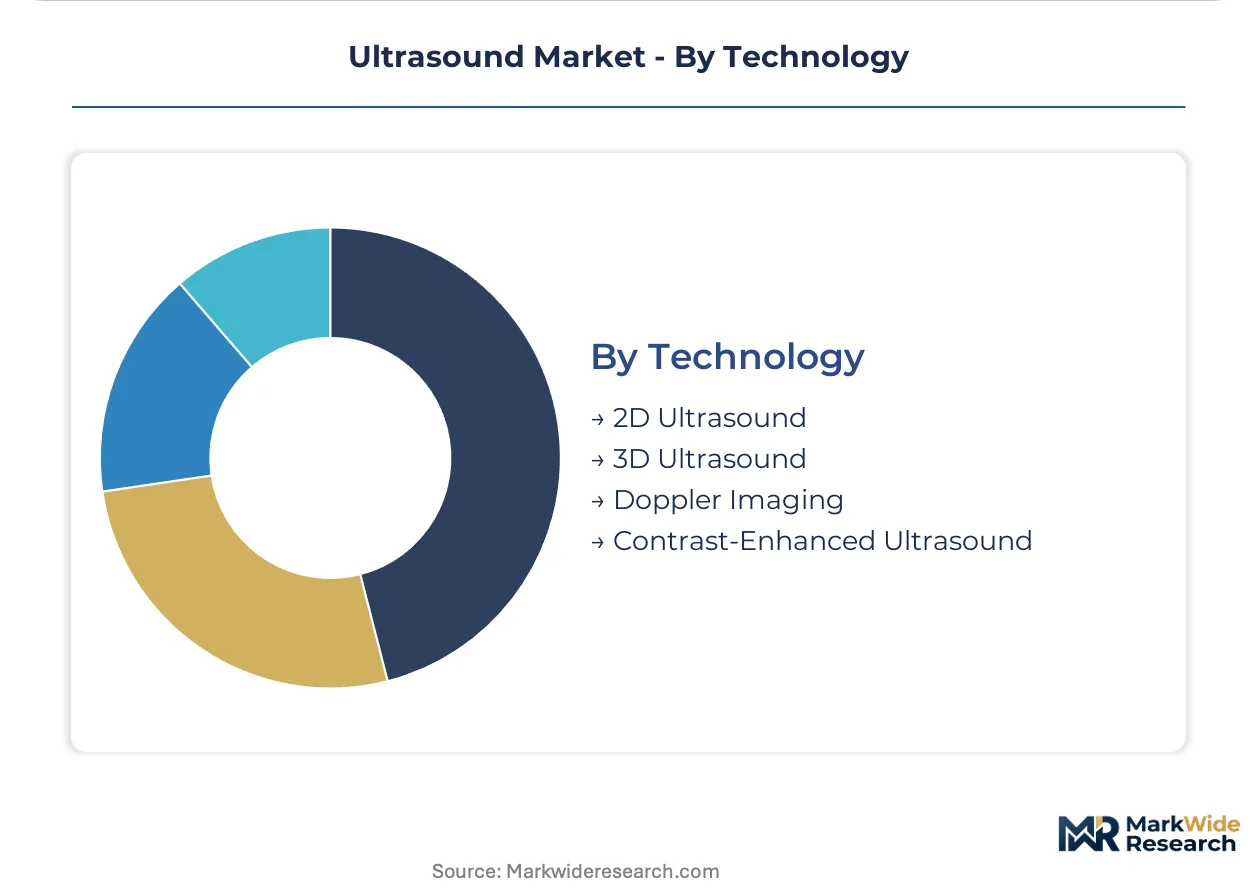
- 2D Ultrasound:Conventional B-mode imaging remains the volume foundation, with NMPA expedited review pathways for domestically manufactured systems in China reducing time-to-market for cost-optimized hardware.
- Doppler Imaging:Spectral and color flow modalities anchor cardiology and vascular workflows, with AI convergence enabling autonomous measurements that reduce sonographer training requirements.
- 3D Ultrasound:Volume reconstruction for obstetric and cardiac applications demands higher computational throughput, creating differentiation through proprietary algorithm portfolios.
- Contrast-Enhanced Ultrasound:Microbubble agents face EU MDR clinical evidence thresholds that delay reimbursement eligibility across European hospital procurement frameworks.
2D platforms retain the broadest installed base, though Doppler capabilities drive the most decisive purchase decisions in high-acuity settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) modernization in the United States is compressing clearance timelines for AI-embedded ultrasound systems. Demand concentrates across three distinct regulatory environments where reimbursement frameworks and procurement authority shape deployment velocity.
United States
Emergency departments accelerate point-of-care adoption as bedside protocols displace radiology referrals for trauma triage. FDA streamlined premarket notification pathways reduce validation timelines for autonomous diagnostic platforms. Texas Medical Center in Houston anchors the largest concentration of AI-integrated ultrasound research programs.
China
Domestic manufacturers exploit NMPA innovation channel designations to accelerate 2D and 3D system commercialization for outpatient networks. The regulator expedites review timelines for domestically manufactured hardware under innovation classifications. Shenzhen's medical device cluster hosts the densest concentration of CMUT semiconductor fabrication facilities.
Germany
Ambulatory diagnostic networks seek portable systems to expand service capacity without radiologist co-location requirements. EU MDR mandates post-market surveillance databases and unique device identifiers for all diagnostic imaging equipment. Munich's university hospital network leads procurement of AI-Doppler convergence platforms for autonomous cardiac output estimation.
Japan
PMDA maintains rigorous clinical evidence thresholds for contrast-enhanced ultrasound agents that delay market entry relative to Western timelines. METI promotes domestic semiconductor miniaturization for next-generation handheld device manufacturing. Tokyo's diagnostic imaging corridor concentrates the highest density of cart-based system installations per capita.
Ultrasound Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the ultrasound equipment sector. The vendor base separates into three tiers: diversified conglomerates with installed base captivity, mid-scale specialists with regional density, and emerging handheld disruptors with CMUT semiconductor advantages. Two dominant competitive moves reshape positioning: unbundling of transducer replacement schedules from initial system purchases, and AI algorithm licensing agreements that reduce operator dependency requirements.
Within the diversified conglomerate tier, GE HealthCare, Philips Healthcare, and Siemens Healthineers occupy positions defined by legacy cart-based installed bases and recurring transducer revenue streams. GE HealthCare exemplifies the installed base captivity archetype through its dominance in tethered platform deployments. Philips Healthcare represents the AI-integrated diagnostic platform strategy. Siemens Healthineers anchors the advanced Doppler imaging specialization for cardiology workflows. These three entities collectively illustrate how hardware commoditization forces defense of margin through software differentiation and service contract restructuring.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips Healthcare |
| FUJIFILM Corporation |
| Canon Medical Systems |
| Mindray |
| Siemens Healthineers |
| Samsung Medison |
| Esaote |
| Konica Minolta Healthcare |
| Others |
Cost & Logistics Intelligence
CMUT semiconductor fabrication scale in Shenzhen and Dongguan compresses unit economics for handheld transducers while simultaneously elevating price floors for legacy piezoelectric arrays. Battery chemistry suppliers in South Korea and Japan leverage cathode material concentration to extract premiums from cart-based system manufacturers seeking energy density improvements.
Pricing Analysis
United States emergency departments pay 40-60% premiums over German ambulatory clinics for identical CMUT handheld configurations due to FDA validation overhead and service contract bundling. Pricing stratifies across premium AI-embedded cart systems, standard tethered platforms without machine learning workstations, and economy handheld units with limited Doppler capability. Cost compression in the economy tier intensifies as Chinese domestic manufacturers exploit NMPA innovation channels to undercut Western OEMs on hardware margins. Hospital procurement committees exhibit the highest price sensitivity, while cardiology departments in tertiary centers remain least sensitive due to clinical workflow lock-in.
Supply Chain Analysis
Port congestion at Shanghai Yangshan and container availability constraints on the Asia-Europe trade lane elevate inbound logistics costs for piezoelectric ceramic substrates sourced from Japanese suppliers. Advanced transducer materials concentrate manufacturing in China, Japan, and South Korea, with rare earth processing capabilities tethered to East Asian supply chains. Single-source vulnerability sits with high-purity lead zirconate titanate crystals used in cardiology-focused phased arrays. Distribution runs through authorized medical device distributors in developed markets and direct hospital procurement relationships in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care deployment velocity fragments demand across emergency departments, ambulatory networks, and resource-limited settings, creating specialization niches that favor focused players over diversified conglomerates.
For Market Incumbents: Shield installed base revenue by restructuring service contracts around utilization metrics rather than captive transducer replacement schedules. Accelerate backward integration into CMUT semiconductor fabrication to neutralize emerging handheld specialists' cost advantage. FDA 510(k) modernization compresses validation timelines for autonomous diagnostic platforms, threatening premium pricing for operator-dependent cart systems. For New Entrants and Emerging Players: China's NMPA innovation channel designation offers the fastest regulatory path to commercialization for cost-optimized 2D and 3D hardware targeting outpatient networks. Target German ambulatory diagnostic centers seeking portable systems without radiologist co-location requirements. Deploy direct-to-consumer subscription models bypassing traditional capital equipment sales cycles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among transducer replacement programs and AI algorithm licensing agreements rather than one-time hardware sales. Long-term viability favors acquisition targets with proprietary CMUT fabrication capabilities or FDA-cleared autonomous measurement algorithms. Monitor FDA clearance velocity for AI-embedded devices as the inflection indicator for platform commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| CMUT Semiconductor Fabrication Scale-Up | Enables disposable transducer economics below legacy service contract minimums. |
| FDA 510(k) AI-Embedded Device Submission | Unlocks autonomous diagnostic platforms reducing operator dependency requirements. |
| Hospital System Partnership | Secures multi-vendor utilization-based service agreements compressing manufacturer captivity. |
| Software Companion Development | Bundles AI reconstruction algorithms with PACS connectivity for subscription licensing. |
| Reimbursement Strategy | Navigates EU MDR clinical evidence thresholds for contrast-enhanced ultrasound agents. |
Research Approach
Operator-level perspectives from emergency department physicians, biomedical engineers, hospital procurement committee members, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, NMPA innovation channel designations, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up equipment shipment modeling triangulated against top-down health system capital expenditure surveys.
Sensitivity analysis tested volume and value outputs across product type, end user, application, and technology segmentation dimensions over the projection horizon. CAGRs derived from equipment replacement cycle analysis, point-of-care adoption velocity, and AI integration penetration curves. Forecast inputs incorporated sonographer certification pipeline constraints and semiconductor miniaturization cost curves.
Decision-makers should treat outputs as directional under assumptions of stable regulatory review timelines and continued NMPA innovation channel access for domestic Chinese manufacturers; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Middle East and Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Global Veterinary Diagnostic Imaging Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Contrast Media Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Handheld Dental X-Ray Systems Market