
 Wireless Ultrasound Scanner Market | 2026-2036
Wireless Ultrasound Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Ultrasound Scanner Market Outlook
The capital-intensity gap between semiconductor-dependent transducer manufacturers and software-centric imaging platforms is collapsing. GE HealthCare leverages its captive piezoelectric supply chain to dominate premium cart-based installations. Butterfly Network differentiates through proprietary single-chip ultrasound-on-CMOS architecture that eliminates discrete crystal arrays. Clarius Mobile Health specializes in cloud-native workflows that extend its addressable market beyond traditional radiology departments.
Wireless ultrasound scanners transmit acoustic pulses through piezoelectric elements and receive returning echoes via Bluetooth or Wi-Fi to smartphones, tablets, or dedicated receivers, with operating frequencies typically spanning 2-15 MHz depending on tissue penetration requirements. Pocket ultrasound and AI-enabled technology segments are capturing disproportionate R&D investment as automated image interpretation reduces operator dependence. Handheld and portable product types are displacing legacy cart-based systems in ambulatory settings where space constraints and capital budgets favor mobility. Emergency services and home care end users represent the fastest-growing demand pools as decentralized care models expand.
FDA 510(k) clearance, CE marking under EU MDR, and NMPA registration in China collectively shape product development roadmaps and geographic launch sequencing for wireless ultrasound devices. ISO 13485 quality management certification has become a baseline requirement for contract manufacturing relationships and hospital procurement eligibility. Stakeholders must monitor reimbursement code evolution for point-of-care ultrasound as payer acceptance determines clinical adoption velocity across outpatient settings.
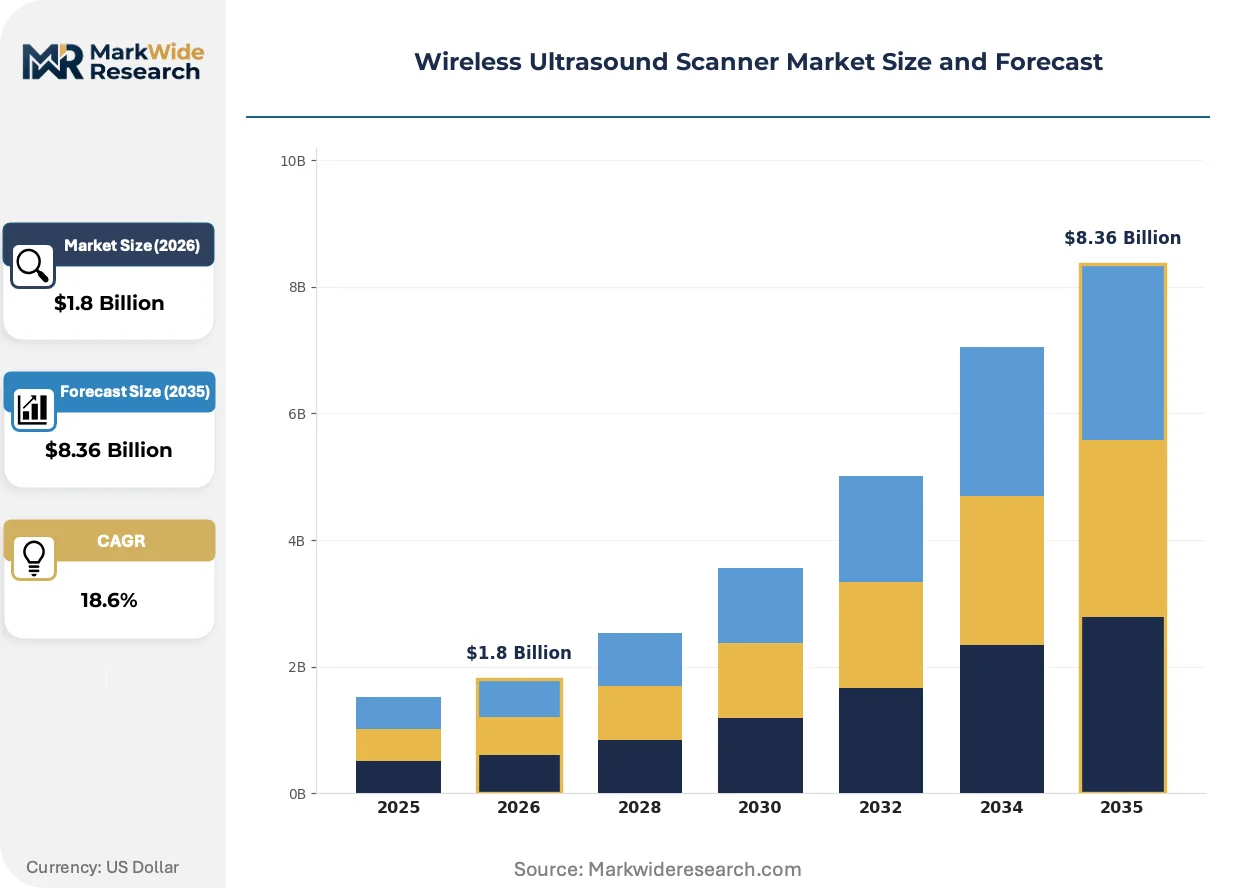
Market Dynamics
Point-of-care imaging workflows are compressing hardware margins while expanding software monetization surfaces for wireless ultrasound vendors.
Growth Catalysts
- FDA 510(k) clearance pathway:Accelerated premarket review timelines for handheld wireless systems reduce commercialization lag between prototype and hospital deployment.
- Emergency medicine services:Ambulance fleets and trauma centers deploy pocket ultrasound for field triage, bypassing radiology department bottlenecks.
- AI-enabled image interpretation:Automated anatomical recognition reduces operator training burden and extends device utility to non-specialist clinicians.
Market Restraints
- Piezoelectric crystal supply concentration:High-purity lead zirconate titanate sourcing clusters in East Asian foundries, exposing transducer manufacturers to input volatility.
- Reimbursement code fragmentation:CMS and private payers maintain inconsistent coverage policies for point-of-care ultrasound, dampening outpatient adoption velocity.
- CMOS sensor substitution ceiling:Silicon-based alternatives struggle to match acoustic impedance matching of traditional ceramics in deep-tissue applications.
Strategic Opportunities
- Home care monitoring:Post-discharge cardiac and obstetric surveillance creates recurring revenue streams beyond acute care settings.
- EU MDR harmonization:Streamlined CE marking pathways under consolidated medical device regulation reduce multi-national registration overhead for European market entry.
- 5G-enabled telesonography:Ultra-reliable low-latency connectivity permits real-time remote guidance between specialists and frontline operators.
Industry Challenges
- Image quality standardization:Operator-dependent acquisition variability complicates AI training dataset curation and diagnostic reliability certification.
- Legacy PACS integration:Hospital IT infrastructure built around DICOM-compliant cart-based systems requires middleware development for wireless data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Ultrasound Scanner Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Cart-based, Transducer Technology: Pocket Ultrasound, 3D Imaging, Doppler Ultrasound, AI-enabled End User: Hospitals, Clinics, Home Care, Emergency Services Delivery Mode: Cloud-based, On-premises, Hybrid, Mobile Application |
| Companies Covered | GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems Corporation, Clarius Mobile Health, Butterfly Network, Mindray Medical International Limited, Fujifilm Holdings Corporation, Konica Minolta Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Ultrasound Scanner Market Strategic Shifts
Semiconductor miniaturization and cloud-native architectures are collapsing the traditional boundary between imaging hardware and diagnostic software layers.
Single-chip ultrasound-on-CMOS architectures are decomposing the discrete transducer assembly into monolithic silicon solutions. Emergency departments and rural clinics adopt these systems for immediate anatomical assessment without capital-intensive infrastructure. The technology is decomposing premium pricing tiers by eliminating crystal array manufacturing complexity and reducing bill-of-materials costs.
EU MDR post-market surveillance requirements mandate systematic clinical follow-up data collection for all wireless ultrasound devices placed on European markets. Manufacturers must establish quality management systems exceeding ISO 13485 baselines to maintain CE marking validity. High-frequency linear probes for musculoskeletal applications face heightened scrutiny under strengthened biocompatibility testing protocols.
Subscription-based software licensing supplants perpetual hardware purchases in ambulatory care networks. Independent physician associations and urgent care chains favor per-scan pricing models that align costs with utilization rather than capital depreciation schedules. Germany and the United States exhibit the strongest uptake of this consumption-based commercial structure among OECD healthcare systems.
Wireless Ultrasound Scanner Market Segmentation
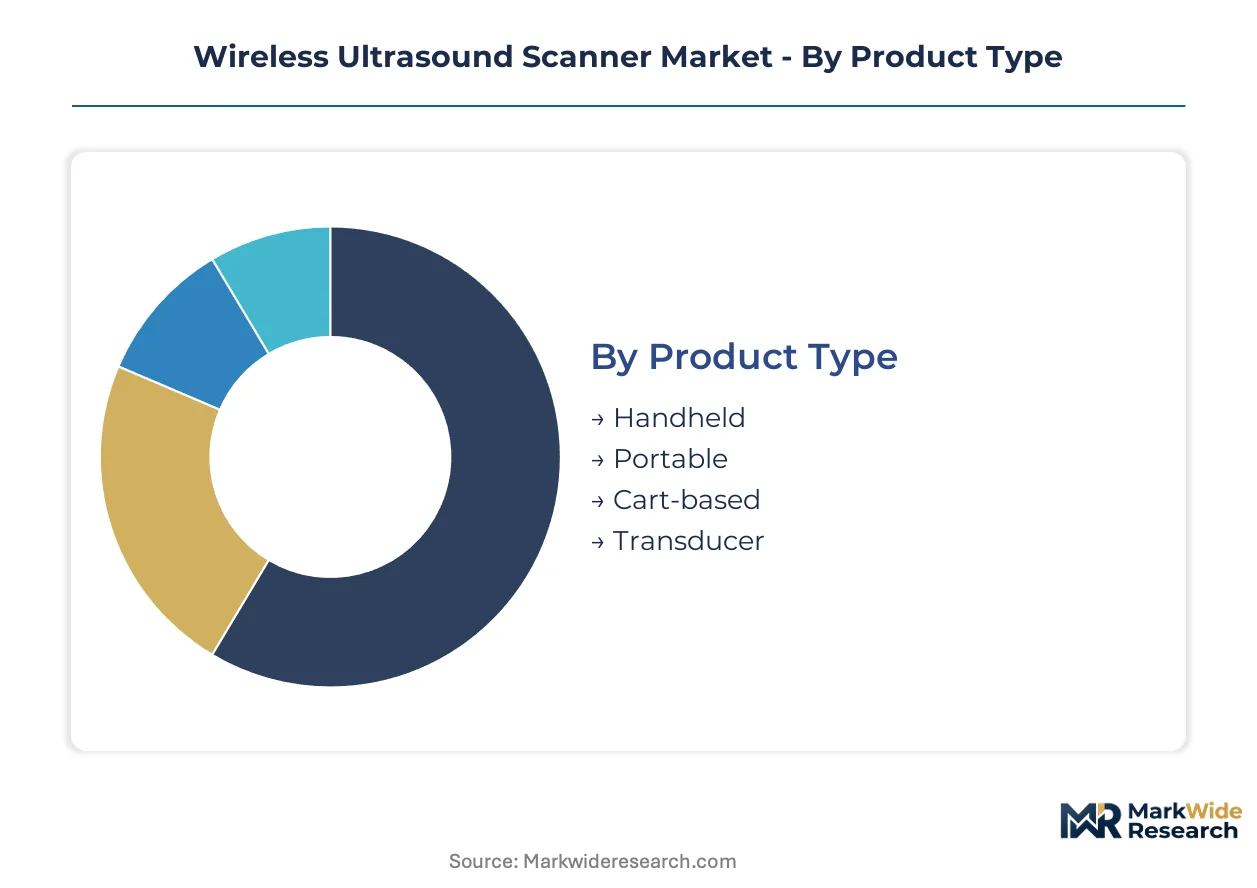
Wireless ultrasound scanner segmentation reveals how hardware form factors, software capabilities, and care delivery settings interact to determine procurement patterns. Product type and technology choices cascade into reimbursement eligibility and clinical workflow integration requirements.
Product Type:
Premium margin pools concentrate in systems that balance portability with diagnostic-grade image quality.
- Handheld:Single-probe devices weighing under 400 grams interface directly with smartphones via Bluetooth 5.0 or Wi-Fi 6. Emergency departments in the United States and trauma centers in Germany deploy these for rapid cardiac and abdominal assessment without waiting for radiology department availability.
- Portable:Battery-operated units with integrated displays and multiple probe connectors serve ambulatory surgery centers and mobile health clinics. These systems capture the largest absolute revenue share by bridging the gap between handheld convenience and cart-based performance.
- Cart-based:Tethered installations with dedicated power supplies and full PACS integration dominate high-volume radiology departments.
- Transducer:Standalone probe replacements and specialty attachments for existing ultrasound platforms generate recurring aftermarket revenue.
The dominant share belongs to Portable systems, while Handheld is closing the gap fastest.
Technology:
Software-enabled differentiation commands pricing power that hardware commoditization erodes.
- AI-enabled:Deep learning algorithms automate anatomical landmark detection, ejection fraction calculation, and pathology flagging. FDA-cleared AI modules from vendors like Butterfly Network and GE HealthCare reduce operator training requirements and extend device utility to primary care physicians in the United States and general practitioners in China.
- Pocket Ultrasound:Ultra-compact CMOS-based systems eliminate discrete crystal arrays through single-chip architectures. These devices are expanding most quickly in resource-limited settings where capital budgets preclude traditional equipment acquisition.
- 3D Imaging:Volumetric acquisition with mechanical or matrix array probes supports obstetric and musculoskeletal applications.
- Doppler Ultrasound:Spectral and color flow mapping capabilities remain essential for vascular assessment and cardiac output measurement.
AI-enabled systems hold the revenue lead, though Pocket Ultrasound shows the steepest expansion trajectory.
End User:
Procurement authority and reimbursement pathways diverge sharply across care settings.
- Emergency Services:Ambulance fleets and air medical programs deploy wireless scanners for field triage and pre-hospital intervention decisions. These units face extreme durability requirements and rapid boot-time specifications.
- Hospitals:Integrated health systems with captive radiology departments prioritize DICOM compliance and enterprise imaging archive connectivity.
- Clinics:Independent physician associations and urgent care chains favor subscription pricing models that align costs with scan volume rather than capital depreciation.
- Home Care:Post-discharge cardiac monitoring and obstetric surveillance create recurring revenue opportunities beyond acute care settings.
Hospitals retain the largest installed base, yet Emergency Services is gaining share fastest.
Delivery Mode:
Data sovereignty requirements and IT infrastructure maturity shape deployment architecture choices.
- Cloud-based:Image storage and AI processing occur on vendor-managed servers with API access for electronic health record integration. Germany's strict data localization requirements under GDPR and BSI standards create compliance complexity for multi-national deployments.
- Mobile Application:Smartphone-native control interfaces with onboard rendering reduce hardware dependency. These solutions are climbing the fastest in China where NMPA regulations increasingly accommodate software-as-medical-device classifications.
- On-premises:Local server installations satisfy hospital IT departments with legacy security protocols.
- Hybrid:Edge processing with cloud backup balances latency sensitivity and scalability.
Cloud-based deployments command the dominant position, while Mobile Application architectures are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for wireless ultrasound scanners diverge sharply across geographies. Emergency medicine services in the United States prioritize rapid triage deployment, while German hospital networks emphasize DICOM-compliant enterprise integration. Chinese healthcare systems favor mobile-native architectures that bypass legacy infrastructure investments.
United States
Ambulance fleets and trauma centers drive procurement for field-ready handheld systems. FDA 510(k) clearance pathways compress commercialization timelines for wireless device manufacturers. The Boston-Cambridge corridor hosts concentrated medtech R&D operations developing AI-enabled interpretation modules.
Germany
Hospital procurement departments prioritize CE-marked devices with full PACS connectivity under EU MDR requirements. Germany's BSI data localization standards create compliance complexity for cloud-native ultrasound platforms. The Baden-Württemberg industrial cluster houses precision transducer manufacturing operations serving European OEMs.
China
Primary care networks and rural clinics adopt pocket ultrasound systems where capital budgets preclude traditional equipment. NMPA registration pathways increasingly accommodate software-as-medical-device classifications for smartphone-controlled probes. Shenzhen's electronics manufacturing ecosystem supplies CMOS sensor components to domestic and international device makers.
Japan
Aging demographics expand home care monitoring applications for post-discharge cardiac surveillance. PMDA regulatory review maintains stringent clinical evidence requirements for AI-enabled diagnostic features. The Kansai region's medical device cluster specializes in miniaturized transducer assemblies for premium portable systems.
United Kingdom
NHS procurement frameworks favor subscription-based software licensing over capital-intensive hardware purchases. MHRA post-Brexit regulatory autonomy creates parallel registration requirements distinct from EU MDR processes. London's digital health accelerator programs incubate telesonography platforms targeting remote clinical guidance applications.
Wireless Ultrasound Scanner Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in wireless ultrasound manufacturing. Diversified health technology conglomerates leverage captive semiconductor supply chains and established hospital sales relationships. Specialist vendors compete through single-chip architectures and cloud-native workflow differentiation. Dominant competitive moves include strategic partnerships with electronic health record platforms and targeted capacity expansion in CMOS sensor foundry capacity.
Within the diversified health technology tier, GE HealthCare and Siemens Healthineers occupy positions anchored by decades of radiology department relationships. Philips Healthcare exemplifies the integrated systems approach combining hardware manufacturing with enterprise software stacks. Among specialist innovators, Butterfly Network and Clarius Mobile Health represent the single-chip and cloud-native archetypes respectively. Mindray Medical International Limited anchors the Asia-Pacific manufacturing vector with Shenzhen-based production operations.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Clarius Mobile Health |
| Butterfly Network |
| Mindray Medical International Limited |
| Fujifilm Holdings Corporation |
| Konica Minolta Healthcare |
| Others |
Value Chain & Pricing Dynamics
CMOS-on-silicon transducer substitution for traditional piezoelectric crystal arrays is redrawing manufacturing geography toward East Asian semiconductor foundries while collapsing premium hardware pricing tiers through reduced bill-of-materials complexity.
Pricing Analysis
Long-term offtake agreements between hospital purchasing groups and device manufacturers dominate procurement, though subscription-based SaaS licensing for AI interpretation modules is gaining share among ambulatory networks. Price differentiation rests on FDA 510(k) clearance tier and enterprise PACS integration depth, with premium handheld systems commanding substantial markups over unconnected probes. Cost compression in the standard tier is intensifying as Shenzhen-based CMOS suppliers flood the component market. Emergency medical services exhibit the highest price sensitivity due to municipal budget constraints, while integrated health systems show relative inelasticity when bundled with EHR contracts.
Supply Chain Analysis
China and Taiwan anchor CMOS sensor fabrication for single-chip ultrasound architectures, while Japan and Germany retain precision lead zirconate titanate crystal production for premium transducer assemblies. Raw material dependencies include high-purity silicon wafers, lead zirconate titanate ceramics, and medical-grade encapsulation polymers. Single-source vulnerability concentrates in advanced CMOS foundry capacity concentrated in Taiwan. Distribution runs through specialized medical device distributors with GPO contracts into hospital procurement departments, supplemented by direct-to-clinic sales for handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent device manufacturers face substitution pressure from software-centric entrants whose cloud-native platforms erode traditional hardware attachment rates.
For Market Incumbents: Secure captive piezoelectric supply through backward integration into crystal manufacturing or exclusive offtake with Japanese suppliers, insulating against CMOS substitution in deep-tissue applications. Accelerate FDA 510(k) submissions for AI-enabled modules to defend reimbursement code access against Butterfly Network and Clarius Mobile Health encroachment.
For New Entrants and Emerging Players: Differentiate on 5G-enabled telesonography workflows targeting rural clinic networks in China and India where specialist scarcity creates immediate demand for remote guidance capabilities. Pursue per-scan subscription pricing to bypass capital budget barriers in independent physician associations.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated hardware-software stacks over pure-play component suppliers. Target acquisition profiles should emphasize firms with NMPA registration in China and established cloud infrastructure. The signal to watch is CMS reimbursement code expansion for point-of-care ultrasound, which would trigger accelerated outpatient deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks German hospital procurement frameworks under BSI oversight. |
| Hospital System Partnership | Epic and Cerner EHR integration secures enterprise imaging workflow positioning. |
| Software Companion Development | FDA-cleared AI modules reduce operator training burden and expand addressable clinician base. |
| Reimbursement Strategy | CMS Category III code conversion to permanent status accelerates outpatient adoption velocity. |
| CMOS Foundry Partnership | Shenzhen semiconductor access lowers unit economics for pocket ultrasound manufacturing. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, NMPA registration filings, and hospital procurement databases. Primary interviews engaged biomedical engineers, GPO contracts managers, emergency department clinicians, and CMOS foundry operations directors. Secondary sources included CMS reimbursement code determinations, EU MDR technical documentation, and SEC filings from publicly traded device manufacturers. Bottom-up unit shipment estimates triangulated against top-down healthcare IT spending allocations.
Segmentation dimensions modeled span product type, technology architecture, end-user setting, and delivery mode across the projection horizon. CAGRs derived from regression analysis of historical adoption curves weighted by regulatory approval timelines and reimbursement policy shifts. Industry-specific forecast inputs incorporated semiconductor foundry capacity expansion schedules and point-of-care ultrasound training program deployment rates.
Material uncertainties — regulatory reclassification of AI diagnostic features, supply disruption in lead zirconate titanate sourcing, and CMS coverage determination reversals — sit outside the modeled envelope. Recalibration cycles align with material shifts in reimbursement policy and semiconductor supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Hyperspectral Imaging Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Dental Digital X Ray Market
Medical Imaging
Spain Magnetic Resonance Imaging Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
US Teleradiology Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
South America Mammography Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Japan Nuclear Imaging Market