
 Breast Imaging Market | 2026-2036
Breast Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Breast Imaging Market Intelligence
China's expanding manufacturing capacity for medical devices is fragmenting the established supplier base for breast imaging systems. Siemens Healthineers leverages its extensive R&D in digital imaging to maintain a premium position in the market. Hologic Inc. specializes in tomosynthesis and 3D imaging technologies, creating a strong niche focus. GE Healthcare competes on a global scale through its broad portfolio and extensive service network in hospitals and diagnostic centers.
Breast imaging encompasses medical procedures that create pictures of the internal structures of the breast, primarily for cancer detection. These systems, particularly digital mammography and tomosynthesis, utilize low-dose X-rays to achieve high spatial resolution for detecting microcalcifications. Tomosynthesis technology represents the fastest-growing product type, increasingly adopted for screening applications over standard 2D mammography. The diagnostic application segment, while smaller in volume than screening, provides higher value per procedure.
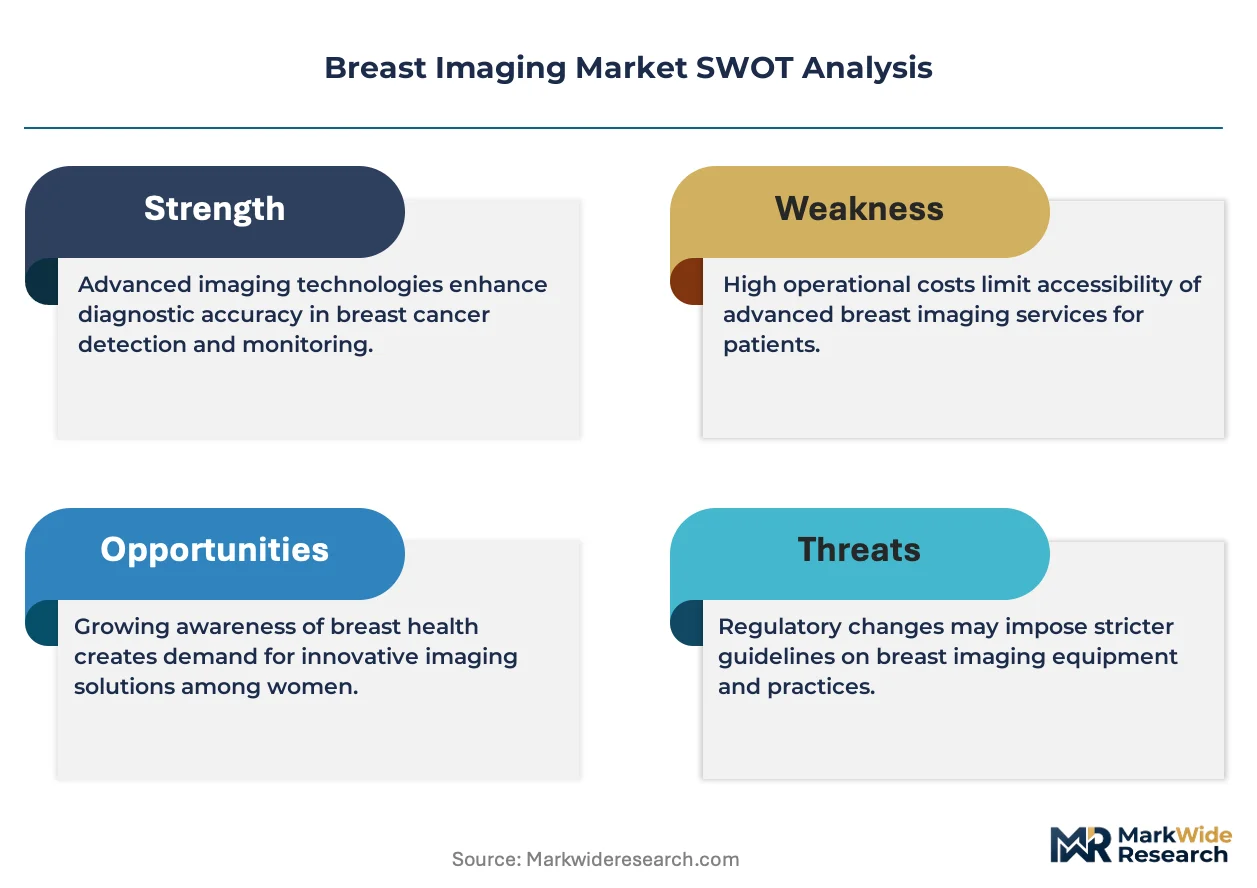
Market access is governed by stringent regulatory approvals from bodies like the US Food and Drug Administration (FDA) and adherence to Europe's Medical Device Regulation (MDR). These frameworks mandate extensive clinical data on safety and efficacy, influencing product development timelines and costs. System manufacturers and healthcare providers must decide whether to invest in standalone AI software or integrated systems that bundle analytics with new imaging hardware.
Market Dynamics
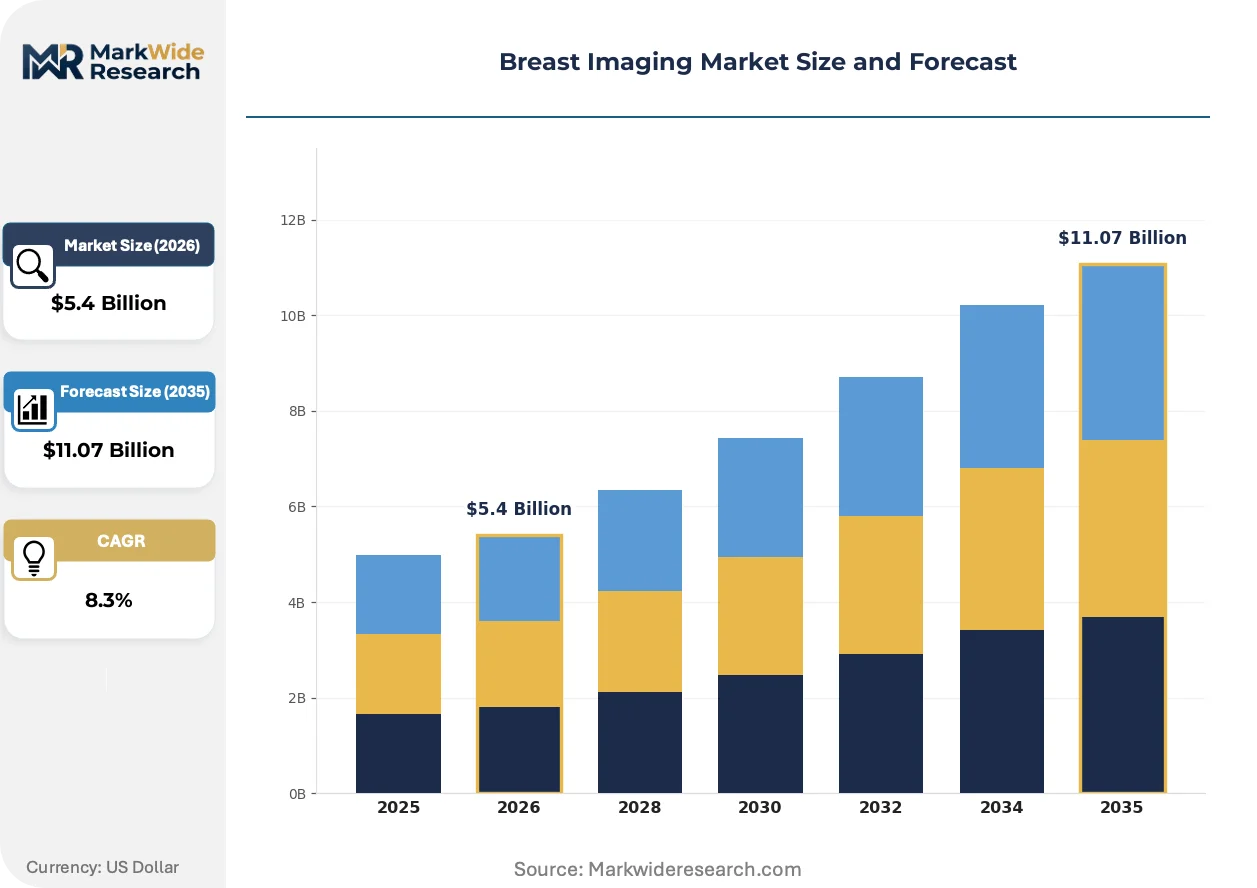
The central force shaping the market is the technological transition from 2D mammography to 3D tomosynthesis, amplified by the integration of artificial intelligence. This shift addresses clinical demands for higher cancer detection rates, especially in dense breast tissue.
Growth Catalysts
- National Screening Programs:Government-funded initiatives in countries like the United Kingdom and Germany mandate regular mammograms, creating a stable, high-volume demand base for screening systems and consumables.
- AI-Powered Analytics:The adoption of AI algorithms for image interpretation accelerates radiologist workflow, improves diagnostic accuracy, and reduces false-positive rates, encouraging investment in AI-enabled hardware and software.
- Diagnostic Center Expansion:An increasing number of outpatient diagnostic centers are investing in advanced imaging technology to compete on service quality and patient throughput, driving system upgrades and new installations.
Market Restraints
- High System Cost:The significant capital investment required for digital breast tomosynthesis (DBT) and AI-integrated systems presents a major barrier for smaller clinics and hospitals, particularly in emerging economies.
- Stringent Regulatory Hurdles:Gaining market access requires lengthy and costly clinical trials to satisfy regulators like the US FDA and to comply with Europe's Medical Device Regulation (MDR), delaying product launches.
- Data Management Infrastructure:The large file sizes generated by 3D tomosynthesis scans place substantial strain on hospital IT networks and data storage infrastructure, requiring costly upgrades to PACS systems.
Strategic Opportunities
- Emerging Market Penetration:Developing healthcare systems in regions like Southeast Asia and Latin America represent significant growth opportunities as they begin to establish and expand national breast cancer screening programs.
- Standalone AI Software:Offering AI analytics as a software-as-a-service (SaaS) solution allows healthcare providers to upgrade the capabilities of their existing imaging hardware without a full system replacement.
- Multi-Modality Integration:There is an opportunity to develop integrated platforms that combine mammography data with information from other modalities like ultrasound or MRI for a more holistic diagnostic assessment.
Industry Challenges
- Radiologist and Technician Shortage:A deficit of trained personnel qualified to operate advanced imaging systems and interpret complex 3D and AI-assisted scans creates operational bottlenecks for healthcare providers.
- System Interoperability:Ensuring seamless integration of new imaging systems and AI software with existing, often proprietary, Picture Archiving and Communication Systems (PACS) and electronic health records is a persistent technical challenge.
- Reimbursement Variability:Inconsistent reimbursement policies for advanced procedures like tomosynthesis and AI-assisted readings across different regions and payers can limit their adoption by budget-conscious providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast Imaging Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $11.07 Billion |
| CAGR (2026 – 2036) | 8.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mammography, Ultrasound, Magnetic Resonance Imaging, Tomosynthesis, Molecular Breast Imaging Technology: Digital, Analog, 3D Imaging, Contrast-Enhanced, Automated Image Analysis Application: Screening, Diagnostic, Surgical Planning, Risk Assessment, Treatment Monitoring End User: Diagnostic Centers, Specialty Clinics, Research Institutions, Mobile Units |
| Companies Covered | FUJIFILM Holdings Corporation, Canon Inc., GE Healthcare, Aurora Healthcare US Corp., Planmed Oy, Hologic Inc., Koninklijke Philips N.V., Carestream Health, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast Imaging Market Strategic Shifts & Innovations
Data-centric diagnostics and workflow automation are defining the next phase of market evolution. The focus is shifting from pure image acquisition to intelligent data analysis that enhances clinical decision-making and operational efficiency in breast cancer screening and diagnosis.
Contrast-enhanced mammography (CEM) provides functional information by using an iodine-based agent to highlight areas of neovascularity. Specialized cancer centers and large hospitals are adopting CEM for diagnostic workups, particularly for inconclusive findings from standard mammography or for pre-surgical planning. This technology is digitizing the assessment of tumor vascularity, adding a physiological dimension to the structural detail provided by conventional imaging.
Europe's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on all medical devices, including breast imaging systems. This regulatory shift increases the compliance burden and costs for manufacturers, forcing more rigorous data collection throughout the product lifecycle. System vendors are consequently investing more heavily in clinical affairs and quality management systems to meet the elevated standards for placing and keeping products on the European market.
A shift toward enterprise-wide imaging strategies is altering purchasing behaviors within large healthcare networks. Instead of department-level procurement, centralized decision-making prioritizes system standardization, interoperability with existing IT infrastructure, and fleet management capabilities. This trend favors vendors who can offer a broad portfolio, extensive service networks, and integrated data management solutions, visible in consolidated health systems in the United States and Germany.
Breast Imaging Market Segmentation
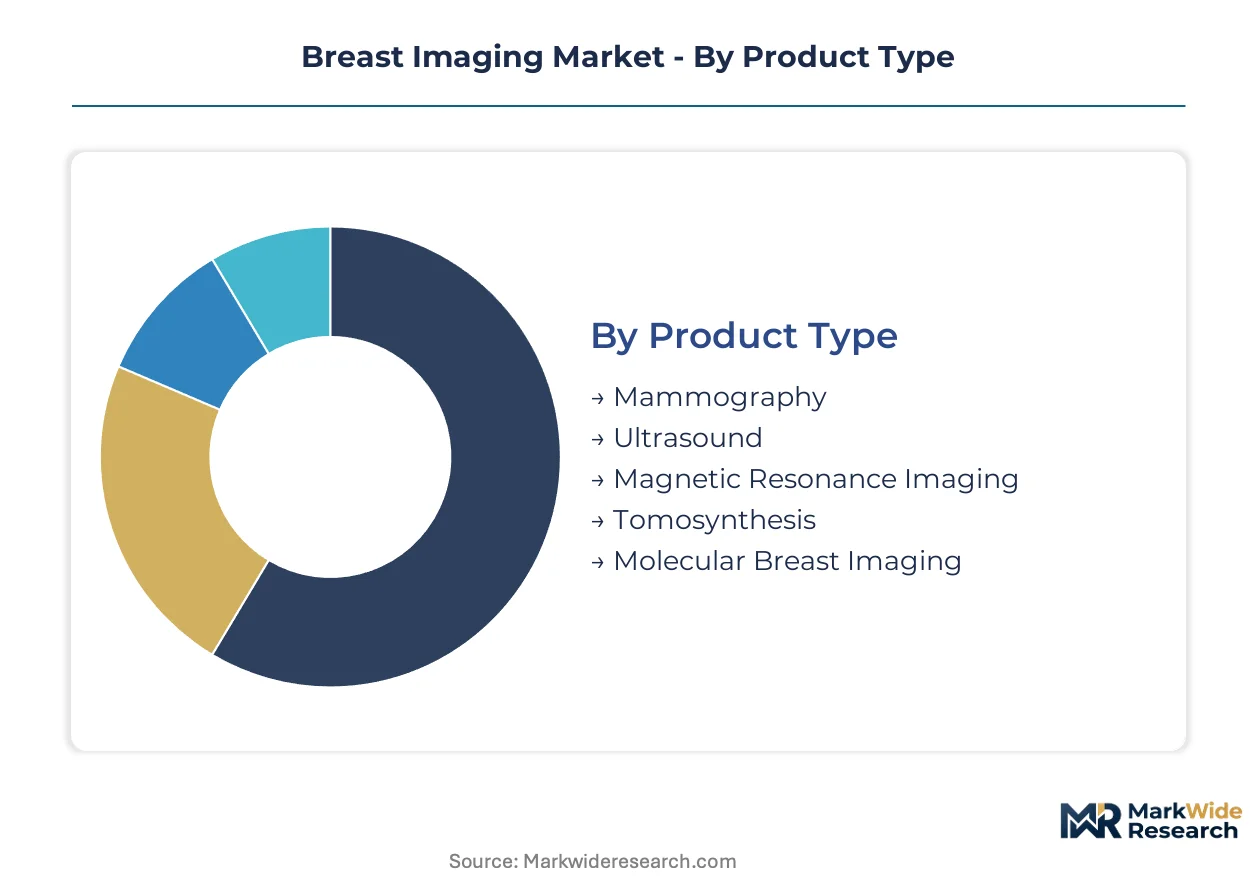
Segmentation analysis provides a granular understanding of the breast imaging market, highlighting the specific product types, technologies, applications, and end-user segments driving demand and innovation. This detailed breakdown reveals the distinct clinical needs and operational environments shaping investment decisions and technological advancements across the healthcare landscape.
Product Type:
The breast imaging market's product type segmentation reflects the diverse clinical requirements for visualizing breast tissue across various diagnostic and screening scenarios.
- Tomosynthesis:Tomosynthesis employs multiple low-dose X-ray images from different angles to reconstruct a 3D volume of the breast, offering enhanced lesion detection. Demand for tomosynthesis is concentrating in national screening programs in countries like the United Kingdom and Germany, driven by its superior ability to detect cancers in dense breast tissue.
- Mammography:Mammography uses low-dose X-rays to create 2D images of breast tissue, serving as the primary modality for routine screening due to its established efficacy. Demand for mammography systems remains high in established diagnostic centers globally, supported by its widespread adoption in population-based screening initiatives.
- Ultrasound:Ultrasound systems utilize high-frequency sound waves to generate real-time images, often employed as an adjunct to mammography for further characterization of suspicious lesions.
- Magnetic Resonance Imaging:Magnetic Resonance Imaging (MRI) offers high-resolution soft tissue contrast without radiation, primarily used for high-risk screening, staging, and problem-solving in complex cases.
- Molecular Breast Imaging:Molecular Breast Imaging (MBI) uses a radioactive tracer to highlight metabolically active cancer cells, providing functional information for diagnostic workups in specific populations.
Established volume favors Mammography; emerging adoption favors Tomosynthesis.
Technology:
Technology segmentation delineates the varying levels of sophistication and investment required for breast imaging systems, influencing accessibility and diagnostic capability.
- 3D Imaging:3D imaging technologies, primarily digital breast tomosynthesis, capture multiple projection images to reconstruct a three-dimensional view of the breast. Demand for 3D imaging is concentrating in advanced diagnostic centers seeking improved lesion detection and reduced recall rates, especially in regions with high breast density prevalence.
- Automated Image Analysis:Automated Image Analysis integrates artificial intelligence algorithms to assist radiologists in interpreting breast images, identifying abnormalities, and quantifying features. Demand for automated image analysis is concentrating in large hospital networks and screening programs aiming to enhance workflow efficiency and improve diagnostic accuracy.
- Digital:Digital technology involves electronic detectors converting X-ray photons directly into digital images, offering improved image quality and post-processing capabilities over film-based systems.
- Contrast-Enhanced:Contrast-Enhanced technology, such as CEM, utilizes an iodine-based agent to highlight areas of increased vascularity associated with malignant lesions.
- Analog:Analog technology relies on film-screen systems for image capture, representing an older generation of mammography that is progressively being replaced by digital solutions.
The evolution of diagnostic capabilities is driven by 3D Imaging, while operational efficiency gains stem from Automated Image Analysis.
Application:
The application segmentation illustrates how breast imaging procedures are utilized across the patient care continuum, from population-level screening to precise treatment guidance.
- Screening:Screening applications involve routine examinations of asymptomatic women to detect breast cancer at an early, more treatable stage, improving patient outcomes. Demand for screening procedures is concentrating in countries with established national programs, such as the United Kingdom and Germany, which mandate regular examinations.
- Diagnostic:Diagnostic applications focus on evaluating symptomatic patients or further investigating abnormal findings from screening mammograms or clinical exams. Demand for diagnostic procedures is concentrating in specialty clinics and hospitals where detailed characterization of suspicious lesions is critical for treatment planning.
- Surgical Planning:Surgical Planning applications leverage imaging data to precisely localize lesions, define tumor margins, and guide surgical interventions, enhancing procedural accuracy.
- Risk Assessment:Risk Assessment applications use imaging alongside clinical factors to identify individuals at higher risk of developing breast cancer, guiding personalized surveillance strategies.
- Treatment Monitoring:Treatment Monitoring applications track the response of known breast cancers to therapies, assessing changes in tumor size or characteristics over time.
The market's foundational activity resides in Screening, while its value expansion is concentrated in Diagnostic applications.
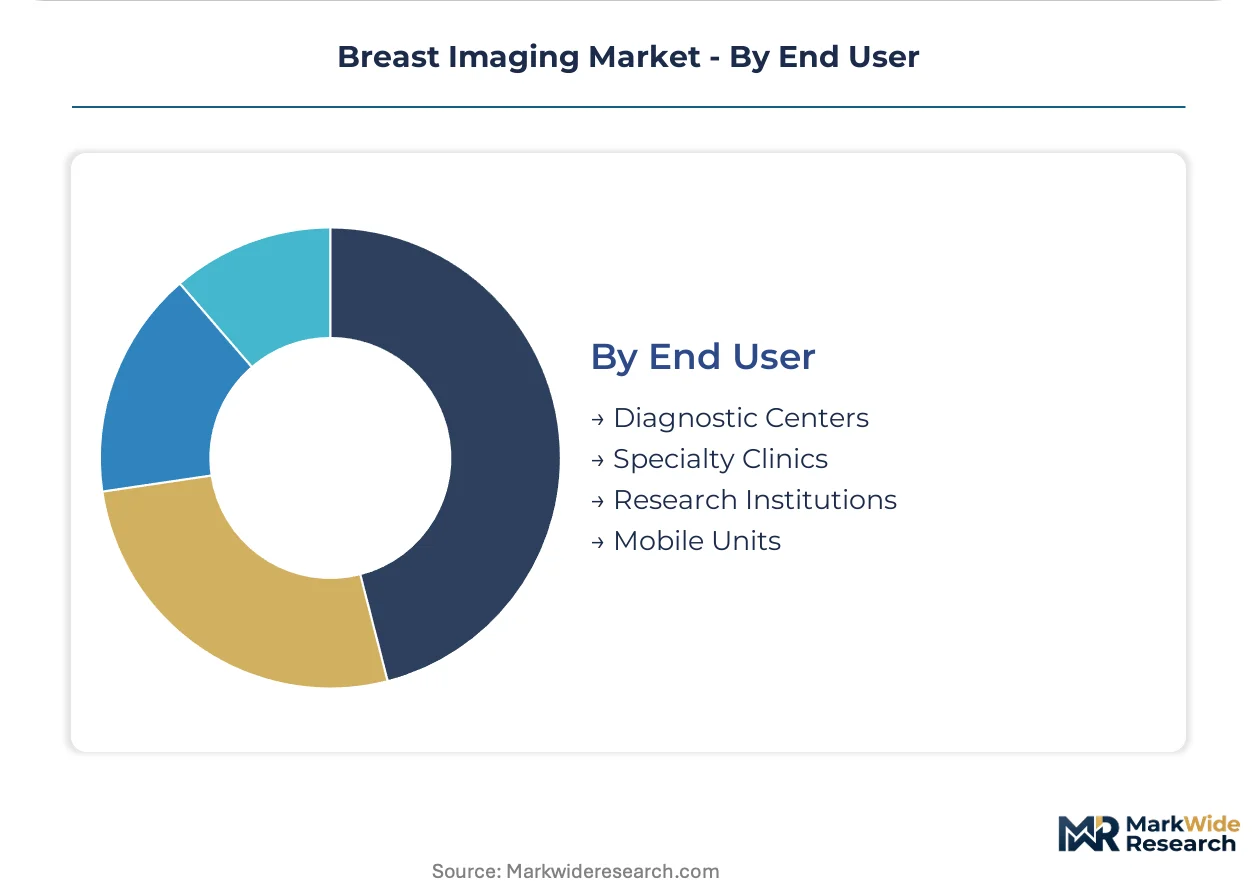
End User:
End user segmentation highlights the diverse institutional settings where breast imaging systems are deployed, each with unique operational needs and procurement patterns.
- Diagnostic Centers:Diagnostic Centers are specialized outpatient facilities offering a range of imaging services, prioritizing efficiency and patient throughput for screening and diagnostic procedures. Demand from diagnostic centers is concentrating on advanced imaging technology to enhance service quality and accommodate increasing patient volumes.
- Specialty Clinics:Specialty Clinics, often focused on women's health or oncology, provide comprehensive breast care services, requiring sophisticated imaging systems for complex diagnostic workups and follow-up. Demand from specialty clinics is concentrating on high-resolution modalities and integrated solutions that support precise diagnosis and personalized treatment pathways.
- Research Institutions:Research Institutions utilize breast imaging systems for clinical trials, technology development, and understanding disease progression, contributing to future innovations.
- Mobile Units:Mobile Units bring screening services to underserved populations or remote areas, improving accessibility to early detection programs.
Volume-driven adoption is characteristic of Diagnostic Centers, whereas specialized care drives investment in Specialty Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for medical devices, particularly breast imaging systems, increasingly concentrates in key global hubs. This supply-side focus drives innovation and cost efficiencies for system providers. Established screening programs and advanced healthcare infrastructure further shape regional demand dynamics.
United States
Demand for advanced breast imaging systems stems from a large patient pool and high healthcare expenditure. The US FDA mandates rigorous clinical data for market approval, influencing product development timelines. Major medical technology clusters in Boston and California drive R&D and new product launches.
Germany
National screening programs and a well-established healthcare infrastructure generate consistent demand for tomosynthesis systems. Europe's MDR imposes strict requirements for clinical evidence, affecting market access for new devices. Bavaria and North Rhine-Westphalia house significant medical device manufacturing and research facilities.
United Kingdom
Government-funded initiatives ensure a stable, high-volume demand base for breast screening systems. The NHS breast screening program prioritizes early detection through regular examinations for eligible women. London and Cambridge serve as hubs for health tech innovation and clinical research.
China
Expanding manufacturing capacity for medical devices positions China as a significant supplier and consumer. The NMPA regulates medical device approvals, fostering domestic innovation and market entry. The Yangtze River Delta region is a key area for medical device production and technological advancement.
Japan
An aging population and high healthcare standards drive investment in advanced diagnostic technologies. The PMDA oversees medical device approvals, ensuring safety and efficacy for new breast imaging solutions. Tokyo and Osaka host prominent medical device companies and research institutions.
Breast Imaging Market Key Industry Players
Global specialists and regional innovators split the breast imaging market, creating a tiered competitive environment. The market structure favors companies with extensive R&D capabilities and broad product portfolios. Strategic archetypes include established imaging giants, specialized technology providers, and emerging AI software developers. Companies pursue portfolio diversification and strategic partnerships to enhance their market presence.
Within the established imaging giants, Siemens Healthineers and GE Healthcare exemplify broad portfolio strategies and extensive service networks across hospitals and diagnostic centers. Siemens Healthineers leverages its significant R&D in digital imaging to maintain a premium market position, while GE Healthcare competes globally through its comprehensive product offerings. Hologic Inc. occupies a distinct position as a specialized technology provider, focusing on advanced tomosynthesis and 3D imaging innovations. These companies anchor key market segments through their technological leadership, regulatory compliance, and global distribution channels. Their activities collectively shape product development and market access strategies.
| Leading Market Players |
|---|
| FUJIFILM Holdings Corporation |
| Canon Inc. |
| GE Healthcare |
| Aurora Healthcare US Corp. |
| Planmed Oy |
| Hologic Inc. |
| Koninklijke Philips N.V. |
| Carestream Health |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta region, a significant medical device production hub, exerts considerable influence on downstream pricing dynamics for breast imaging systems. Expanding manufacturing capacity in this area contributes to competitive pricing pressures globally.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure for breast imaging systems, requiring significant investment in clinical evidence. Pricing stratifies across premium systems with advanced AI and 3D imaging, to more standard digital mammography units; differentiation also stems from regulatory compliance and integrated service offerings. Pricing softness runs through the standard digital mammography segment due to increasing competition and manufacturing efficiencies. Smaller clinics and hospitals exhibit higher price sensitivity compared to large hospital networks.
Supply Chain Analysis
Upstream sourcing of high-resolution digital detectors and specialized X-ray tubes forms a critical dependency for breast imaging system manufacturers. Manufacturing concentrates in countries like China, Germany, and the United States, influencing component availability. A key supply chain risk involves single-source vulnerability for highly specialized X-ray components, impacting production timelines. Distribution runs through direct sales forces for major players like GE Healthcare and Siemens Healthineers, complemented by regional distributors for niche technology providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breast imaging market is currently in an early-cycle expansion phase, driven by the accelerating transition from 2D mammography to 3D tomosynthesis. This technological shift, amplified by AI integration, enhances diagnostic capabilities and workflow efficiency.
For Market Incumbents: Pre-empt disruption from emerging AI software developers by deepening integrated AI capabilities within existing hardware platforms. Expand service networks in developing healthcare systems to capture early growth in national screening programs. Prioritize R&D in advanced digital imaging, particularly contrast-enhanced mammography, to maintain a premium market position. Strengthen regulatory affairs teams to navigate evolving frameworks like Europe's MDR, ensuring continuous market access.
For New Entrants and Emerging Players: Standalone AI software-as-a-service (SaaS) solutions represent the most penetrable entry point, allowing upgrades to existing imaging hardware without full system replacement. Target diagnostic centers in emerging markets like Southeast Asia, which are establishing new screening programs. Focus on developing AI algorithms that reduce radiologist workload and improve diagnostic accuracy, offering clear workflow efficiency gains. Strategic partnerships with local distributors can accelerate market penetration.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven healthcare diagnostics play because of the persistent global demand for early breast cancer detection and ongoing innovation. Acquisition targets include specialized AI software developers enhancing image interpretation and niche tomosynthesis innovators expanding clinical applications. Focus on companies with strong regulatory compliance records and established market access in key regions. The signal to watch is the expansion of reimbursement policies for advanced imaging procedures and AI-assisted readings across major healthcare systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI Software Integration | Enhances diagnostic accuracy and radiologist workflow efficiency across hospital networks. |
| Expand Emerging Market Footprint | Captures new demand from developing national breast cancer screening programs in Southeast Asia. |
| Develop Multi-Modality Platforms | Offers a more holistic diagnostic assessment by combining mammography with ultrasound data. |
| Invest in Regulatory Affairs Expertise | Ensures continuous market access and compliance with stringent frameworks like Europe's MDR. |
| Advance Tomosynthesis R&D | Maintains technological leadership in 3D imaging, crucial for dense breast tissue detection. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis. Primary interviews included radiologists, hospital procurement managers, medical device engineers, and regulatory compliance officers. Secondary validation drew from US FDA filings, Europe MDR guidelines, clinical trial databases, and national health statistics. A robust bottom-up and top-down triangulation approach ensured data accuracy.
Forecast calibration utilized historical market trends and future growth projections across the analysis window. The model segmented data by product type, technology, application, end-user, and regional breast density prevalence. Compound Annual Growth Rates were derived from market share shifts and underlying adoption drivers, with key inputs including the installed base of 2D mammography systems and AI algorithm development pace.
Macroeconomic conditions sit as an overlay; deviation in healthcare expenditure or regulatory policies would shift the trajectory. Forecasts reflect assumptions documented through extensive research. Cross-checking against national health organization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Digital X-Ray Imaging Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Digital X Ray Market
Medical Imaging
AI Radiology Worklist Orchestration Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Global Technetium-99M Market