
 United States Digital X-Ray Devices Market | 2026-2036
United States Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Digital X-Ray Devices Market Analytics
Project finance and equipment leasing is tilting competitive dynamics toward vendors with strong balance sheets and captive financing arms. GE Healthcare leverages its in-house capital division to place fixed systems in cash-constrained community hospitals. Siemens Healthineers sustains premium positioning through direct long-term service contracts that lock in replacement cycles. Carestream competes aggressively on retrofit system financing, converting aging analog rooms at lower upfront cost.
Digital x-ray devices capture two-dimensional projection images using solid-state flat-panel detectors with cesium iodide or gadolinium oxysulfide scintillators, converting x-ray photons directly into digital signals for immediate display and storage. Their primary purpose spans diagnostic radiology, intraoperative imaging, and emergency trauma screening across ambulatory and acute care settings. Portable systems command expanding share as hospital-at-home programs and rural outreach expand, while fixed systems retain margin concentration in high-throughput academic medical centers. Flat-panel technology leads volume but hybrid systems are gaining traction in orthopedic surgery suites seeking intraoperative flexibility.
FDA 510(k) clearance pathways shape product development timelines and predicate device strategies for domestic manufacturers. CMS reimbursement codes and the Protecting Access to Medicare Act quality criteria directly influence hospital capital allocation toward digital replacement. OSHA radiation exposure standards and state-level certificate-of-need regulations in states like New York and Illinois constrain installed-base expansion. Stakeholders must monitor how AI-enabled diagnostic algorithms trigger new FDA software-as-medical-device classifications and reshape procurement evaluation criteria.
Market Dynamics
Flat-panel detector technology is collapsing legacy computed radiography economics, forcing hospital networks in Texas, Florida, and California to accelerate replacement cycles ahead of Protecting Access to Medicare Act quality deadlines.
Growth Catalysts
- CMS value-based reimbursement:Outpatient clinics are expanding digital radiography adoption as reimbursement policies shift toward quality metrics and reduced repeat imaging rates.
- Hospital-at-home expansion:Portable systems command expanding share from Medicare-funded home health programs requiring point-of-care diagnostic capability.
- Cesium iodide scintillator advances:Improved photon conversion efficiency is lowering radiation dose requirements while maintaining image resolution in trauma screening.
Market Restraints
- Certificate-of-need regulations:State-level CON laws in New York and Illinois constrain installed-base expansion by requiring capital expenditure approval for new fixed-room installations.
- Flat-panel supply concentration:Detector manufacturing concentrates among a limited supplier base in East Asia, creating input vulnerability for domestic system integrators.
- Computed radiography residual value:Existing CR infrastructure in rural facilities delays replacement decisions despite superior flat-panel workflow economics.
Strategic Opportunities
- AI-enabled diagnostic algorithms:FDA software-as-medical-device classifications for computer-aided detection are creating new procurement evaluation criteria and premium positioning potential.
- Orthopedic hybrid systems:Surgery suites in high-volume joint replacement centers are adopting dual-purpose fixed/portable configurations for intraoperative flexibility.
- Rural outreach networks:Federally qualified health centers in underserved counties present untapped demand for mobile digital radiography units.
Industry Challenges
- Interoperability with PACS legacy:Hospital IT departments face integration complexity connecting new digital detectors to aging picture archiving infrastructure without full replacement.
- OSHA radiation officer certification:Facilities struggle to retain qualified medical physicists for compliance with exposure monitoring and equipment calibration mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Digital X-Ray Devices Market |
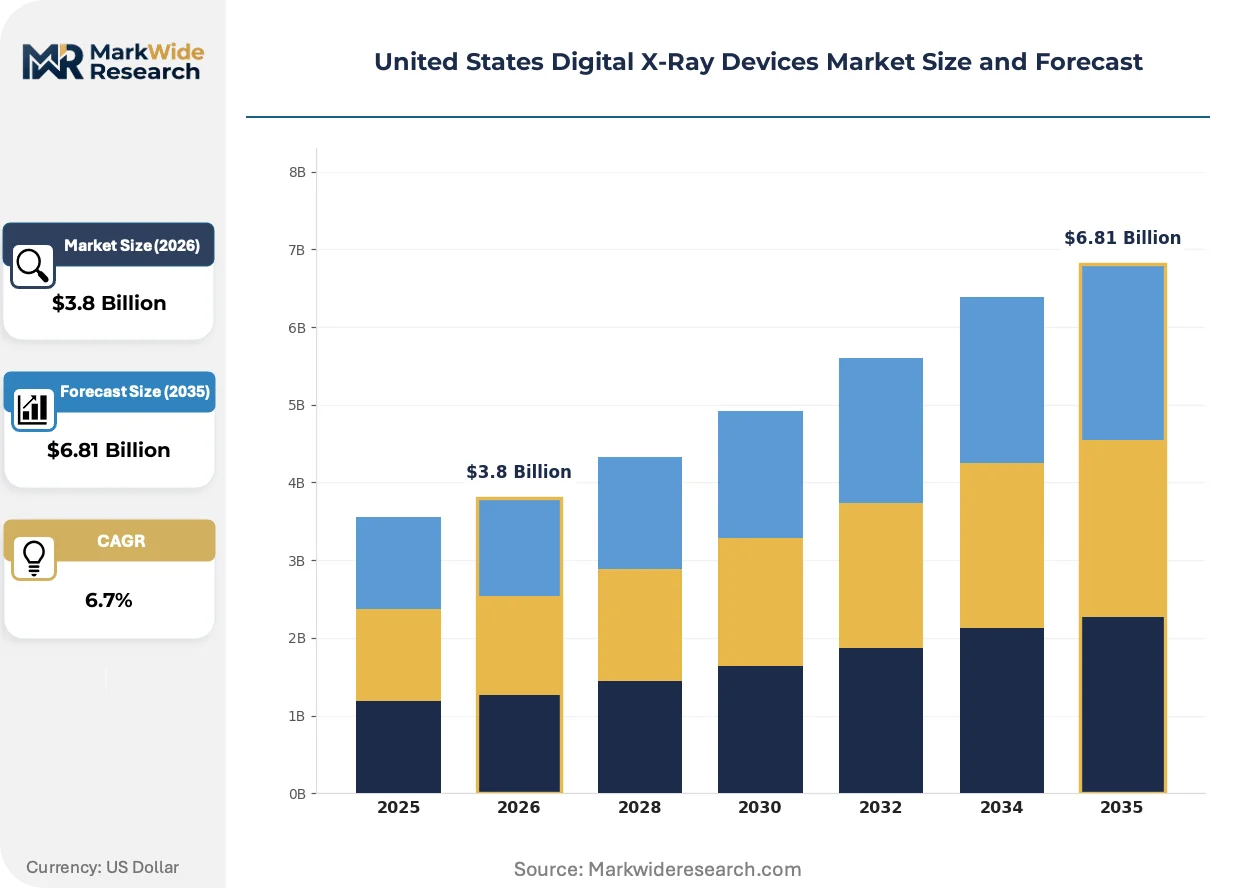
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Portable Systems, Retrofit Systems, Mobile Systems End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Flat Panel, Computed Radiography, Digital Radiography, Hybrid Systems Application: Orthopedics, Dentistry, Cardiology, Oncology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, FUJIFILM Holdings Corp, Canon Medical Systems Corporation, Carestream Health, Samsung Electronics Co Ltd, Varex Imaging Corporation, Shimadzu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Digital X-Ray Devices Market Evolving Landscape
Technology convergence and regulatory pressure are compressing product lifecycles while redrawing competitive boundaries between equipment manufacturers and software developers.
Direct-conversion flat-panel detectors using amorphous selenium photoconductors are collapsing the performance gap between general radiography and specialized mammography systems. Academic medical centers in California are piloting these panels for high-resolution extremity imaging. The technology is collapsing price premiums previously commanded by dedicated systems, forcing vendors to bundle advanced visualization software to maintain margin.
FDA 510(k) clearance pathways are tightening predicate device requirements for AI-enhanced imaging systems, extending development timelines for algorithm developers seeking diagnostic claims. Manufacturers must now submit clinical validation data beyond traditional technical performance benchmarks. Radiology groups in Florida are delaying procurement decisions pending clarity on reimbursement codes for computer-aided detection.
Equipment leasing through captive finance arms is displacing traditional capital purchase models in community hospitals with constrained balance sheets. GE Healthcare's in-house capital division and similar vendor financing programs are capturing multi-year service lock-in. Texas hospital networks are negotiating bundled replacement cycles that tie detector upgrades to long-term maintenance agreements.
United States Digital X-Ray Devices Market Segmentation
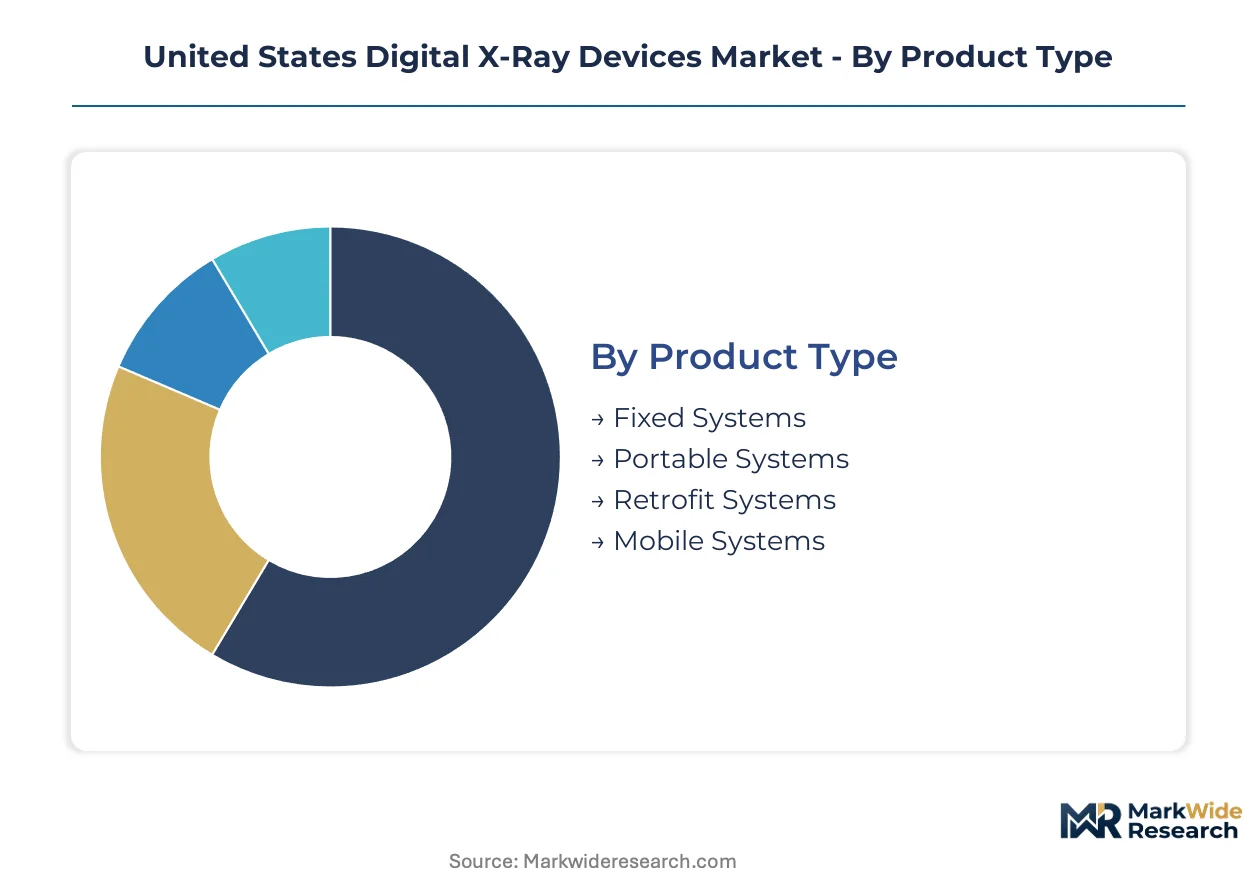
Segmentation in the United States digital x-ray devices market reveals distinct service intensity patterns across equipment categories. Procurement decisions diverge sharply between high-throughput fixed installations requiring intensive maintenance contracts and mobile units demanding rapid field response capabilities.
Product Type:
After-sales-service intensity varies dramatically across product categories, with fixed systems generating multi-year service lock-in while portable units require rapid turnaround logistics.
- Fixed Systems:These installations integrate cesium iodide flat-panel detectors into dedicated radiography rooms with overhead tube suspension and automated positioning. Demand clusters in California academic medical centers where high patient throughput justifies capital-intensive infrastructure and premium service agreements.
- Portable Systems:Battery-powered wireless detectors enable bedside imaging in ICU settings and emergency departments. Texas hospital-at-home programs are driving procurement as Medicare reimbursement expands for point-of-care diagnostics in residential settings.
- Retrofit Systems:Conversion kits upgrade existing analog rooms with digital detector panels at reduced capital outlay.
- Mobile Systems:Self-contained units on motorized bases serve multiple departments within large hospital campuses.
Fixed systems hold the largest share; momentum sits with portable systems.
End User:
Customer type determines pricing tolerance and replacement cycle timing, with hospitals prioritizing uptime guarantees while clinics emphasize acquisition cost.
- Hospitals:Integrated delivery networks in Florida negotiate enterprise-wide agreements bundling equipment, software, and predictive maintenance. These facilities demand 99.5% uptime guarantees and same-day service response for critical care units.
- Clinics:Outpatient facilities in Texas pursue retrofit solutions to meet CMS quality metrics without full room replacement capital burden.
- Diagnostic Centers:Specialized imaging chains concentrate volume in high-margin procedures requiring rapid throughput.
- Research Institutions:Academic medical centers pilot emerging detector technologies before commercial deployment.
Hospitals dominate installed base value; clinics are expanding most quickly.
Technology:
Technology choice dictates detector supply chain exposure and regulatory pathway complexity for manufacturers seeking FDA clearance.
- Flat Panel:Direct-conversion amorphous selenium and indirect-conversion cesium iodide scintillator architectures deliver immediate digital imaging with dose reduction. California orthopedic surgery suites are adopting these for high-resolution extremity work.
- Computed Radiography:Photostimulable phosphor plate systems persist in rural facilities where replacement capital remains constrained despite inferior workflow economics.
- Digital Radiography:Solid-state detector systems with integrated acquisition software streamline PACS connectivity.
- Hybrid Systems:Dual-purpose configurations switch between fixed-room and portable operation for intraoperative flexibility.
Flat panel technology commands the largest share; hybrid systems are gaining share fastest.
Application:
Application-specific requirements drive detector specification differentiation and software bundling strategies among vendors.
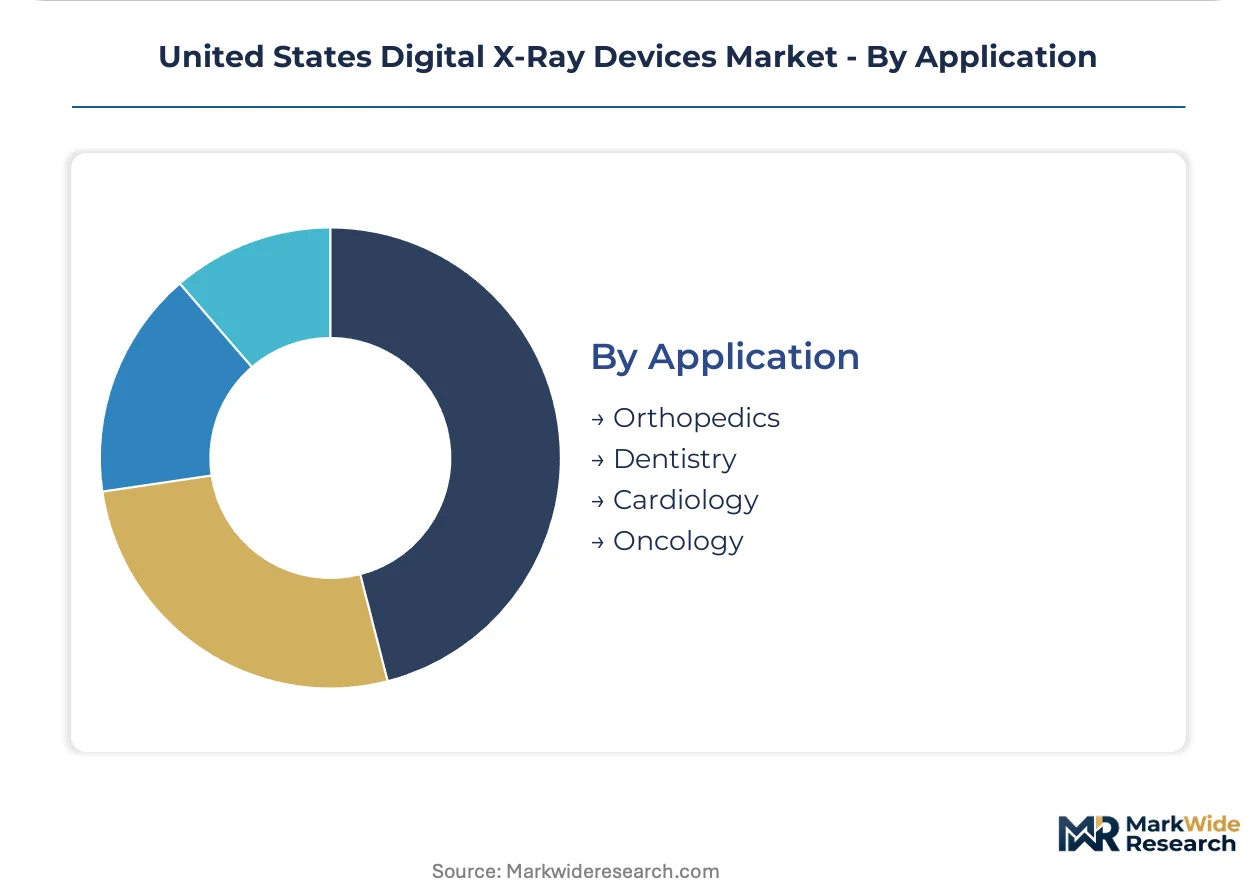
- Orthopedics:Weight-bearing extremity imaging and intraoperative fracture verification demand high-resolution detectors with specialized positioning apparatus. Joint replacement centers in Florida require seamless OR-to-recovery workflow integration.
- Dentistry:Intraoral and panoramic systems utilize smaller-format sensors with reduced radiation output for pediatric compliance.
- Cardiology:Angiography suites require rapid frame-rate acquisition for dynamic cardiac visualization.
- Oncology:Radiation therapy planning demands geometric accuracy and tissue density calibration precision.
Orthopedics holds the largest share; oncology presents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMS reimbursement incentives and state-level capital regulations are redistributing demand across United States sub-regions. Hospital networks in states with flexible certificate-of-need frameworks are accelerating flat-panel detector replacement ahead of federal quality deadlines.
California
Academic medical centers in Los Angeles and San Francisco are piloting direct-conversion amorphous selenium panels for high-resolution extremity imaging. FDA 510(k) clearance pathways shape procurement timelines for these institutions evaluating AI-enhanced diagnostic algorithms. The state's integrated delivery networks negotiate enterprise-wide service agreements bundling equipment upgrades with predictive maintenance contracts.
Texas
Medicare-funded hospital-at-home programs in Houston and Dallas are driving portable digital radiography procurement for point-of-care residential diagnostics. CMS value-based reimbursement shifts support outpatient clinic expansion of digital systems in Austin and San Antonio metropolitan clusters. Rural outreach networks in West Texas present demand for mobile units serving federally qualified health centers.
Florida
Joint replacement centers in Miami and Tampa are adopting hybrid fixed-portable configurations for intraoperative orthopedic flexibility. The state's certificate-of-need regulations remain less restrictive than Northeast counterparts, enabling faster capital deployment for new fixed-room installations. Radiology groups in Orlando are delaying procurement pending clarity on computer-aided detection reimbursement codes.
New York
Certificate-of-need laws constrain installed-base expansion in New York City and Buffalo metropolitan areas, requiring state approval for new fixed-room capital expenditure. Academic medical centers in Rochester and Syracuse navigate OSHA radiation officer certification challenges for compliance with exposure monitoring mandates. Upstate health systems face interoperability complexity connecting new digital detectors to aging PACS infrastructure.
Illinois
Chicago-area hospital networks accelerate computed radiography replacement as Protecting Access to Medicare Act quality deadlines approach. State-level CON regulations in Springfield and Peoria limit greenfield fixed-system installations, favoring retrofit digital detector conversions. Rural facilities in Southern Illinois retain legacy CR infrastructure despite flat-panel workflow economics due to constrained replacement capital.
United States Digital X-Ray Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across financing, service lock-in, and technology bundling dimensions. The market exhibits consolidated structure among imaging system integrators with captive capital divisions, while detector component suppliers concentrate manufacturing in East Asian supplier bases. Three archetypes dominate: diversified health technology conglomerates with in-house financing arms, specialized radiography equipment manufacturers, and flat-panel detector component specialists. Competitive moves center on multi-year service contract bundling and retrofit system financing for cash-constrained community hospitals.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions defined by capital access and long-term service infrastructure. GE Healthcare exemplifies the captive financing archetype through balance sheet deployment for fixed-system placement. Siemens Healthineers represents premium-tier positioning sustained through direct service contract structures. Carestream Health sits within the retrofit-specialist tier, competing on conversion kit economics for aging analog room upgrades.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| FUJIFILM Holdings Corp |
| Canon Medical Systems Corporation |
| Carestream Health |
| Samsung Electronics Co Ltd |
| Varex Imaging Corporation |
| Shimadzu Corporation |
| Others |
Value Network & Pricing Analysis
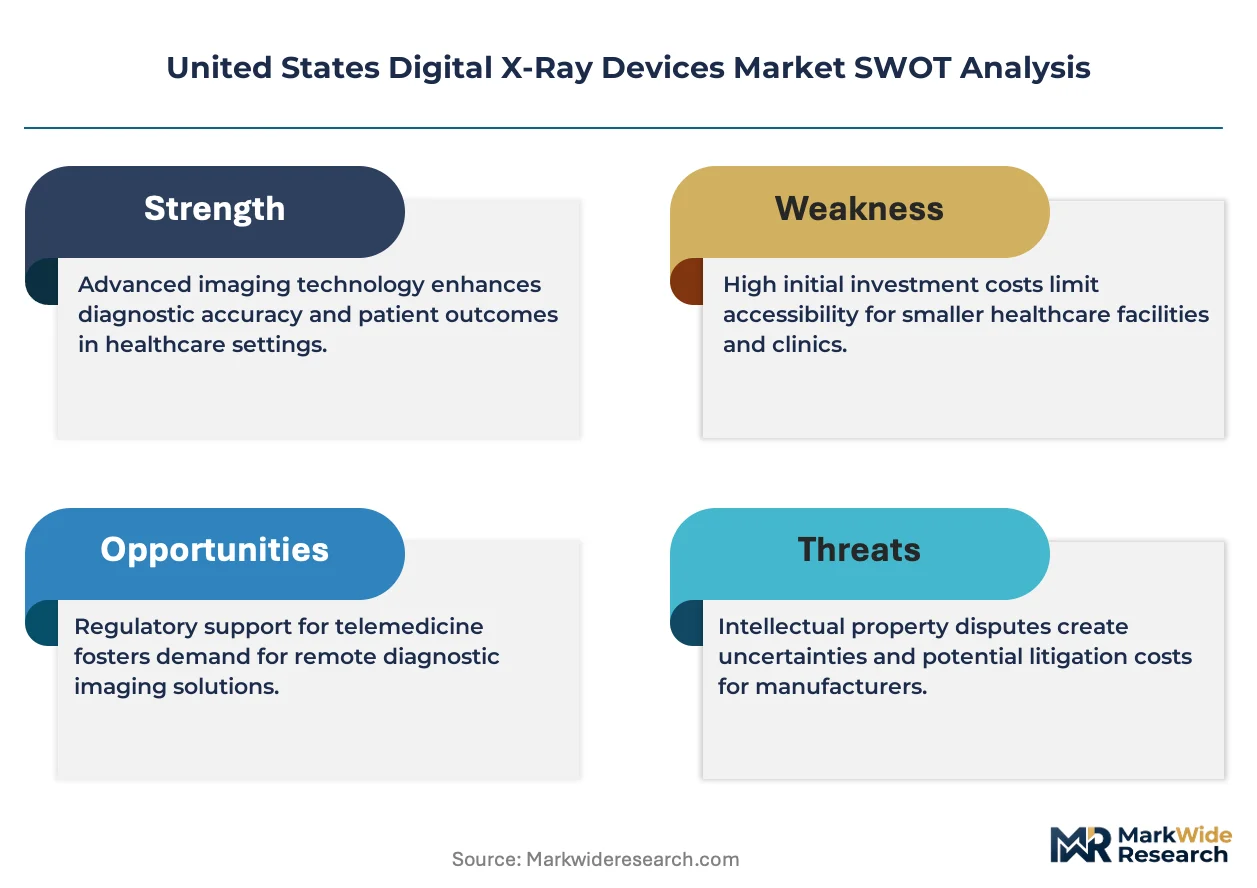
Tariff exposure on East Asian flat-panel detector imports determines both pricing tier spreads and supply chain shape across the United States digital x-ray devices market. Domestic system integrators face margin compression when sourcing cesium iodide scintillator substrates and amorphous silicon backplanes from concentrated East Asian supplier bases, forcing tiered equipment pricing that passes input volatility downstream to hospital procurement committees.
Pricing Analysis
FDA 510(k) clearance tier creates the primary spread between premium and standard system pricing, with Class II diagnostic claims commanding substantial markups over general radiography configurations. Equipment vendors deploy three-tier pricing structure across premium, standard, and economy levels, bundling predictive maintenance contracts at the top tier while stripping service commitments for price-sensitive clinic buyers. Cost compression in economy-tier portable systems is intensifying because OEMs compete for federally qualified health center contracts with limited capital budgets. Clinics in rural Texas and Southern Illinois exhibit highest price sensitivity, whereas California academic medical centers prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentrates among Taiwanese and South Korean foundries producing amorphous silicon thin-film transistor backplanes, with Japanese specialists dominating cesium iodide crystal growth. The supply chain draws from China for rare-earth phosphor processing, South Korea for semiconductor fabrication, and Japan for precision scintillator deposition. Single-source vulnerability concentrates in detector module assembly, where two East Asian facilities supply over half of global flat-panel capacity. Distribution runs through manufacturer-direct sales forces for fixed systems and regional medical equipment distributors for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States digital x-ray devices market represents a service-attach opportunity where predictive maintenance contracts and software subscription layers expand faster than hardware replacement cycles. Recurring revenue from detector calibration services and AI-enabled diagnostic algorithm licenses now commands higher margins than initial equipment placement.
For Market Incumbents: Harden service infrastructure lock-in by converting fixed-system installations into multi-year predictive maintenance agreements before Protecting Access to Medicare Act quality deadlines accelerate replacement decisions. Expand captive financing arms to capture clinic segments vulnerable to emerging retrofit specialists. Vertical integration into detector refurbishment capabilities defends margin against third-party service encroachment. For New Entrants and Emerging Players: Rural outreach networks in West Texas and Southern Illinois present the most penetrable geography, where legacy computed radiography infrastructure delays incumbent replacement cycles and creates white-space for mobile digital radiography units. Federally qualified health centers offer procurement pathways outside enterprise hospital network agreements. A software-first go-to-market angle bundling AI-enhanced diagnostic algorithms with economy-tier hardware bypasses capital-intensive service infrastructure requirements. For Investors and Strategic Acquirers: FDA software-as-medical-device classification reshapes the acquisition landscape by elevating algorithm developers with diagnostic claims above pure hardware manufacturers. Long-term viability centers on platforms combining detector hardware with recurring software revenue across the projection horizon. Acquisition targets should demonstrate installed base scale in underserved geographies paired with service contract penetration above industry norms. The signal to watch is CMS reimbursement code finalization for computer-aided detection, which will trigger accelerated procurement and valuation step-ups for algorithm-enabled systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Clearance for computer-aided detection algorithms unlocks premium pricing in Florida radiology groups. |
| Hospital System Partnership | Enterprise agreements with Texas integrated delivery networks secure multi-year detector replacement cycles. |
| Reimbursement Strategy | CMS value-based coding alignment accelerates outpatient clinic adoption ahead of quality deadlines. |
| Software Companion Development | AI-enabled diagnostic tools bundled with hardware defend margin against retrofit competitors. |
| CE Marking Pathway | Dual regulatory clearance expands addressable market for portable systems in research institutions. |
Research Methodology
Desk research of FDA 510(k) clearance databases, CMS reimbursement code filings, and hospital procurement contract records preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads. Primary fieldwork validated secondary findings across Texas, Florida, California, New York, and Illinois hospital networks. Bottom-up equipment shipment analysis triangulated against top-down healthcare capital expenditure surveys.
Forecast assumptions held constant the current FDA regulatory pathway structure and CMS reimbursement framework across the analysis window, while varying detector technology substitution rates and state-level certificate-of-need enforcement intensity. The analytical framework modeled product type, end user category, technology architecture, and application area dimensions. CAGRs derived from logistic diffusion curves fitted to historical replacement cycle data, with inputs including Protecting Access to Medicare Act compliance deadlines and Medicare hospital-at-home program expansion trajectories.
Practitioners should monitor FDA software-as-medical-device classification precedents and CMS computer-aided detection reimbursement determinations for early signals of demand inflection. Forecasts reflect assumptions about continued flat-panel detector cost reduction and stable East Asian supply chain access. Quarterly review of hospital capital expenditure announcements and state CON approval dockets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
New Born Eye Imaging Systems Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Echocardiography Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Spectroscopy Intravascular Imaging System Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Australia Mammography Market