
 South America CT Market | 2026-2036
South America CT Market Size, Share, and Industry Trends Forecast 2026-2036
South America CT Market Analytics
Modular CT platform configurations is restructuring buyer choice across South America, as hospitals shift from purchasing standalone scanners toward bundled service contracts that integrate hardware, software, and maintenance into multi-year agreements. Siemens Healthineers leverages its regional service infrastructure to anchor long-term hospital partnerships. GE Healthcare competes through localized technical support networks that reduce equipment downtime. Koninklijke Philips NV differentiates via low-dose imaging portfolios tailored to radiation-conscious Latin American clinicians.
Computed tomography systems generate cross-sectional anatomical images using rotating X-ray tubes and detector arrays, with slice counts ranging from 16-slice units for general diagnostics to 640-slice systems for cardiac perfusion imaging; these systems serve stroke assessment, trauma evaluation, and interventional planning across acute care settings. Multislice CT dominates installed base volumes due to its throughput advantages in high-patient-load public hospitals, while portable CT represents the fastest-expanding technology segment as Brazilian emergency departments deploy mobile units for bedside neuroimaging. Diagnostic centers concentrate margin pools through volume-based scanning contracts with private insurers.
ANVISA governs medical device registration and post-market surveillance in Brazil, requiring clinical evidence submissions that extend approval timelines for novel CT technologies. Argentina's national pharmaceutical regulator and Colombia's INVIMA enforce comparable safety standards, creating a fragmented compliance landscape for vendors operating across Mercosur and Andean Community markets. Stakeholders must monitor convergence between national procurement frameworks and sub-regional harmonization initiatives to anticipate tender participation rules and localization requirements.
Market Dynamics
Modular CT platform configurations are restructuring buyer choice across South America, as hospitals shift from purchasing standalone scanners toward bundled service contracts that integrate hardware, software, and maintenance into multi-year agreements. This structural shift concentrates purchasing power within large hospital networks and rewards vendors with established regional service infrastructure.
Growth Catalysts
- ANVISA Streamlined Pathways:Brazil's medical device regulator has compressed approval timelines for advanced imaging equipment, accelerating market entry for next-generation CT systems.
- Oncology Diagnostics Concentration:Hospital networks in São Paulo and Rio de Janeiro are expanding CT procurement specifically for cancer staging and treatment monitoring protocols.
- Emergency Department Modernization:Brazilian public hospitals are deploying mobile CT units for bedside neuroimaging, creating demand for portable systems with rapid deployment capabilities.
Market Restraints
- Import Dependency:Domestic manufacturing capacity for CT detector arrays and X-ray tubes remains negligible across South America, exposing buyers to currency fluctuation risk and extended lead times.
- ANVISA Clinical Evidence Requirements:Novel CT technologies face extended approval timelines due to mandatory clinical submissions, delaying revenue recognition for vendors introducing iterative hardware improvements.
- Public Hospital Budget Cycles:Procurement in Brazil's Unified Health System operates on rigid fiscal calendars, creating demand lumpiness that complicates production planning for equipment manufacturers.
Strategic Opportunities
- Colombia Diagnostic Center Expansion:Private imaging chains in Bogotá and Medellín are consolidating through acquisition, creating volume-based contracting opportunities for CT vendors with flexible financing structures.
- Radiation Dose Optimization:Low-dose imaging protocols are gaining preference among Argentine clinicians, rewarding vendors with iterative reconstruction algorithms and automated exposure control systems.
- Telemedicine Integration:Cloud-based image sharing platforms are enabling remote interpretation partnerships between urban tertiary centers and rural hospitals across the Andean corridor.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Qualified CT service technicians are concentrated in São Paulo and Buenos Aires, leaving secondary cities dependent on vendor dispatch networks with 48-72 hour response windows.
- Legacy System Interoperability:Hospital networks operating mixed-vendor CT fleets face PACS integration complexity when consolidating imaging archives across departmental silos.
- Extended Certification Timelines:Argentina's national pharmaceutical regulator enforces device-specific technical documentation requirements that delay parallel market entry strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America CT Market |
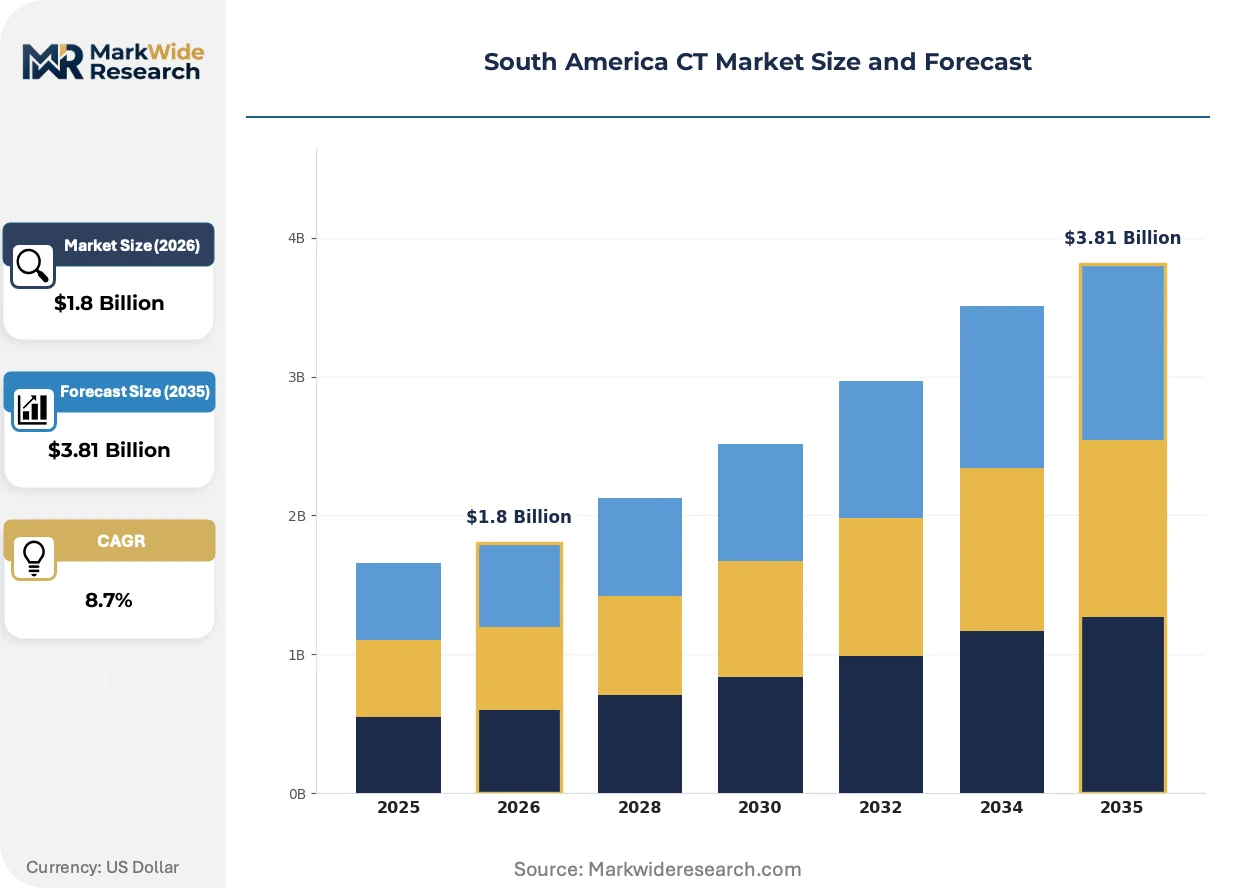
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Cone Beam, Multislice, Integrated Systems End User: Hospitals, Diagnostic Centers, Imaging Clinics, Research Facilities Technology: High-Resolution, Low-Dose, Hybrid, Portable Service Type: Maintenance, Technical Support, Installation, Upgrades |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Hitachi Healthcare Systems, Fujifilm Holdings Corporation, NeuroLogica Corporation, Neusoft Medical Systems Co. Ltd, Mindray Medical International Limited, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America CT Market Evolving Landscape
Photon-counting detector technology is penetrating South American hospital procurement specifications, while regulatory harmonization initiatives across Mercosur attempt to reduce compliance fragmentation. These forces are compressing vendor margins and accelerating service contract bundling.
Artificial intelligence-enabled image reconstruction is absorbing computational workloads previously handled by iterative algorithms, reducing scan times and radiation exposure. Brazilian oncology centers are adopting these systems fastest, prioritizing throughput gains in high-volume screening programs. The technology is absorbing margin pressure from hardware commoditization by creating software-based differentiation.
ANVISA's post-market surveillance requirements now mandate adverse event reporting for CT systems, extending vendor liability exposure beyond the initial sale. Equipment distributors must maintain traceability records across secondary markets. Argentine and Colombian regulators are observing Brazil's enforcement patterns, signaling potential regulatory convergence.
Service unbundling is emerging as procurement officers separate equipment acquisition from maintenance obligations, comparing multi-vendor service quotes against captive vendor programs. Private diagnostic chains in Colombia pioneered this approach, and Brazilian hospital networks are replicating the model. The shift is most visible in São Paulo's competitive private insurance market, where capital efficiency metrics dominate equipment committee decisions.
South America CT Market Segmentation
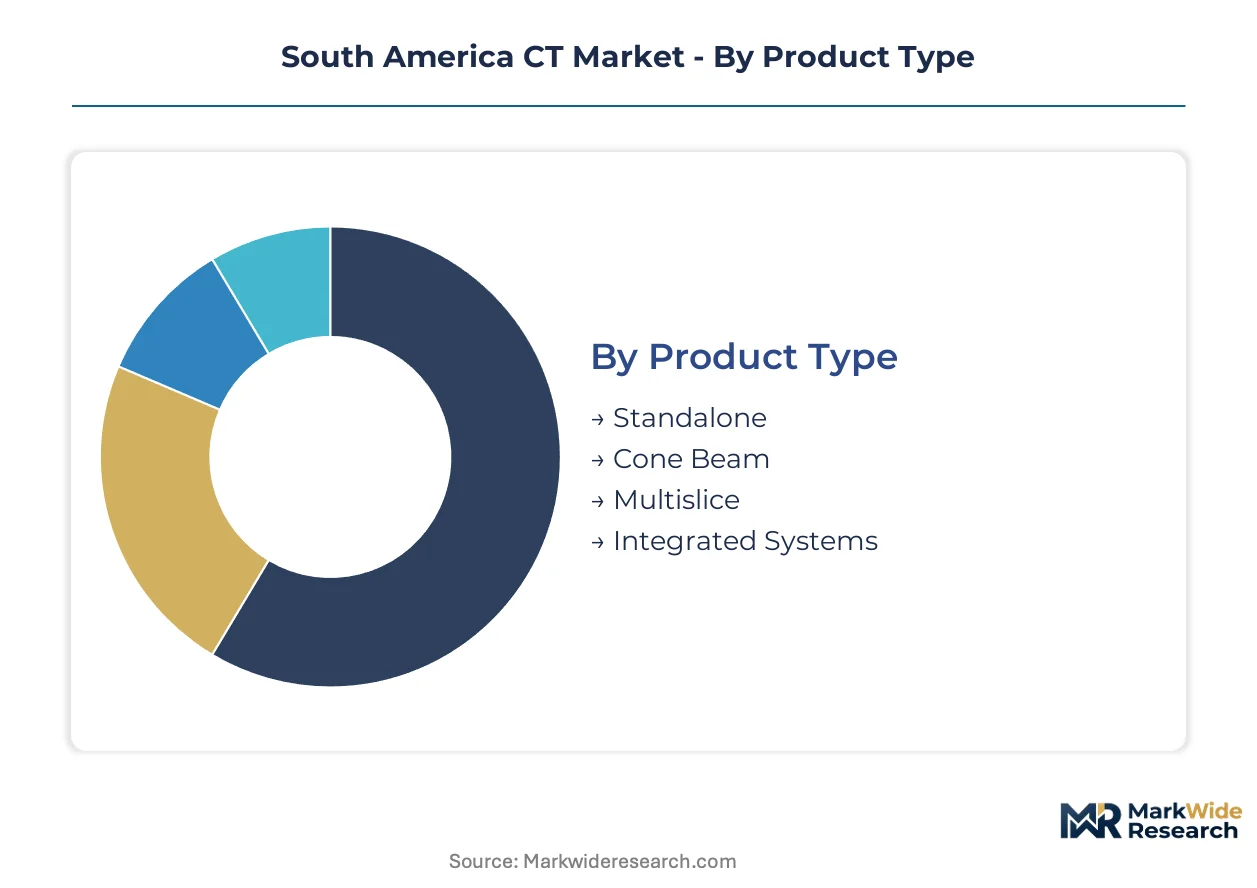
CT procurement patterns across South America diverge sharply between high-volume public hospital networks and specialized private diagnostic chains. Understanding these segment boundaries reveals where vendors can anchor service contracts versus where hardware margins dominate purchasing decisions.
Product Type:
The customization-vs-standardization spectrum runs from configurable modular platforms to fixed-configuration units, with Brazilian hospital networks increasingly demanding flexible upgrade paths.
- Multislice:Rotating X-ray tube systems with 16 to 640 detector rows enable rapid volumetric acquisition for cardiac and trauma protocols. São Paulo's tertiary oncology centers are standardizing on 256-slice configurations for perfusion imaging, driven by throughput requirements in Brazil's Unified Health System screening programs.
- Standalone:Fixed-configuration CT scanners with dedicated hardware-software pairings serve general diagnostic workloads without upgrade pathways. Argentine provincial hospitals favor these units for budget predictability, though they face earlier obsolescence as reconstruction algorithms advance.
- Cone Beam:Flat-panel detector systems optimized for maxillofacial and dental applications with limited soft-tissue contrast.
- Integrated Systems:CT-PET and CT-angiography hybrids combining anatomical and functional imaging in single gantries.
Leading the category by volume: Multislice. Expanding most quickly: Integrated Systems.
End User:
Customer concentration varies from capital-rich hospital networks to fragmented imaging clinics, reshaping vendor sales cycle economics across the region.
- Hospitals:Acute care institutions with emergency departments, surgical suites, and inpatient wards requiring 24/7 imaging availability. Rio de Janeiro's public hospital clusters are consolidating CT procurement through centralized tenders, compressing vendor margins while extending contract durations to seven-year service agreements.
- Diagnostic Centers:Dedicated imaging facilities processing high scan volumes for private insurers and out-of-pocket patients. Colombia's Bogotá-based chains are acquiring regional competitors, creating consolidated purchasing power that demands outcome-based performance guarantees from equipment suppliers.
- Imaging Clinics:Smaller outpatient facilities with single-unit installations and limited technical staffing.
- Research Facilities:University hospitals and clinical trial sites requiring specialized reconstruction protocols and data export capabilities.
Hospitals command the largest installed base. Diagnostic centers are gaining share fastest.
Technology:
Technical differentiation clusters around radiation exposure management and deployment flexibility, with Argentine clinicians particularly sensitive to dose optimization.
- Low-Dose:Iterative reconstruction algorithms and automated exposure modulation reducing radiation per scan while maintaining diagnostic confidence. Argentine oncology networks are mandating these protocols for pediatric and screening populations, creating specification advantages for vendors with mature dose-tracking software.
- Portable:Mobile CT units with self-contained power and climate systems deployable to bedside or emergency field settings. Brazilian emergency departments in Belo Horizonte and Salvador are acquiring these for stroke protocol compliance, bypassing radiology department bottlenecks.
- High-Resolution:Sub-millimeter isotropic voxel acquisition for orthopedic and inner ear applications.
- Hybrid:Dual-energy spectral imaging enabling material decomposition for gout and kidney stone characterization.
Low-Dose installations dominate new procurement. Portable units are climbing the fastest.
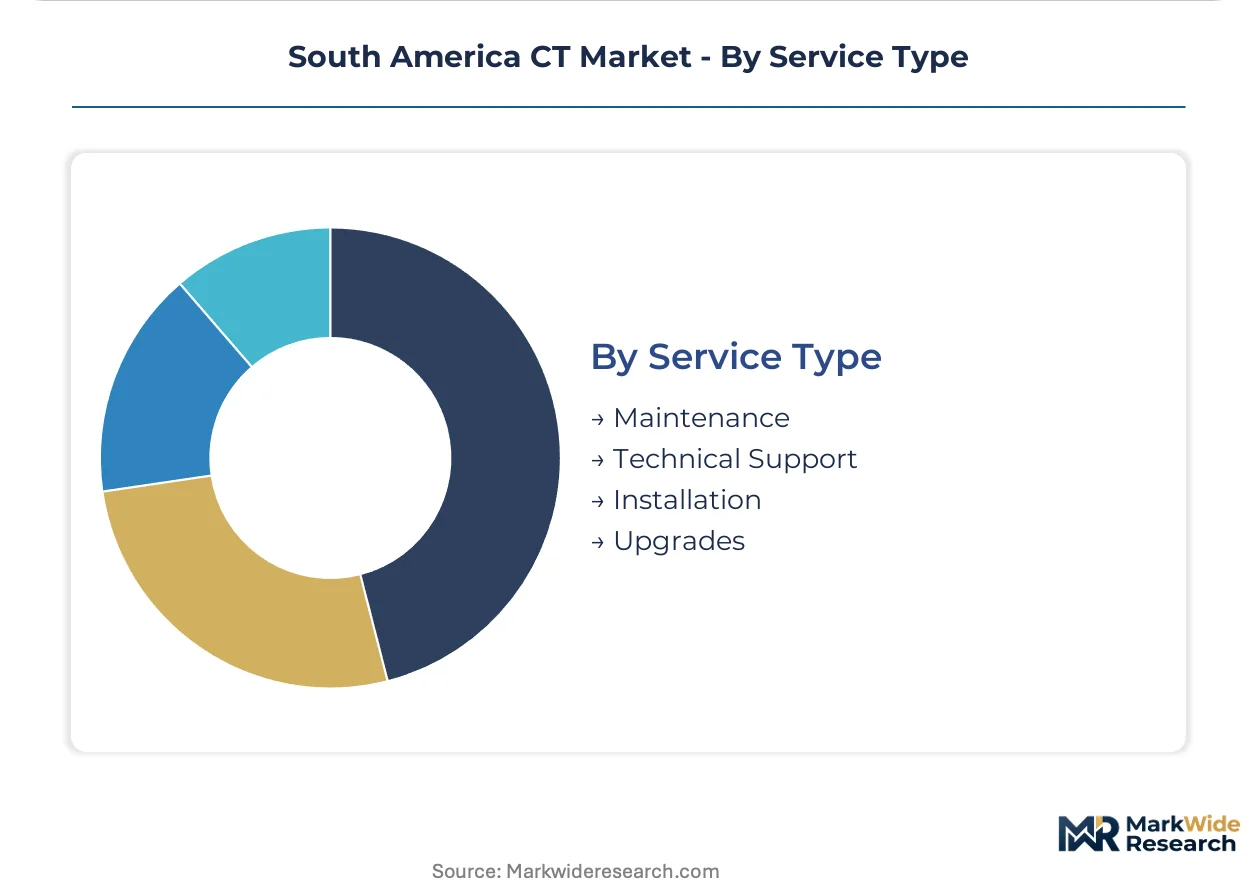
Service Type:
Margin capture is shifting from initial hardware sales toward recurring service revenue, with Colombian diagnostic chains pioneering unbundled maintenance sourcing.
- Maintenance:Preventive and corrective service contracts covering tube replacements, detector calibration, and software updates. Large Brazilian hospital networks are negotiating enterprise-wide maintenance agreements spanning mixed-vendor fleets, forcing independent service organizations to certify across GE, Siemens, and Philips platforms.
- Technical Support:Remote monitoring, application training, and clinical workflow optimization delivered by field engineers. The scarcity of qualified CT service technicians in secondary cities like Curitiba and Porto Alegre is extending response windows, creating premium pricing for guaranteed four-hour arrival contracts.
- Installation:Site preparation, gantry positioning, and regulatory commissioning for new system deployments.
- Upgrades:Hardware retrofits and software version installations extending system functional life.
Maintenance generates the largest service revenue pool. Technical support contracts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil consumes the majority of CT equipment imports across South America while domestic manufacturing capacity remains negligible throughout the region. Argentina and Colombia function as secondary demand centers with distinct procurement frameworks. Chile and Peru represent emerging corridors where private diagnostic investment is accelerating.
Brazil
Oncology screening programs and emergency department modernization drive CT procurement across São Paulo and Rio de Janeiro hospital clusters. ANVISA has compressed approval timelines for advanced imaging equipment, though clinical evidence requirements still delay novel technology introductions. Belo Horizonte and Salvador emergency departments are deploying portable CT units for bedside neuroimaging to bypass radiology bottlenecks.
Argentina
Radiation dose sensitivity among clinicians is elevating demand for low-dose imaging protocols in pediatric and screening populations. The country's national pharmaceutical regulator enforces device-specific technical documentation that extends certification timelines beyond Brazilian benchmarks. Buenos Aires anchors the installed base while provincial hospitals favor fixed-configuration units for budget predictability.
Colombia
Private imaging chains in Bogotá and Medellín are consolidating through acquisition, creating volume-based contracting opportunities. INVIMA maintains comparable safety standards to ANVISA, though enforcement patterns remain less developed. Diagnostic center expansion in secondary cities is outpacing public hospital procurement.
Chile
Private insurance penetration is driving demand for premium CT configurations in Santiago's tertiary centers. The country's medical device regulatory framework aligns with Mercosur harmonization initiatives, streamlining import pathways for established vendors. Northern mining corridor hospitals are investing in trauma-capable imaging for occupational health programs.
Peru
Lima's private diagnostic sector is expanding CT capacity to capture medical tourism flows from neighboring Andean countries. The national health technology regulator is observing Brazilian enforcement patterns for post-market surveillance. Provincial hospital networks remain dependent on public procurement cycles with extended tender timelines.
South America CT Market Competitive Landscape
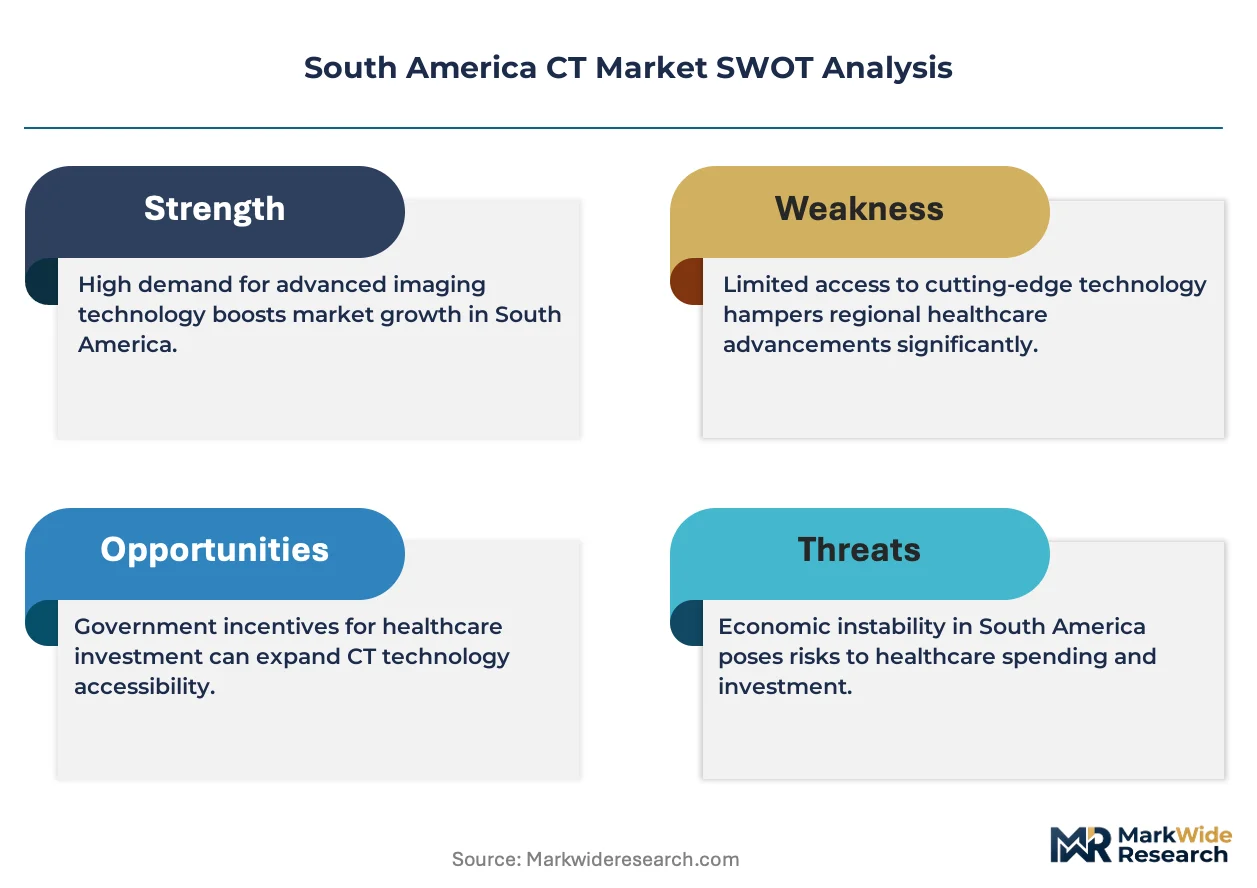
Diversified conglomerates compete with focused pure-play specialists across South America's CT market, creating a tiered structure where service infrastructure often outweighs hardware differentiation. Siemens Healthineers leverages its regional service footprint to anchor long-term hospital partnerships, while GE Healthcare competes through localized technical support networks that reduce equipment downtime. Koninklijke Philips NV occupies a distinct position via low-dose imaging portfolios. The dominant competitive moves involve bundling multi-year service contracts with hardware procurement and unbundling maintenance obligations to capture independent service organization opportunities.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers exemplify archetypes that compete through established regional service infrastructure and long-term hospital network relationships. Koninklijke Philips NV represents a positioning focused on radiation-conscious clinical protocols. These three companies anchor the competitive landscape, with Canon Medical Systems Corporation and Hitachi Healthcare Systems occupying secondary positions that challenge primarily on price-performance metrics in specific segments.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Hitachi Healthcare Systems |
| Fujifilm Holdings Corporation |
| NeuroLogica Corporation |
| Neusoft Medical Systems Co. Ltd |
| Mindray Medical International Limited |
| Others |
Value Network & Pricing Analysis
Captive service infrastructure integration by Siemens Healthineers and GE Healthcare anchors pricing power across South America's CT market, as vendors bundle multi-year maintenance contracts with hardware procurement to lock in recurring revenue streams and defend against independent service organization competition.
Pricing Analysis
Margin tightening in mid-tier configurations reflects currency volatility exposure and extended ANVISA approval timelines that compress vendor cash conversion cycles. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes, with São Paulo hospital networks least price-sensitive due to consolidated purchasing power while Argentine provincial hospitals prioritize budget predictability over upgrade pathways. Cost-down pressure on standalone fixed-configuration units accelerates because Colombian diagnostic chains pioneered service unbundling, forcing captive vendors to compete on discrete maintenance quotes.
Supply Chain Analysis
X-ray tube and detector array supply rests on German, Japanese, and US specialty manufacturers, with negligible domestic production capacity across Brazil, Argentina, or Colombia. Raw material dependencies include high-purity tungsten for filament assemblies, rare-earth ceramic scintillators for detector substrates, and liquid metal bearings for rotating gantry components. Single-source vulnerability concentrates in photon-counting detector substrates, where two global suppliers feed the entire South American installed base. Distribution runs through authorized dealer networks with regional technical certification requirements that extend lead times for secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified CT service technician scarcity props vendor pricing power, as 48-72 hour response windows in Curitiba and Porto Alegre create premium opportunities for guaranteed four-hour arrival contracts.
For Market Incumbents: Extend enterprise-wide maintenance agreements spanning mixed-vendor fleets to capture independent service organization revenue, while deepening backward integration into detector calibration and tube replacement logistics to reduce third-party dependency. ANVISA's post-market surveillance mandate extends liability exposure, creating defensive moats through traceability infrastructure that emerging competitors lack capital to replicate. For New Entrants and Emerging Players: ANVISA's streamlined approval pathways in Brazil open a window for portable CT specialists to penetrate Belo Horizonte and Salvador emergency departments bypassing established radiology department procurement committees. Colombia's diagnostic center consolidation in Bogotá and Medellín presents the most penetrable entry point, with flexible financing structures and outcome-based performance guarantees as the critical go-to-market angle against incumbent bundled offerings. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified health technology conglomerates seeking regional service density, with mid-scale independent service organizations commanding premiums for multi-vendor certification capabilities. Long-term viability hinges on software differentiation through AI-enabled reconstruction algorithms that offset hardware commoditization. The signal to watch is ANVISA harmonization with Mercosur regulatory standards, which would compress compliance costs and accelerate cross-border scaling for platform players.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Siemens Healthineers leverages regional service infrastructure to anchor seven-year agreements with Rio de Janeiro public hospital clusters. |
| Software Companion Development | AI-enabled image reconstruction reduces scan times and radiation exposure, creating differentiation beyond hardware specifications for Brazilian oncology centers. |
| Reimbursement Strategy | Outcome-based performance guarantees align equipment procurement with private insurer volume-based scanning contracts in Colombia's consolidating diagnostic chains. |
| CE Marking Pathway | European certification accelerates parallel ANVISA submissions for novel photon-counting detector technologies entering Mercosur markets. |
| Backward Integration | In-house production of detector calibration capabilities reduces dependency on scarce qualified technicians in secondary Brazilian cities. |
Research Methodology
Multi-period observation of ANVISA approval timelines, hospital procurement tender patterns, and service contract renewal rates anchored the trend analysis, supplemented by interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and aftermarket service heads. Secondary validation drew from ANVISA registration databases, hospital procurement disclosures, GPO contract repositories, and customs import records for imaging equipment. Bottom-up installed base modeling triangulated against top-down market sizing from equipment manufacturer regional revenue disclosures.
Segment-weighting across product type, end user, technology, and service type dimensions structured the analytical framework, with cross-segment interaction effects modeled throughout the projection horizon. CAGRs derived from logistic adoption curves for portable CT and linear replacement cycles for multislice installed base units. Forecast inputs included ANVISA regulatory harmonization progress, currency volatility bands for Brazilian real and Argentine peso, and technician training pipeline capacity at São Paulo and Buenos Aires technical institutes.
The model assumes a particular technology adoption path; alternative pathways for photon-counting detector commercialization would alter the outlook if supply constraints persist beyond the modeling period. Forecasts reflect assumptions regarding ANVISA enforcement consistency, public hospital budget cycle regularity, and Mercosur regulatory convergence momentum. A small set of named triggers warrants ongoing watch: ANVISA adverse event reporting enforcement patterns, Colombian diagnostic chain consolidation velocity, and Argentine radiation dose protocol mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
Digital X Ray Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Echocardiography Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Global Technetium-99M Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Non-Invasive Coronary Imaging Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Portable Ultrasound Bladder Scanner Market
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Global Spinal Imaging Treatment Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Digital Pathology Market