
 Wireless Intraoral Camera Market | 2026-2036
Wireless Intraoral Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Intraoral Camera Market Analytics
The capital-intensity gap between full-platform manufacturers and component assemblers is collapsing as CMOS sensor costs fall and wireless module commoditization accelerates. Dentsply Sirona leverages integrated software-to-hardware ecosystems to sustain premium positioning across dental workflows. Carestream Dental anchors its competitive stance through imaging informatics that extend beyond hardware sales. Flight Dental Systems specializes in value-engineered wireless platforms for mid-market practices.
A wireless intraoral camera captures high-resolution digital images of oral structures via radio-frequency or Wi-Fi transmission to display systems, typically employing CMOS or CCD sensors with LED illumination and operating at focal distances of 1–10 mm for caries detection and periodontal assessment. The handheld cameras segment dominates volume shipments due to ergonomic demands in crowded operatories, while teledentistry applications are expanding fastest as asynchronous consultation models gain reimbursement traction. CMOS technology leads sensor adoption for its low-power wireless compatibility, though CCD persists in practices prioritizing color fidelity for shade matching.
FDA 510(k) premarket notification governs wireless medical device clearance in the United States, while the EU Medical Device Regulation imposes post-market surveillance and clinical evidence requirements for intraoral imaging systems sold in Europe. ISO 10993 biocompatibility standards and IEC 60601-1 electrical safety protocols further constrain design choices and supplier qualification. Stakeholders must monitor evolving teledentistry reimbursement codes and cybersecurity guidance for connected diagnostic devices as regulatory scope broadens beyond traditional hardware safety.
Market Dynamics
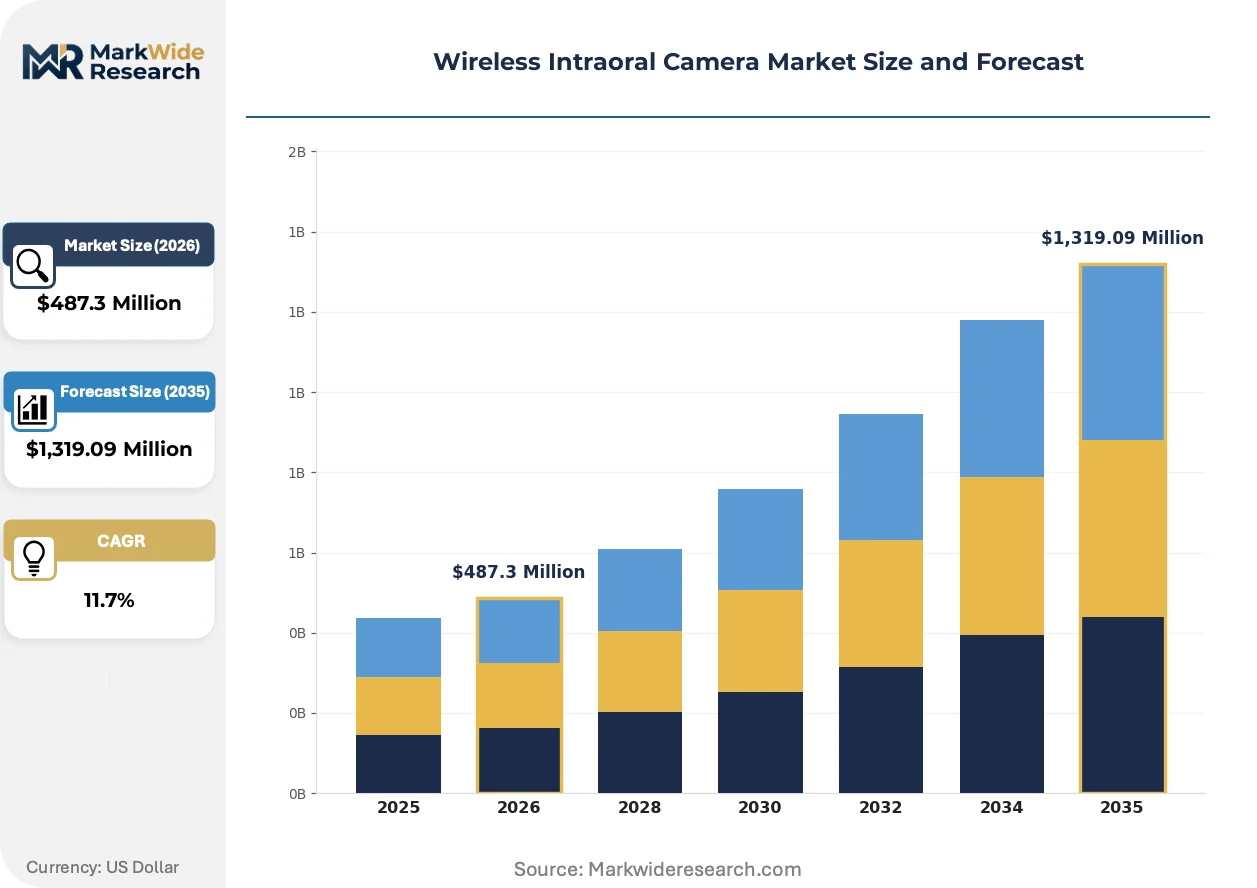
CMOS sensor commoditization and wireless module standardization are collapsing the historical capital barrier between integrated manufacturers and component assemblers, redistributing margin capture across the dental imaging value chain.
Growth Catalysts
- FDA 510(k) pathway efficiency:Streamlined premarket notification for wireless medical devices accelerates product commercialization timelines for US market entrants.
- Teledentistry reimbursement codes:Expanding coverage for asynchronous dental consultations in the United States, Germany, and Japan drives hardware procurement for remote diagnostic capabilities.
- CMOS-LED convergence:Low-power sensor-illumination integration enables single-handpiece wireless designs that reduce operatory clutter.
Market Restraints
- EU MDR clinical evidence requirements:Post-market surveillance mandates for intraoral imaging systems impose documentation burdens that extend regulatory timelines.
- CMOS sensor supply concentration:Dependence on East Asian semiconductor foundries creates vulnerability to geopolitical trade friction.
- CCD persistence in shade-matching workflows:Color fidelity limitations of CMOS technology sustain niche demand for legacy sensor architectures.
Strategic Opportunities
- Mid-market practice digitization:Value-engineered wireless platforms address cost-sensitive dental clinics in secondary US metropolitan areas.
- AI-assisted caries detection integration:Convergence of edge-computing image processing with wireless transmission enables real-time diagnostic support.
- Indian dental infrastructure investment:Government and private sector expansion of chairside digital systems creates demand for wireless imaging hardware.
Industry Challenges
- IEC 60601-1 electrical safety certification:Wireless power transmission compliance testing extends product development cycles.
- Legacy PACS integration complexity:Interoperability gaps between proprietary wireless protocols and established dental imaging archives require custom middleware development.
- Cybersecurity hardening for HIPAA-covered entities:Connected diagnostic devices face escalating security audit requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Intraoral Camera Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Cameras, Fixed Cameras, Wireless Cameras, Digital Cameras End User: Dental Clinics, Hospitals, Research Laboratories, Orthodontic Practices Technology: LED, CCD, CMOS, Infrared Application: Diagnostic Imaging, Patient Education, Treatment Planning, Teledentistry |
| Companies Covered | Acteon Group, Digital Doc, Dentsply Sirona, Flight Dental Systems, Gendex, Carestream Dental, Planmeca Oy, Owandy Radiology, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Intraoral Camera Market Evolving Landscape
Wireless intraoral imaging is undergoing architectural transformation as modular component ecosystems replace vertically integrated hardware stacks, compressing development cycles and democratizing market entry.
CMOS sensor technology is decomposing the traditional camera manufacturing stack by separating image capture, processing, and transmission into interoperable subsystems. Mid-market dental practices in the United States and Germany are adopting these modular platforms at accelerating pace. This decomposition is enabling component assemblers to compete with established full-platform manufacturers on feature parity.
The EU Medical Device Regulation is tightening post-market surveillance obligations for wireless intraoral cameras sold in Europe, requiring systematic clinical evidence collection. Manufacturers must now maintain vigilance systems that track device performance across distributed installations. Dental imaging specialists with European commercial presence are restructuring quality management systems to accommodate MDR Article 83 periodic safety update report requirements.
Subscription-based equipment procurement is displacing capital purchase models among multi-location dental service organizations in the United States. These buyers now prioritize per-procedure cost structures that bundle hardware, software, and maintenance. The shift is most visible in dental support organization networks across Texas, Florida, and California.
Wireless Intraoral Camera Market Segmentation
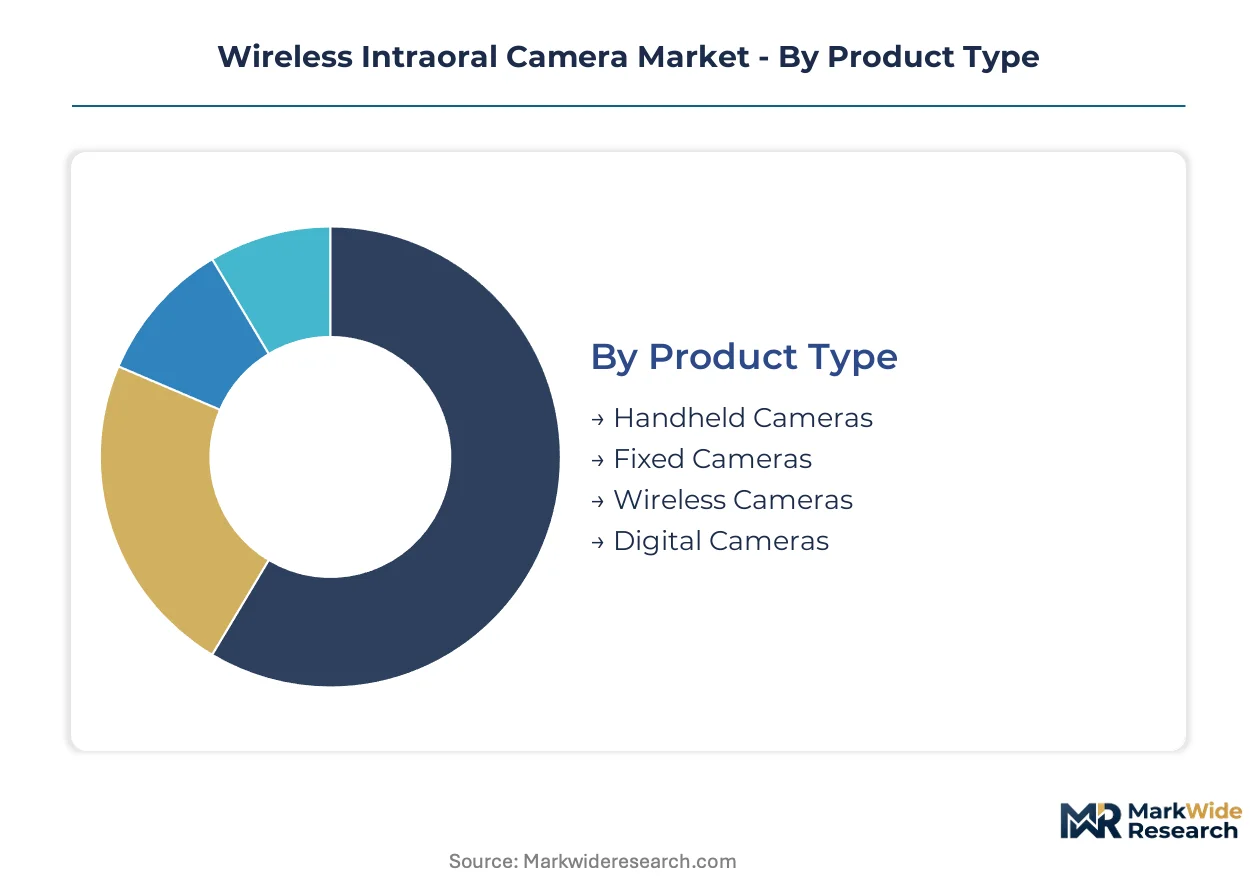
Wireless intraoral camera segmentation reveals how technology substitution and workflow integration reshape procurement priorities across dental settings. Each dimension captures distinct trade-offs between image quality, operatory flexibility, and total cost of ownership that manufacturers must navigate.
Product Type:
Handheld configurations face intensifying substitution pressure from fully wireless designs that eliminate cable maintenance and sterilization burdens.
- Handheld Cameras:Ergonomic pistol-grip housings with integrated capture buttons dominate crowded operatories where maneuverability constrains equipment selection. Demand concentrates in high-volume United States dental clinics where chairside efficiency drives procurement, though sterilization protocols add lifecycle cost.
- Wireless Cameras:Radio-frequency or Wi-Fi transmission modules eliminate tethering constraints and enable flexible operatory layouts. Teledentistry workflows in Germany and Japan are accelerating adoption as asynchronous consultation models gain reimbursement traction.
- Fixed Cameras:Ceiling-mounted or wall-integrated systems serve specialized procedural suites requiring hands-free operation during complex restorations.
- Digital Cameras:USB-tethered imaging devices persist in budget-constrained practices prioritizing upfront cost over wireless convenience.
Handheld cameras anchor the volume base while wireless cameras gain share at the steepest rate.
End User:
Procurement authority concentrates with dental clinics, though hospital systems are consolidating purchasing power through integrated delivery networks.
- Dental Clinics:Independent and group practices generate the majority of unit demand, with multi-location service organizations in Texas, Florida, and California driving subscription-based equipment procurement.
- Orthodontic Practices:Specialized alignment and occlusion documentation requirements favor high-resolution CMOS sensors with rapid capture sequences.
- Hospitals:Academic medical centers and oral surgery departments prioritize PACS interoperability and HIPAA-compliant data transmission architectures.
- Research Laboratories:Clinical trial sites and dental schools require calibrated imaging protocols with audit trails for regulatory submission.
Dental clinics dominate installed base while orthodontic practices expand most quickly as clear aligner therapy proliferates.
Technology:
CMOS-LED convergence is displacing legacy CCD architectures across mid-market price tiers.
- CMOS:Complementary metal-oxide-semiconductor sensors enable low-power wireless transmission and single-handpiece integration. CMOS technology leads adoption in cost-sensitive United States metropolitan markets where power efficiency reduces battery weight.
- LED:Solid-state illumination arrays deliver consistent color temperature with minimal heat generation, supporting extended procedural use without tissue desiccation.
- CCD:Charge-coupled device sensors persist in shade-matching workflows where color fidelity determines restoration acceptance, particularly among Japanese ceramic laboratories.
- Infrared:Near-infrared capture enables subsurface caries detection without ionizing radiation, though clinical validation remains incomplete for reimbursement coverage.
CMOS anchors volume production while infrared imaging climbs the fastest on early diagnostic validation.
Application:
Diagnostic imaging faces workflow integration from AI-assisted analysis platforms.
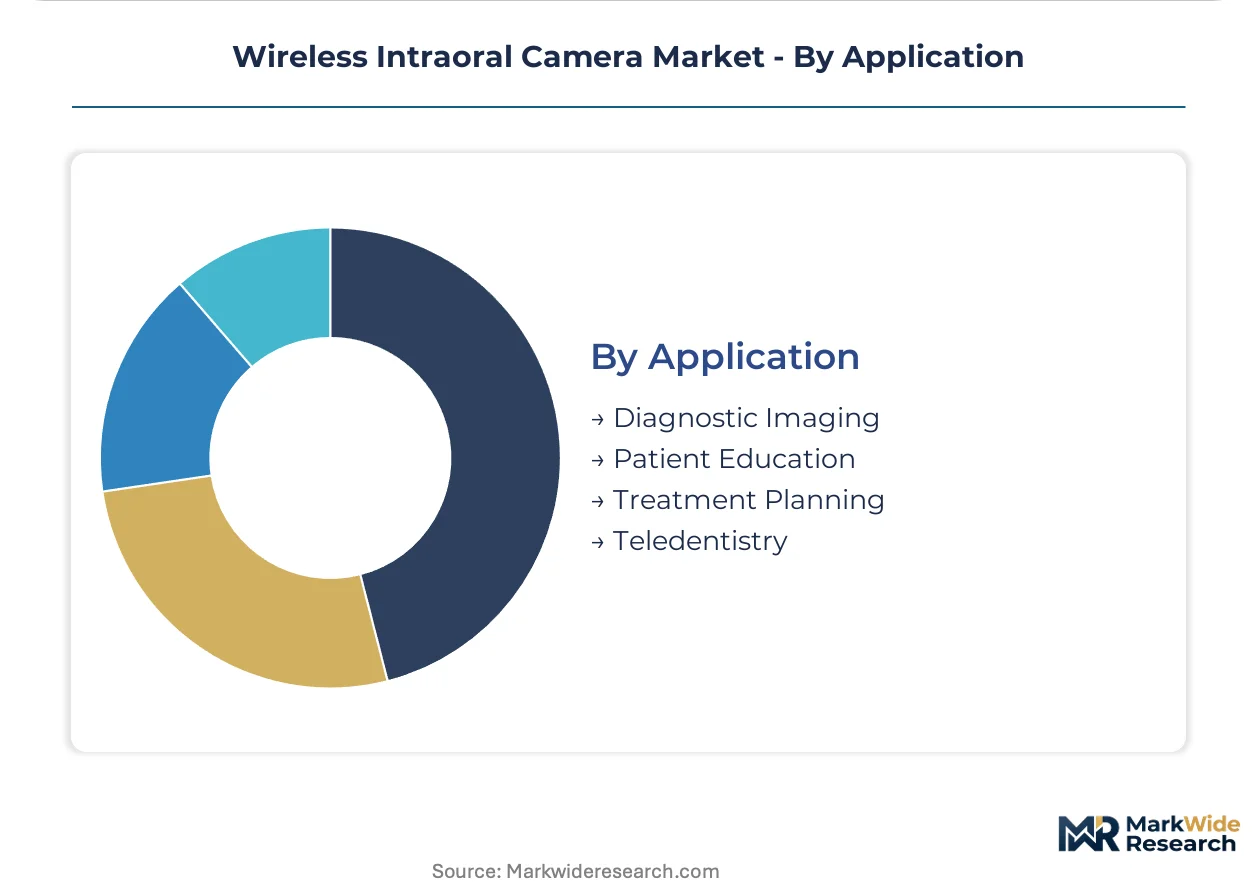
- Diagnostic Imaging:Caries detection and periodontal assessment constitute the core use case, with FDA 510(k) clearance pathways validating algorithm-assisted interpretation.
- Teledentistry:Asynchronous consultation models require secure wireless transmission to cloud platforms, with reimbursement code expansion in Germany and Japan driving hardware procurement.
- Patient Education:Chairside display integration supports treatment acceptance through visual co-diagnosis, particularly in cosmetic dentistry segments.
- Treatment Planning:Digital impression correlation and orthodontic simulation software demand calibrated image capture with dimensional accuracy.
Diagnostic imaging sustains the revenue base while teledentistry applications expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States clinics prioritize subscription-based procurement for multi-location networks, while German practices emphasize MDR-compliant documentation systems, and Japanese ceramic laboratories sustain demand for color-fidelity-optimized hardware.
United States
Dental service organizations across Texas, Florida, and California are consolidating procurement through per-procedure equipment subscriptions. FDA 510(k) premarket notification pathways govern wireless medical device clearance timelines. Greater Boston and Pacific Northwest metropolitan clusters anchor demand for HIPAA-compliant teledentistry infrastructure.
Germany
Mid-market dental practices in Bavaria and North Rhine-Westphalia are accelerating modular wireless platform adoption. EU Medical Device Regulation post-market surveillance mandates impose systematic clinical evidence collection requirements. Stuttgart and Munich industrial corridors concentrate imaging informatics development for chairside diagnostics.
Japan
Ceramic laboratories and aesthetic-focused clinics in Tokyo and Osaka sustain CCD sensor demand for shade-matching workflows. METI digital health initiatives support reimbursement expansion for asynchronous dental consultations. Kanto region dental schools drive calibrated imaging protocol adoption for regulatory submission standards.
India
Government and private sector investment in Maharashtra and Karnataka dental infrastructure creates demand for value-engineered wireless imaging hardware. Central Drugs Standard Control Organization regulates medical device import and quality certification. Hyderabad and Bengaluru technology corridors incubate component assembly capabilities for cost-sensitive markets.
United Kingdom
London and Southeast England dental clinics prioritize PACS interoperability for integrated diagnostic workflows. Care Quality Commission inspection frameworks emphasize equipment documentation and audit trail maintenance. Midlands orthodontic practices drive rapid-capture CMOS sensor procurement for clear aligner therapy documentation.
Wireless Intraoral Camera Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the capital-intensity gap collapsing as CMOS sensor commoditization accelerates. Full-platform manufacturers defend position through software-to-hardware ecosystem integration, while component assemblers exploit modular subsystem interoperability to achieve feature parity. Strategic moves concentrate on imaging informatics extension beyond hardware sales and value-engineered platform development for mid-market penetration.
Among integrated dental technology conglomerates, Dentsply Sirona and Danaher Corporation exemplify the ecosystem-anchored archetype, leveraging captive software distribution to sustain premium positioning across chairside workflows. Carestream Dental occupies a position within the imaging informatics specialist tier, extending competitive stance through data management capabilities that transcend hardware transactions. Flight Dental Systems represents the value-engineered platform segment, targeting cost-sensitive practice digitization with streamlined wireless architectures.
| Leading Market Players |
|---|
| Acteon Group |
| Digital Doc |
| Dentsply Sirona |
| Flight Dental Systems |
| Gendex |
| Carestream Dental |
| Planmeca Oy |
| Owandy Radiology |
| Danaher Corporation |
| Others |
Value Network & Pricing Analysis
FDA 510(k) premarket notification requirements gate both supplier qualification timelines and price differentiation tiers for wireless intraoral cameras entering the United States market. CMOS sensor commoditization and wireless module standardization are compressing margins at the component level while certification investment sustains premium positioning for integrated manufacturers.
Pricing Analysis
Long-term subscription contracts dominate procurement among multi-location dental service organizations in Texas, Florida, and California, displacing capital purchase models. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with integrated imaging informatics from value-engineered alternatives. Cost compression in the mid-market tier is intensifying because component assemblers achieve feature parity through modular subsystem sourcing. Independent dental clinics in secondary United States metropolitan areas exhibit the highest price sensitivity, while academic medical centers prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach and trans-Pacific trade lanes from East Asian semiconductor foundries create working capital pressure for CMOS-dependent manufacturers. Supply concentrates in Taiwan, South Korea, and China for image sensors, with Japan and Germany anchoring precision optical component fabrication. Raw material dependencies span CMOS wafers, LED illumination arrays, and lithium-polymer battery cells. Single-source vulnerability in advanced CMOS fabrication at Taiwanese foundries represents the dominant structural risk. Distribution runs through dental equipment distributors and direct sales forces to dental clinics, with dental service organizations consolidating procurement through national accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as teledentistry reimbursement expansion and modular platform decomposition redistribute procurement authority away from integrated incumbents.
For Market Incumbents: Secure imaging informatics lock-in through PACS interoperability investments that raise switching costs for hospital systems and dental service organizations. CMOS sensor commoditization from East Asian component assemblers threatens premium positioning; backward integration into edge-computing image processing software defends margin capture beyond hardware transactions. For New Entrants and Emerging Players: Lead with value-engineered wireless platforms targeting cost-sensitive dental clinics in Indian metropolitan markets and secondary United States cities where FDA 510(k) pathway efficiency accelerates commercialization timelines. Teledentistry infrastructure procurement in Germany and Japan represents the most penetrable application segment. Direct-to-practice digital marketing bypasses incumbent distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular wireless platform assembly as CMOS sensor and wireless module commoditization collapses historical barriers to entry. Viability across a multi-year horizon hinges on software-to-hardware ecosystem integration capabilities. Acquisition targets with imaging informatics development and European MDR compliance infrastructure warrant priority attention. The signal to watch is teledentistry reimbursement code expansion in additional national markets as inflection indicator for hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Streamlined premarket notification accelerates United States commercialization timelines for wireless medical devices. |
| CE Marking Pathway | EU MDR compliance enables European market access with systematic post-market surveillance documentation. |
| Hospital System Partnership | PACS interoperability agreements with academic medical centers secure high-volume diagnostic imaging procurement. |
| Software Companion Development | AI-assisted caries detection integration differentiates hardware platforms through real-time diagnostic support. |
| Reimbursement Strategy | Teledentistry code expansion in Germany and Japan drives hardware procurement for asynchronous consultation models. |
Research Methodology
Initial hypotheses were tested against primary input from dental equipment procurement managers, biomedical engineers at academic medical centers, GPO contracts managers, and regulatory affairs specialists at imaging manufacturers and refined through secondary validation. Primary interviews combined with FDA 510(k) clearance databases, EU MDR vigilance system records, hospital procurement databases, and dental service organization equipment subscription disclosures. Bottom-up unit shipment modeling and top-down market sizing triangulated across component supplier interviews and end-user demand assessment.
Variance decomposition across product type, technology architecture, end-user setting, and application use case anchored the analytical framework. CAGRs were derived from segmented growth trajectory analysis incorporating CMOS sensor cost decline curves, wireless module adoption rates, and teledentistry reimbursement expansion patterns. Industry-specific forecast inputs included dental clinic digitization investment cycles and dental service organization consolidation velocity.
The analysis sits within stated boundaries; outcomes outside sustained CMOS sensor commoditization, stable FDA 510(k) pathway efficiency, and continued teledentistry reimbursement expansion would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline stability and supply chain continuity from East Asian semiconductor foundries. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
South America MRI Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
Medical X-Ray Films Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
North America MRI (Magnetic Resonance Imaging) Market