
 Structural Heart Imaging Market | 2026-2036
Structural Heart Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Structural Heart Imaging Market Intelligence
3D transesophageal echocardiography resolution standards is unwinding diagnostic confidence in transcatheter edge-to-edge repair planning. GE Healthcare leverages its ultrasound platform breadth to sustain installed-base loyalty across cardiac service lines. Siemens Healthineers anchors its position through advanced visualization software that integrates CT and echocardiography datasets for procedural guidance.
Structural heart imaging encompasses non-invasive and minimally invasive visualization techniques used to characterize cardiac anatomy, quantify valve dysfunction, and guide interventional procedures, typically employing spatial resolutions below one millimeter and real-time frame rates exceeding thirty frames per second. Echocardiography occupies the dominant share of procedural volume due to its bedside availability and established reimbursement, while CT scanners capture the fastest growth trajectory as pre-procedural planning for transcatheter interventions demands high-resolution three-dimensional anatomical maps. Doppler imaging remains a mature, indispensable workhorse for hemodynamic assessment, whereas contrast ultrasound represents an emerging margin pool as microbubble agents expand perfusion imaging indications.
FDA premarket notification pathways and CE marking requirements under the EU Medical Device Regulation shape product development timelines and clinical evidence standards for structural heart imaging systems. The EPA and state-level radiation safety commissions impose dose-reduction mandates on CT-based cardiac protocols, directly influencing detector technology investment priorities. Stakeholders must monitor evolving reimbursement decisions for procedural imaging guidance, as coverage determinations for real-time three-dimensional echocardiography will dictate capital allocation across hospital catheterization laboratories.
Market Dynamics
The structural heart imaging market pivots on catheterization laboratory expansion and reimbursement determination timing. Hospitals in the United States, Germany, and Japan are building dedicated structural heart programs that concentrate capital deployment around real-time three-dimensional echocardiography and CT-based pre-procedural planning capabilities.
Growth Catalysts
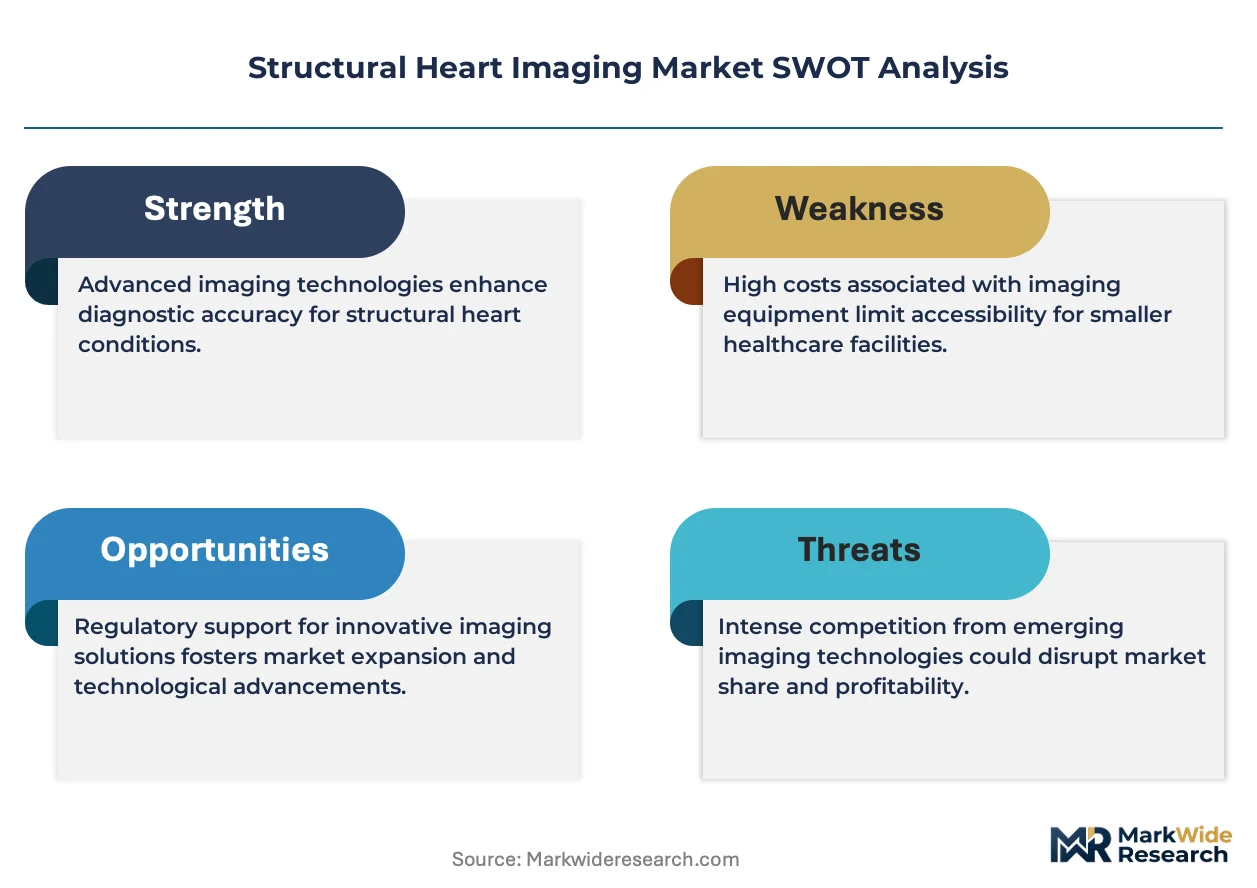
- FDA breakthrough device designations:Accelerated review pathways compress time-to-market for structural heart planning software, incentivizing algorithm developers to pursue predicate device strategies.
- Transcatheter edge-to-edge repair volumes:Procedural growth in mitral valve intervention is pulling demand for high-resolution 3D transesophageal echocardiography systems into catheterization laboratories.
- CE marking under EU MDR:The Medical Device Regulation's clinical evidence requirements are elevating software validation standards, favoring established visualization platforms with robust quality management systems.
Market Restraints
- CT detector technology investment cycles:EPA and state-level radiation safety mandates force dose-reduction hardware refreshes that strain hospital capital budgets.
- Microbubble contrast agent supply concentration:Perfluorocarbon-based microsphere manufacturing concentrates among limited specialty chemical suppliers, creating input vulnerability for perfusion imaging expansion.
- Reimbursement lag for real-time guidance:Coverage determination delays for three-dimensional echocardiography during transcatheter procedures create adoption friction in United States hospital systems.
Strategic Opportunities
- Japan's aging valve disease population:METI-supported medical device innovation clusters in Kobe and Osaka create regulatory-fast-tracked entry points for CT-echocardiography fusion platforms.
- Artificial intelligence segmentation algorithms:Machine learning integration with Doppler hemodynamic assessment is opening automated quantification workflows that reduce operator variability.
- Outpatient catheterization laboratory models:Ambulatory surgical center licensing for select transcatheter procedures is redistributing imaging system placement toward lower-acuity settings.
Industry Challenges
- Echocardiographer-proceduralist coordination:Real-time three-dimensional image interpretation during transcatheter valve deployment demands hybrid skill sets that training pipelines have not yet scaled.
- Legacy PACS integration:DICOM conformance testing for new visualization software against hospital archive systems extends deployment timelines and inflates implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Structural Heart Imaging Market |
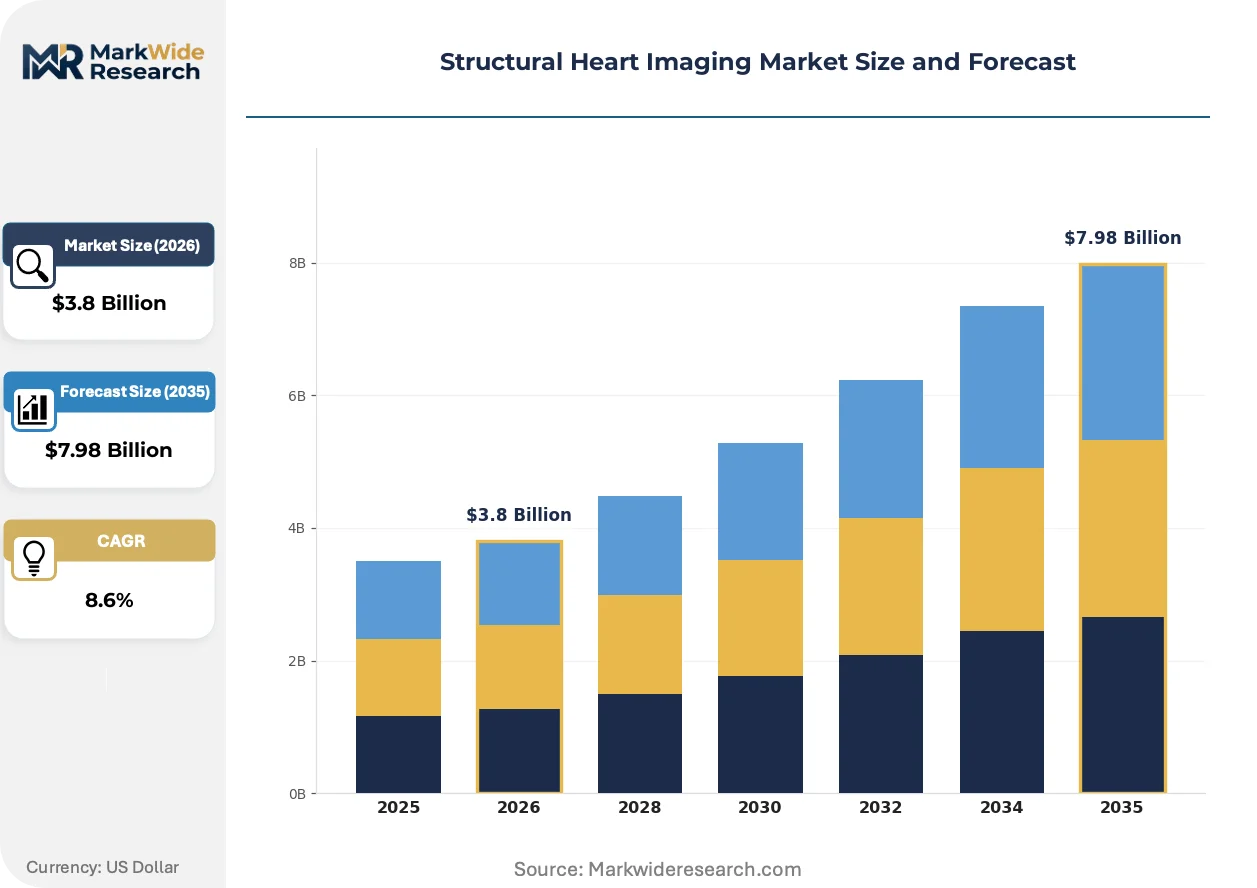
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Echocardiography, MRI Systems, CT Scanners, Ultrasound Devices End User: Cardiology Clinics, Hospitals, Diagnostic Laboratories, Research Institutes Technology: 2D Imaging, 3D Imaging, Doppler Imaging, Contrast Ultrasound Application: Valve Disease, Congenital Heart Defects, Coronary Artery Disease, Aortic Aneurysms |
| Companies Covered | Boston Scientific Corporation, Canon Medical Systems, GE Healthcare, Abbott Laboratories, Edwards Lifesciences Corporation, Siemens Healthineers, Medtronic, Pie Medical Imaging, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Structural Heart Imaging Market Strategic Shifts & Innovations
Computational imaging and regulatory pathway evolution are compressing product development cycles while redistributing competitive advantage toward software-integrated hardware platforms. The convergence of artificial intelligence with real-time visualization is altering how procedural teams consume imaging data.
Photon-counting CT detector technology is decomposing the trade-off between spatial resolution and radiation dose in cardiac protocols. Cardiac catheterization laboratories in tertiary United States hospitals are adopting these systems at replacement-cycle pace. The technology is decomposing conventional energy-integrating detector architectures by enabling sub-millimeter isotropic resolution at sub-millisievert dose levels.
The EU Medical Device Regulation's software-as-a-medical-device classification is redefining clinical evidence requirements for AI-enabled segmentation tools. Manufacturers must now submit retrospective validation studies across multiple sites to support CE marking. Cardiac imaging algorithm developers are responding by establishing European regulatory affairs functions earlier in product lifecycles.
Hospital purchasing committees are consolidating vendor relationships around integrated platform contracts that bundle hardware, software, and service. Independent service organizations and third-party maintenance providers are losing share to manufacturer-captive service models. This concentration is most visible in United States integrated delivery networks managing multi-site catheterization laboratory standardization programs.
Structural Heart Imaging Market Segmentation
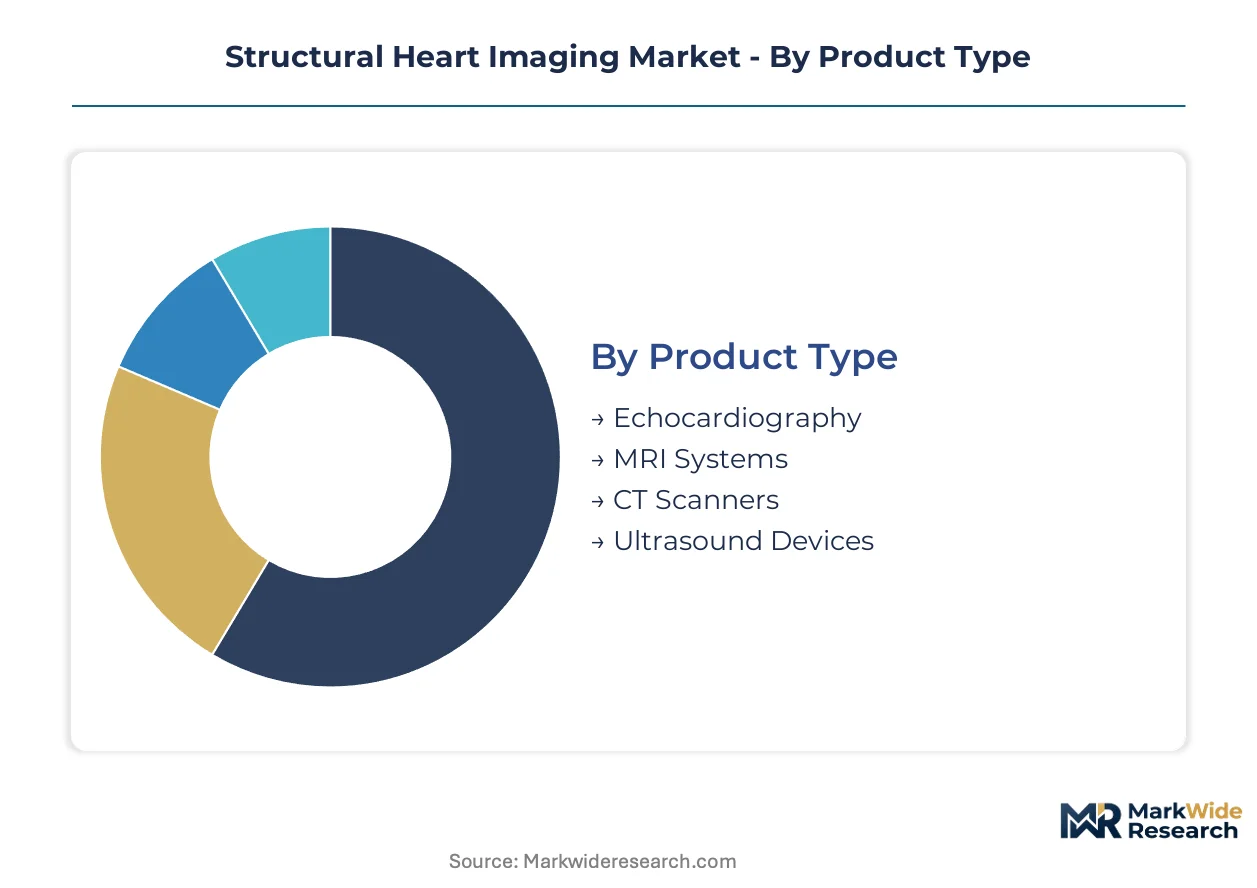
Structural heart imaging segments diverge sharply in substitution vulnerability. CT scanners erode echocardiography's procedural planning role while ultrasound devices face margin compression from integrated platform contracts.
Product Type:
Echocardiography confronts the most acute substitution pressure as CT-based pre-procedural planning displaces traditional volume assessment workflows.
- Echocardiography:Bedside systems employing transesophageal and transthoracic acoustic modalities dominate real-time procedural guidance. United States catheterization laboratories concentrate demand around three-dimensional transesophageal systems for transcatheter edge-to-edge repair, though reimbursement determination delays constrain capital refresh cycles.
- CT Scanners:Photon-counting detector architectures now deliver sub-millimeter isotropic resolution at sub-millisievert dose levels for cardiac protocols. Tertiary hospitals in Germany and Japan are adopting these systems at replacement-cycle pace as EPA and state-level radiation safety mandates force dose-reduction hardware refreshes.
- MRI Systems:Magnetic resonance platforms provide tissue characterization without ionizing radiation for complex congenital anatomy assessment.
- Ultrasound Devices:Handheld and point-of-care systems serve screening and follow-up monitoring outside catheterization laboratory environments.
Echocardiography anchors the volume base while CT Scanners gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital deployments from outpatient clinic models seeking lower-acuity procedure licensing.
- Hospitals:Integrated delivery networks in the United States manage multi-site catheterization laboratory standardization programs around bundled hardware-software-service contracts. Dedicated structural heart programs in Germany and Japan concentrate deployment of real-time three-dimensional echocardiography and CT fusion platforms.
- Cardiology Clinics:Ambulatory surgical center licensing for select transcatheter procedures is redistributing imaging system placement toward lower-acuity settings with streamlined capital requirements.
- Diagnostic Laboratories:Independent imaging centers perform pre-procedural planning studies on referral from proceduralist practices.
- Research Institutes:Academic medical centers validate artificial intelligence segmentation algorithms and novel contrast agent protocols.
Hospitals command the installed base while Cardiology Clinics expand most quickly through ambulatory licensing pathways.
Technology:
Application maturity varies from indispensable Doppler hemodynamics to emerging contrast perfusion modalities seeking expanded indications.
- 3D Imaging:Real-time volumetric reconstruction enables transcatheter valve deployment guidance with spatial resolution below one millimeter and frame rates exceeding thirty frames per second. FDA breakthrough device designations for planning software and CE marking under EU MDR are accelerating algorithm introductions.
- Doppler Imaging:Spectral and color flow modalities remain the indispensable workhorse for hemodynamic quantification across all procedural settings.
- 2D Imaging:Conventional tomographic planes persist for screening and longitudinal monitoring where three-dimensional reconstruction adds limited value.
- Contrast Ultrasound:Microbubble-enhanced perfusion imaging represents an emerging margin pool as perfluorocarbon-based microsphere agents expand ischemia assessment indications.
Doppler Imaging anchors the volume base while Contrast Ultrasound climbs the fastest on expanded perfusion indications.
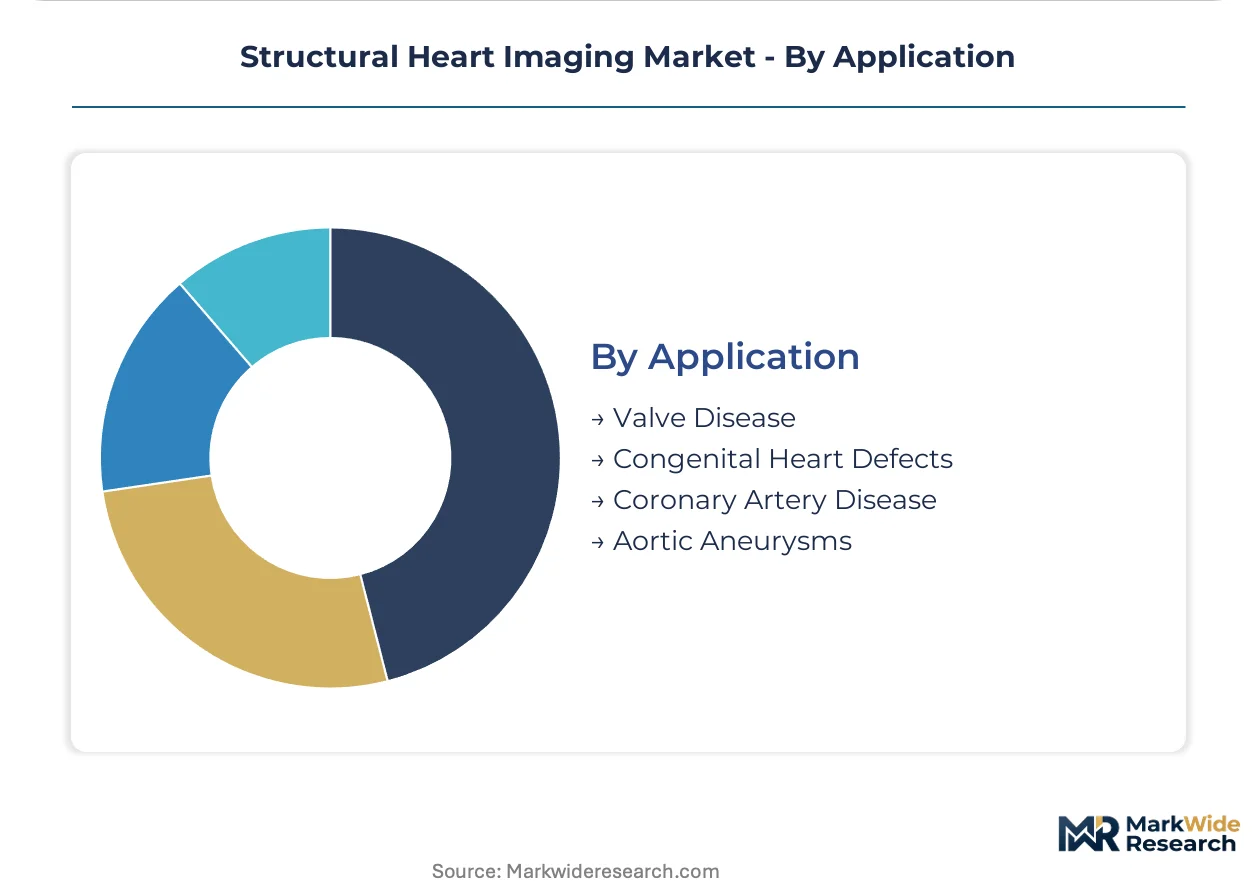
Application:
Volume concentration tracks procedural reimbursement availability and transcatheter device approval status across valve and coronary interventions.
- Valve Disease:Transcatheter aortic valve replacement and mitral edge-to-edge repair volumes pull demand for high-resolution pre-procedural planning and real-time guidance systems. METI-supported medical device innovation clusters in Kobe and Osaka create regulatory-fast-tracked entry points for CT-echocardiography fusion platforms targeting Japan's aging valve disease population.
- Coronary Artery Disease:Fractional flow reserve imaging and intravascular ultrasound integration with angiography systems supports percutaneous intervention planning.
- Congenital Heart Defects:Complex anatomy characterization demands multi-modality fusion for surgical and interventional planning in pediatric and adult congenital populations.
- Aortic Aneurysms:Endovascular repair planning requires precise three-dimensional centerline analysis and landing zone assessment.
Valve Disease anchors the volume base while Congenital Heart Defects gains share fastest on multi-modality fusion adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Structural heart imaging equipment flows disproportionately toward markets with mature reimbursement pathways for transcatheter procedures. The United States, Germany, and Japan absorb the majority of high-end system shipments, while emerging markets rely on refurbished platforms and secondary-market transfers.
United States
Integrated delivery networks in Texas, Florida, and the Northeast Corridor are consolidating catheterization laboratory procurement around bundled hardware-software-service contracts. FDA breakthrough device designations for planning software are accelerating algorithm introductions from developers seeking predicate device pathways. The Cleveland Clinic and Mayo Clinic anchor multi-site standardization programs that concentrate demand for real-time three-dimensional echocardiography.
Germany
Tertiary hospitals in Bavaria and North Rhine-Westphalia are adopting photon-counting CT systems at replacement-cycle pace as radiation safety mandates force dose-reduction hardware refreshes. CE marking under the EU Medical Device Regulation elevates software validation standards, favoring established visualization platforms with robust quality management systems. The Berlin-Brandenburg medical technology cluster supports regulatory affairs functions for algorithm developers.
Japan
METI-supported innovation clusters in Kobe and Osaka create regulatory-fast-tracked entry points for CT-echocardiography fusion platforms targeting the country's aging valve disease population. PMDA consultation pathways compress pre-market review timelines for structural heart planning software. The Kansai region concentrates deployment of hybrid imaging systems for transcatheter edge-to-edge repair procedures.
United Kingdom
NHS England specialized commissioning frameworks are concentrating structural heart program accreditation in London, Manchester, and Birmingham. MHRA recognition of FDA-approved devices accelerates market entry for visualization platforms already cleared in the United States. The Oxford-Cambridge arc hosts clinical validation studies for AI-enabled segmentation algorithms seeking CE marking.
India
Corporate hospital chains in Maharashtra, Karnataka, and Telangana are expanding catheterization laboratory capabilities to capture medical tourism flows for transcatheter valve procedures. CDSCO medical device rules are harmonizing with international standards, reducing registration timelines for established manufacturers. The Hyderabad medical devices park is attracting assembly operations for point-of-care ultrasound systems.
Structural Heart Imaging Market Key Industry Players
Listed leaders compete with private specialists across visualization software and detector hardware domains. The vendor base clusters around three tiers: diversified imaging conglomerates with full cardiac portfolios, cardiovascular-focused device manufacturers extending into procedural guidance, and pure-play software developers seeking algorithm licensing arrangements. Consolidation pressures favor integrated platform contracts that bundle hardware, software, and captive service models over independent maintenance providers.
Among diversified imaging conglomerates, GE Healthcare and Siemens Healthineers exemplify the hardware-software integration archetype, while Koninklijke Philips N.V. occupies a position spanning both diagnostic imaging and interventional device ecosystems. Boston Scientific Corporation and Abbott Laboratories represent the cardiovascular device manufacturer vector, leveraging proceduralist relationships to pull through imaging system placement. These groupings illustrate how competitive positioning increasingly depends on ecosystem breadth rather than point-product superiority.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Canon Medical Systems |
| GE Healthcare |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Siemens Healthineers |
| Medtronic |
| Pie Medical Imaging |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Ninety-day lead times for photon-counting CT detector arrays concentrate pricing power among German and Japanese component specialists, while integrated delivery networks in the United States exploit bundled procurement to compress margins on echocardiography systems.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade positioning through FDA breakthrough device designations and CE marking under EU MDR, while economy tiers serve refurbished secondary markets. Price differentiation separates photon-counting CT architectures from energy-integrating legacy systems. Cost compression in mid-tier echocardiography is intensifying because hospital purchasing committees consolidate vendor relationships around captive service models. Cardiology clinics in ambulatory settings exhibit highest price sensitivity; tertiary integrated delivery networks show lowest sensitivity due to bundled contract lock-in.
Supply Chain Analysis
Japan and Germany anchor precision detector manufacturing for cardiac CT protocols, while the United States concentrates visualization software development. Perfluorocarbon-based microsphere production for contrast agents draws from limited specialty chemical suppliers in Belgium and the United States. Supply chain risk centers on single-source vulnerability for photon-counting semiconductor substrates. Distribution runs through manufacturer-direct field service organizations that displace independent maintenance providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid skill scarcity in echocardiographer-proceduralist coordination constrains procedural throughput, creating acquisition premiums for training-scaled platforms and AI-enabled workflow automation.
For Market Incumbents: Consolidate installed-base loyalty through software companion development that locks visualization platforms into catheterization laboratory workflows. Deepen backward integration into detector semiconductor sourcing to mitigate single-source exposure. Defend against pure-play algorithm developers by accelerating predicate device strategies under FDA breakthrough pathways. For New Entrants and Emerging Players: Anchor in outpatient catheterization laboratory licensing as the most penetrable deployment channel. Target cardiology clinics in United States ambulatory surgical centers with streamlined capital requirements. Pursue algorithm licensing arrangements with diversified imaging conglomerates rather than hardware competition. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because bundled platform contracts are concentrating procurement decisions around ecosystem breadth rather than point-product superiority. Acquisition targets should demonstrate CE marking readiness under EU MDR software-as-a-medical-device classification. The signal to watch is reimbursement determination timing for real-time three-dimensional echocardiography guidance.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR software classification elevates validation standards for AI segmentation tools. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic anchor multi-site standardization programs. |
| Software Companion Development | Machine learning integration with Doppler assessment reduces operator variability. |
| Reimbursement Strategy | Coverage determination delays for 3D echocardiography create adoption friction. |
| FDA Submission | Breakthrough device designations compress time-to-market for planning software. |
Research Approach
Cross-validation between hospital purchasing committee interviews and CMS Medicare reimbursement data anchors the qualitative findings. Primary fieldwork engaged catheterization laboratory directors, biomedical engineers, GPO contracts managers, and visualization software product leads. Secondary validation drew from FDA 510(k) filings, CE marking databases under EU MDR, hospital procurement records, and EPA radiation safety mandate documentation. Bottom-up equipment shipment tracking triangulates against top-down expenditure modeling across the analysis window.
Sensitivity analysis tests forecast stability under alternative reimbursement determination timelines and detector technology replacement cycles. Segmentation dimensions span imaging modality, end-user facility type, technology maturity tier, and procedural application. CAGRs derive from installed-base expansion rates and capital refresh cycle analysis. Industry-specific inputs include transcatheter edge-to-edge repair volume projections and photon-counting CT adoption curves in tertiary hospitals.
Decision-makers should treat outputs as directional under base assumptions of stable FDA and CE marking pathways; material deviation in regulatory timelines would warrant model refresh. Specific risks include microbubble contrast agent supply disruptions and reimbursement lag for real-time guidance modalities. Recalibration cycles align with material shifts in structural heart program accreditation and detector technology investment cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
United Kingdom Nuclear Imaging Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
United Kingdom Magnetic Resonance Imaging Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Medical Imaging Outsourcing Market
Medical Imaging
Italy Magnetic Resonance Imaging Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Dental Imaging Market