
 Asia-Pacific Digital Radiology Market | 2026-2036
Asia-Pacific Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Radiology Market Analytics
Remote monitoring subscriptions and software-defined imaging protocols is recalibrating how vendors monetize hardware deployments across Asia-Pacific. GE Healthcare leverages its cloud-native analytics platform to sustain recurring revenue from installed base expansions in Australia and South Korea. Siemens Healthineers anchors its regional position through R&D intensity in photon-counting detector development. Canon Medical Systems competes on manufacturing scale, controlling production of flat-panel detectors at its Japanese facilities.
Digital radiology encompasses computed radiography systems, direct radiography panels, and portable units that convert X-ray photons into digital images through scintillator-coupled thin-film transistor arrays, enabling immediate visualization at dose levels below analog film. Direct Radiography dominates installed value across tertiary hospitals, while Portable Systems represent the fastest-expanding category as point-of-care protocols penetrate emergency departments and field clinics. CT Scan technology commands concentrated margin pools in oncology staging workflows, whereas Ultrasound segments face pricing pressure from commoditized transducer supply.
Japan's PMDA governs software-as-medical-device classifications for AI-embedded radiology platforms, while Australia's TGA enforces electromagnetic compatibility standards for mobile imaging units. India's CDSCO aligns with BIS certification requirements for imported detector assemblies, shaping market access timelines for foreign manufacturers. Stakeholders must monitor how China's NMPA classifies cloud-based image archiving services under revised medical device software rules.
Market Dynamics
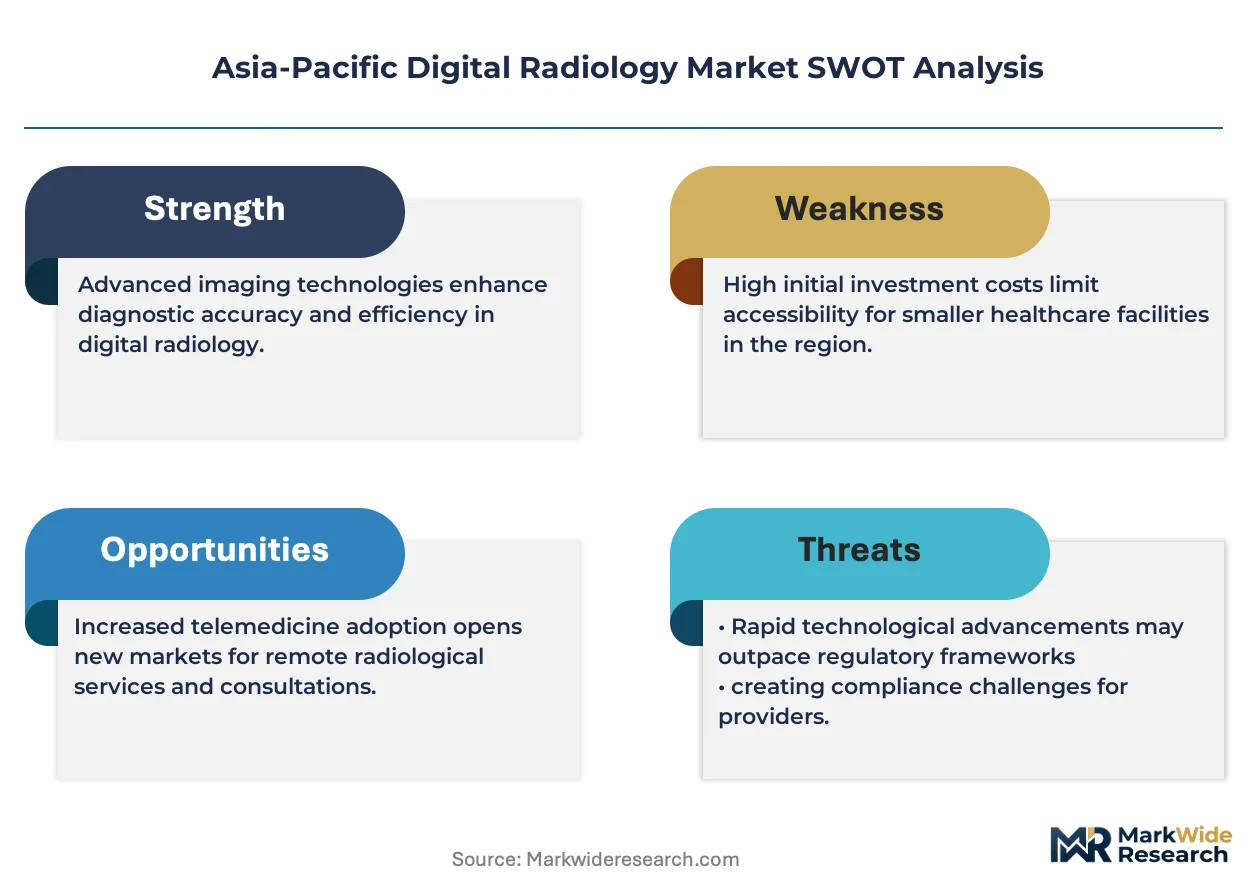
Photon-counting detector technology is compressing dose-exposure thresholds while expanding spectral imaging capabilities across tertiary hospitals in Australia, Japan, and South Korea. This hardware transition is forcing parallel investments in cloud-native analytics infrastructure and recalibrating procurement evaluation criteria away from standalone equipment specifications toward integrated ecosystem performance.
Growth Catalysts
- Australia's TGA electromagnetic compatibility standards:Streamlined approval pathways for mobile imaging units accelerate emergency department deployments in rural Queensland and Western Australia.
- India's Ayushman Bharat health infrastructure programs:Government-mandated rural clinic digitization creates sustained demand for portable digital radiography systems across tier-3 cities.
- AI-embedded diagnostic software:Japan's PMDA software-as-medical-device classification enables faster market entry for algorithm-assisted detection platforms in oncology workflows.
Market Restraints
- Scintillator crystal supply concentration:Cesium iodide and gadolinium oxysulfide production concentrates in East Asian refiners, exposing detector manufacturers to input cost volatility and single-source risk.
- China's NMPA cloud-classification uncertainty:Pending medical device software rules for image archiving services create compliance timeline friction for foreign platform vendors.
- Computed radiography substitution pressure:Legacy CR systems face accelerated replacement by direct radiography panels, stranding installed base service revenue for distributors.
Strategic Opportunities
- Vietnam and Indonesia hospital network expansion:Underpenetrated secondary cities present whitespace for turnkey digital imaging suite deployments as healthcare spending rises.
- Subscription-based remote monitoring:Software-defined imaging protocols enable recurring revenue models that decouple vendor economics from hardware replacement cycles.
- India's PLI scheme for medical electronics:Production-linked incentives attract flat-panel detector assembly investments, reducing import dependency and shortening fulfillment lead times.
Industry Challenges
- AI algorithm validation expertise:Shortage of radiologists trained in machine-learning quality assurance creates deployment bottlenecks for diagnostic software vendors.
- Legacy PACS integration complexity:Hospital IT departments struggle to harmonize proprietary DICOM implementations across multi-vendor installed bases.
- BIS certification timelines:India's mandatory testing for imported detector assemblies extends market access windows by 4-6 months compared to domestic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Radiology Market |
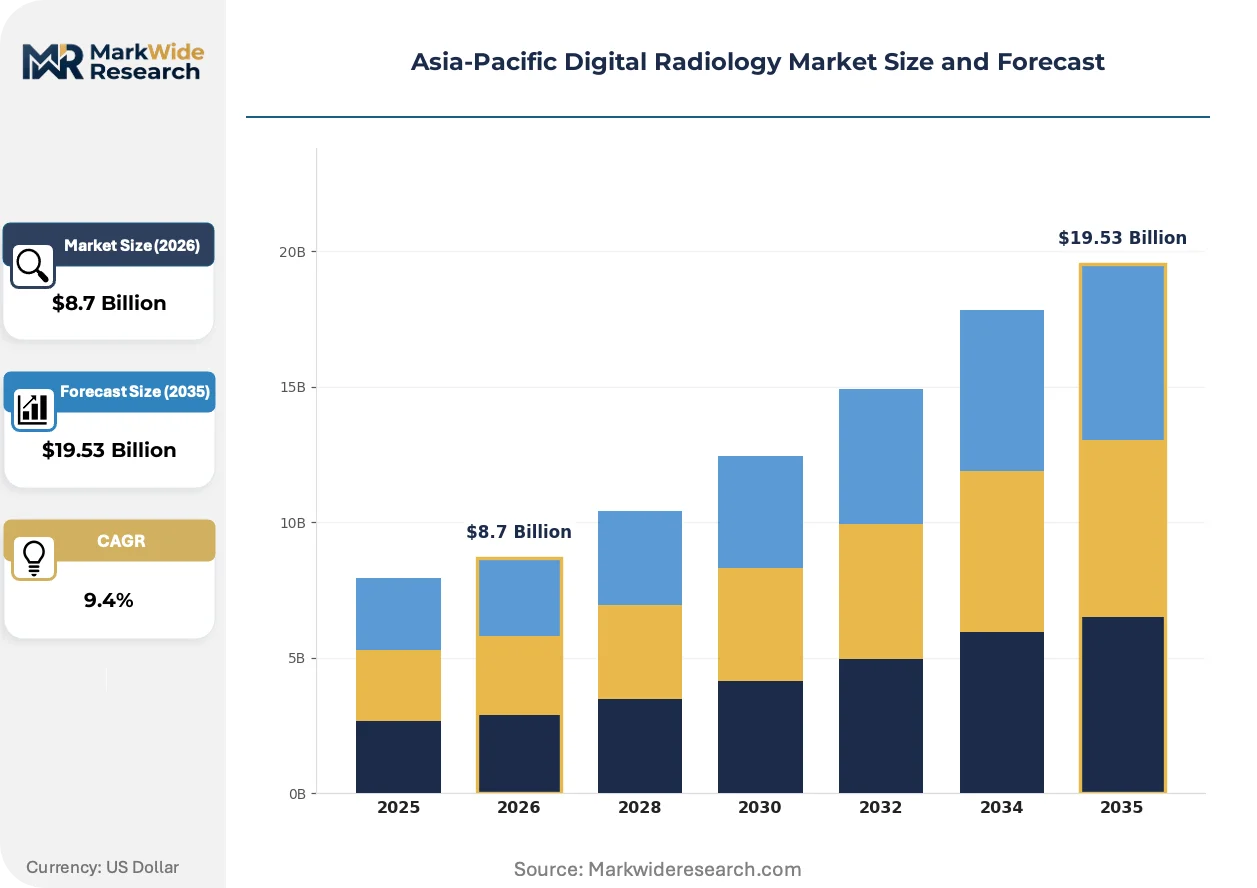
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Radiography, Direct Radiography, Hybrid Systems, Portable Systems Technology: X-Ray, MRI, Ultrasound, CT Scan End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Facilities Application: Oncology, Orthopedics, Cardiology, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips, Canon Medical Systems, FUJIFILM, Shimadzu, Samsung Medison, Mindray Medical International, Hitachi Healthcare, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Radiology Market Evolving Landscape
Deep-learning inference engines are embedding directly into detector electronics, shifting image reconstruction from centralized servers to edge hardware. This architectural inversion is compressing latency for time-critical diagnostics while redistributing computational load across the imaging network.
Convolutional neural networks trained on multi-institutional Asian patient cohorts are automating preliminary abnormality flagging in chest and musculoskeletal radiographs. Community hospitals in Thailand and Malaysia deploy these tools to compensate for radiologist staffing gaps. The technology is automating triage prioritization and reducing report turnaround times from hours to minutes in high-volume emergency settings.
Japan's PMDA revised its QMS guidance for AI-embedded devices in 2023, requiring continuous performance monitoring post-market rather than static pre-approval validation. Manufacturers must now submit algorithm update protocols as part of initial applications. This regulatory evolution most impacts vendors selling adaptive learning platforms into Japanese university hospitals, which are demanding contractual clarity on version-control liabilities.
Public hospital procurement across India's Maharashtra and Tamil Nadu states is consolidating vendor selection through centralized tendering portals. Single-source framework agreements now cover 3-5 year equipment lifecycles with bundled service commitments. This purchasing consolidation displaces fragmented district-level negotiations and favors suppliers with demonstrated spare parts logistics within the subcontinent.
Asia-Pacific Digital Radiology Market Segmentation
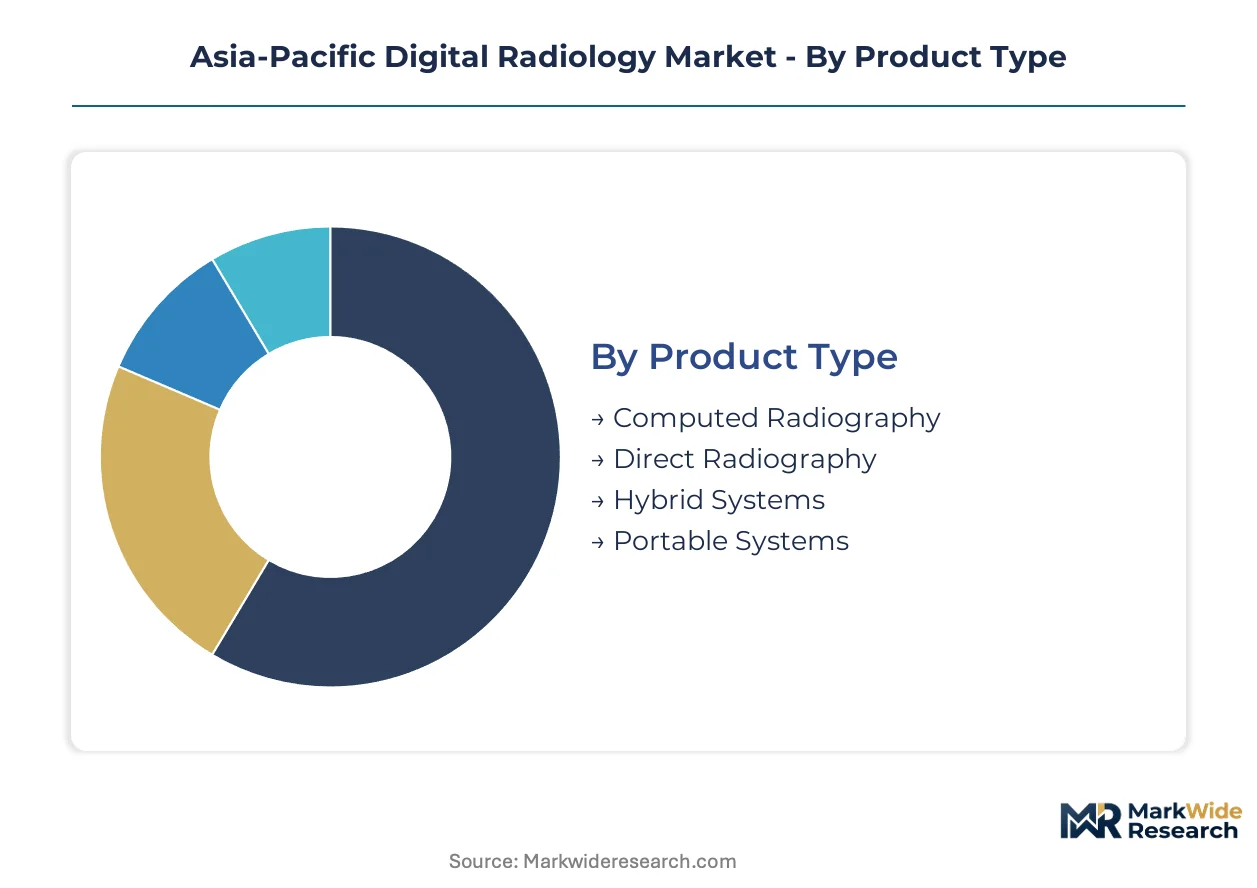
Segmentation reveals how hardware specifications, clinical workflows, and procurement budgets diverge across the Asia-Pacific digital radiology landscape. Understanding these splits enables vendors to align detector performance tiers with facility capabilities and regulatory pathways.
Product Type:
Volume deployments concentrate in entry-level systems for rural clinics, while premium installations target tertiary hospitals seeking spectral imaging capabilities.
- Direct Radiography:Flat-panel detectors with thin-film transistor arrays convert X-ray photons directly into digital signals without intermediate phosphor plates. Tertiary hospitals in Japan and South Korea concentrate procurement here, driven by PMDA and MFDS streamlined approvals for high-throughput oncology workflows.
- Portable Systems:Battery-powered wireless detector panels enable bedside and field deployment through lightweight scintillator-coupled assemblies. India's Ayushman Bharat rural clinic digitization programs concentrate demand in Maharashtra and Tamil Nadu, where centralized tendering favors vendors with domestic spare parts logistics.
- Computed Radiography:Legacy phosphor plate systems requiring mechanical scanning mechanisms dominate older installed bases.
- Hybrid Systems:Modular architectures allowing CR-to-DR upgrade paths serve budget-constrained facilities in Vietnam and Indonesia.
Mature deployment sits with Computed Radiography. Newer deployment is concentrated in Portable Systems.
Technology:
Margin pools concentrate in modalities requiring heavy shielding and computational reconstruction, while volume expansion targets point-of-care alternatives.
- CT Scan:Multi-detector ring assemblies with rotating X-ray sources generate cross-sectional volumetric datasets through filtered back-projection algorithms. Oncology staging workflows in Australia's major metropolitan hospitals anchor demand here, with TGA electromagnetic compatibility standards shaping mobile unit deployments in rural Queensland.
- Ultrasound:Piezoelectric transducer arrays emitting high-frequency sound waves create real-time anatomical visualization without ionizing radiation. Commoditized transducer supply chains from East Asian manufacturers concentrate pricing pressure across Southeast Asian outpatient facilities.
- X-Ray:Conventional radiographic tubes with fixed or rotating anodes remain the workhorse for skeletal and chest imaging.
- MRI:Superconducting magnet systems with cryogenic cooling enable soft-tissue contrast without radiation exposure.
Established infrastructure supports X-Ray. CT Scan is climbing the fastest as cancer screening programs expand.
End User:
Procurement authority separates centralized hospital networks from fragmented independent operators.
- Hospitals:Multi-department imaging departments with 24/7 emergency coverage require redundant detector arrays and integrated PACS infrastructure. Japan's university hospitals concentrate AI-embedded diagnostic software adoption, where PMDA post-market performance monitoring mandates shape vendor contracting.
- Diagnostic Centers:Specialized outpatient facilities focusing on high-volume screening services optimize throughput over clinical breadth. India's tier-2 and tier-3 cities see fastest expansion here, with CDSCO and BIS certification timelines determining foreign versus domestic equipment sourcing.
- Research Institutes:Academic medical centers prioritizing protocol development over clinical revenue.
- Outpatient Facilities:Primary care clinics with limited capital budgets and space constraints.
Capital deployment concentrates in Hospitals. Diagnostic Centers are gaining share fastest as screening privatizes.
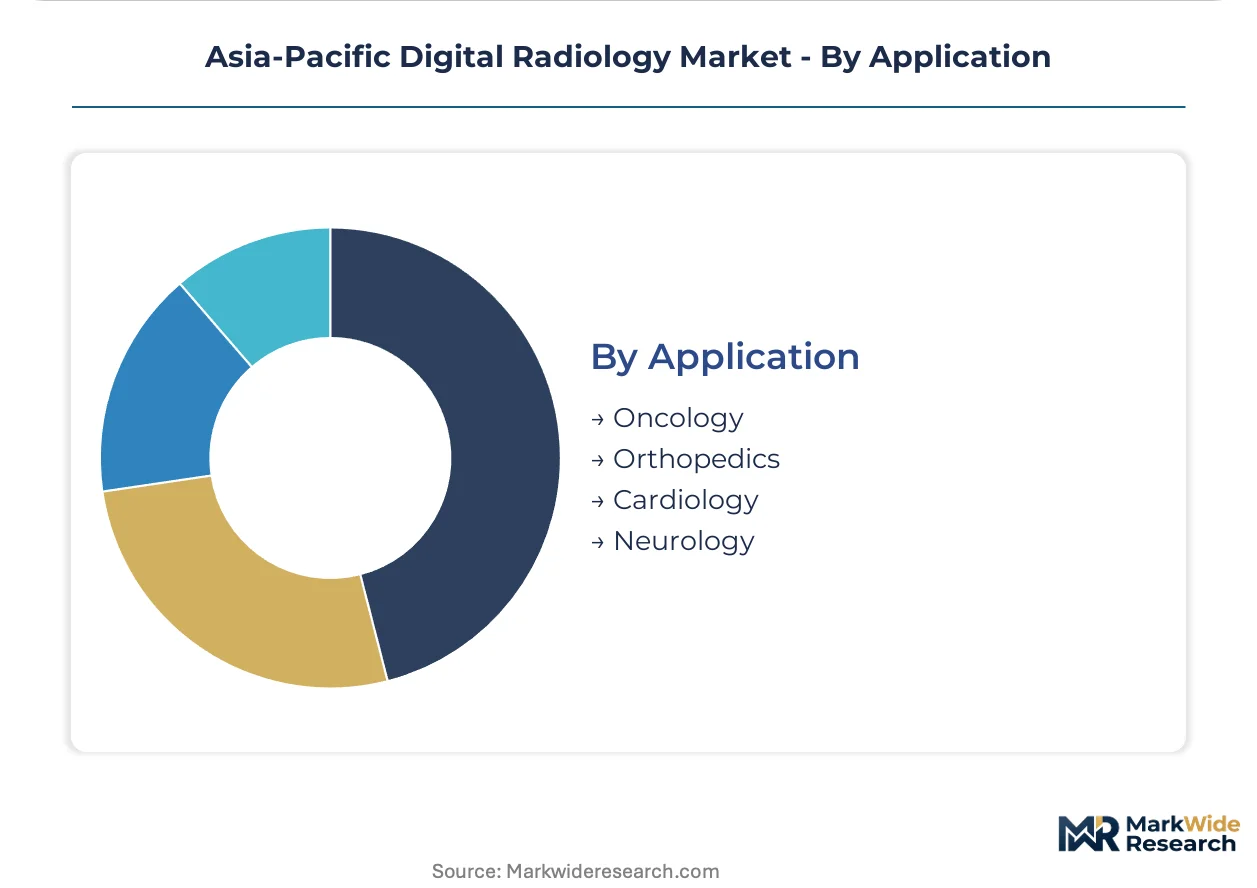
Application:
Clinical urgency and reimbursement rates determine detector specification requirements across therapeutic areas.
- Oncology:Low-dose spectral imaging with iterative reconstruction algorithms enables tumor detection and treatment monitoring at reduced radiation exposure. Australia's public hospital networks concentrate investment here, with photon-counting detector transitions compressing dose thresholds for repeat scanning protocols.
- Orthopedics:High-resolution musculoskeletal visualization demands large field-of-view detectors with edge-enhancement processing. Thailand and Malaysia deploy AI-assisted triage tools here to compensate for radiologist staffing gaps in community hospital settings.
- Cardiology:Gated imaging synchronized with cardiac cycles requires sub-millisecond temporal resolution.
- Neurology:Brain perfusion and vascular imaging prioritizes soft-tissue contrast over spatial resolution.
Reimbursement maturity sits with Orthopedics. Oncology shows the steepest expansion trajectory as screening programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's Kanto corridor anchors photon-counting detector development, with university hospitals driving AI-embedded software procurement. Hospital network expansions across Southeast Asia and India's rural digitization programs are redistributing demand geography across the Asia-Pacific digital radiology landscape.
Japan
PMDA's streamlined software-as-medical-device classifications accelerate AI diagnostic platform approvals. Post-market performance monitoring mandates now require continuous algorithm validation protocols. Osaka's Kansai region concentrates photon-counting R&D investments from major detector manufacturers.
India
Ayushman Bharat health infrastructure programs mandate rural clinic digitization across tier-3 cities. CDSCO and BIS certification timelines for imported detector assemblies extend market access windows by 4-6 months. Maharashtra and Tamil Nadu states consolidate procurement through centralized tendering portals favoring domestic spare parts logistics.
Australia
TGA electromagnetic compatibility standards shape mobile imaging unit deployments in rural Queensland and Western Australia. Oncology staging workflows in metropolitan hospitals anchor CT scanner investments. Photon-counting transitions compress dose thresholds for repeat scanning protocols in public hospital networks.
South Korea
MFDS regulatory alignment with international standards enables faster approval pathways for high-throughput digital radiography systems. Seoul Capital Area hospitals concentrate demand for integrated PACS infrastructure. Domestic flat-panel detector production scales through manufacturing investments in the Busan-Ulsan corridor.
Vietnam
Hospital network expansions in underpenetrated secondary cities create whitespace for turnkey digital imaging suite deployments. Government healthcare spending increases support procurement of portable systems for emergency departments. Ho Chi Minh City's medical device distribution hubs serve as import gateways for Southeast Asian markets.
Asia-Pacific Digital Radiology Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Asia-Pacific digital radiology landscape. The market structure consolidates around integrated equipment vendors with captive detector manufacturing and cloud-native analytics platforms. Three strategic archetypes dominate: full-stack imaging system providers, specialized detector component fabricators, and AI-embedded software platforms. M&A activity concentrates on analytics capabilities and regional service networks, while strategic partnerships secure scintillator crystal supply chains.
Within the full-stack imaging tier, GE Healthcare and Siemens Healthineers exemplify capital-intensive positions with integrated hardware-software ecosystems. Canon Medical Systems occupies a manufacturing-scale archetype with Japanese-based flat-panel detector production. These three entities represent the dominant competitive anchors across tertiary hospital procurement in Japan, Australia, and South Korea.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips |
| Canon Medical Systems |
| FUJIFILM |
| Shimadzu |
| Samsung Medison |
| Mindray Medical International |
| Hitachi Healthcare |
| Others |
Value Network & Pricing Analysis
Japan's university hospital networks and India's Ayushman Bharat procurement programs anchor demand concentration, locking vendors into long-term service contracts that bundle hardware, software, and maintenance into subscription-based recurring revenue models rather than transactional equipment sales.
Pricing Analysis
Throughput-based pricing anchors vendor economics across Asia-Pacific tertiary hospitals, where contracts tie payments to scan volumes, uptime guarantees, and AI-assisted diagnostic yields. Price differentiation separates premium photon-counting detector tiers from standard flat-panel configurations, with certification grade under Japan's PMDA software-as-medical-device rules adding further stratification. Cost compression in portable digital radiography intensifies as domestic assembly under India's PLI scheme shortens fulfillment lead times and reduces import dependency. Government procurement programs in Maharashtra and Tamil Nadu exhibit highest price sensitivity, while Japan's university hospitals prioritize performance specifications over unit economics.
Supply Chain Analysis
Refurbished detector panels and remanufactured scintillator assemblies flow back through authorized service depots in Japan and South Korea, extending component lifecycles and reducing raw material draw from primary refiners. Cesium iodide and gadolinium oxysulfide crystal production concentrates in Japan, South Korea, and select Chinese refiners, exposing detector manufacturers to single-source vulnerability in scintillator supply. Thin-film transistor array fabrication rests on semiconductor-grade silicon wafer supply from Taiwanese and South Korean foundries. Distribution runs through Ho Chi Minh City's medical device hubs for Southeast Asian markets and Mumbai-Chennai corridors for Indian subcontinent fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting detector transitions and AI-embedded software mandates are compressing margins for hardware-only vendors, forcing consolidation around integrated platform providers with captive component supply and cloud-native analytics capabilities.
For Market Incumbents:Lock in spare parts logistics within India's Maharashtra and Tamil Nadu states to defend position against domestic assembly competitors benefiting from PLI scheme incentives. Deepen backward integration into scintillator crystal supply through offtake agreements with Japanese and South Korean refiners, reducing exposure to single-source concentration risk in detector inputs.
For New Entrants and Emerging Players:Capture whitespace in Vietnam's secondary city hospital expansions and Indonesia's underpenetrated diagnostic center networks where turnkey digital imaging suite demand outpaces established vendor service capacity. Lead with portable system deployments targeting emergency department point-of-care protocols, leveraging wireless detector form factors to bypass entrenched PACS infrastructure requirements.
For Investors and Strategic Acquirers:The window for entry favors AI-embedded diagnostic software platforms with validated algorithm performance on Asian patient cohorts and clear regulatory pathways under Japan's PMDA post-market monitoring frameworks. Watch for PMDA algorithm update protocol submissions as early signals of vendor capability to meet evolving continuous validation mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Submission | Accelerates AI diagnostic platform market entry under Japan's streamlined approval pathways. |
| Domestic Flat-Panel Detector Assembly | Shortens fulfillment timelines and reduces BIS certification friction for Indian government tenders. |
| Photon-Counting Detector R&D Partnership | Secures spectral imaging capabilities for oncology staging workflows in Australian public hospitals. |
| Cloud-Native Analytics Platform Integration | Enables recurring revenue models decoupled from hardware replacement cycles across South Korean installations. |
| Centralized Tendering Portal Qualification | Unlocks multi-year framework agreements with Maharashtra and Tamil Nadu state procurement authorities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads. PMDA software classification databases, TGA electromagnetic compatibility standards documentation, CDSCO import certification registries, and India's centralized tendering portal awards provided validation benchmarks. Bottom-up detector shipment analysis and top-down healthcare infrastructure spending triangulation cross-checked volume estimates.
Granularity-level modeling disaggregated hardware specifications by detector technology tier, procurement channel, and end-user facility type across the projection horizon. CAGRs derived from fitted growth curves against government health infrastructure program budgets and hospital network expansion timelines. AI-embedded software adoption curves and photon-counting detector transition rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA cloud-classification rule finalization and scintillator crystal supply disruptions. Practitioners should monitor PMDA algorithm update protocol submission volumes and India's PLI scheme participant expansion for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
South Korea Magnetic Resonance Imaging Market
Medical Imaging
Brazil Digital X-Ray Market
Medical Imaging
Vascular Imaging Systems Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Argentina Nuclear Imaging Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Global Medical Imaging Workstation Market