
 Mammography Workstation Market | 2026-2036
Mammography Workstation Market Size, Share, and Industry Trends Forecast 2026-2036
Mammography Workstation Market Intelligence
Cloud-native PACS integration with artificial intelligence is reconfiguring how mammography workstations acquire, process, and distribute diagnostic images across hospital networks. Siemens Healthineers leverages its syngo platform to anchor enterprise imaging deployments in European academic medical centers. Fujifilm Holdings Corporation sustains competitive positioning through specialized breast imaging algorithms and end-to-end modality-to-workstation workflows. Hologic dominates the 3D tomosynthesis workstation segment with proprietary image reconstruction architectures.
A mammography workstation is a dedicated computing system engineered for acquisition, display, manipulation, and archival of digital breast images, typically supporting spatial resolutions exceeding five megapixels and DICOM compliance for interoperability with hospital information systems. Its primary commercial purpose is to enable radiologists to detect microcalcifications and architectural distortions with diagnostic confidence while integrating with broader breast imaging IT infrastructure. Fully-integrated systems lead installed base volumes but AI-enhanced imaging workstations represent the fastest-expanding margin pool as algorithms automate density assessment and lesion triage. Diagnostic imaging centers anchor demand within the end-user landscape, while screening applications concentrate procurement volume due to population-scale breast cancer detection programs.
FDA premarket notification pathways and the European Medical Device Regulation shape product development cycles, with FDA's breakthrough device designation accelerating AI-enabled workstation reviews and MDR clinical evidence requirements extending certification timelines for new entrants. HIPAA security rule provisions and GDPR data governance frameworks further constrain how breast imaging data traverses cloud-connected workstation architectures. Stakeholders must monitor evolving reimbursement codes for AI-assisted mammography interpretation, as coverage determinations will dictate whether health systems accelerate workstation refresh cycles or defer capital deployment.
Market Dynamics
Cloud-native PACS integration with artificial intelligence is compressing product development cycles and forcing incumbent workstation manufacturers to rebuild software architectures around API-first deployment models. FDA breakthrough device designations for AI-enhanced mammography algorithms are accelerating clearance timelines while simultaneously raising the competitive bar for algorithmic performance validation.
Growth Catalysts
- MDR Clinical Evidence Pathways:European Medical Device Regulation requirements for clinical performance data are driving academic medical centers in Germany and France to upgrade to AI-validated workstations that meet post-market surveillance mandates.
- Screening Program Expansion:United States breast cancer screening initiatives targeting underserved populations are generating procurement volume for diagnostic imaging centers requiring high-throughput 3D tomosynthesis workstations.
- Density Assessment Automation:AI-powered breast density classification algorithms are reducing radiologist reading time and prompting health system capital committees to approve workstation refresh cycles ahead of schedule.
Market Restraints
- Semiconductor Component Concentration:GPU and specialized AI accelerator supply constraints concentrated among Taiwan-based foundries are extending workstation manufacturing lead times and inflating hardware costs.
- GDPR Data Sovereignty Requirements:European Union data governance frameworks mandating local processing of patient health records are complicating cloud-native workstation deployments and requiring redundant infrastructure investments.
- Legacy PACS Interoperability Friction:Proprietary DICOM implementation variations across installed base systems from the 2010s are forcing expensive middleware development for AI integration.
Strategic Opportunities
- Community Hospital Undersupply:Rural and suburban United States health systems operating on decade-old 2D mammography infrastructure represent untapped demand for cost-optimized AI-enhanced workstation packages.
- Telemammography Service Models:Teleradiology networks are creating distributed workstation deployment opportunities where centralized AI processing supports geographically dispersed reading stations.
- IRA Preventive Care Incentives:United States Inflation Reduction Act provisions expanding zero-cost breast cancer screening are aligning reimbursement policy with workstation procurement decisions in federally qualified health centers.
Industry Challenges
- Radiologist AI Literacy Gap:Practicing breast imaging specialists require structured training on algorithm-assisted interpretation workflows, creating implementation bottlenecks at academic medical centers.
- FDA 510(k) Predicate Device Complexity:Substantial equivalence determinations for AI-modified workstations demand extensive predicate comparison documentation, extending regulatory submission preparation timelines.
- Multi-Vendor Integration Architecture:Health systems deploying best-of-breed combinations of imaging modalities, PACS, and AI algorithms face middleware compatibility testing burdens that delay go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mammography Workstation Market |
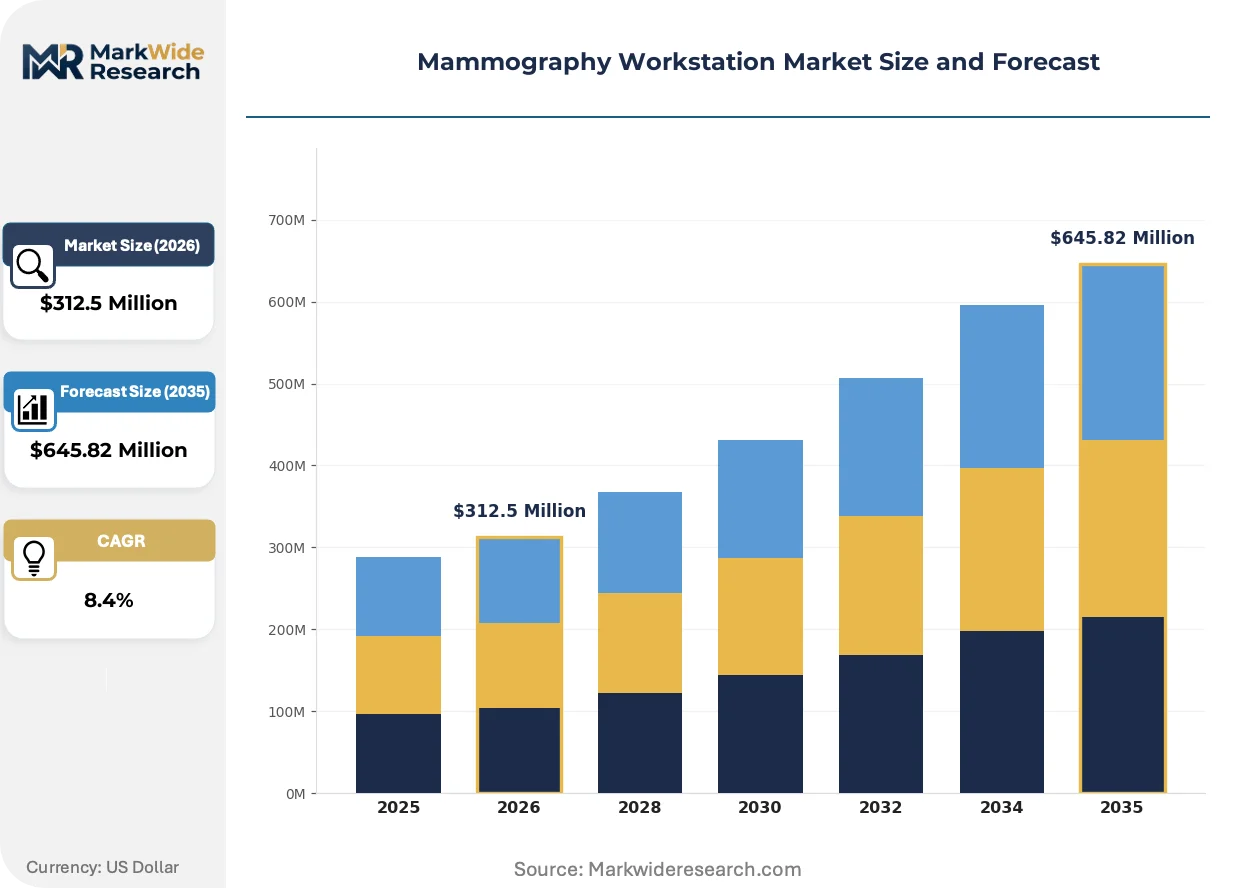
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully-Integrated System, Viewing Workstation, Image Management Software, Mobile Workstation End User: Hospitals, Diagnostic Imaging Centers, Research Laboratories, Outpatient Clinics Technology: Digital Mammography, Analog Mammography, 3D Tomosynthesis, AI-Enhanced Imaging Application: Screening, Diagnostic Imaging, Patient Monitoring, Image Analysis |
| Companies Covered | Philips Healthcare, Sectra, GE Healthcare, Konica Minolta, Analogic Corporation, Siemens Healthineers, Fujifilm Holdings Corporation, Agfa-Gevaert, Hologic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mammography Workstation Market Strategic Shifts & Innovations
Edge computing architectures are relocating AI inference workloads from centralized cloud servers to on-premise workstation hardware, reshaping latency requirements and data governance strategies across hospital networks.
GPU-accelerated real-time tomosynthesis reconstruction is rendering obsolete the batch-processing workstations that required minutes per 3D mammography study. Academic medical centers in the United States are adopting these sub-30-second reconstruction systems to maintain screening throughput during peak volume periods. The technology is compressing capital depreciation schedules as health systems retire hardware purchased just three to five years prior.
FDA breakthrough device designation pathways for AI-enabled mammography workstations are compressing premarket notification review timelines from twelve months to under six months for qualifying submissions. The industrial consequence is an acceleration of competitive product launches crowding the premium segment. European manufacturers are responding by front-loading clinical validation studies to secure parallel CE marking under MDR Article 54.
Subscription-based software licensing is displacing perpetual license purchases for AI algorithm modules across United States diagnostic imaging centers. The capital expenditure avoidance model appeals to independent radiology groups facing reimbursement compression from CMS fee schedule adjustments. This shift is most visible in California and Texas markets where private equity-backed imaging rollups prioritize operational expenditure predictability over asset ownership.
Mammography Workstation Market Segmentation
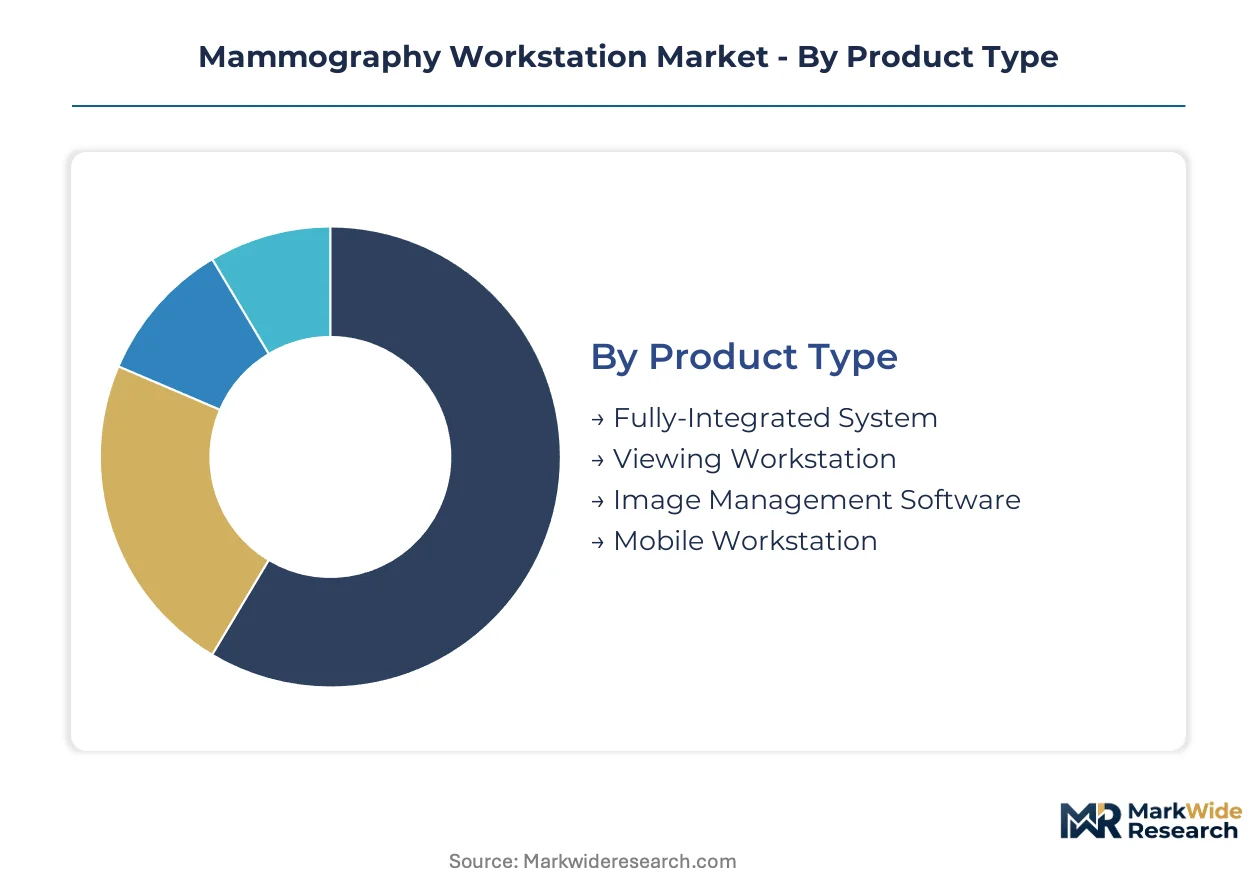
Mammography workstation procurement patterns diverge sharply across product architectures and care settings. Technical specifications, integration requirements, and reimbursement pathways create distinct commercial pockets within each segmentation dimension.
Product Type:
After-sales-service intensity varies dramatically across product architectures, with fully-integrated systems demanding multi-year maintenance contracts and software-defined platforms shifting toward subscription-based support models.
- Fully-Integrated System:Complete hardware-software bundles with proprietary image reconstruction engines and vendor-locked calibration protocols. Demand concentrates in United States academic medical centers where enterprise imaging consolidation mandates unified workstation fleets.
- Viewing Workstation:Display-centric units optimized for radiologist interpretation workflows, typically featuring five-megapixel grayscale monitors and DICOM calibration. Diagnostic imaging centers in California and Texas prioritize these for high-volume screening programs where throughput dictates procurement decisions.
- Image Management Software:PACS-agnostic applications enabling multi-vendor image aggregation and AI algorithm orchestration.
- Mobile Workstation:Portable units with battery-backed operation for point-of-care breast imaging and rural deployment scenarios.
Fully-Integrated System holds the largest share; momentum sits with Image Management Software.
End User:
Capital deployment cycles and reimbursement exposure create distinct customer tiers, with hospitals optimizing for enterprise integration and outpatient settings prioritizing payback period metrics.
- Hospitals:Integrated delivery networks with centralized IT governance and multi-modality imaging portfolios. United States health systems in the Northeast are consolidating workstation procurement through single-vendor enterprise agreements to reduce interoperability friction.
- Diagnostic Imaging Centers:Independent facilities with volume-based revenue models and rapid equipment depreciation schedules. These operators in Florida and Arizona are adopting AI-enhanced workstations to maintain competitive positioning against hospital-affiliated imaging departments.
- Research Laboratories:Academic and commercial R&D sites requiring specialized workstations for clinical trial imaging and algorithm development.
- Outpatient Clinics:Federally qualified health centers and community-based facilities serving screening-naive populations.
Hospitals command the greatest procurement volume; Diagnostic Imaging Centers are expanding most quickly.
Technology:
Technology selection directly determines regulatory pathway complexity and clinical validation burden, with AI-enabled platforms facing heightened FDA scrutiny alongside accelerated breakthrough designations.
- 3D Tomosynthesis:Tomographic reconstruction systems generating slice-based breast imaging with reduced tissue overlap artifacts. United States screening programs mandate tomosynthesis capability for reimbursement eligibility, concentrating demand in Medicare Advantage networks.
- AI-Enhanced Imaging:Algorithm-augmented workstations automating density assessment, lesion detection, and triage prioritization. Academic medical centers in Germany are deploying these under MDR Article 54 clinical evidence requirements to satisfy post-market surveillance mandates.
- Digital Mammography:Conventional 2D full-field digital systems with established reimbursement codes and mature installed base.
- Analog Mammography:Film-based systems with declining installed base, primarily in resource-constrained international markets.
Digital Mammography retains the broadest installed base; AI-Enhanced Imaging shows the steepest expansion trajectory.
Application:
Workflow design and throughput specifications diverge between population-scale screening and complex diagnostic scenarios, with distinct workstation configurations optimized for each use case.
- Screening:High-volume interpretation workflows with standardized protocols and double-reading requirements. United States breast cancer screening initiatives targeting underserved populations are generating procurement volume for workstations capable of processing 150-plus studies daily.
- Diagnostic Imaging:Multi-modality correlation workflows integrating mammography with ultrasound and MRI for lesion characterization. Tertiary care centers in France and the United Kingdom prioritize these workstations for symptomatic patient pathways.
- Patient Monitoring:Longitudinal imaging surveillance for high-risk cohorts and post-treatment follow-up.
- Image Analysis:Quantitative imaging research and radiomics applications requiring specialized processing pipelines.
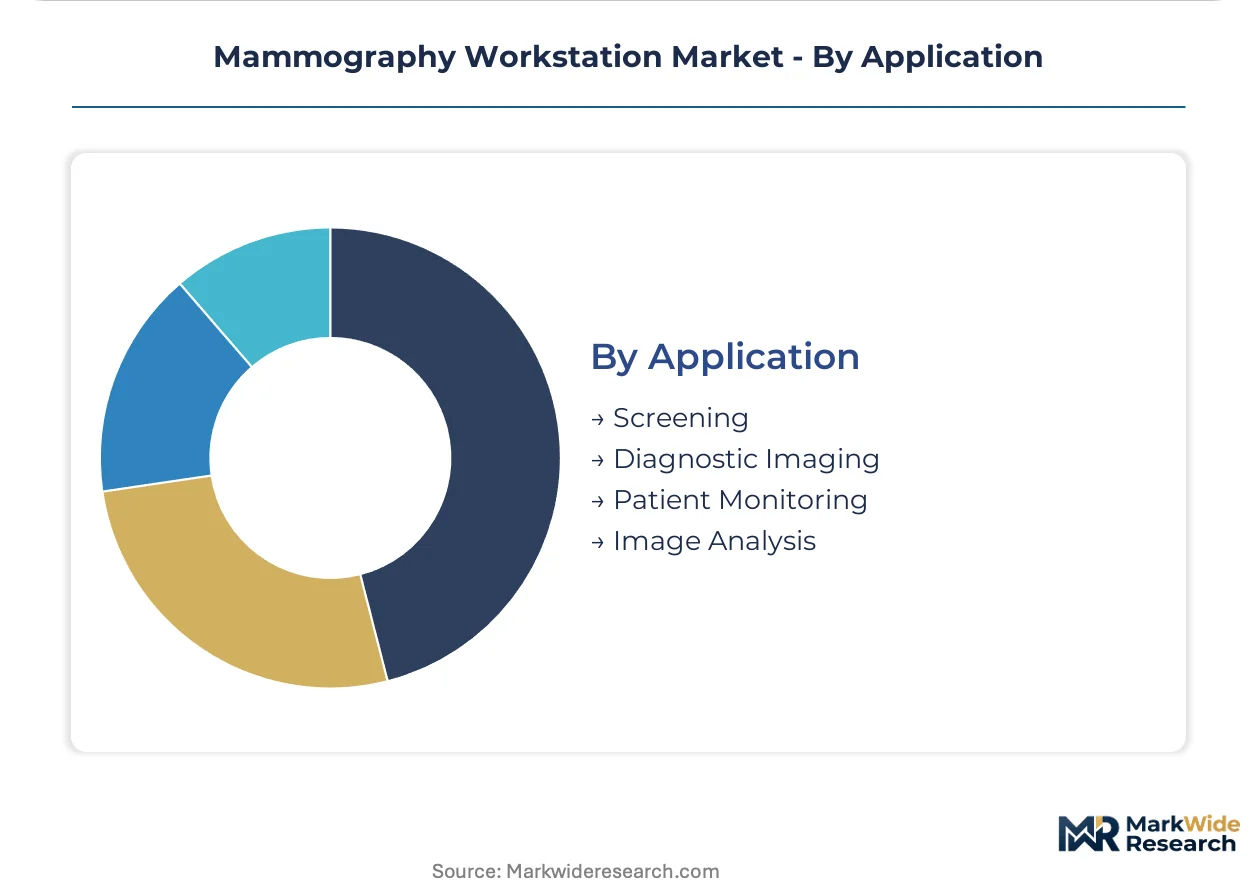
Screening dominates procurement volume; Diagnostic Imaging captures the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export AI-validated mammography workstations to academic medical centers in France and the United Kingdom, establishing a north-south trade corridor across European screening networks.
United States
Medicare Advantage screening program expansions and FDA breakthrough device designations drive procurement of 3D tomosynthesis workstations. The Inflation Reduction Act's zero-cost preventive care provisions align reimbursement policy with capital deployment in federally qualified health centers. Texas and Florida diagnostic imaging centers concentrate demand for high-throughput systems processing 150-plus daily studies.
Germany
MDR Article 54 clinical evidence requirements and post-market surveillance mandates compel university hospitals to upgrade AI-enhanced imaging infrastructure. BfArM regulatory oversight shapes validation protocols for algorithm-assisted breast density classification. Bavarian medical technology clusters around Munich anchor manufacturing of GPU-accelerated reconstruction systems.
France
ANSM regulatory frameworks and national breast cancer screening program extensions generate demand for enterprise imaging consolidation. GDPR data sovereignty requirements complicate cloud-native workstation deployments in Parisian hospital networks. Lyon-based academic medical centers pilot edge computing architectures for on-premise AI inference.
United Kingdom
NHS England breast screening service modernization and AI diagnostic funding pilots accelerate workstation refresh cycles. MHRA post-Brexit regulatory autonomy streamlines clearance pathways for 3D tomosynthesis systems. London teaching hospitals concentrate procurement of multi-modality correlation workstations for symptomatic patient pathways.
Japan
PMDA regulatory harmonization with FDA standards accelerates approval timelines for AI-enhanced mammography algorithms. METI industrial policy supports domestic production of specialized medical imaging processors. Tokyo and Osaka metropolitan areas concentrate demand for compact workstations serving dense urban screening populations.
Mammography Workstation Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers: enterprise imaging conglomerates with PACS integration capabilities, modality-native workstation architects, and AI algorithm specialists licensing software layers. Market structure tilts toward consolidation as health systems prioritize single-vendor agreements to reduce interoperability friction. Dominant competitive moves include strategic partnerships between hardware manufacturers and AI developers, plus geographic expansion through teleradiology network deployments.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the enterprise imaging archetype with platform-agnostic deployment capabilities. Hologic occupies a position representing the modality-native specialist tier, while Sectra exemplifies the PACS-centric software layer approach. Fujifilm Holdings Corporation and Philips Healthcare anchor the integrated modality-to-workstation workflow segment.
| Leading Market Players |
|---|
| Philips Healthcare |
| Sectra |
| GE Healthcare |
| Konica Minolta |
| Analogic Corporation |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Agfa-Gevaert |
| Hologic |
| Others |
Cost & Logistics Intelligence
Taiwan-based foundry capacity for GPU and AI accelerator silicon directly shapes workstation pricing power, with supply constraints inflating hardware costs for manufacturers dependent on advanced semiconductor nodes. Health systems negotiating enterprise imaging contracts face compressed margins as component scarcity propagates through tiered product architectures.
Pricing Analysis
Three-generation pricing stratification separates real-time GPU-accelerated reconstruction systems from batch-processing legacy workstations and emerging edge-computing inference units. Premium-mid-economy pricing differentiation rests on FDA breakthrough designation status and AI algorithm validation depth, with certified systems commanding substantial uplifts. Cost compression in the mid-tier intensifies because independent imaging centers prioritize operational expenditure predictability over capital ownership, accelerating subscription licensing adoption. Federally qualified health centers exhibit the highest price sensitivity due to constrained capital budgets, while academic medical centers demonstrate the lowest sensitivity given enterprise consolidation mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for mammography workstation manufacturers sourcing display panels and specialized imaging processors. Production gravity centers on Taiwan for GPU silicon, Japan for high-resolution grayscale monitors, and Germany for precision mechanical components. Raw material dependencies include rare earth elements for magnet assemblies, medical-grade aluminum for chassis fabrication, and specialized glass substrates for five-megapixel displays. Single-source vulnerability concentrates in Taiwan-based foundry capacity for AI inference accelerators. Distribution runs through direct sales forces serving integrated delivery networks and specialized imaging distributors targeting independent diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as United States health systems consolidate workstation procurement through single-vendor enterprise agreements, reducing interoperability friction while squeezing supplier margins across the competitive landscape.
For Market Incumbents: Build regulatory certification moats by accelerating FDA breakthrough device submissions for AI-enhanced density classification algorithms and securing parallel CE marking under MDR Article 54. Siemens Healthineers and Hologic should deepen backward integration into GPU-accelerated reconstruction silicon to offset Taiwan foundry pricing volatility. Channel control through long-term service contracts with academic medical centers provides defensive positioning against emerging AI-native software entrants. For New Entrants and Emerging Players: Pursue community hospital and rural health system segments where decade-old 2D mammography infrastructure creates replacement demand for cost-optimized AI-enhanced packages. The most penetrable geography spans Texas and Florida diagnostic imaging centers facing reimbursement compression from CMS fee schedule adjustments. A software-first go-to-market angle leveraging PACS-agnostic image management platforms bypasses incumbent hardware lock-in and accelerates time-to-revenue. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because enterprise imaging mandates favor platform-agnostic vendors with proven multi-modality integration capabilities. Acquisition targets should display AI algorithm validation depth paired with established hospital system relationships rather than pure hardware manufacturing scale. The signal to watch is reimbursement code expansion for AI-assisted mammography interpretation, which would trigger accelerated workstation refresh cycles across capital-constrained health systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated clearance timelines compress competitive launch windows for AI-enhanced workstations. |
| Hospital System Partnership | Enterprise agreements with integrated delivery networks lock out multi-vendor procurement alternatives. |
| Software Companion Development | Density assessment algorithms integrated with existing PACS infrastructure expand addressable market. |
| CE Marking Pathway | MDR Article 54 compliance opens academic medical center procurement in Germany and France. |
| Reimbursement Strategy | Coverage determination alignment with IRA preventive care provisions drives federally qualified health center demand. |
Research Approach
Operator-level perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and radiology department chairs anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA 510(k) premarket notification databases, CMS Medicare reimbursement code filings, and hospital procurement contract registries. Bottom-up and top-down triangulation cross-checked installed base estimates against capital expenditure disclosures from United States health systems and European academic medical centers.
Scenario-bracketing framed volume and value outputs across the projection horizon, with base, optimistic, and conservative cases reflecting alternative regulatory approval timelines and reimbursement policy trajectories. Segmentation dimensions modeled include product architecture, end-user facility type, technology generation, and application workflow. CAGRs derived from fitted growth curves incorporating historical procurement patterns and policy-aligned demand inflection points. Forecast inputs included MDR compliance deadlines, IRA preventive care expansion schedules, and AI algorithm validation study completion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native AI software entrants or cross-border imaging modality manufacturers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Digital Radiology Market
Medical Imaging
US Medical Imaging Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Medical Imaging Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Germany Mammography Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market