
 India Mammography Market | 2026-2036
India Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
India Mammography Market Foresight
Maharashtra is reshaping competitive dynamics in the India mammography landscape through concentrated hospital infrastructure expansion and diagnostic hub development. Hologic Inc. leverages its digital breast tomosynthesis portfolio to sustain premium positioning across metropolitan imaging networks. Siemens Healthineers anchors its presence through localized service infrastructure and radiologist training ecosystems. Wipro GE Healthcare competes on cost-optimized digital systems tailored for mid-tier hospital procurement cycles.
Mammography denotes X-ray imaging of breast tissue using low-dose ionizing radiation, typically operating at 25–35 kVp tube voltage with molybdenum or rhodium target materials and dedicated compression paddles to enhance image contrast. The technology enables early detection of microcalcifications and mass lesions for population-scale breast cancer screening and diagnostic workup. Full-field digital mammography dominates installed base economics due to superior dose efficiency and PACS integration, while tomosynthesis segments command margin premiums through reconstructed slice imaging that reduces tissue overlap artifacts. Diagnostic centers represent the fastest-growing end-user channel as standalone operators invest in capital-light leasing models to capture outpatient referral flows.
CDSCO governs device registration and import licensing for mammography systems under the Medical Device Rules, while BIS certification mandates electrical safety and electromagnetic compatibility compliance for domestic manufacture. The PLI scheme for medical devices incentivizes local production of high-value imaging components, altering import dependency patterns for detector panels and X-ray tube assemblies. Stakeholders must monitor state-level oncology mission tenders and radiologist workforce density gaps to calibrate geographic deployment strategies.
Market Dynamics
Ayushman Bharat reimbursement expansion is redrawing capital deployment patterns across India's mammography infrastructure, pulling private diagnostic chains toward tier-2 cities while compressing equipment procurement cycles.
Growth Catalysts
- PLI scheme for medical devices:Domestic production incentives for high-value imaging components are reducing import dependency for detector panels and X-ray tube assemblies.
- Tier-2 city hospital expansion:Maharashtra and Karnataka oncology clusters are driving screening program scale-up through concentrated infrastructure investment.
- Digital breast tomosynthesis adoption:Reconstructed slice imaging technology is displacing conventional 2D mammography in metropolitan diagnostic networks.
Market Restraints
- Import concentration for core components:Detector panel and X-ray tube supply chains remain concentrated in East Asian manufacturing hubs, exposing procurement to logistics volatility.
- Radiologist workforce density gaps:Interpretation capacity constraints in tier-2 and tier-3 cities limit effective utilization of installed imaging equipment.
- CDSCO registration timelines:Device import licensing and BIS certification requirements extend commercialization lead times for new system introductions.
Strategic Opportunities
- Standalone diagnostic center leasing models:Capital-light equipment financing is enabling outpatient referral capture without full ownership burden.
- Karnataka-Maharashtra hub densification:Oncology infrastructure clustering in these states creates service ecosystem opportunities for maintenance and training.
- AI-assisted image interpretation:Machine learning integration with digital mammography systems addresses radiologist scarcity in underserved districts.
Industry Challenges
- PACS integration complexity:Legacy hospital information systems in public sector facilities require costly middleware development for seamless connectivity.
- Service technician certification gaps:Specialized training for digital breast tomosynthesis maintenance lags behind equipment deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Mammography Market |
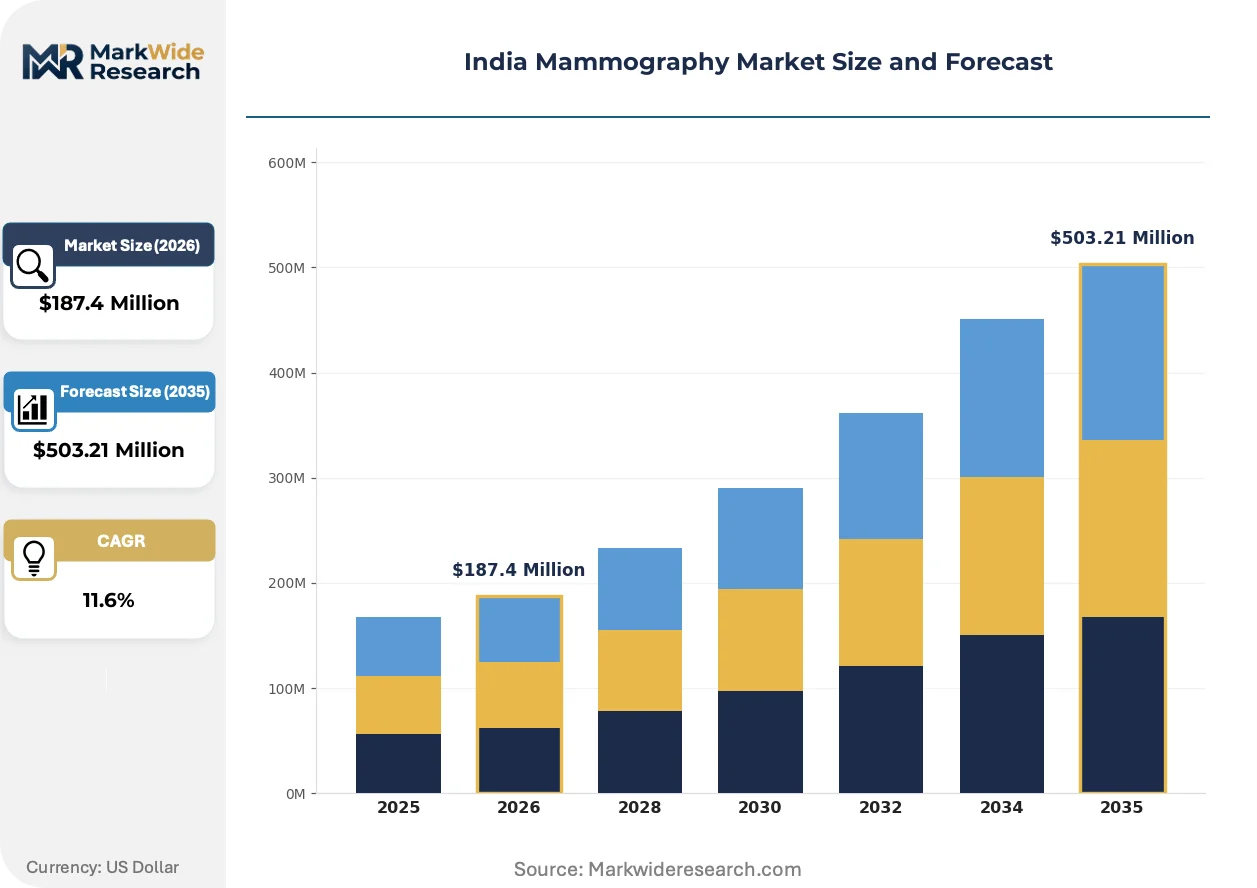
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital, Analog, 3D, Portable Technology: Full-Field Digital, Screen-Film, Tomosynthesis, Contrast-Enhanced End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Research Institutes Application: Routine Screening, Diagnostic Imaging, Research Studies, Follow-Up |
| Companies Covered | Hologic Inc., GE Healthcare, Siemens Healthineers, Wipro GE Healthcare, Fujifilm Holdings Corporation, Philips Healthcare, BPL Medical Technologies, Allengers Medical Systems, Planmed Oy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Mammography Market Shifts & Advancements
Technology convergence and reimbursement mechanics are compressing traditional equipment ownership models while elevating software-enabled service differentiation.
Digital breast tomosynthesis is collapsing the diagnostic accuracy gap between screening and diagnostic mammography workflows. Tier-1 hospital networks in Mumbai and Bangalore are replacing 2D systems at accelerated refresh cycles. The technology is collapsing tissue overlap artifacts that previously drove callback rates and patient anxiety.
CDSCO's streamlined Medical Device Rules implementation is compressing registration timelines for domestically manufactured components. The regulatory shift favors local assembly operations over fully-built unit imports. Maharashtra-based manufacturers are responding with detector panel sourcing partnerships to capture PLI scheme benefits.
Diagnostic chains are unbundling equipment ownership from service delivery through operating lease structures. Standalone imaging centers in Pune and Hyderabad are adopting per-scan pricing models that transfer technology obsolescence risk to lessors. This restructuring is most visible in Karnataka's outpatient referral networks where capital efficiency determines competitive survival.
India Mammography Market Segmentation
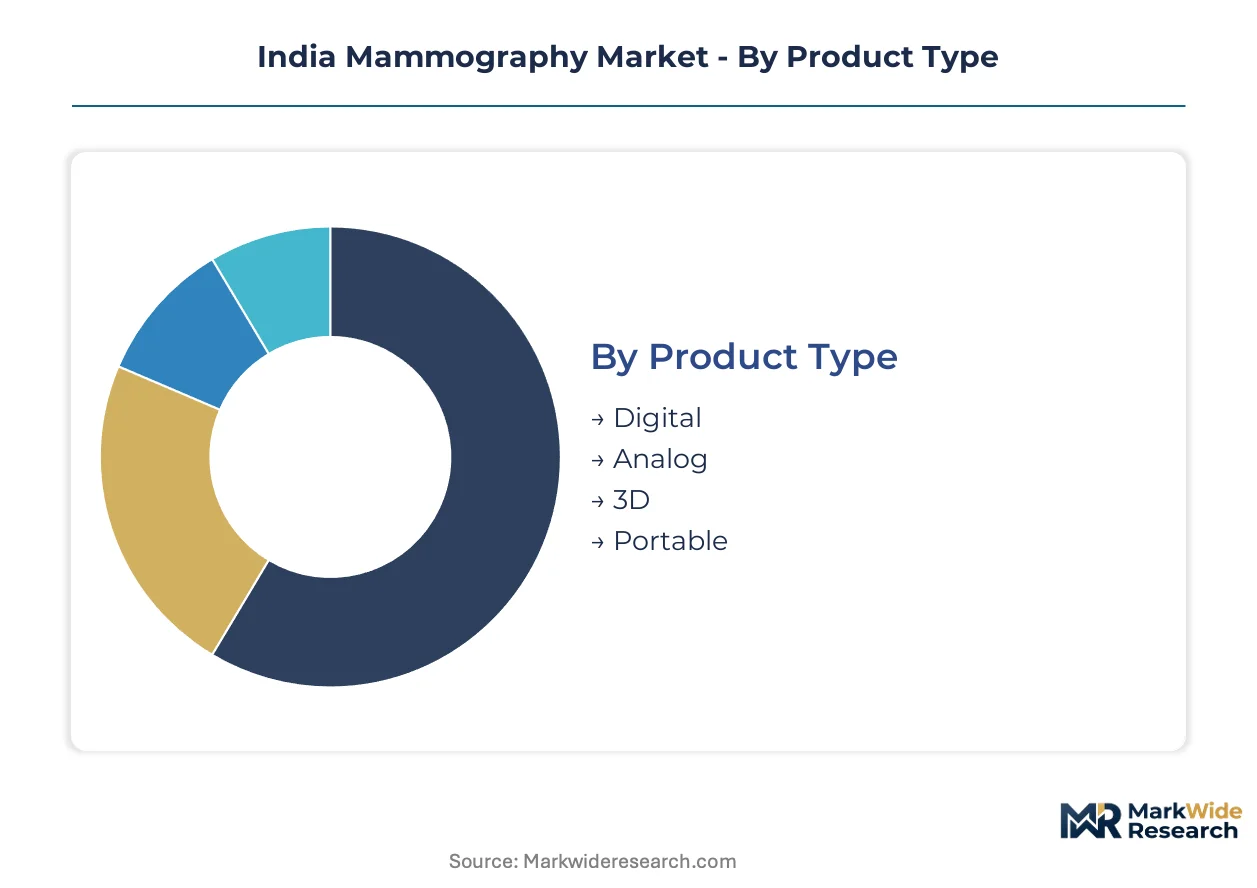
Segmentation in India's mammography market reveals divergent equipment lifecycles and procurement priorities across technology tiers and care settings. Understanding these patterns enables manufacturers to calibrate product portfolios against distinct capital deployment rhythms and reimbursement pathways.
Product Type:
Equipment refresh cycles vary dramatically across this category, with portable systems turning over fastest due to wear-intensive field deployment while fixed installations persist through decade-long amortization schedules.
- Digital:Flat-panel detector systems operating at 25–35 kVp with direct radiography capture dominate Maharashtra and Karnataka hospital procurement. CDSCO-registered digital platforms anchor screening program tenders under Ayushman Bharat expansion.
- 3D:Digital breast tomosynthesis reconstructs multiple slice images from limited-angle X-ray acquisition, collapsing tissue overlap artifacts. Mumbai and Bangalore diagnostic networks are displacing 2D systems at accelerated refresh cycles despite capital premiums.
- Analog:Screen-film cassettes with chemical processing persist in tier-3 public health facilities where digital infrastructure remains incomplete.
- Portable:Battery-powered units with lightweight gantry designs enable camp-based screening in rural districts with limited fixed infrastructure.
Digital systems anchor the volume base while 3D configurations gain share at the steepest rate.
Technology:
Cost stratification across this dimension separates premium reconstructed imaging from commoditized planar capture, with reimbursement differentials reinforcing tiered adoption curves.
- Full-Field Digital:Amorphous selenium or cesium iodide detector arrays enable direct-to-digital capture without intermediate film processing. This technology concentrates in tier-2 city hospital expansion programs where CDSCO registration timelines favor established platforms.
- Tomosynthesis:Limited-angle tomographic acquisition generates 1mm slice reconstructions through filtered back-projection algorithms. Karnataka diagnostic chains are prioritizing tomosynthesis for outpatient referral differentiation despite radiologist interpretation training gaps.
- Screen-Film:Analog cassette systems with molybdenum target tubes and single-emulsion film persist where PACS connectivity remains absent.
- Contrast-Enhanced:Dual-energy subtraction techniques with iodinated contrast administration enable lesion vascularity assessment in diagnostic workup protocols.
Full-field digital systems sustain the broadest installed base while tomosynthesis climbs fastest among metropolitan networks.
End User:
Customer type determines procurement channel structure, with institutional buyers favoring capital purchase against diagnostic center preferences for operational lease structures.
- Diagnostic Centers:Standalone imaging operators in Pune and Hyderabad are adopting per-scan pricing models that transfer technology obsolescence risk to equipment lessors. Capital-light leasing enables outpatient referral capture without full ownership burden.
- Hospitals:Integrated health systems in Maharashtra oncology clusters deploy mammography within comprehensive breast care pathways, prioritizing PACS interoperability and radiologist workflow integration.
- Outpatient Clinics:Limited-service settings concentrate on symptomatic patient triage with basic 2D screening capability.
- Research Institutes:Academic medical centers in Bangalore deploy advanced imaging for clinical trial endpoints and AI training dataset generation.
Hospitals retain the largest equipment footprint while diagnostic centers expand most aggressively through leased asset models.
Application:
Reimbursement mechanics and clinical urgency create divergent utilization intensity across use cases, with screening programs driving volume throughput against diagnostic applications demanding higher resolution specifications.
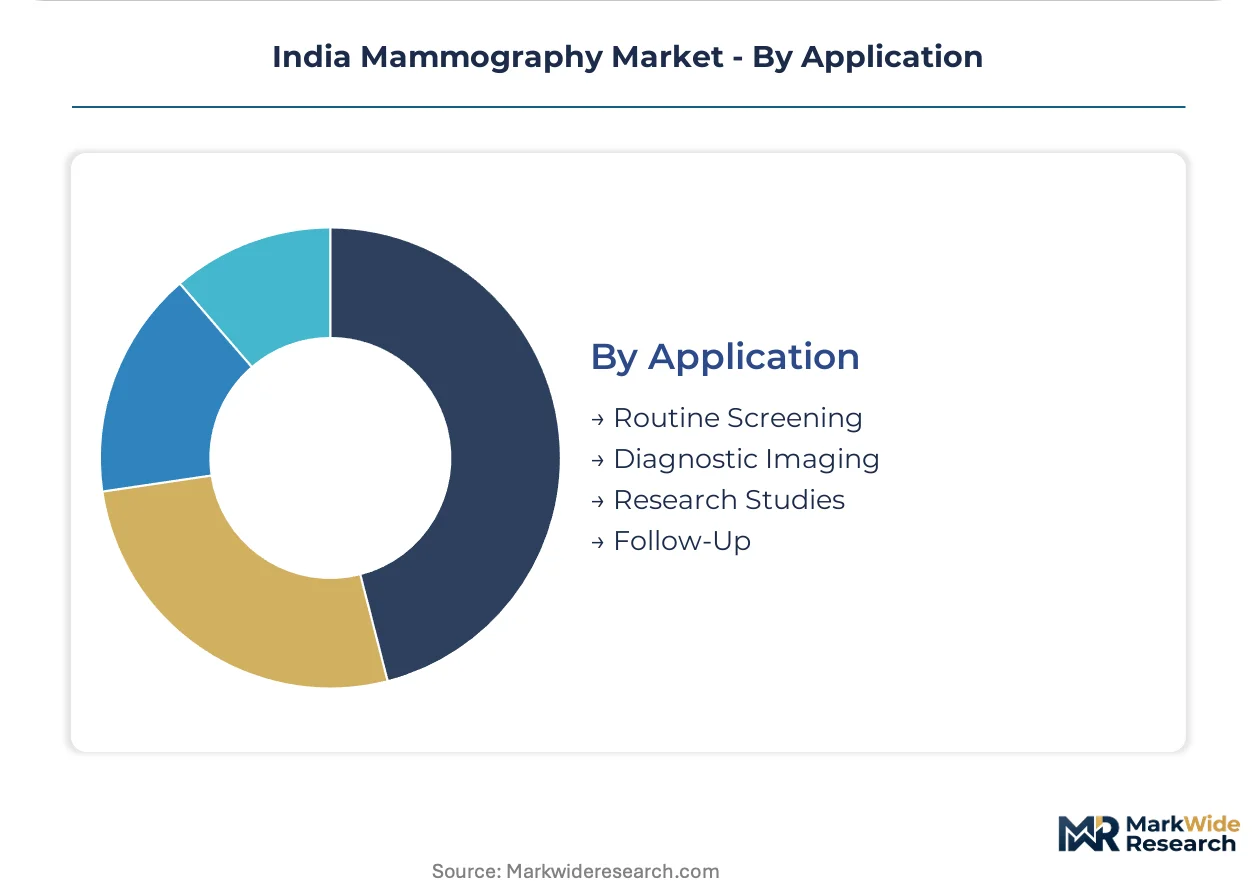
- Routine Screening:Asymptomatic population imaging at 24-month intervals for women 40–69 years constitutes the volume base for public health program tenders. Ayushman Bharat reimbursement expansion is pulling equipment deployment toward tier-2 cities.
- Diagnostic Imaging:Symptomatic workup and callback evaluation requires tomosynthesis or contrast-enhanced protocols with specialized radiologist interpretation. Karnataka's outpatient networks are building dedicated diagnostic mammography capacity separate from screening workflows.
- Follow-Up:Surveillance imaging for post-treatment monitoring and high-risk patient protocols generates recurring revenue streams with lower per-exam reimbursement.
- Research Studies:Clinical trial imaging and AI algorithm validation demands standardized acquisition protocols with comprehensive metadata capture.
Routine screening sustains the highest exam volume while diagnostic imaging commands the steepest technology upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector panel and X-ray tube supply chains concentrate in East Asian manufacturing hubs, exposing Indian procurement to logistics volatility. Maharashtra and Karnataka oncology clusters absorb the majority of domestic equipment deployment. CDSCO registration timelines and BIS certification requirements shape sub-regional commercialization velocity.
Maharashtra
Mumbai and Pune diagnostic networks drive tomosynthesis adoption through accelerated refresh cycles. The Ayushman Bharat scheme expands reimbursement access for screening programs across tier-2 city hospitals. Maharashtra-based manufacturers are forming detector panel sourcing partnerships to capture PLI scheme benefits for local assembly operations.
Karnataka
Bangalore metropolitan imaging networks prioritize 3D mammography for outpatient referral differentiation. CDSCO streamlined Medical Device Rules implementation compresses registration timelines for domestically manufactured components. Karnataka diagnostic chains are adopting per-scan pricing models that transfer technology obsolescence risk to equipment lessors.
Telangana
Hyderabad standalone imaging centers expand through capital-light leasing structures without full ownership burden. The PLI scheme for medical devices incentivizes local production of high-value imaging components. Telangana's outpatient referral networks demonstrate capital efficiency as a competitive survival determinant.
Tamil Nadu
Chennai hospital systems deploy mammography within comprehensive breast care pathways prioritizing PACS interoperability. BIS certification mandates electrical safety and electromagnetic compatibility compliance for domestic manufacture. Tamil Nadu research institutes deploy advanced imaging for clinical trial endpoints and AI training dataset generation.
Delhi-NCR
Public sector facilities in the capital region face PACS integration complexity with legacy hospital information systems requiring costly middleware development. CDSCO governs device registration and import licensing for mammography systems under Medical Device Rules. Delhi-NCR radiologist workforce density gaps limit effective utilization of installed imaging equipment in surrounding tier-3 districts.
India Mammography Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in detector arrays and tube assemblies. The vendor base separates into three strategic archetypes: multinational imaging conglomerates with full modality portfolios, regional assemblers leveraging PLI scheme incentives, and standalone diagnostic operators unbundling ownership from service delivery. Competitive moves concentrate on localized service infrastructure buildout and radiologist training ecosystem anchoring.
Among multinational platform integrators, Hologic Inc., Siemens Healthineers, and GE Healthcare occupy positions representing premium tomosynthesis capability, localized service density, and cost-optimized digital system deployment respectively. Hologic exemplifies the premium-tier archetype through reconstructed slice imaging portfolios. Siemens Healthineers anchors the service-intensive positioning with radiologist training ecosystems. GE Healthcare, through its Wipro GE Healthcare joint structure, represents the cost-optimization pathway for mid-tier hospital procurement cycles.
| Leading Market Players |
|---|
| Hologic Inc. |
| GE Healthcare |
| Siemens Healthineers |
| Wipro GE Healthcare |
| Fujifilm Holdings Corporation |
| Philips Healthcare |
| BPL Medical Technologies |
| Allengers Medical Systems |
| Planmed Oy |
| Others |
Supply & Pricing Matrix
Undercapacity in domestic detector panel assembly is compressing margins for Indian system integrators while amplifying pricing power for East Asian component suppliers serving the mammography market.
Pricing Analysis
CDSCO Medical Device Rules dictate the pricing tier structure across the India mammography landscape. Three-tier pricing structure across premium, standard, and economy levels separates tomosynthesis systems with full service bundling from basic digital units with limited warranty coverage. Cost compression in the standard tier is intensifying because PLI scheme incentives are pulling regional assemblers into detector panel sourcing partnerships. Government hospital procurement committees exhibit the highest price sensitivity, while metropolitan diagnostic chains prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Tariff exposure between India and China dominates supply chain risk calculus for mammography system manufacturers. Detector panel fabrication concentrates in South Korea, Japan, and China, while X-ray tube assemblies draw from German and Japanese precision engineering hubs. Amorphous selenium substrates, cesium iodide scintillators, and molybdenum target materials constitute critical input dependencies. Single-source vulnerability in flat-panel detector arrays threatens procurement continuity. Distribution runs through authorized dealer networks with localized service technician certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India mammography market represents a high-growth disruption as Ayushman Bharat reimbursement expansion converges with PLI scheme manufacturing incentives to restructure equipment ownership economics.
For Market Incumbents: Pre-empt radiologist workforce scarcity by anchoring training ecosystems in Karnataka and Maharashtra oncology clusters. Deepen backward integration into detector panel assembly through Maharashtra-based sourcing partnerships to capture PLI scheme benefits. Counter emerging leasing-model competitors by bundling predictive maintenance software with hardware refresh guarantees. For New Entrants and Emerging Players: Tier-2 city diagnostic centers in Telangana and Tamil Nadu represent the most penetrable entry point for capital-light equipment financing models. Camp-based portable mammography deployment in rural Maharashtra districts offers white-space access with minimal fixed infrastructure requirements. Pursue per-scan pricing partnerships with standalone imaging operators to transfer technology obsolescence risk from end-users. For Investors and Strategic Acquirers: Long-term, this sits as a healthcare infrastructure consolidation play because reimbursement expansion is structurally shifting equipment procurement from capital purchase toward operational lease structures. Acquisition targets should emphasize service technician certification density and radiologist training program scale. Monitor state-level oncology mission tender awards as the inflection signal for geographic deployment momentum.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Streamlining | Compressed approval timelines favor domestic assembly operations over fully-built unit imports. |
| PLI Scheme Component Localization | Detector panel sourcing partnerships reduce import dependency for Indian system integrators. |
| AI-Assisted Interpretation Integration | Machine learning deployment addresses radiologist scarcity in tier-2 and tier-3 districts. |
| Operating Lease Model Expansion | Per-scan pricing transfers technology obsolescence risk from diagnostic centers to lessors. |
| Radiologist Training Ecosystem Buildout | Certification programs in Maharashtra and Karnataka anchor service differentiation for equipment vendors. |
Research Methodology
Cross-validation between hospital procurement database analysis and CDSCO registration filings anchors the qualitative findings in this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and diagnostic center operators combined with secondary validation against BIS certification records, PLI scheme beneficiary disclosures, and state health mission tender documents. Bottom-up equipment installation tracking and top-down reimbursement flow analysis complete the triangulation.
Calibration against historical tender award patterns and refresh cycle documentation shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product technology tier, end-user facility type, application purpose, and state-level infrastructure maturity. CAGRs derive from equipment deployment velocity correlation with reimbursement expansion trajectories. Radiologist workforce density by district and detector panel import volume fluctuations serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates or PLI scheme funding allocation would shift the trajectory. Forecasts reflect documented assumptions regarding Ayushman Bharat geographic rollout pace and CDSCO regulatory processing efficiency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Korea Nuclear Imaging Market
Medical Imaging
South America Mammography Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
Brain PET-MRI Systems Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Mobile Tomography Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Open System MRI Market
Medical Imaging
Germany Nuclear Imaging Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Italy Magnetic Resonance Imaging Market