
 Sleep Disorders Treatment Market | 2026-2036
Sleep Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Sleep Disorders Treatment Market Analytics
The sleep disorders treatment market is rebalancing as premium pharmacologic interventions for narcolepsy and insomnia pull away from commodity continuous positive airway pressure hardware. Jazz Pharmaceuticals differentiates through its narcolepsy franchise and orexin-targeting compounds. ResMed Inc. dominates connected respiratory care with cloud-integrated device platforms. Merck & Co. competes in the insomnia segment with its dual orexin receptor antagonist portfolio.
Sleep disorders treatment encompasses pharmaceutical agents, mechanical devices, behavioral therapies, and nutraceutical formulations designed to correct disrupted sleep architecture and restore restorative sleep cycles. Continuous positive airway pressure machines deliver pressurized air at 4–20 cm H2O to maintain pharyngeal patency in obstructive sleep apnea, while pharmacologic agents modulate GABA, orexin, or histamine pathways to induce or sustain sleep. The pharmaceuticals segment anchors value creation as patent-protected orexin antagonists command pricing power against generic z-drugs. Devices face hardware commoditization, though adaptive servo ventilation and cloud-connected monitoring systems preserve margin pools for manufacturers with installed-base lock-in. Sleep centers and home care channels are diverging in procurement patterns, with hospitals consolidating to volume contracts while direct-to-home channels expand.
FDA oversight of pharmacologic sleep agents through its Division of Psychiatry Products shapes clinical trial endpoints and labeling restrictions that directly determine commercial viability. The EMA's MDR framework and CE marking requirements for sleep apnea devices create divergent compliance burdens across Atlantic markets. Japan's PMDA maintains distinct efficacy standards for insomnia drugs that delay entry for Western developers. Stakeholders must monitor how reimbursement authorities in Germany, France, and the United States classify home sleep testing against in-lab polysomnography, as this boundary will determine where capital flows across the care continuum.
Market Dynamics
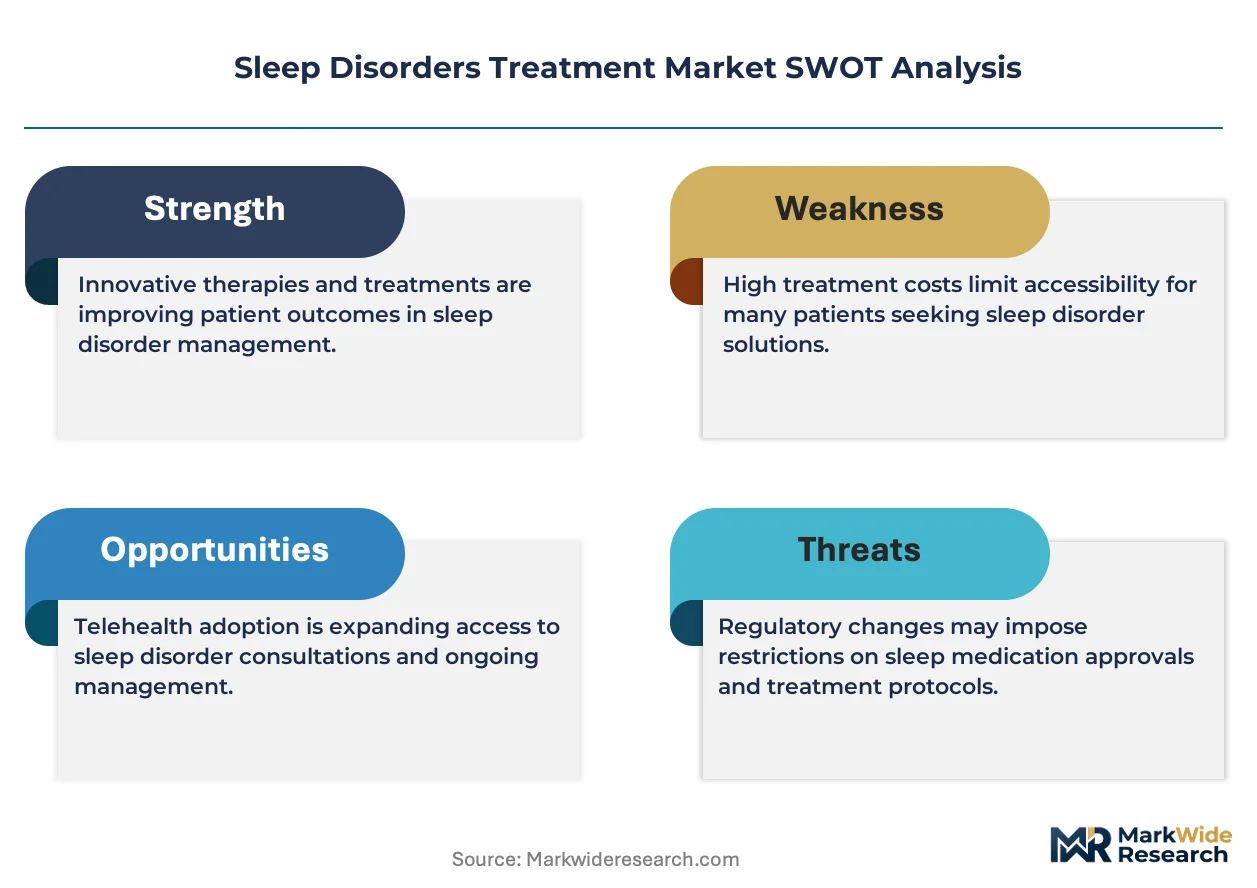
The sleep disorders treatment market is rebalancing around orexin-targeting pharmacology as FDA clearance pathways for dual orexin receptor antagonists redirect R&D investment away from generic sedative-hypnotics toward patent-protected specialty therapeutics.
Growth Catalysts
- Dual orexin receptor antagonist pipeline:Novel compounds targeting wake-promoting neuropeptides are expanding therapeutic options beyond GABA modulation. The FDA Division of Psychiatry Products has established streamlined review pathways for narcolepsy and insomnia indications.
- Home-based sleep apnea therapy reimbursement:Germany's statutory health insurance system and Japan's Ministry of Health, Labour and Welfare have deepened coverage for remote diagnostic monitoring and CPAP titration outside hospital sleep centers.
- Cloud-integrated respiratory platforms:Manufacturers are embedding cellular connectivity into positive airway pressure devices to enable remote adherence monitoring and automated pressure adjustment algorithms.
Market Restraints
- Commoditization of CPAP hardware:Continuous positive airway pressure machines face margin compression as manufacturing concentrates in East Asian contract producers and patent protection expires on core blower motor designs.
- EMA MDR compliance burden:The European Union's Medical Device Regulation imposes stringent clinical evidence requirements on sleep apnea diagnostic equipment, extending time-to-market for novel sensor technologies.
- Behavioral therapy substitution:Cognitive behavioral therapy for insomnia (CBT-I) protocols delivered through digital health applications are displacing pharmacologic first-line treatment in some reimbursement jurisdictions.
Strategic Opportunities
- Underpenetrated narcolepsy diagnosis:France and Italy exhibit significant gaps between estimated disease prevalence and confirmed cases, creating whitespace for specialty pharmaceutical detailing and diagnostic partnerships.
- Adaptive servo-ventilation for central sleep apnea:Algorithm-driven pressure support systems that respond to Cheyne-Stokes respiration patterns represent an emerging application distinct from obstructive sleep apnea protocols.
- Direct-to-consumer distribution channels:Online prescription platforms and telemedicine networks are bypassing traditional sleep center referrals for home sleep testing and CPAP initiation.
Industry Challenges
- Polysomnography technologist shortage:Sleep medicine fellowship programs in the United States and Germany are failing to produce sufficient board-certified interpreters for in-lab diagnostic demand.
- Legacy device interoperability:Cloud platforms from incumbent respiratory device manufacturers use proprietary data formats that resist integration with third-party electronic health record systems and remote monitoring dashboards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleep Disorders Treatment Market |
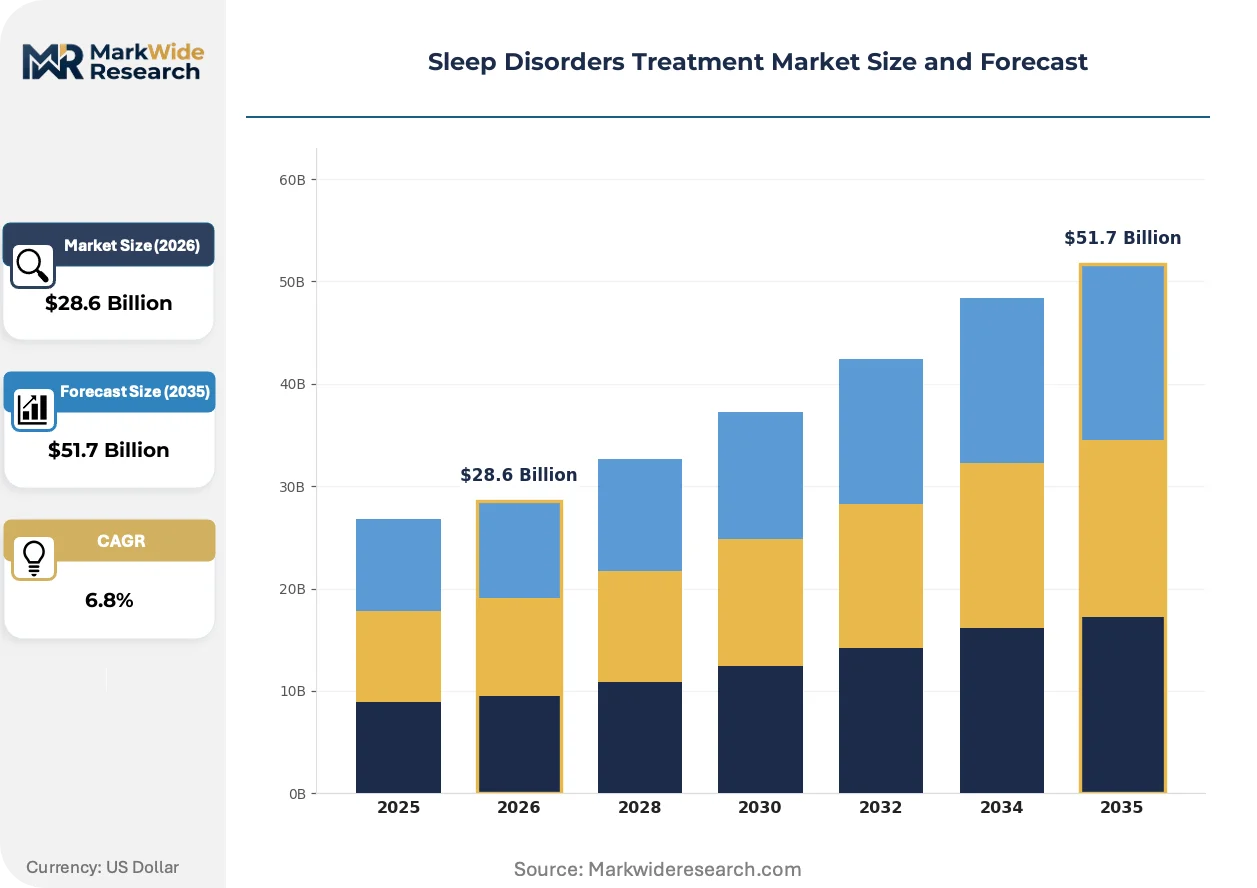
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Devices, Therapies, Nutraceuticals Application: Insomnia, Sleep Apnea, Narcolepsy, Restless Legs Syndrome End User: Hospitals, Clinics, Home Care, Sleep Centers Technology: Continuous Positive Airway Pressure, Bi-level Positive Airway Pressure, Adaptive Servo Ventilation, Sleep Monitoring Devices |
| Companies Covered | Eisai Co., Ltd., Merck & Co., Jazz Pharmaceuticals, Pfizer Inc., ResMed Inc., Idorsia Pharmaceuticals Ltd., Philips Respironics, Fisher & Paykel Healthcare, Harmony Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleep Disorders Treatment Market Evolving Landscape
Pharmaceutical and device segments are diverging in innovation trajectory as orexin science reshapes drug development priorities while hardware manufacturers compete on connectivity ecosystems rather than core therapeutic mechanics.
Artificial intelligence algorithms for automated sleep staging are integrating polysomnography interpretation workflows to reduce scorer burden and standardize diagnostic consistency. Hospital sleep centers in the United States and university medical centers in Germany are piloting FDA-cleared and CE-marked systems for epoch-by-epoch classification. This technology is integrating diagnostic throughput expansion with labor cost containment as reimbursement pressure intensifies on in-lab testing.
The FDA's 2023 guidance on patient-reported outcome measures for insomnia treatments is tightening evidentiary standards for new drug approvals beyond simple sleep latency endpoints. Sponsors must now demonstrate functional improvement metrics that complicate trial design and extend development timelines. The insomnia pharmaceutical segment is responding with adaptive trial designs and real-world evidence collection through wearable-derived sleep architecture data.
Employer-sponsored wellness programs are unbundling sleep health from general medical benefits to address occupational safety and productivity metrics. Large self-insured employers in the United States are contracting directly with home sleep testing vendors and behavioral sleep medicine providers. This procurement evolution is most visible in transportation, manufacturing, and shift-work-intensive industries where fatigue-related incident liability drives investment.
Sleep Disorders Treatment Market Segmentation
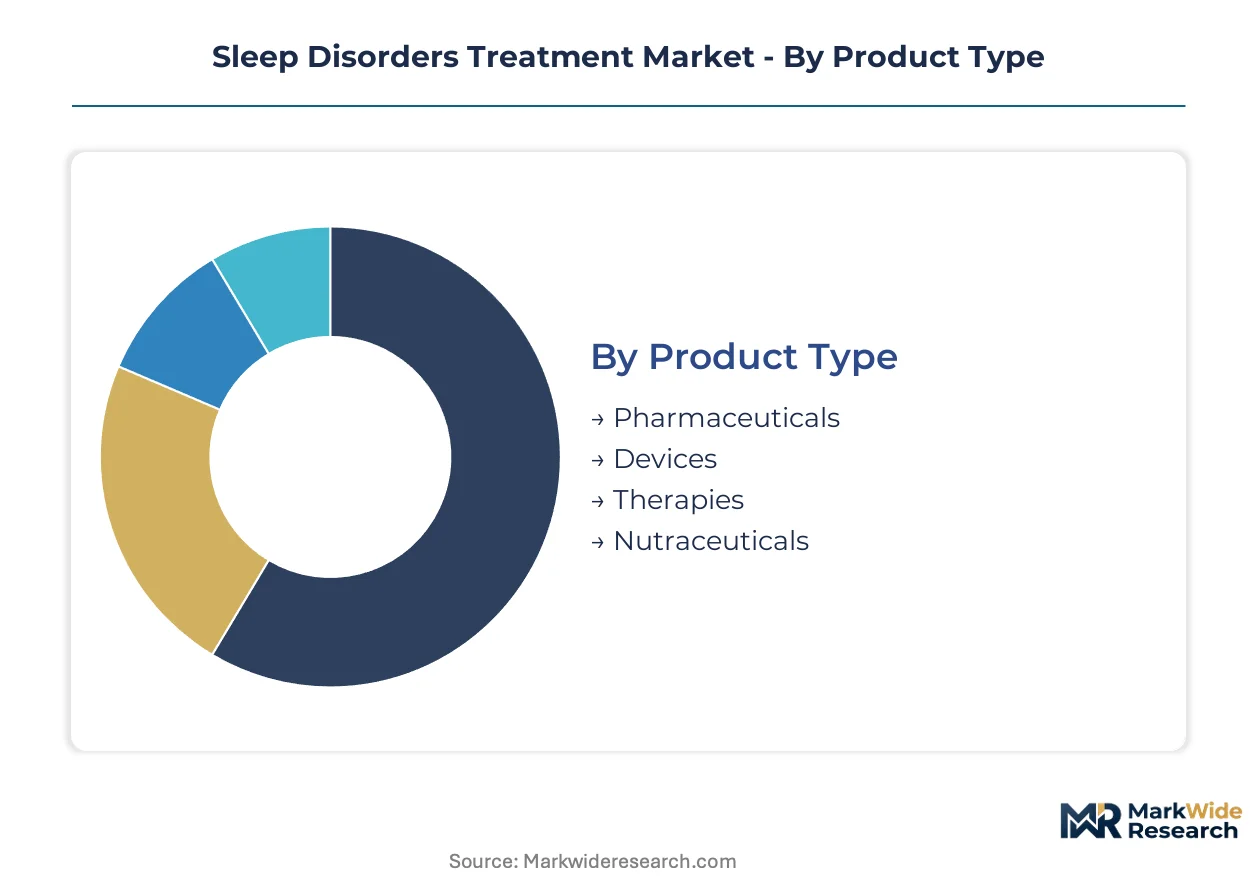
Sleep disorders treatment markets fragment across therapeutic modality and care setting, with pharmaceutical and device segments following divergent margin trajectories. Understanding these boundaries clarifies where pricing power concentrates versus where procurement consolidation erodes returns.
Product Type:
Technology sophistication and patent protection status separate segments with pricing autonomy from those facing commodity pressure.
- Pharmaceuticals:Patent-protected orexin receptor antagonists and GABA modulators command premium positioning against generic z-drugs. Demand concentrates in the United States and Japan where reimbursement frameworks reward novel mechanisms over me-too sedatives.
- Devices:Positive airway pressure hardware and diagnostic sensors face manufacturing scale economics and connectivity integration as primary competitive axes. Germany's statutory insurers and Japan's Ministry of Health, Labour and Welfare are deepening remote monitoring reimbursement, shifting procurement toward cloud-integrated platforms.
- Therapies:Cognitive behavioral protocols for insomnia deliver non-pharmacologic intervention through digital and clinician-guided channels.
- Nutraceuticals:Melatonin and herbal formulations occupy over-the-counter distribution with minimal regulatory oversight.
Mature deployment sits with Pharmaceuticals. Newer deployment is concentrated in Devices as connectivity integration reshapes competitive requirements.
Application:
Prevalence rates and diagnostic penetration gaps create divergent addressable market dynamics across indications.
- Insomnia:Chronic sleep initiation and maintenance disorders affect population-wide cohorts with significant untreated burden. The FDA Division of Psychiatry Products tightened evidentiary standards for new drug approvals, forcing sponsors toward functional outcome metrics beyond simple sleep latency endpoints.
- Sleep Apnea:Obstructive and central variants drive mechanical ventilation device demand with strong adherence monitoring economics. Home-based diagnostic and titration protocols are expanding fastest in Germany and Japan as reimbursement authorities relax in-lab requirements.
- Narcolepsy:Orexin deficiency disorders command specialty pharmaceutical focus with limited generic competition.
- Restless Legs Syndrome:Dopaminergic and alpha-2-delta ligand therapies address sensorimotor disruption with moderate prevalence.
Volume concentration rests with Sleep Apnea. Steepest expansion trajectory belongs to Narcolepsy as orexin science unlocks novel therapeutic targets.
End User:
Procurement authority and patient acuity determine channel-specific product configurations and service bundling requirements.
- Hospitals:Acute care settings manage complex sleep-disordered breathing with intensive monitoring capabilities and specialist oversight.
- Clinics:Outpatient facilities balance diagnostic throughput against reimbursement constraints on in-lab polysomnography.
- Home Care:Direct-to-patient channels bypass traditional sleep center referrals for CPAP initiation and adherence management. Large self-insured employers in the United States are contracting directly with home testing vendors, unbundling sleep health from general medical benefits.
- Sleep Centers:Dedicated diagnostic facilities face technologist shortage pressures in the United States and Germany as fellowship programs fail to produce sufficient board-certified interpreters.
Revenue gravity centers on Sleep Centers. Channel expansion is accelerating fastest in Home Care as telemedicine platforms and online prescription networks disintermediate traditional referral pathways.
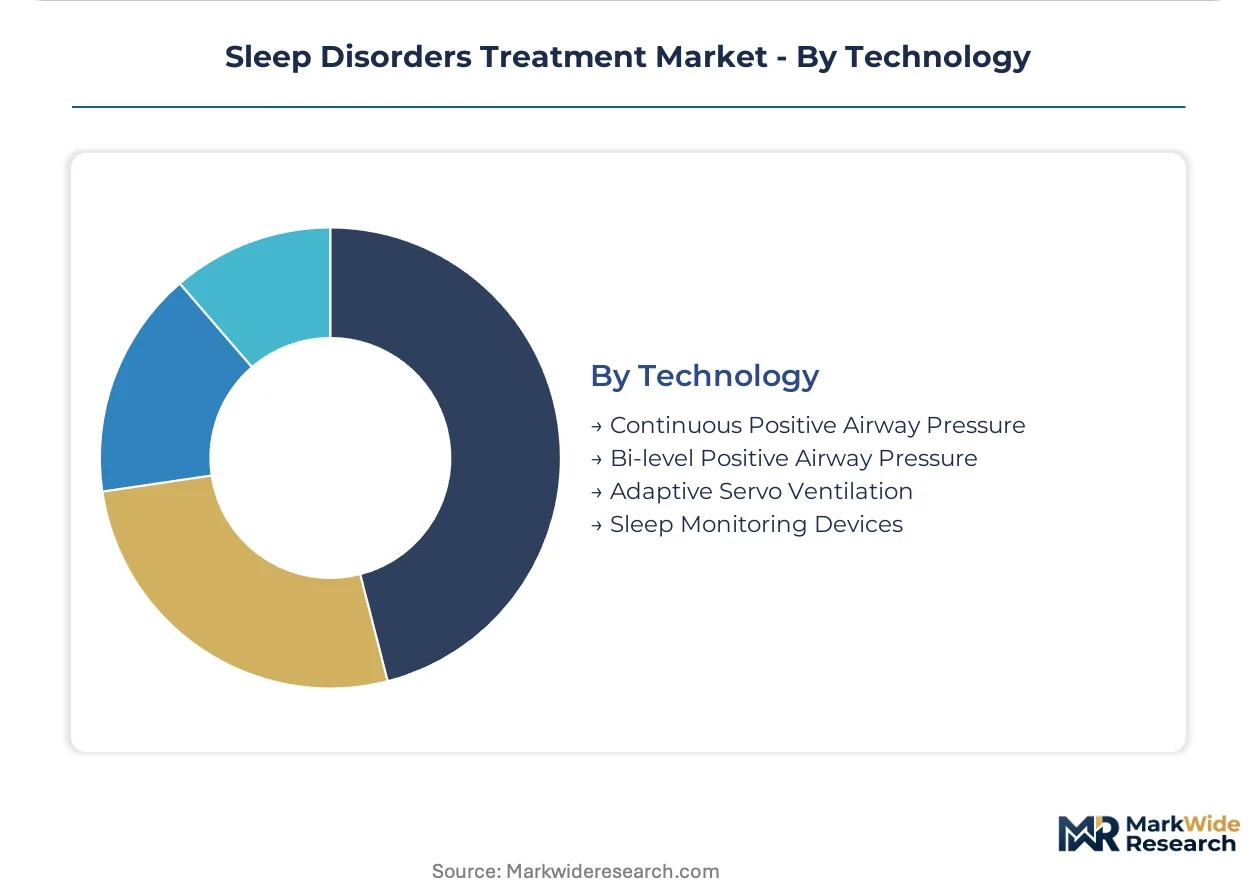
Technology:
Pressure delivery algorithms and sensor integration capabilities differentiate competitive positioning within mechanical ventilation.
- Continuous Positive Airway Pressure:Fixed-pressure devices maintain pharyngeal patency at 4–20 cm H2O with mature manufacturing economics. Cloud-connected platforms with automated adherence reporting are preserving margin pools for manufacturers with installed-base lock-in.
- Bi-level Positive Airway Pressure:Pressure-cycled ventilation assists spontaneous breathing with separate inspiratory and expiratory pressures. Demand concentrates in complex respiratory failure and neuromuscular indications where pressure support requirements vary across the respiratory cycle.
- Adaptive Servo Ventilation:Algorithm-driven systems respond to Cheyne-Stokes respiration patterns in central sleep apnea. The FDA maintains specific labeling restrictions following cardiovascular outcomes data, constraining deployment in heart failure populations.
- Sleep Monitoring Devices:Wearable and bedside sensors capture sleep architecture data for diagnostic and adherence applications. Artificial intelligence algorithms for automated sleep staging are integrating polysomnography interpretation workflows to reduce scorer burden.
Installed base dominance resides with Continuous Positive Airway Pressure. Technology transition is concentrating in Adaptive Servo Ventilation as algorithm sophistication unlocks central sleep apnea applications distinct from obstructive protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors pharmaceutical development for orexin-targeting compounds, while Minneapolis concentrates connected respiratory device manufacturing. Hospital sleep centers in these metros expand diagnostic throughput as reimbursement frameworks shift toward home-based care models.
United States
FDA Division of Psychiatry Products streamlines review pathways for dual orexin receptor antagonists, accelerating narcolepsy and insomnia drug approvals. Large self-insured employers in transportation and manufacturing sectors contract directly with home sleep testing vendors, unbundling sleep health from general medical benefits. The Minneapolis-St. Paul corridor hosts major connected respiratory device manufacturing.
Germany
Statutory health insurance deepens coverage for remote diagnostic monitoring and CPAP titration outside hospital sleep centers. EMA MDR framework imposes stringent clinical evidence requirements on sleep apnea diagnostic equipment, extending time-to-market for novel sensor technologies. University medical centers in Munich and Heidelberg pilot AI-integrated polysomnography interpretation systems.
Japan
Ministry of Health, Labour and Welfare expands reimbursement for home-based sleep apnea therapy and remote adherence monitoring. PMDA maintains distinct efficacy standards for insomnia drugs that delay entry for Western developers. Tokyo and Osaka metropolitan areas concentrate sleep medicine fellowship programs and diagnostic facility networks.
United Kingdom
NHS England evaluates digital cognitive behavioral therapy for insomnia protocols as first-line alternatives to pharmacologic treatment. MHRA aligns with FDA evidentiary standards for patient-reported outcome measures in insomnia drug trials. London's academic medical centers drive adoption of automated sleep staging algorithms for diagnostic throughput expansion.
France
ANSM oversees pharmacovigilance for orexin-targeting therapeutics while CNIL governs data protection for cloud-connected sleep monitoring platforms. Significant gaps between estimated narcolepsy prevalence and confirmed cases create whitespace for specialty pharmaceutical detailing. Paris and Lyon hospital networks consolidate sleep center procurement to volume contracts.
Sleep Disorders Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across patent protection status and connectivity integration depth. The market structures around three tiers: specialty pharmaceutical developers with orexin science portfolios, connected respiratory device manufacturers with cloud platform lock-in, and generic hardware producers facing manufacturing scale economics. Two dominant competitive moves are reshaping positioning: strategic partnerships between diagnostic platforms and telemedicine networks, and portfolio diversification into behavioral sleep medicine applications.
Within the specialty pharmaceutical tier, Jazz Pharmaceuticals and Merck & Co. exemplify patent-protected orexin-targeting development. ResMed Inc. anchors the connected respiratory device segment. These three companies represent divergent margin architectures—pharmaceutical patent cliffs versus device installed-base economics—while collectively illustrating how regulatory clearance pathways determine competitive positioning across the sleep disorders treatment landscape.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Merck & Co. |
| Jazz Pharmaceuticals |
| Pfizer Inc. |
| ResMed Inc. |
| Idorsia Pharmaceuticals Ltd. |
| Philips Respironics |
| Fisher & Paykel Healthcare |
| Harmony Biosciences |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up sleep center networks in the United States and Germany are consolidating procurement authority, translating volume concentration into pricing discipline that squeezes margins for standalone CPAP manufacturers while rewarding cloud-integrated platform vendors with multi-year service contracts.
Pricing Analysis
Outcome-based pricing anchored to adherence metrics and clinical efficacy endpoints now governs reimbursement contracts for dual orexin receptor antagonists in the United States and Japan. Pricing stratifies across patent-protected orexin-targeting compounds, generic z-drugs, and over-the-counter melatonin formulations based on FDA clearance tier and mechanism novelty. Cost compression in CPAP hardware intensifies as East Asian contract manufacturers scale blower motor production. Hospital sleep centers exhibit lowest price sensitivity due to bundled diagnostic service economics, while direct-to-consumer channels face acute pressure from online prescription platform price transparency.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese contract manufacturers for CPAP blower motors and Chinese API producers for GABA-modulating sedative-hypnotic active pharmaceutical ingredients. Component sourcing draws from Germany for precision pressure sensors, Japan for miniaturized flow generators, and Malaysia for final device assembly. Tariff exposure on Chinese-manufactured electronic components threatens margin stability for respiratory device OEMs. Distribution runs through hospital procurement consortia and direct-to-home telemedicine platforms with diverging service bundling requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around orexin pharmacology and cloud-connected respiratory platforms, with EMA MDR compliance costs and FDA evidentiary standard tightening forcing subscale device manufacturers and generic sedative developers toward exit or acquisition.
For Market Incumbents: To counter behavioral therapy substitution and digital CBT-I platform encroachment, pharmaceutical incumbents should deepen vertical integration into diagnostic partnerships that identify treatment-naïve insomnia patients before non-pharmacologic intervention. Device incumbents must embed proprietary adherence algorithms that resist interoperability with third-party remote monitoring dashboards, preserving installed-base lock-in against cloud-platform challengers. For New Entrants and Emerging Players: Enter via underdiagnosed narcolepsy populations in France and Italy where confirmed case gaps exceed fifty percent of estimated prevalence, enabling specialty pharmaceutical detailing without incumbent formulary defense. Target adaptive servo-ventilation for central sleep apnea in heart failure populations where FDA labeling restrictions have constrained legacy player deployment, creating whitespace for algorithm-differentiated entrants. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap CPAP manufacturers with CE marking progress but stalled EMA MDR certification in Germany, where statutory insurer volume contracts await compliant device availability. The signal to watch is PMDA insomnia drug approval velocity for Western developers, which would indicate regulatory pathway convergence and unlock Japan market entry premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Orexin Receptor Antagonist FDA Submission | Streamlined Division of Psychiatry Products review accelerates narcolepsy and insomnia indication timelines. |
| Cloud Platform Integration Partnership | ResMed and Philips cellular connectivity ecosystems capture remote adherence monitoring reimbursement expansion. |
| Diagnostic-Therapeutic Vertical Integration | Sleep center acquisition enables patient capture before competitor formulary or device placement. |
| EMA MDR Certification Investment | CE marking compliance unlocks German statutory insurance volume contracting for novel sensor technologies. |
| Direct-to-Consumer Channel Launch | Telemedicine prescription networks bypass traditional sleep center referral bottlenecks in United States employer contracts. |
Research Methodology
Independent corroboration across FDA Division of Psychiatry Products filings, EMA MDR certification databases, and Japan PMDA submission records underwrites the qualitative findings. Primary interviews with sleep medicine fellowship directors, hospital GPO contracts managers, respiratory device biomedical engineers, and statutory health insurance formulary directors combined with secondary validation from ClinicalTrials.gov, CMS Medicare reimbursement schedules, and German G-BA benefit assessment documents. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window separated volume expansion from price-mix effects in orexin-targeting pharmacology and connected respiratory devices. Segmentation dimensions modeled include therapeutic modality, care setting, pressure delivery technology, and regional regulatory cluster. CAGRs derived from indication-specific prevalence growth, diagnostic penetration trajectories, and reimbursement depth indices. Forecast inputs incorporated PMDA insomnia drug approval lag assumptions and EMA MDR transition timelines for sleep apnea diagnostic equipment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA orexin antagonist safety signal emergence or major statutory insurer behavioral therapy first-line mandate adoption. Deviation in German home sleep testing reimbursement classification would shift capital allocation between hospital sleep center and direct-to-home channels materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Sleep Disorder Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Short Sleep Syndrome Treatment Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Chronotherapy Market
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Anti-Snoring Treatment Market
Sleep Medicine
Home Sleep Screening Devices Market
Sleep Medicine
Europe Insomnia Market
Sleep Medicine
Global Sleep Aids Market
Sleep Medicine
Sleep Screening Devices Market