
 France Digital X-Ray Devices Market | 2026-2036
France Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
France Digital X-Ray Devices Market Foresight
Aftermarket service revenue is reshaping margin distribution across the France digital x-ray landscape. Siemens Healthineers leverages its extensive installed base to sustain recurring service contracts throughout French hospital networks. GE Healthcare anchors its position through deep integration with radiology information systems deployed in major university hospitals.
France digital x-ray devices are electronic imaging systems that convert x-ray photons into digital signals using flat panel detectors or computed radiography plates, typically achieving spatial resolution between 100-200 micrometers for diagnostic clarity. These systems eliminate chemical processing, enabling immediate image review and PACS integration for clinical workflows. Digital radiography systems command the dominant product share as French facilities prioritize room-based installations with wireless detector mobility, while handheld x-ray devices represent the fastest-expanding category driven by point-of-care adoption in emergency departments and intensive care units. Direct radiography technology leads the technology split due to superior dose efficiency and faster acquisition speeds that align with France's radioprotection optimization requirements.
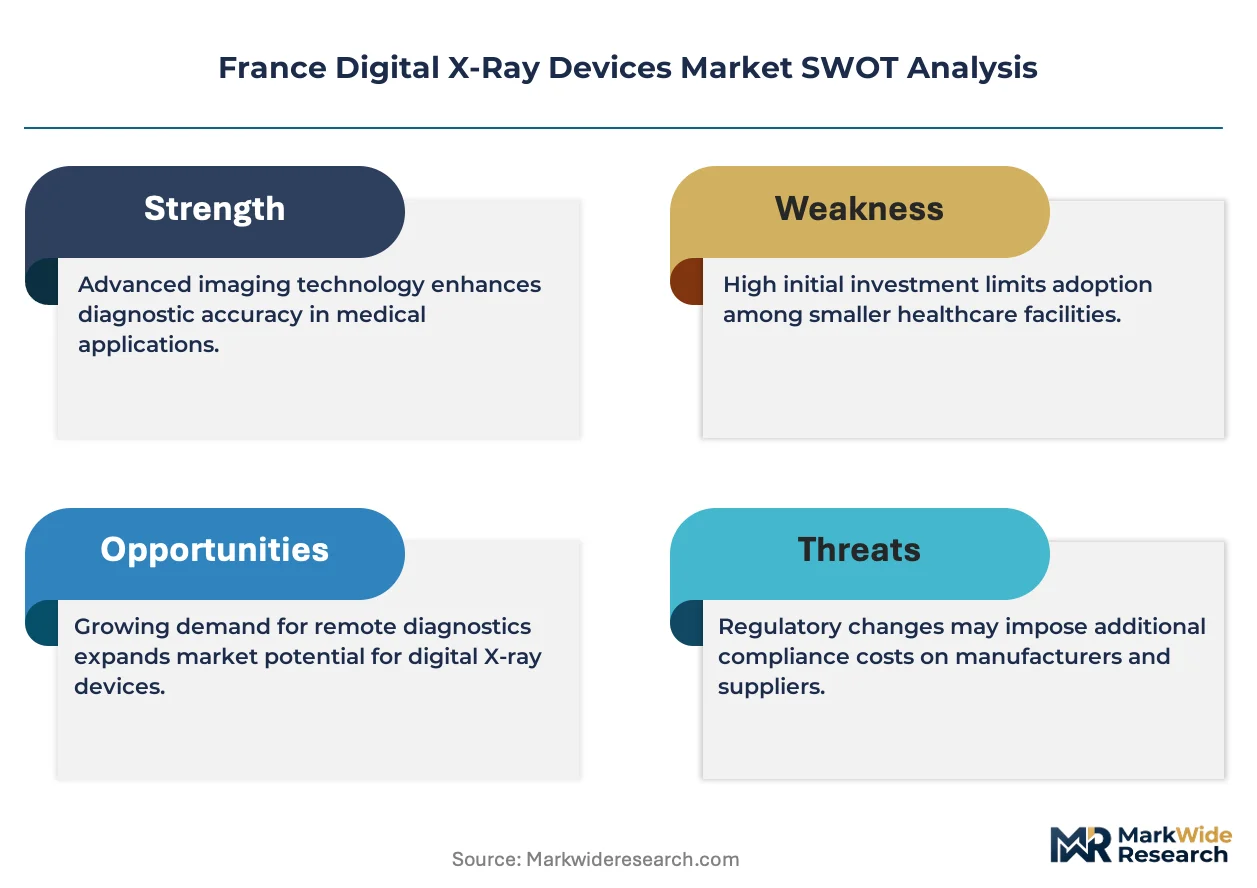
ANSM oversees medical device market authorization and post-market surveillance for digital x-ray equipment distributed in France, enforcing conformity with MDR requirements that elevate clinical evidence standards for new system approvals. HAS accreditation criteria and IRSN dose reference levels shape hospital procurement specifications, pushing vendors toward ALARA-compliant detector sensitivity and automated exposure control. Stakeholders must monitor how France's accelerated hospital digitalization fund redirects capital toward integrated imaging platforms versus standalone x-ray replacements.
Market Dynamics
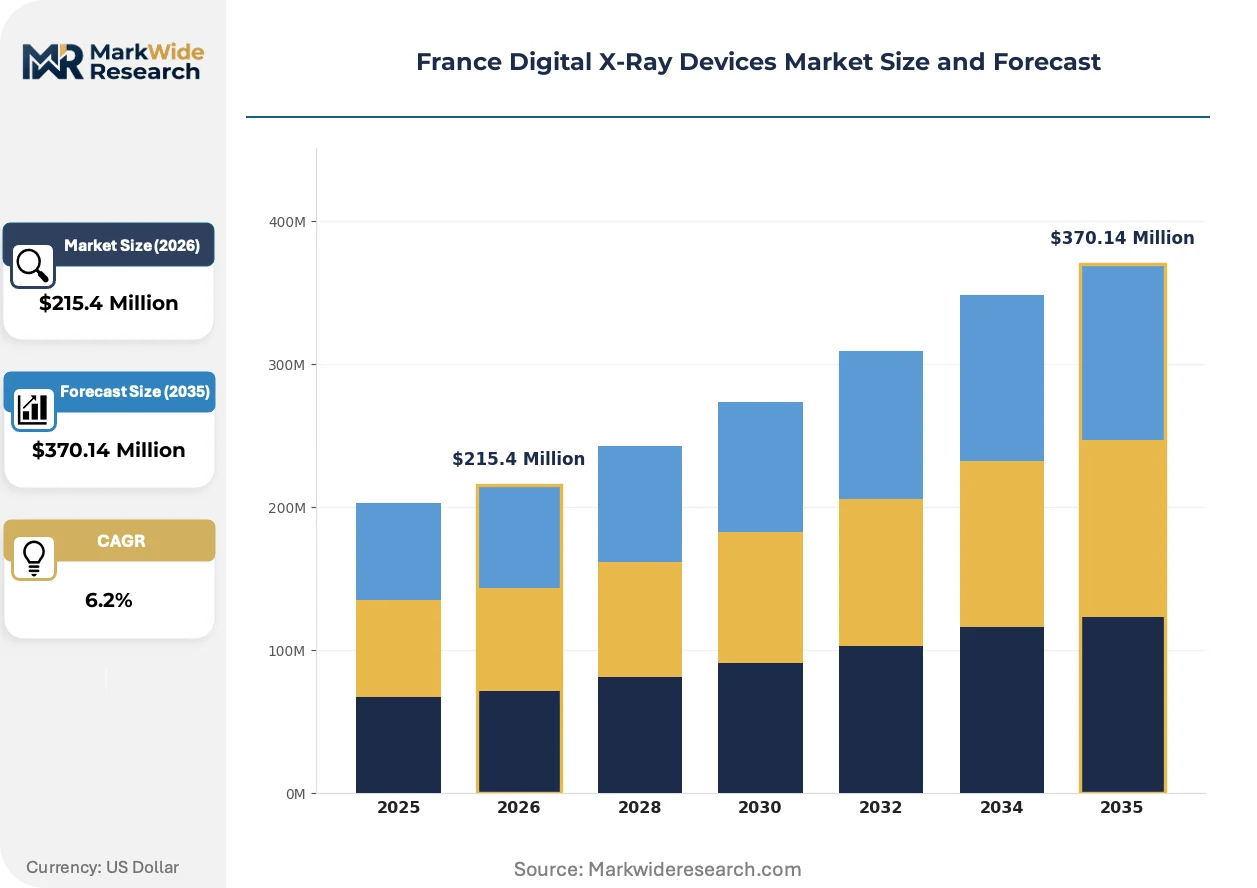
France's hospital digitalization fund is compressing replacement cycles for aging analog x-ray infrastructure, forcing capital allocation decisions between standalone system upgrades and integrated imaging platform investments across public healthcare networks.
Growth Catalysts
- HAS Accreditation Mandates:France's national health authority enforces equipment renewal timelines through hospital accreditation standards, creating mandatory replacement demand for compliant digital radiography systems.
- Île-de-France Procurement Concentration:Paris-area teaching hospitals drive premium system volume, with radiology departments in this region accounting for disproportionate procurement of wireless detector mobility configurations.
- ALARA Compliance Requirements:IRSN dose reference levels push facilities toward direct radiography technology with superior dose efficiency, accelerating detector sensitivity upgrades.
Market Restraints
- Flat Panel Detector Supply Concentration:Manufacturing of amorphous silicon and cesium iodide scintillator components concentrates among Asian suppliers, exposing French OEMs to input volatility and extended lead times.
- MDR Clinical Evidence Burden:EU Medical Device Regulation elevates conformity assessment requirements for new digital x-ray approvals, extending time-to-market for system innovations.
- Computed Radiography Substitution Pressure:Legacy CR plate systems in smaller French clinics face displacement by DR technology, stranding intermediate investments and complicating upgrade sequencing.
Strategic Opportunities
- Point-of-Care Handheld Expansion:Emergency departments and intensive care units across French university hospitals represent underpenetrated demand for battery-powered mobile x-ray units with wireless image transmission.
- PACS-RIS Convergence:Deep integration between digital radiography hardware and radiology information systems creates vendor lock-in potential for comprehensive workflow platforms.
- Occitania Regional Investment:France's territorial hospital group restructuring in southern regions opens procurement windows for consolidated imaging fleet standardization.
Industry Challenges
- Medical Physics Specialist Scarcity:Qualified radioprotection competence for ALARA protocol implementation and dose optimization remains concentrated in major urban centers, limiting deployment in peripheral facilities.
- Legacy Analog Integration Friction:Hybrid workflows combining remaining film-based systems with digital infrastructure create operational complexity during transition periods.
- ANSM Post-Market Surveillance Burden:Vigilance reporting requirements for detector malfunction incidents demand dedicated quality management resources from distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Digital X-Ray Devices Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $370.14 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography Systems, Digital Radiography Systems, Handheld X-Ray Devices, Portable X-Ray Units Technology: Direct Radiography, Indirect Radiography, Charge-Coupled Device, Complementary Metal-Oxide Semiconductor, Amorphous Silicon Application: Orthopedics, Dentistry, Veterinary Imaging, Emergency Medicine, Cardiology End User: Diagnostic Centers, Specialty Clinics, Imaging Centers, Medical Laboratories, Mobile Radiology Units |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Fujifilm Holdings Corporation, Siemens Healthineers, Canon Medical Systems, Carestream Health, Shimadzu Corporation, Agfa Healthcare, Thales Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Digital X-Ray Devices Market Shifts & Advancements
Artificial intelligence inference engines are embedding directly into detector electronics, compressing workflow steps from image acquisition to diagnostic-ready output while reshaping service contract value propositions across French hospital procurement.
Dual-energy subtraction software is virtualizing the hardware differentiation between premium and standard digital radiography configurations, allowing mid-tier detector platforms to deliver spectral imaging capabilities previously requiring dedicated systems. Regional hospital groups in Auvergne-Rhône-Alpes are piloting these software-defined upgrades to extend fleet utility without full replacement capital outlay. This virtualization is compressing the premium pricing window for hardware-differentiated spectral systems.
France's transposition of EU AI Act requirements into national medical device guidance is mandating conformity assessments for machine learning-enabled diagnostic assistance features embedded in x-ray workstations. Manufacturers must document algorithm training data provenance and performance validation across French patient demographics. Radiology departments in Strasbourg and Lyon university hospitals are prioritizing vendors with completed AI Act technical documentation.
Aftermarket service unbundling is fragmenting traditional full-service contracts into component offerings—detector warranty extensions, software maintenance, and remote technical support purchased separately. Independent service organizations are capturing detector recalibration and replacement business from OEM captive service arms. This shift is most pronounced in Provence-Alpes-Côte d'Azur, where hospital purchasing cooperatives negotiate modular service agreements to optimize lifecycle cost visibility.
France Digital X-Ray Devices Market Segmentation
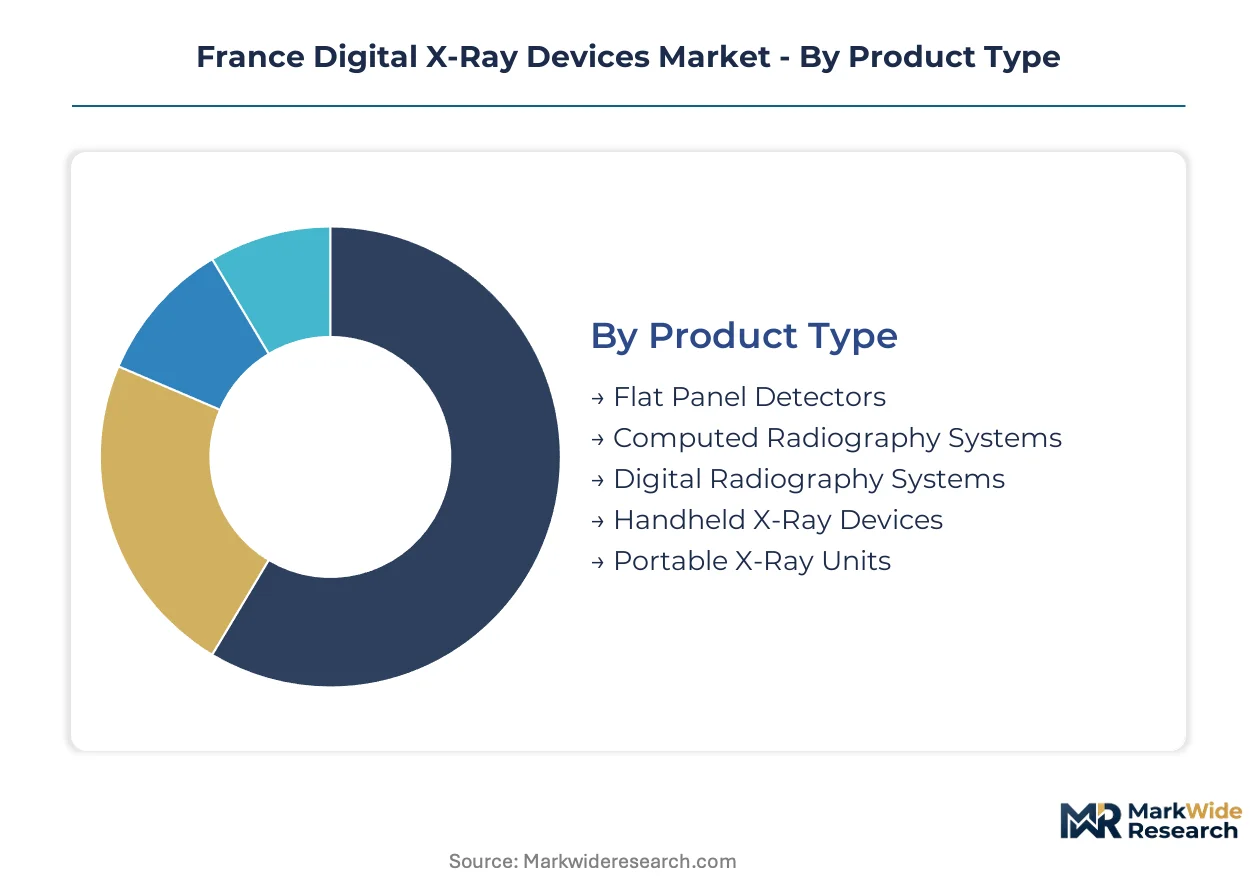
Segmentation reveals how procurement patterns fragment across French healthcare infrastructure. Equipment specifications diverge sharply between high-throughput hospital radiology departments and distributed point-of-care settings, with service contract structures varying accordingly.
Product Type:
After-sales service intensity varies dramatically across product categories, with detector-based systems generating recurring calibration and replacement revenue while portable units demand field repair networks.
- Digital Radiography Systems:Room-based installations with ceiling-suspended or floor-mounted tube stands dominate hospital radiology departments in Île-de-France. Paris-area teaching hospitals prioritize wireless detector mobility configurations to maximize room utilization.
- Handheld X-Ray Devices:Battery-powered mobile units with wireless image transmission are expanding most quickly across emergency departments and intensive care units. French university hospitals in Lyon and Marseille drive procurement for point-of-care imaging.
- Flat Panel Detectors:Amorphous silicon and cesium iodide scintillator components form the core imaging sensor in premium DR installations.
- Computed Radiography Systems:Legacy CR plate readers persist in smaller French clinics facing capital constraints on full DR conversion.
- Portable X-Ray Units:Wheeled systems with integrated generators serve mobile radiography needs in nursing homes and remote facilities.
Digital radiography systems hold the largest share; momentum sits with handheld x-ray devices.
Technology:
Detector technology choices directly determine dose efficiency performance against IRSN reference levels, with material science differentiation driving procurement decisions in radiation-sensitive pediatric and maternity applications.
- Direct Radiography:Selenium-based photoconductive detectors convert x-ray photons directly to electrical charge without intermediate light conversion. French facilities prioritize this technology for ALARA compliance in high-volume screening programs.
- Indirect Radiography:Scintillator-coupled sensors using cesium iodide or gadolinium oxysulfide dominate cost-sensitive installations. Regional hospital groups in Auvergne-Rhône-Alpes standardize on these platforms for fleet uniformity.
- Amorphous Silicon:Thin-film transistor backplanes form the readout layer in most flat panel detector architectures.
- Charge-Coupled Device:Legacy sensor technology persists in specialized dental and veterinary imaging equipment.
- Complementary Metal-Oxide Semiconductor:CMOS active pixel sensors enable faster readout speeds for fluoroscopy-integrated systems.
Direct radiography commands the dominant technology position; indirect radiography retains substantial installed base protection.
Application:
Clinical application determines detector resolution requirements and examination protocol complexity, with orthopedic and emergency applications driving divergent mobility specifications.
- Orthopedics:Long-length imaging for scoliosis assessment and trauma alignment studies demands large-format detectors. French rehabilitation centers prioritize weight-bearing extremity capabilities.
- Emergency Medicine:Rapid acquisition protocols with automated exposure control support high-throughput trauma bays. HAS accreditation mandates push university hospital emergency departments toward DR standardization.
- Dentistry:Intraoral sensors and panoramic units serve private dental practices across French urban centers.
- Cardiology:Specialized chest units with high temporal resolution support cardiac silhouette assessment.
- Veterinary Imaging:Modified human systems with specialized positioning tables address companion animal and equine practices.
Orthopedics generates the highest equipment utilization; emergency medicine is climbing the fastest.
End User:
End-user category shapes capital availability and procurement centralization, with public hospital networks operating under HAS-directed renewal timelines while private imaging centers optimize throughput economics.
- Diagnostic Centers:High-volume outpatient facilities in Île-de-France operate multiple digital radiography rooms with centralized PACS infrastructure. These centers negotiate fleet-wide service agreements with major OEMs.
- Imaging Centers:Specialized radiology practices focus on musculoskeletal and chest imaging with premium detector specifications. Occitania regional restructuring is consolidating purchasing for these facilities.
- Specialty Clinics:Orthopedic and sports medicine practices deploy compact DR systems with limited room modifications.
- Medical Laboratories:Chest screening and occupational health examinations drive equipment selection.
- Mobile Radiology Units:Truck-mounted or van-based systems serve nursing homes and remote communities in peripheral French departments.
Diagnostic centers represent the largest installed base; mobile radiology units show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Île-de-France consumes digital x-ray systems differently from other French regions, prioritizing wireless detector mobility and premium spectral capabilities over cost-optimized configurations favored elsewhere. This consumption-mix differential concentrates procurement volume in Paris-area teaching hospitals while peripheral regions emphasize fleet standardization and extended equipment lifecycles.
Île-de-France
Paris-area teaching hospitals drive premium system procurement for wireless detector mobility configurations. HAS accreditation standards enforce equipment renewal timelines across public hospital networks in this region. Radiology departments at AP-HP facilities concentrate demand for high-throughput digital radiography rooms.
Auvergne-Rhône-Alpes
Regional hospital groups in this southeastern cluster standardize on indirect radiography platforms for fleet uniformity across consolidated purchasing. The hospital digitalization fund redirects capital toward integrated imaging platforms in Lyon university hospitals. Medical physics specialists concentrate in Grenoble and Saint-Étienne to support ALARA protocol implementation.
Provence-Alpes-Côte d'Azur
Hospital purchasing cooperatives negotiate modular service agreements to optimize lifecycle cost visibility for detector recalibration. ANSM post-market surveillance requirements shape quality management resource allocation among distributors. Marseille university hospitals drive point-of-care handheld x-ray procurement for emergency department imaging.
Occitanie
Territorial hospital group restructuring opens procurement windows for consolidated imaging fleet standardization across southern facilities. IRSN dose reference levels push facilities toward direct radiography technology with superior dose efficiency. Toulouse-area teaching hospitals anchor demand for pediatric-optimized detector sensitivity configurations.
Hauts-de-France
Legacy computed radiography systems in smaller clinics face displacement pressure as regional health agencies prioritize full DR conversion. Medical physics specialist scarcity limits ALARA deployment in peripheral facilities across this northern region. Lille university hospitals concentrate expertise for hybrid workflow management during analog-to-digital transitions.
France Digital X-Ray Devices Market Competitive Landscape
Capability concentration sits with premium-tier OEMs commanding detector material science and AI-embedded electronics; scale advantage sits with diversified health technology conglomerates leveraging installed base density for recurring service revenue. The vendor base stratifies across three archetypes: full-platform integrators with PACS-RIS convergence capabilities, detector technology specialists supplying component subsystems, and point-of-care mobility innovators. Dominant competitive moves include aftermarket service unbundling into modular component offerings and strategic partnerships for AI inference engine integration.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions anchored by extensive installed bases across French hospital networks. Within the detector technology tier, Thales Group exemplifies component subsystem supply concentration. These three companies represent the competitive structure's anchor points: conglomerate-scale service leverage versus specialized sensor engineering capability.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Fujifilm Holdings Corporation |
| Siemens Healthineers |
| Canon Medical Systems |
| Carestream Health |
| Shimadzu Corporation |
| Agfa Healthcare |
| Thales Group |
| Others |
Supply & Pricing Matrix
Flat panel detector supply concentration among Asian component manufacturers exposes French OEMs to input volatility that compresses both premium-tier pricing spreads and procurement flexibility across hospital networks. This single-source dependency for amorphous silicon backplanes and cesium iodide scintillators forces pricing discipline on mid-tier configurations while extending lead times for wireless detector mobility upgrades.
Pricing Analysis
Long-term service contracts dominate French hospital procurement, with full-platform vendors bundling detector warranty extensions, software maintenance, and remote technical support into multi-year agreements. Price differentiation stems from AI-embedded electronics tier and PACS-RIS integration depth, with university hospitals least sensitive to premium positioning. Cost compression in standard DR configurations is intensifying as regional hospital groups consolidate purchasing volume, while emergency departments demonstrate highest price sensitivity for point-of-care handheld units.
Supply Chain Analysis
Upstream feedstock for selenium-based photoconductive layers and thin-film transistor backplanes draws from Japan, South Korea, and Taiwan manufacturing clusters. Raw material dependencies center on high-purity selenium, indium tin oxide substrates, and rare-earth phosphor compounds. Single-source vulnerability for amorphous silicon deposition equipment creates procurement chokepoints for detector scaling. Distribution runs through authorized French distributors with ANSM quality management certification, feeding directly into AP-HP and regional hospital group procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated regional hospital groups in France, as territorial restructuring concentrates procurement volume across fewer decision-making entities with standardized fleet requirements.
For Market Incumbents: Entrench position through captive detector recalibration services and AI inference engine integration that deepens PACS-RIS workflow lock-in. Threats from independent service organizations capturing modular maintenance contracts demand defensive moves into software-defined spectral imaging upgrades. Priority lever: backward integration into detector refurbishment capabilities within French borders to shorten replacement cycles and capture stranded CR system displacement revenue. For New Entrants and Emerging Players: Mid-market specialty clinics in Hauts-de-France and peripheral Occitanie departments represent the most penetrable entry point for compact DR systems with limited room modification requirements. Handheld x-ray white space in Marseille and Lyon intensive care units offers second-mover opportunity through battery-powered wireless units with simplified go-to-market via hospital purchasing cooperatives rather than direct OEM sales forces. For Investors and Strategic Acquirers: France's transposition of EU AI Act requirements into national medical device guidance reshapes the acquisition landscape toward vendors with completed technical documentation for machine learning-enabled diagnostic features. Five-to-ten year viability favors detector technology specialists with material science differentiation and established ANSM post-market surveillance infrastructure. Signal to watch: acceleration of hospital digitalization fund allocations toward integrated imaging platforms versus standalone x-ray replacements.| Strategic Initiative | Industry Significance |
|---|---|
| AI Inference Engine Integration | Embedding diagnostic assistance directly into detector electronics compresses workflow steps for French radiology departments. |
| Service Contract Unbundling | Modular offerings for detector warranty and software maintenance optimize lifecycle cost visibility for hospital purchasing cooperatives. |
| Dual-Energy Subtraction Software | Virtualization extends fleet utility across Auvergne-Rhône-Alpes regional hospital groups without full replacement capital outlay. |
| Point-of-Care Handheld Expansion | Battery-powered mobile units with wireless transmission address underpenetrated demand in Lyon and Marseille emergency departments. |
| PACS-RIS Convergence Deepening | Workflow platform integration creates vendor lock-in potential across Île-de-France teaching hospital networks. |
Research Methodology
A standing panel of hospital biomedical engineers, GPO contracts managers, radiology department heads, and ANSM regulatory affairs specialists provided ongoing calibration throughout the research process. Primary interviews with French healthcare procurement committees and detector technology suppliers combined with secondary validation from hospital procurement databases, GPO contract filings, HAS accreditation records, and ANSM vigilance reports. Bottom-up equipment unit economics and top-down healthcare expenditure flows were triangulated to establish market sizing boundaries.
Scenario-bracketing around hospital digitalization fund allocation trajectories and MDR conformity assessment timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, detector technology, clinical application, and end-user category with regional procurement concentration patterns. CAGRs were derived from installed base replacement cycles, HAS-directed renewal timelines, and point-of-care adoption curves for handheld mobility configurations.
Practitioners should monitor ANSM post-market surveillance burden expansion and IRSN dose reference level revisions for early signals of regulatory-driven procurement specification shifts. Forecasts reflect assumptions about territorial hospital group restructuring pace and AI Act technical documentation completion rates among incumbent vendors. Quarterly review of HAS accreditation enforcement intensity and flat panel detector supply lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
Europe Digital X-Ray Market
Medical Imaging
Global Spinal Imaging Treatment Market
Medical Imaging
Europe Digital Radiology Market
Medical Imaging
Europe Intraoperative Imaging Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Neurophotonics Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
India Mammography Market
Medical Imaging
Australia Computed Tomography Market