

AI Radiology Worklist Orchestration Market Size, Share, and Industry Trends Forecast 2026-2036
AI Radiology Worklist Orchestration Market Insights
Modular bundling of triage, notification, and workflow tracking capabilities into unified platform subscriptions is repositioning buyer procurement patterns. Aidoc leverages integrated stroke and pulmonary embolism modules to anchor enterprise contracts with large hospital networks. Viz.ai competes through real-time care coordination features that extend beyond pure imaging workflow into treatment logistics. Qure.ai specializes in tuberculosis and chest X-ray screening tools that occupy distinct price-performance tiers in emerging health systems.
AI radiology worklist orchestration denotes algorithmic systems that prioritize, route, and track diagnostic imaging cases based on clinical acuity, modality type, and subspecialist availability, typically processing DICOM metadata and natural language reports through machine learning pipelines with sub-minute inference latency. Its primary commercial purpose is to reduce turnaround times for critical findings while balancing radiologist workload across distributed reading pools. Machine learning-based automated triage commands the largest current revenue share, whereas edge computing deployments represent the fastest-growing technology segment as latency-sensitive emergency applications expand. Cloud computing infrastructure sustains the dominant delivery model for teleradiology networks seeking elastic capacity during peak demand periods.
FDA premarket notification requirements for AI diagnostic devices shape product development timelines and clinical validation standards for vendors targeting the United States. GDPR and HIPAA frameworks govern cross-border patient data flows and cloud hosting architectures, directly constraining deployment options for European and North American health systems respectively. Stakeholders must monitor evolving reimbursement codes for AI-assisted diagnosis, as coverage determinations will decide whether health systems absorb platform costs or defer adoption until payment parity emerges.
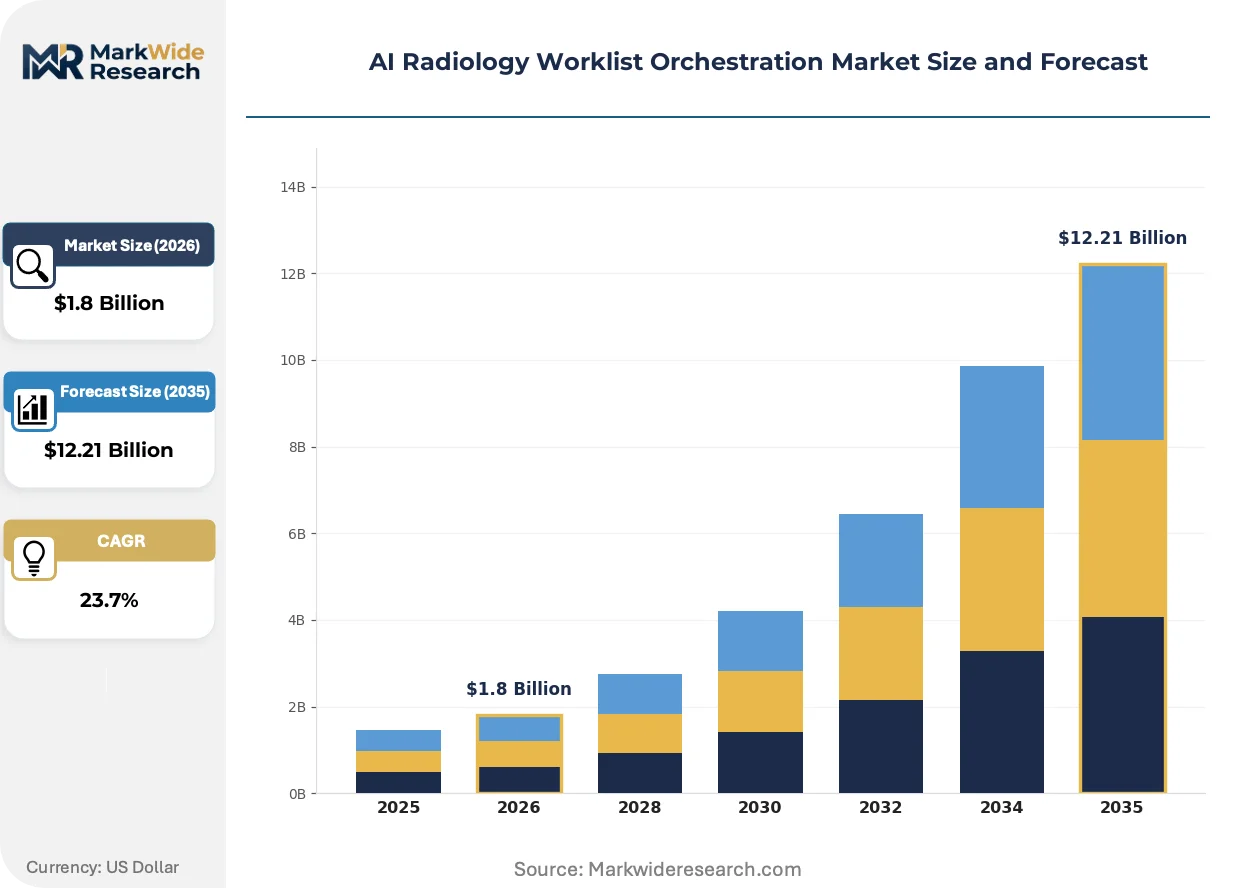
Market Dynamics
Enterprise health systems are consolidating radiology infrastructure around unified AI platforms that embed triage, notification, and workflow tracking into single vendor relationships, compressing procurement cycles and displacing point-solution vendors.
Growth Catalysts
- FDA 510(k) clearance acceleration:Streamlined premarket notification pathways for AI diagnostic devices are compressing vendor commercialization timelines and expanding deployable algorithm inventories across US hospital networks.
- Teleradiology network expansion:Remote reading pools are integrating automated triage tools to manage elastic case volumes during peak demand periods, particularly for stroke and trauma protocols.
- Cloud infrastructure elasticity:Hyperscale hosting architectures enable sub-minute inference latency for emergency applications without capital-intensive on-premise GPU clusters.
Market Restraints
- HIPAA-GDPR jurisdictional friction:Cross-border patient data flows between US and European teleradiology networks face conflicting cloud hosting requirements that constrain multi-continental platform architectures.
- Radiologist liability ambiguity:Unclear malpractice allocation between AI algorithm vendors and interpreting physicians creates institutional risk aversion among academic medical centers.
- Interoperability standard gaps:DICOM metadata parsing inconsistencies across PACS vendors from GE Healthcare, Philips, and Siemens force costly integration engineering.
Strategic Opportunities
- Edge computing deployment:Latency-sensitive emergency applications are migrating inference workloads to hospital-site GPU appliances, creating hardware-software bundled revenue streams.
- India chest X-ray screening:National tuberculosis elimination programs present volume contracting opportunities for algorithm vendors with price-optimized screening tools.
- EU AI Act compliance services:Conformity assessment requirements for high-risk medical AI systems are opening advisory and validation service revenue adjacent to software licensing.
Industry Challenges
- Machine learning operations talent scarcity:Health systems lack internal expertise to monitor model drift and maintain FDA-mandated post-market surveillance without vendor dependency.
- Legacy PACS integration complexity:Decades-old radiology information systems require custom HL7 FHIR middleware development that extends deployment timelines.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Radiology Worklist Orchestration Market Trends and Innovations
Algorithmic inference is migrating from centralized cloud architectures toward distributed edge deployments, while regulatory frameworks on both sides of the Atlantic impose new conformity burdens that favor established vendors with compliance infrastructure.
Federated learning architectures are electrifying how AI radiology models train across institutional boundaries without centralizing patient data. Academic medical centers in the United States and Germany are piloting these frameworks to pool diagnostic patterns while preserving HIPAA and GDPR separation. This architecture is electrifying competitive positioning for vendors that can demonstrate zero-data-movement model improvement.
The EU AI Act's high-risk system classification is mandating conformity assessments and post-market monitoring for diagnostic algorithms deployed in European health systems. Vendors must now maintain quality management systems and risk documentation that mirror medical device regulations. French and Dutch hospital procurement committees are prioritizing CE-marked algorithms with established EU AI Act technical documentation.
Subscription bundling of triage, notification, and quality assurance modules is displacing standalone algorithm procurement at large US health systems. Hospital networks are consolidating vendor relationships to reduce contract management overhead and standardize clinical protocols across acquired facilities. This pattern is most visible in Texas and Florida markets where health system consolidation has concentrated buying power.
AI Radiology Worklist Orchestration Market Segmentation
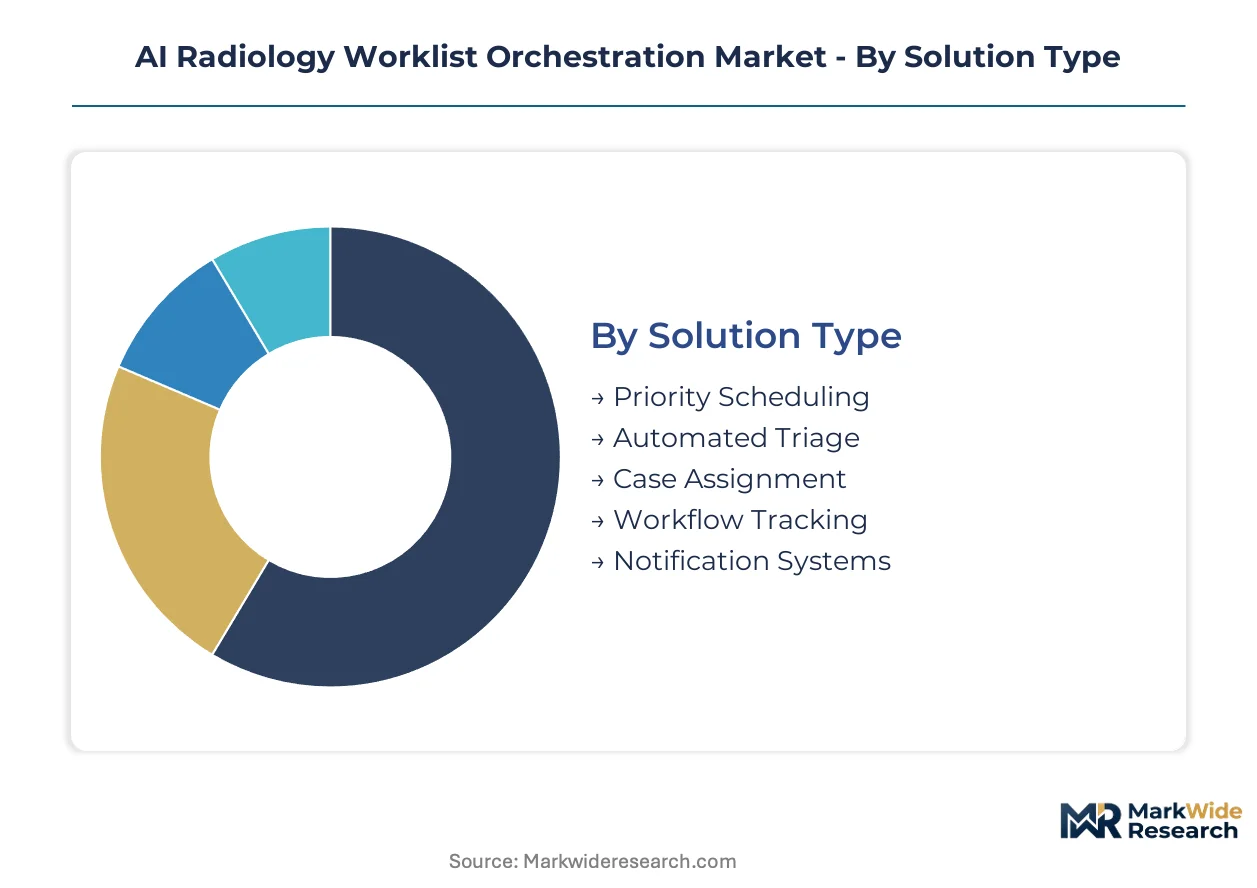
AI radiology worklist orchestration platforms segment across functional modules, underlying technologies, clinical applications, and institutional settings. Procurement patterns diverge sharply between emergency-critical deployments and elective screening workflows, with technology choices increasingly constrained by latency requirements and regulatory jurisdiction.
Solution Type:
Supply concentration in automated triage modules anchors vendor revenue, while notification and tracking capabilities fragment across specialized point-solution providers.
- Automated Triage:Algorithmic systems rank imaging studies by clinical acuity using DICOM metadata and preliminary findings. Stroke and trauma protocols in US hospital networks drive procurement concentration here, with FDA 510(k) clearance timelines compressing vendor selection cycles.
- Priority Scheduling:Dynamic case sequencing optimizes radiologist availability against subspecialty requirements and SLA commitments. Teleradiology networks in India and Southeast Asia deploy these modules to manage elastic overnight volumes without permanent staffing expansion.
- Case Assignment:Rules-based routing distributes studies to qualified readers based on credentialing, workload balance, and turnaround targets.
- Workflow Tracking:Real-time dashboards monitor study status from acquisition through final report distribution.
- Notification Systems:Alert infrastructure escalates critical findings to ordering physicians via mobile and EHR-integrated channels.
Today's leader: Automated Triage. Tomorrow's challenger: Notification Systems.
Technology:
Cost tier stratification separates capital-intensive edge deployments from subscription-based cloud consumption, with hybrid architectures emerging as the compromise procurement pattern.
- Machine Learning:Supervised classification models trained on annotated imaging datasets prioritize cases by probability of critical findings. Academic medical centers in Germany and the Netherlands validate these algorithms through federated learning frameworks that preserve GDPR separation.
- Edge Computing:Hospital-site GPU appliances execute inference with sub-50-millisecond latency for emergency applications. US trauma centers in Texas and Florida lead adoption here, driven by network reliability concerns and HIPAA data localization preferences.
- Cloud Computing:Hyperscale hosting delivers elastic capacity for teleradiology networks facing diurnal demand swings.
- Natural Language Processing:Report parsing extracts structured findings from radiologist narratives to trigger workflow actions.
- Computer Vision:Direct pixel analysis of imaging studies enables abnormality detection independent of metadata quality.
Machine Learning commands current procurement budgets. Edge Computing expands most quickly as latency-sensitive emergency protocols proliferate.
Application:
Volume concentration in diagnostic imaging general workflows contrasts with margin concentration in specialized cardiac and oncology applications requiring subspecialist coordination.
- Emergency Radiology:Stroke, trauma, and aortic syndrome protocols demand sub-minute turnaround times that mandate automated triage. US health systems consolidate vendor relationships around these capabilities, particularly in consolidated Florida and Texas networks.
- Oncology Imaging:Tumor board coordination and longitudinal tracking require workflow integration across radiology, pathology, and medical oncology. European hospital procurement committees prioritize CE-marked algorithms with EU AI Act technical documentation here.
- Diagnostic Imaging:General radiology workflows encompass the majority of non-emergent CT, MRI, and ultrasound studies.
- Cardiac Imaging:Coronary CT angiography and cardiac MRI demand specialized reader credentialing and structured reporting.
- Musculoskeletal Imaging:Sports medicine and orthopedic surgery alignment drives subspecialty routing requirements.
Diagnostic Imaging handles study volume. Emergency Radiology captures platform investment priority.
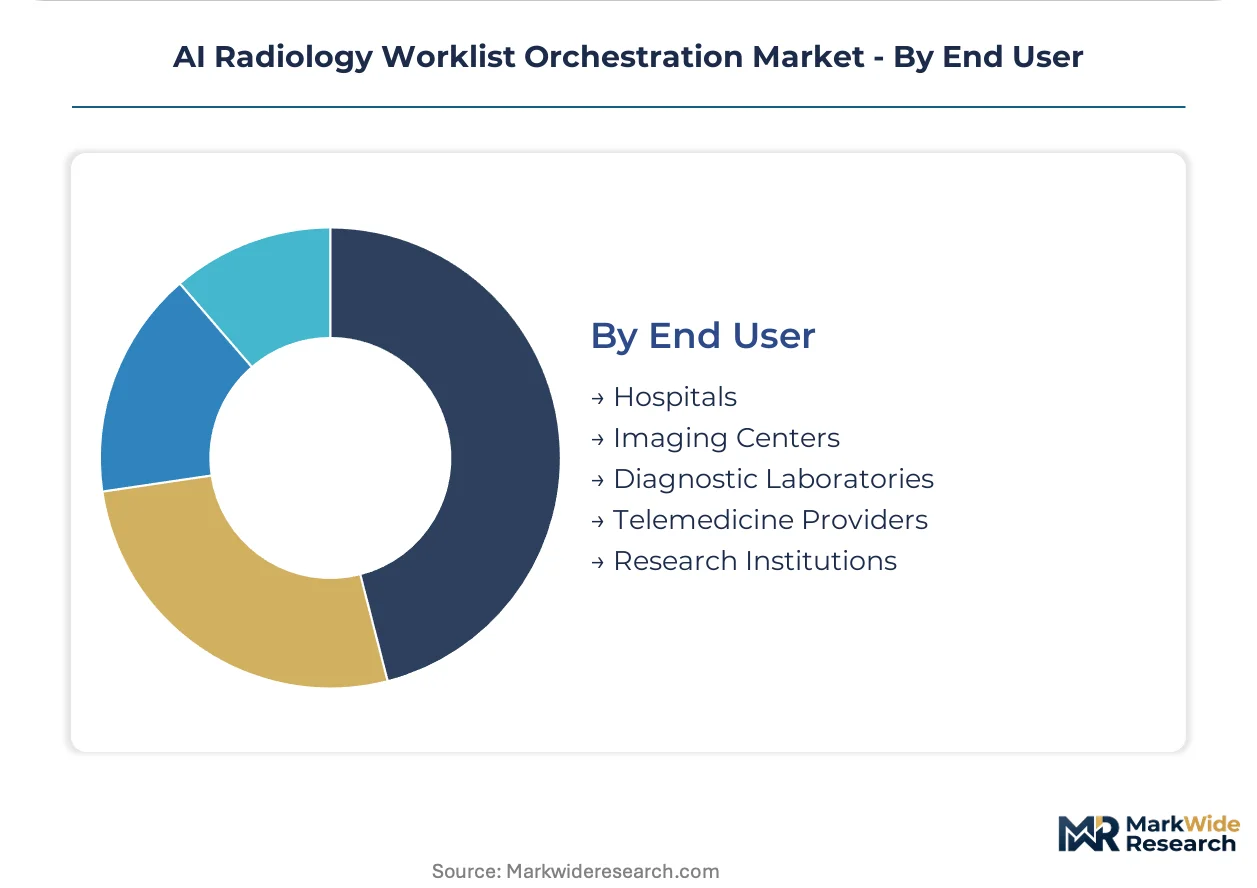
End User:
Customer type maturity separates enterprise health systems with consolidated procurement authority from fragmented imaging centers negotiating module-by-module.
- Hospitals:Integrated delivery networks deploy enterprise-wide platforms embedding triage, notification, and quality assurance. US health system consolidation in Texas and Florida concentrates buying power and compresses vendor selection timelines.
- Telemedicine Providers:Remote reading pools require elastic cloud infrastructure and automated case distribution across time zones. Indian teleradiology firms serving domestic and Middle Eastern markets prioritize price-optimized screening tools with tuberculosis and chest X-ray specialization.
- Imaging Centers:Independent facilities select point solutions based on PACS compatibility and per-study pricing.
- Diagnostic Laboratories:Integrated lab-radiology workflows drive API-first platform requirements.
- Research Institutions:Federated learning pilots and algorithm validation studies demand data governance tooling.
Hospitals dominate contract value. Telemedicine Providers represent the steepest expansion trajectory as cross-border reading networks proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The AI radiology worklist orchestration industry originated in academic medical centers across the United States and Israel, where early stroke detection algorithms proved clinical utility before scaling to enterprise health systems worldwide.
United States
Health system consolidation in Texas and Florida drives enterprise-wide platform procurement, with integrated delivery networks demanding unified triage and notification capabilities. FDA 510(k) clearance pathways compress vendor selection timelines for stroke and trauma protocols. The Dallas-Fort Worth metroplex anchors several teleradiology networks expanding automated case distribution across multi-state reading pools.
Germany
Academic medical centers in Berlin and Munich pilot federated learning frameworks that pool diagnostic patterns while preserving GDPR data separation. The EU AI Act mandates conformity assessments for high-risk diagnostic algorithms, favoring vendors with established quality management systems. The Rhine-Ruhr region concentrates hospital procurement committees prioritizing CE-marked algorithms with technical documentation.
India
National tuberculosis elimination programs create volume contracting opportunities for chest X-ray screening algorithms optimized for price-sensitive health systems. CDSCO medical device regulations govern algorithm deployment in domestic hospital networks. Bangalore-based teleradiology firms serve Middle Eastern markets with automated triage tools managing overnight case volumes.
United Kingdom
NHS England's imaging modernization programs accelerate procurement of automated workflow tools addressing radiologist workforce shortages. MHRA regulatory frameworks align with EU AI Act requirements for high-risk medical AI systems. London's academic hospital trusts lead validation studies for federated learning architectures preserving patient data localization.
Australia
Remote and rural healthcare networks deploy cloud-based triage tools to manage specialist radiologist access across vast geographic distances. TGA medical device regulations require clinical evidence standards for diagnostic algorithm deployment. Melbourne's health technology clusters host pilot programs integrating automated notification systems with statewide emergency stroke protocols.
AI Radiology Worklist Orchestration Market Competitive Landscape
Premium-margin players sit above commodity-margin players across clinical validation depth and regulatory certification breadth. Enterprise health systems consolidate vendor relationships around unified platforms, compressing procurement cycles and displacing point-solution specialists. Three archetypes dominate: integrated platform vendors with multi-module subscriptions, specialized triage algorithm developers, and teleradiology-native workflow tools. Dominant competitive moves include strategic partnerships with PACS vendors and geographic expansion through regulatory certification stacking.
Within the integrated platform tier, Aidoc and Viz.ai occupy positions anchoring enterprise contracts through stroke and care coordination capabilities respectively. Qure.ai represents the screening-specialist archetype with price-optimized tools for tuberculosis and chest X-ray applications in emerging health systems. These three companies exemplify how vendor positioning diverges across clinical application focus and geographic market prioritization.
| Leading Market Players |
|---|
| Aidoc |
| Viz.ai |
| Qure.ai |
| Harrison.ai |
| Gleamer |
| deepc |
| Blackford |
| Enlitic |
| Merative |
| Others |
Pricing and Supply Chain Analysis
GPU hardware costs cascade through three-tier pricing structures across premium, standard, and economy levels, with NVIDIA H100 clusters anchoring enterprise subscriptions at US academic medical centers while cloud inference credits feed mid-market teleradiology networks in India and Southeast Asia.
Pricing Analysis
Subscription bundling of triage, notification, and quality assurance modules anchors enterprise contracts at US health systems, with FDA 510(k) clearance tier and edge-computing latency performance separating premium deployments from cloud-based economy tiers. Price differentiation hinges on certification depth and subspecialty algorithm coverage. Cost compression in economy tiers intensifies as Indian teleradiology firms negotiate volume discounts for tuberculosis screening tools. Imaging centers exhibit highest price sensitivity, deferring procurement until per-study pricing models emerge.
Supply Chain Analysis
Domestic-content mandates in India's CDSCO medical device regulations and the EU AI Act's conformity assessment requirements are reshaping algorithm development sourcing toward local validation partnerships. GPU hardware concentrates in Taiwan and South Korea, with cloud infrastructure anchoring in US hyperscale regions. Software dependencies draw from open-source machine learning frameworks and proprietary DICOM parsing libraries. Single-source vulnerability runs through NVIDIA's datacenter GPU allocation. Distribution runs through direct enterprise sales teams and PACS vendor channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise health systems now demand validated stroke and trauma protocols as table stakes, compressing procurement timelines for vendors with FDA-cleared algorithm portfolios and pushing late entrants toward specialized screening applications.
For Market Incumbents: Cement enterprise platform positions by deepening PACS integration partnerships with GE Healthcare and Philips while building federated learning infrastructure to preempt GDPR-constrained academic medical centers in Germany. The threat of modular point-solution vendors undercutting per-module pricing demands defensive bundling of quality assurance and notification capabilities. For New Entrants and Emerging Players: The mid-tier price gap between Aidoc's enterprise contracts and Qure.ai's emerging-market screening tools opens white-space targeting of community hospital networks in Texas and Florida seeking stroke triage without full platform commitments. Penetrate through API-first deployment models that bypass lengthy PACS integration cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where EU AI Act compliance costs exceed €2 million for quality management system documentation, favoring acquisition of CE-marked algorithm developers with established conformity infrastructure. Target vendors with proven federated learning pilots and hospital system validation partnerships. Watch FDA 510(k) clearance velocity as inflection signal for commercial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified triage-notification bundles displace point-solution vendors at US health systems. |
| FDA 510(k) Clearance Pathway | Streamlined premarket notification accelerates commercial deployment timelines for stroke algorithms. |
| Hospital System Partnership | Enterprise contracts with Texas and Florida networks anchor recurring revenue streams. |
| CE Marking Pathway | EU AI Act conformity assessments open procurement access to Rhine-Ruhr hospital committees. |
| Strategic Partnership | PACS vendor alliances with GE Healthcare reduce integration friction for mid-market deployments. |
Research Methodology
Direct dialogue with radiology department chairs, hospital purchasing committee members, teleradiology network operations directors, and FDA regulatory consultants grounded qualitative findings in deployment friction points and procurement decision criteria. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement filings, hospital procurement contract disclosures, and GPO pricing benchmarks. Bottom-up algorithm deployment counts triangulated against top-down health system IT spending estimates.
Segment-level revenue projections across automated triage, priority scheduling, and notification modules incorporated deployment model splits between edge computing and cloud infrastructure, with radiologist FTE shortages and teleradiology network expansion serving as demand-side inputs. CAGRs were derived from algorithm adoption curves weighted by FDA clearance timelines and health system consolidation patterns. Inference latency requirements and GDPR jurisdictional constraints shaped technology segment trajectories.
The model assumes a particular technology adoption path; alternative pathways for federated learning architectures would alter the outlook if academic medical centers accelerate zero-data-movement validation. Forecasts reflect assumptions of continued HIPAA-GDPR friction and stable FDA 510(k) clearance velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.