
 Europe Digital X-Ray Market | 2026-2036
Europe Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digital X-Ray Market Foresight
Outpatient clinics is bifurcating from hospital-centric procurement as the fastest-growing buyer archetype in European digital radiology. Siemens Healthineers leverages its installed base of imaging suites to sustain service contract renewals across German university hospitals. Philips Healthcare anchors its position through integrated PACS workflows that dominate Dutch and Belgian diagnostic networks. GE Healthcare competes on detector manufacturing scale, supplying flat-panel substrates to third-party OEMs alongside its own branded systems.
Europe digital x-ray equipment comprises electronic detector arrays, typically cesium iodide or gadolinium oxysulfide scintillator layers coupled to thin-film transistor backplanes, that convert transmitted radiation into digital images for diagnostic interpretation. Flat Panel Detectors lead technology shipments due to superior dose efficiency and faster acquisition cycles compared to legacy Charge-Coupled Devices. Digital Radiography systems command the largest product type revenue pool, though Portable X-Ray configurations are gaining fastest in emergency and bedside applications where workflow mobility determines purchasing decisions.
The EU Medical Device Regulation (MDR) and CE marking requirements administered by notified bodies in Germany, France, and the Netherlands shape product compliance timelines and clinical evidence standards for new system approvals. ECHA REACH restrictions on hazardous substances in electronics manufacturing influence detector material selection and supplier qualification processes across the value chain. Stakeholders must monitor evolving national reimbursement catalogues in Italy and Spain, where regional health authorities are consolidating procurement into centralized frameworks that favor multi-modality vendors with established service infrastructure.
Market Dynamics
EU MDR compliance deadlines are compressing replacement cycles across German and French hospital networks, forcing radiology departments to accelerate capital deployment toward wireless detector systems that satisfy notified body imaging quality thresholds.
Growth Catalysts
- EU Medical Device Regulation (MDR):CE marking requirements administered by German and French notified bodies mandate digital workflow integration, eliminating analog retrofit pathways for aging film-based installations.
- Wireless detector panels:Cesium iodide scintillator layers coupled to thin-film transistor backplanes deliver superior dose efficiency, accelerating adoption in Western European tertiary care networks where reimbursement frameworks favor throughput optimization.
- Outpatient clinic procurement:Diagnostic networks in the Netherlands and Belgium are bifurcating from hospital-centric purchasing, creating dedicated capital allocation streams for portable X-ray configurations.
Market Restraints
- Flat-panel substrate supply concentration:Manufacturing scale for gadolinium oxysulfide scintillator materials concentrates among specialized chemical suppliers, exposing OEMs to input cost volatility and qualification timeline extensions.
- ECHA REACH substance restrictions:Hazardous substance limitations in electronics manufacturing constrain detector material selection, forcing reformulation of legacy scintillator compositions and supplier requalification.
- Charge-Coupled Device installed base:Legacy CCD systems in Southern European regional health authorities create substitution friction where capital constraints delay full digital radiography conversion.
Strategic Opportunities
- Spanish regional consolidation:Andalusian and Catalan health authorities are centralizing procurement into multi-modality frameworks that favor vendors with established service infrastructure across Iberian diagnostic networks.
- Artificial intelligence convergence:Machine learning algorithms for automated image analysis are integrating with PACS workflows, creating premium pricing tiers for AI-enabled detector systems in Dutch university hospitals.
- Bedside emergency applications:Portable X-ray configurations are penetrating emergency departments and intensive care units where workflow mobility determines purchasing decisions outside traditional radiology department budgets.
Industry Challenges
- Notified body capacity constraints:German and Dutch conformity assessment organizations face backlog pressures under expanded EU MDR clinical evidence requirements, extending system approval timelines for novel detector technologies.
- Legacy PACS integration complexity:Italian regional health networks operate heterogeneous imaging archives that resist seamless digital radiography connectivity, requiring costly middleware development for workflow continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digital X-Ray Market |
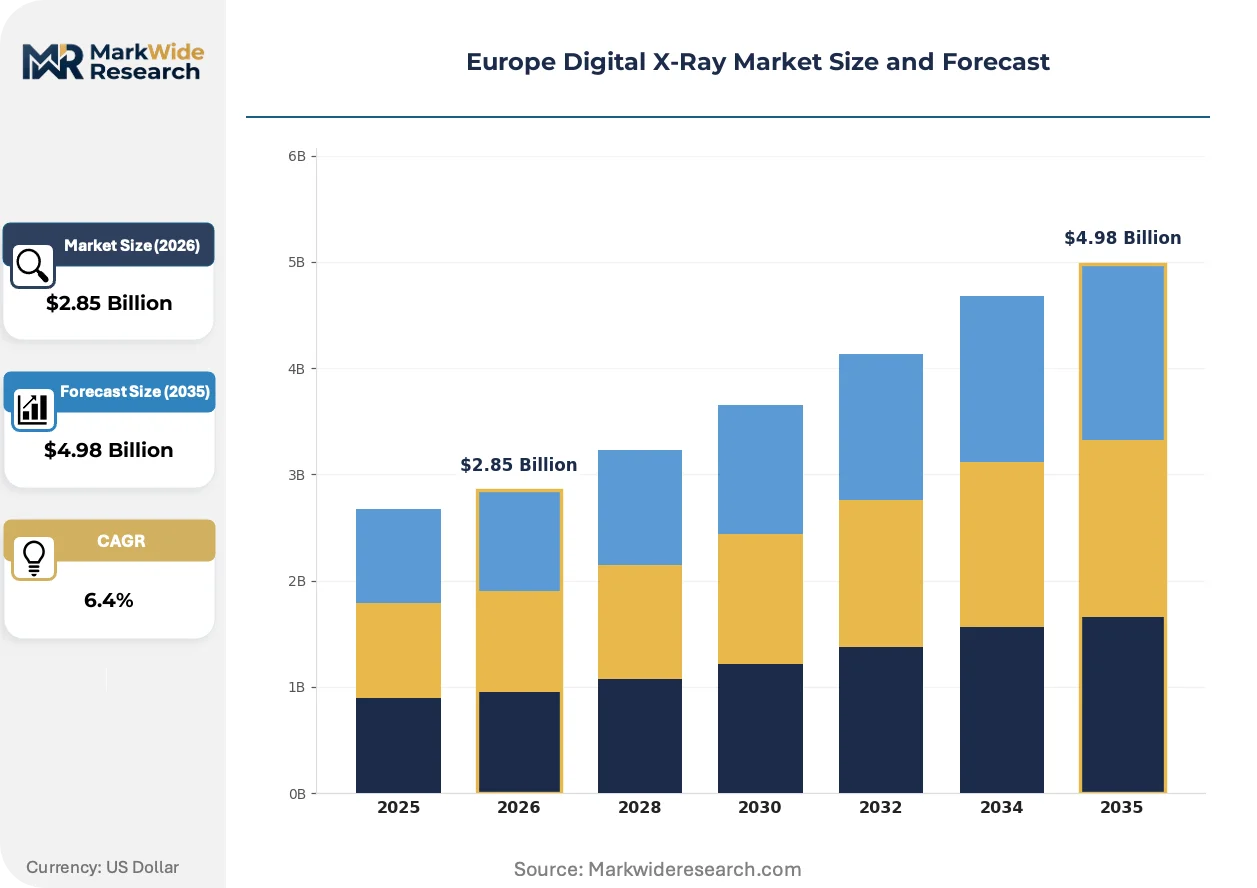
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable X-Ray, Computed Radiography, Digital Radiography, Static X-Ray Technology: Flat Panel Detectors, Charge-Coupled Devices, Image Intensifiers, Computed Radiography Systems End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Academic Institutions Application: Orthopedics, Dental Imaging, Cardiovascular, Oncology |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Fujifilm Medical Systems, Canon Medical Systems, Carestream Health, Hologic, Agfa-Gevaert Group, Shimadzu, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digital X-Ray Market Shifts & Advancements
Detector technology roadmaps are diverging between premium wireless panels and cost-optimized tethered configurations, while regulatory frameworks and procurement centralization reshape competitive positioning across European radiology networks.
Cesium iodide scintillator technology is fragmenting the premium detector segment from gadolinium oxysulfide alternatives. German university hospitals are adopting wireless cesium iodide panels for their superior detective quantum efficiency in low-dose protocols. This technical stratification is fragmenting vendor portfolios into distinct performance tiers that compress mid-market pricing bandwidth.
EU Medical Device Regulation (MDR) clinical evidence requirements are extending conformity assessment timelines for new system introductions. Notified bodies in France and Germany now demand post-market surveillance data that previously sufficed with pre-market technical documentation. Flat-panel detector OEMs are responding by front-loading clinical validation investments and consolidating submission portfolios to manage regulatory throughput.
Regional procurement centralization in Italy and Spain is consolidating purchasing authority away from individual hospital radiology departments. Multi-year framework agreements now dominate equipment acquisition in Lombardy and Madrid, displacing spot purchasing and unbundling after-sales service contracts. This behavioral shift is most visible in Southern European markets where fiscal consolidation pressures intersect with diagnostic network modernization mandates.
Europe Digital X-Ray Market Segmentation
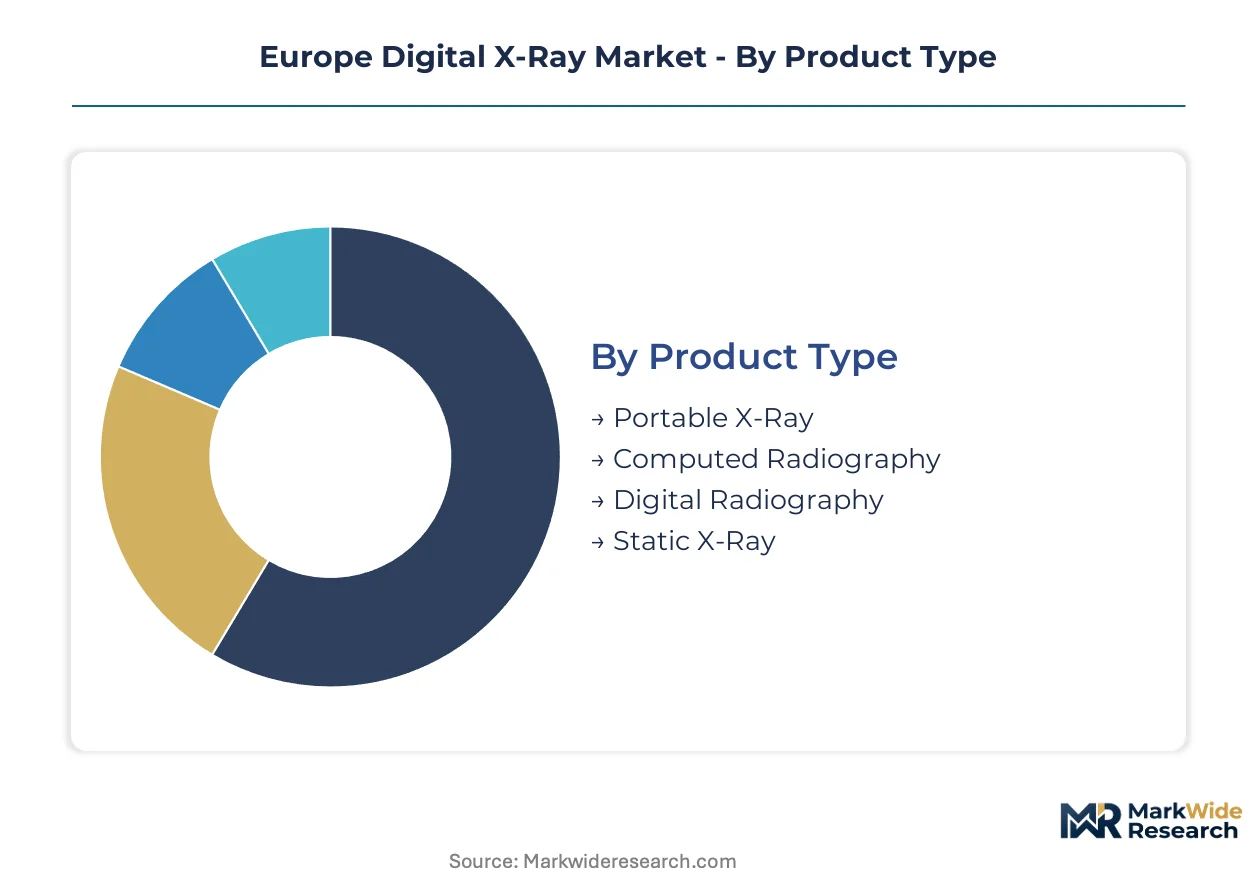
Digital X-ray market segmentation reveals distinct margin architectures across hardware configurations, detector technologies, and clinical deployment settings. Procurement patterns diverge sharply between capital-intensive hospital networks and distributed outpatient settings, reshaping vendor go-to-market priorities across European radiology.
Product Type:
Margin pools concentrate in systems that balance throughput density with workflow flexibility, rewarding configurations that minimize room retrofit costs.
- Digital Radiography:Fixed-room installations with wireless flat-panel detectors dominate tertiary care procurement in Germany and France. EU MDR compliance deadlines are compressing replacement cycles for aging film-based systems, accelerating capital deployment toward integrated digital workflows.
- Portable X-Ray:Battery-powered mobile units with tethered or wireless detectors are penetrating emergency departments and intensive care units where bedside imaging eliminates patient transport. Dutch and Belgian diagnostic networks are bifurcating procurement toward these configurations for workflow mobility.
- Computed Radiography:Cassette-based digital systems serve as transition technology for Southern European regional health authorities with capital constraints.
- Static X-Ray:Conventional fixed-tube systems persist in price-sensitive procurement frameworks where detector retrofitting extends equipment life.
The dominant share belongs to Digital Radiography, while Portable X-Ray is closing the gap fastest.
Technology:
Detector architecture determines dose efficiency, acquisition speed, and total cost of ownership across European reimbursement environments.
- Flat Panel Detectors:Cesium iodide scintillator layers coupled to thin-film transistor backplanes deliver superior detective quantum efficiency. German university hospitals are adopting wireless configurations for low-dose protocols, fragmenting vendor portfolios into distinct performance tiers.
- Charge-Coupled Devices:Legacy phosphor plate systems with optical scanning mechanisms create substitution friction in Italian and Spanish regional health networks where capital constraints delay full digital conversion.
- Image Intensifiers:Vacuum tube-based fluoroscopy detectors persist in interventional suites where real-time imaging demands override flat-panel economics.
- Computed Radiography Systems:Photostimulable phosphor technology bridges analog-to-digital transition for mid-tier diagnostic centers.
Flat Panel Detectors command installed base leadership, though Charge-Coupled Devices retain residual presence where budget cycles lag technology roadmaps.
End User:
Customer archetype shapes purchasing authority, service contract structures, and modality bundling requirements.
- Hospitals:Radiology departments across German and French tertiary networks drive volume concentration, with procurement favoring multi-modality vendors with established service infrastructure.
- Outpatient Clinics:Independent diagnostic facilities in the Netherlands and Belgium are creating dedicated capital allocation streams, expanding fastest among buyer archetypes as procurement bifurcates from hospital-centric models.
- Diagnostic Centers:Specialized imaging facilities concentrate throughput in urban corridors, prioritizing detector reliability and PACS integration.
- Academic Institutions:University hospitals combine clinical service with research protocols, demanding premium specifications for protocol development.
Hospitals retain procurement volume leadership, while Outpatient Clinics are expanding most quickly as distributed care models gain reimbursement traction.
Application:
Clinical use case determines detector specification, software workflow, and reimbursement coding complexity.
- Orthopedics:Weight-bearing extremity and spinal imaging demands high-resolution detectors with specialized positioning systems. German rehabilitation networks are standardizing digital radiography for trauma follow-up protocols.
- Dental Imaging:Intraoral and panoramic configurations operate on distinct regulatory and reimbursement pathways from medical radiology, with CE marking under EU MDR extending to dedicated dental notified bodies.
- Cardiovascular:Interventional suites require fluoroscopy-capable detectors with rapid frame rates, concentrating in Western European catheterization laboratories.
- Oncology:Treatment planning and response monitoring integrate digital X-ray with CT and MRI workflows, favoring vendors with cross-modality PACS connectivity.
Orthopedics anchors application revenue, with Dental Imaging climbing fastest as independent practice consolidation drives equipment standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital radiology departments concentrate procurement authority in Western European tertiary networks, while outpatient clinics in the Netherlands and Belgium are bifurcating purchasing patterns toward portable configurations. German and French notified bodies administer EU MDR compliance deadlines that compress replacement cycles across diagnostic networks.
Germany
University hospitals in Bavaria and North Rhine-Westphalia drive wireless detector adoption for low-dose imaging protocols. BfArM and TÜV Süd administer notified body functions under EU MDR, extending conformity assessment timelines for novel flat-panel technologies. The Munich-Berlin corridor anchors Siemens Healthineers' service infrastructure renewal contracts.
France
Tertiary care networks in Île-de-France and Auvergne-Rhône-Alpes prioritize multi-modality vendors with established maintenance capabilities. ANSM oversees clinical evidence standards for CE marking, while regional health agencies consolidate procurement authority away from individual hospital radiology departments. The Lyon-Paris axis concentrates fluoroscopy-capable detector deployments in interventional suites.
Netherlands
Diagnostic networks in Randstad and Eindhoven Region are creating dedicated capital allocation streams for outpatient clinic procurement. The Dutch Health and Youth Care Inspectorate aligns with EU MDR implementation timelines, favoring integrated PACS workflow vendors. Philips Healthcare anchors its position through dominance of hospital network imaging archives.
Italy
Lombardy and Lazio regional health authorities operate heterogeneous PACS environments that resist seamless digital radiography connectivity. AIFA coordinates with notified bodies on clinical evidence requirements, while fiscal consolidation pressures delay full detector conversion in Southern networks. The Milan-Rome corridor concentrates mid-tier diagnostic center procurement.
Spain
Andalusian and Catalan health authorities are centralizing procurement into multi-year framework agreements that favor established service infrastructure. AEMPS administers medical device regulations under EU MDR alignment, with regional authorities consolidating purchasing authority. The Madrid-Barcelona axis drives portable X-ray penetration in emergency department budgets.
Europe Digital X-Ray Market Competitive Landscape
Player mix skews toward diversified imaging conglomerates with multi-modality portfolios and captive detector manufacturing capabilities. The vendor base stratifies across three tiers: integrated healthcare technology conglomerates with full-stack imaging suites, specialized radiology equipment manufacturers with focused detector expertise, and regional service providers leveraging aftermarket maintenance contracts. Consolidation pressure favors scale-driven players with established notified body relationships and multi-country service footprints. Competitive moves center on PACS workflow integration partnerships and wireless detector technology licensing arrangements.
Among diversified healthcare technology conglomerates, Siemens Healthineers, GE Healthcare, and Philips Healthcare exemplify the integrated archetype that dominates Western European tertiary procurement. Siemens Healthineers occupies a position anchored in German university hospital networks, while GE Healthcare represents scale-driven detector substrate manufacturing that supplies OEM channels alongside branded systems. Philips Healthcare sits within the workflow integration tier, exemplifying PACS-centric competitive positioning across Dutch and Belgian diagnostic networks.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Fujifilm Medical Systems |
| Canon Medical Systems |
| Carestream Health |
| Hologic |
| Agfa-Gevaert Group |
| Shimadzu |
| Others |
Supply & Pricing Matrix
Long-term service contracts with price indexation clauses lock in detector panel supply for German university hospitals while insulating procurement budgets from cesium iodide scintillator volatility. These agreements bundle wireless flat-panel hardware with multi-year maintenance, creating predictable cost structures for radiology departments navigating EU MDR compliance timelines.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate detector procurement for Western European hospital networks, passing through gadolinium oxysulfide and thin-film transistor substrate fluctuations. Three-tier pricing structure across premium wireless, standard tethered, and economy retrofit configurations segments buyers by workflow integration requirements. Pricing pressure stems from outpatient clinic procurement consolidation in the Netherlands and Belgium, where capital constraints favor portable configurations over fixed-room installations. Regional health authorities in Southern Europe exhibit highest price sensitivity due to fiscal consolidation mandates, while German tertiary networks prioritize dose efficiency over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for thin-film transistor backplanes sourced from East Asian foundries. Manufacturing concentration in Japan, South Korea, and Taiwan feeds cesium iodide crystal growth and TFT substrate fabrication, with European OEMs drawing from these hubs for detector assembly. Single-source vulnerability concentrates in specialized scintillator chemical suppliers qualified under ECHA REACH restrictions. Distribution runs through authorized service depots in Munich, Paris, and Eindhoven that maintain spare panel inventories for hospital network uptime guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, where notified body relationships and CE marking track records create switching costs that lock hospital procurement into established vendor ecosystems.
For Market Incumbents: Secure multi-year framework agreements with Spanish regional health authorities before Andalusian and Catalan consolidation finalizes, locking out emerging competitors. Deepen backward integration into cesium iodide crystal growth to insulate margins from chemical supplier concentration, while accelerating AI-enabled detector development to capture premium pricing in Dutch university hospitals. For New Entrants and Emerging Players: CE marking fast-track through German BfArM parallel consultation offers pathway to bypass incumbent backlog advantages for novel wireless configurations. Target portable X-ray procurement in Belgian emergency departments, where workflow mobility requirements outpace established service infrastructure. Lead with PACS-native detector architectures that minimize Italian regional network integration friction. For Investors and Strategic Acquirers: Detector technology specialists with captive scintillator manufacturing and established notified body dossiers represent prime acquisition targets in a market where regulatory throughput constrains new system introductions. Long-term viability hinges on AI convergence and outpatient clinic penetration trajectories. Watch for inflection when Spanish regional framework agreements displace spot purchasing volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Detector Portfolio Expansion | Captures EU MDR-driven replacement demand in German and French tertiary networks. |
| AI Image Analysis Integration | Creates premium pricing tiers through automated diagnostic workflow enhancement. |
| Regional Procurement Framework Bids | Locks multi-year revenue streams as Italian and Spanish authorities centralize purchasing. |
| Scintillator Material Backward Integration | Reduces exposure to ECHA REACH qualification delays and chemical supplier concentration. |
| Outpatient Clinic Service Infrastructure | Supports portable X-ray penetration in Dutch and Belgian distributed diagnostic networks. |
Research Methodology
The analysis maps digital radiography systems, portable X-ray configurations, and detector technology tiers, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and notified body regulatory leads. Primary intelligence combines with secondary sources including EU MDR submission databases, hospital capital expenditure records, ECHA REACH substance restriction filings, and European medical device trade flows. Bottom-up equipment shipment tracking triangulates against top-down healthcare capital spending analysis.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions encompass product type, detector technology, end-user archetype, and application area, with reimbursement framework variations modeled as regional modifiers. CAGRs derive from replacement cycle compression under EU MDR deadlines and outpatient clinic procurement expansion rates.
Underlying assumptions cover notified body capacity availability, scintillator material supply continuity, and regional health authority fiscal consolidation trajectories, with deviation risk concentrated in Southern European capital constraint severity and ECHA REACH substance restriction scope expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Global Artificial Intelligence in MRI Market
Medical Imaging
India Computed Tomography Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Portable MRI Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Dental X-Ray Market